
 United Arab Emirates Oil and Gas Market | 2026-2036
United Arab Emirates Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Oil and Gas Market Analytics
Advanced reservoir characterization is narrowing the gap between conventional and unconventional recovery economics in the UAE's carbonate formations. ADNOC leverages its integrated drilling-to-export infrastructure across the Lower Zakum and Umm Shaif fields to sustain production plateau targets. TotalEnergies SE competes through its partnership stakes in ultra-sour gas projects that demand specialized metallurgy and processing capabilities. Dolphin Energy anchors regional energy security via its cross-border pipeline network delivering processed gas to northern emirates and export markets.
The United Arab Emirates Oil and Gas sector encompasses the exploration, extraction, processing, and distribution of hydrocarbon resources across onshore and offshore concessions, with crude oil API gravities ranging from 39° in Murban to ultra-heavy 10° in some border fields and sour gas compositions exceeding 15% hydrogen sulfide in specific offshore structures. Its primary purpose is to supply feedstock for domestic power generation, water desalination, petrochemical manufacturing, and export revenue generation. Upstream activity dominates capital allocation through mega-project developments at Belbazem and Nasr fields, while Digital Oilfield technology represents the fastest-expanding technology category as operators deploy IoT sensors and predictive analytics to optimize artificial lift performance. Midstream infrastructure remains the most mature segment with established pipeline corridors and LNG export terminals, though margin pools are shifting toward oilfield services firms capable of high-pressure high-temperature completions in sour environments.
MOHAP oversees occupational health and environmental compliance for onshore operations, while ADNOC's own technical standards exceed federal baseline requirements for well integrity and process safety management. The UAE's dual regulatory structure—federal oversight plus ADNOC's concession-specific technical guidelines—creates layered compliance obligations that favor contractors with proven track records in the region. Stakeholders must weigh the capital intensity of sour gas development against the strategic priority of gas self-sufficiency as the Emirates phases out power sector coal imports.
Market Dynamics
ADNOC's digital twin deployment across mature carbonate reservoirs is compressing the breakeven threshold for enhanced oil recovery, forcing service contractors to reprice artificial lift packages around predictive maintenance outcomes rather than equipment throughput.
Growth Catalysts
- MOHAP Environmental Standards:Federal baseline requirements for well integrity and process safety management are accelerating replacement cycles for aging wellhead equipment across onshore concessions.
- Petrochemical Feedstock Demand:Industrial complexes at Ruwais and Jebel Ali are expanding cracking capacity, pulling additional sour gas volumes through Dolphin Energy's cross-border pipeline network.
- Digital Oilfield Sensors:IoT-enabled predictive analytics for artificial lift optimization are spreading from pilot fields to full-field deployment, reducing unplanned downtime in high-temperature completions.
Market Restraints
- Specialized Metallurgy Costs:Ultra-sour gas developments exceeding 15% hydrogen sulfide require nickel-alloy completions that cost 3-4x standard grades, constraining marginal field economics.
- Concession Access Concentration:ADNOC's technical standards exceed federal baselines, creating layered compliance that locks out contractors without proven regional track records.
- Carbonate Reservoir Complexity:Mature fields exhibit heterogeneous porosity that limits standard hydraulic fracturing effectiveness, extending payback periods for unconventional exploration blocks.
Strategic Opportunities
- Al Dhafra Unconventional Blocks:Tight gas formations in Abu Dhabi's western region remain underexplored relative to offshore concessions, offering first-mover positioning for hydraulic fracturing specialists.
- Power Sector Coal Phase-Out:The Emirates' strategic priority of gas self-sufficiency is redirecting capital toward sour gas processing capacity expansion at Ruwais.
- Digital Twin Convergence:Integration of reservoir simulation with real-time production data is collapsing the iteration cycle between geological modeling and artificial lift tuning.
Industry Challenges
- High-Pressure High-Temperature Certification:HPHT completions in sour environments require specialized personnel that ADNOC's contractors struggle to source at scale.
- Legacy SCADA Integration:Brownfield digitalization projects must bridge 1990s-era control systems with modern IoT architectures, multiplying deployment timelines.
- Artificial Lift Optimization Talent:The shortage of engineers capable of calibrating electrical submersible pumps in carbonate formations with variable permeability is throttling recovery rate improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Oil and Gas Market |
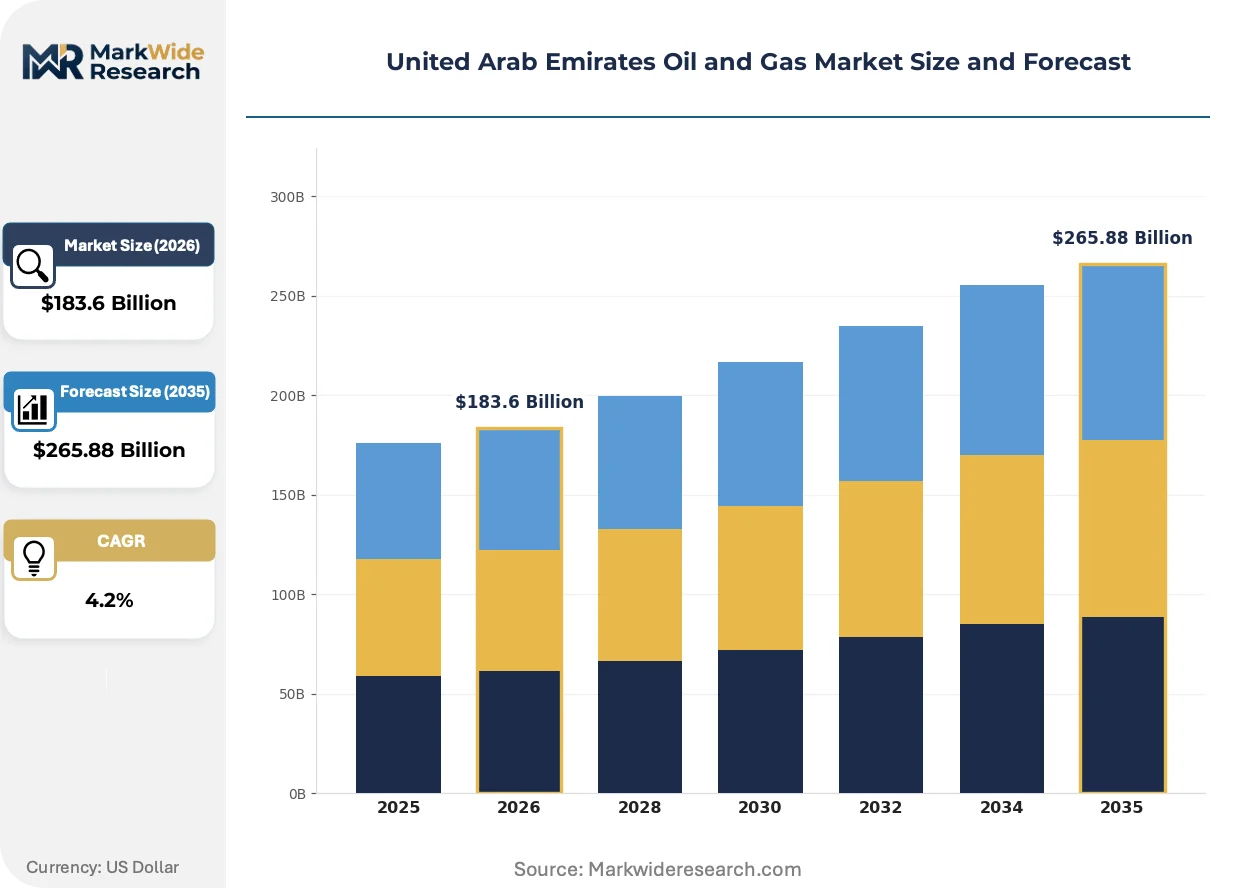
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $265.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Oilfield Services Technology: Enhanced Oil Recovery, Offshore Platforms, Hydraulic Fracturing, Digital Oilfield Application: Exploration, Production, Refining, Distribution End User: Industrial, Commercial, Residential, Transportation |
| Companies Covered | Exxon Mobil Corporation, Dolphin Energy, Abu Dhabi National Oil Company (ADNOC), Sharjah National Oil Company, Dana Gas PJSC, TotalEnergies SE, Emirates National Oil Company Group (ENOC), Crescent Petroleum, BP PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Oil and Gas Market Evolving Landscape
Technology deployment in the Emirates is pivoting from incremental efficiency gains toward structural reconfiguration of how reserves are classified, developed, and monetized across the project lifecycle.
Digital twin technology is collapsing the traditional separation between reservoir engineering and production operations. ADNOC's integrated drilling-to-export infrastructure now feeds real-time sensor data from Lower Zakum and Umm Shaif into unified simulation environments. Field operators are adopting these platforms at pace, compressing the feedback loop between geological uncertainty and artificial lift adjustments from months to hours.
MOHAP's technical standards for well integrity are hardening into de facto barriers to entry for international service contractors. The dual regulatory structure—federal oversight plus ADNOC's concession-specific guidelines—creates compliance friction that favors incumbents with established regional certification histories. Offshore sour gas projects face the steepest compliance burden, driving procurement toward integrated service providers capable of bundling metallurgy, completions, and environmental monitoring.
Buyer concentration among ADNOC's operating companies is reshaping how oilfield services are contracted. Procurement teams are unbundling equipment supply from technical services, forcing vendors to compete on outcome-based metrics rather than capital equipment margins. This shift is most visible in artificial lift tenders, where contractors now guarantee production uptime percentages rather than pump delivery specifications.
United Arab Emirates Oil and Gas Market Segmentation
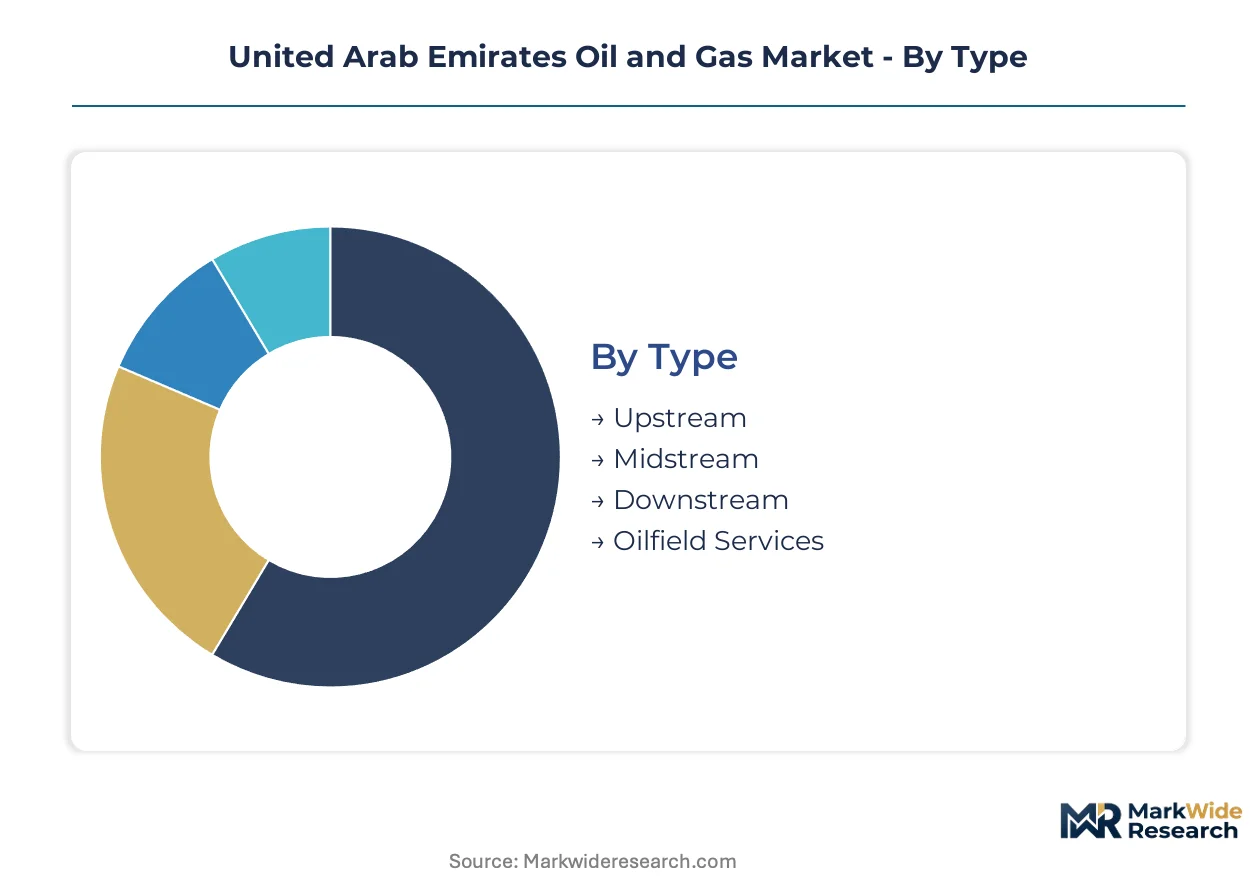
Segmentation across the UAE oil and gas market reveals how capital allocation priorities diverge between mature infrastructure segments and emerging technology deployments. Understanding these divisions clarifies where procurement power concentrates and which service categories face the steepest capability requirements.
Type:
Mature pipeline networks and processing facilities anchor established segments, while emerging categories concentrate investment in unconventional resource access and digital integration.
- Upstream:Exploration and production activities span onshore carbonate reservoirs and offshore sour gas structures. Capital deployment prioritizes Belbazem and Nasr field developments, with artificial lift optimization driving recovery economics in mature formations.
- Midstream:Established pipeline corridors, LNG export terminals, and cross-border gas transmission infrastructure. Dolphin Energy's network delivers processed volumes to northern emirates, anchoring regional energy security through fixed-route capacity.
- Downstream:Refining and petrochemical manufacturing capacity concentrated at Ruwais and Jebel Ali. Cracking capacity expansion pulls additional sour gas feedstock through integrated processing chains.
- Oilfield Services:Technical contracting for drilling, completions, and production optimization. Procurement teams unbundle equipment supply from services, forcing outcome-based competition on uptime guarantees rather than capital equipment margins.
Midstream retains volume leadership; Oilfield Services holds the steepest expansion curve.
Technology:
Cost tier stratification separates proven mechanical methods from capital-intensive digital and precision interventions requiring specialized personnel certification.
- Enhanced Oil Recovery:Thermal and chemical methods targeting mature carbonate reservoirs with heterogeneous porosity. Digital twin integration compresses breakeven thresholds by collapsing feedback loops between reservoir simulation and lift adjustments.
- Offshore Platforms:Fixed and floating structures for ultra-sour gas extraction exceeding fifteen percent hydrogen sulfide. Nickel-alloy completions and specialized metallurgy multiply capital intensity relative to standard offshore developments.
- Hydraulic Fracturing:Stimulation techniques for tight gas in Al Dhafra unconventional blocks. Carbonate complexity limits standard fracturing effectiveness, extending payback periods for western Abu Dhabi exploration.
- Digital Oilfield:IoT sensor networks and predictive analytics for real-time production optimization. Fastest-expanding technology category as operators deploy unified simulation environments across Lower Zakum and Umm Shaif fields.
Enhanced Oil Recovery dominates current spend; Digital Oilfield is gaining share fastest.
Application:
Application focus shifts from volume extraction toward precision targeting and integrated processing as reservoir quality degrades and sour gas ratios climb.
- Exploration:Seismic surveying and appraisal drilling across offshore concessions and Al Dhafra onshore blocks. Unconventional tight gas formations remain underexplored relative to established offshore structures.
- Production:Extraction operations spanning artificial lift deployment in mature fields and HPHT completions in sour environments. Talent scarcity for electrical submersible pump calibration throttles recovery improvements.
- Refining:Crude processing and conversion to refined products and petrochemical feedstock. Ruwais complex expansion aligns with strategic priority of gas self-sufficiency and power sector coal phase-out.
- Distribution:Product logistics through pipeline networks, marine terminals, and domestic supply chains. Established infrastructure limits margin expansion compared to upstream technology services.
Production commands the largest operational footprint; Exploration shows the most volatile capital commitment patterns.
End User:
Customer type concentration reveals how domestic energy security priorities shape demand patterns across power, manufacturing, and mobility sectors.
- Industrial:Petrochemical manufacturers, power generators, and water desalination facilities. Ruwais and Jebel Ali complexes anchor feedstock demand with expanding cracking capacity.
- Commercial:Business energy consumption across retail, hospitality, and office sectors. Lower per-account volume but distributed demand supports midstream infrastructure utilization.
- Residential:Household electricity and natural gas consumption concentrated in northern emirates. Dolphin Energy's cross-border pipeline network serves this segment through processed gas delivery.
- Transportation:Fuel demand for aviation, marine bunkering, and road transport. Abu Dhabi crude grades including Murban supply refining streams for mobility energy products.
Industrial retains volume leadership; Transportation holds the steepest demand volatility exposure.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE crude exports flow primarily to Asian refining centers, with Murban and Upper Zakum grades supplying complex cokers in Japan, South Korea, and India. This trade corridor shapes Abu Dhabi's production planning and infrastructure investments.
Abu Dhabi
Offshore sour gas developments at Belbazem and Nasr fields drive capital deployment, with hydrogen sulfide concentrations exceeding fifteen percent requiring nickel-alloy completions. MOHAP environmental standards enforce layered compliance for well integrity and process safety management. The Ruwais industrial complex anchors petrochemical feedstock demand through expanding cracking capacity.
Dubai
Jebel Ali petrochemical manufacturing clusters pull processed gas volumes through integrated supply chains serving domestic power generation and water desalination. Federal energy security priorities redirect investment toward gas self-sufficiency as coal phase-out accelerates. The emirate's logistics infrastructure supports marine bunkering and aviation fuel distribution across the Gulf.
Sharjah
Onshore tight gas formations in the emirate's concession blocks remain underexplored relative to Abu Dhabi's offshore structures. Sharjah National Oil Company operates mature fields where artificial lift optimization compresses breakeven thresholds for enhanced recovery. Sajaa and Moveyid fields concentrate operational activity with heterogeneous carbonate porosity challenging standard stimulation techniques.
Northern Emirates
Fujairah, Ras Al Khaimah, Ajman, and Umm Al Quwain rely on Dolphin Energy's cross-border pipeline network for processed gas delivery to power generation and industrial facilities. MOHAP oversight extends federal environmental baselines across these lower-volume production zones. Limited indigenous reserves position these emirates as demand centers rather than upstream investment targets.
United Arab Emirates Oil and Gas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across concession tiers, with ADNOC's integrated operating companies dominating procurement decisions. The vendor base stratifies into three tiers: international majors holding equity stakes in ultra-sour gas projects, regional NOCs controlling midstream infrastructure, and specialized service contractors competing on outcome-based metrics. Dominant competitive moves include portfolio diversification into petrochemical integration and technology licensing partnerships for digital oilfield deployment.
Among Abu Dhabi-based national oil companies, ADNOC anchors the integrated operator archetype through its drilling-to-export infrastructure across Lower Zakum and Umm Shaif fields. TotalEnergies SE and BP PLC represent the international equity partner tier, holding concession stakes that demand specialized metallurgy and processing capabilities for high-hydrogen-sulfide environments. Dolphin Energy occupies a distinct midstream position, exemplifying cross-border infrastructure control through its pipeline network delivering processed gas to northern emirates and export markets.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Dolphin Energy |
| Abu Dhabi National Oil Company (ADNOC) |
| Sharjah National Oil Company |
| Dana Gas PJSC |
| TotalEnergies SE |
| Emirates National Oil Company Group (ENOC) |
| Crescent Petroleum |
| BP PLC |
| Others |
Value Network & Pricing Analysis
Dolphin Energy's cross-border pipeline network cost dynamics amplify supply concentration effects across Abu Dhabi's offshore concessions, translating upstream metallurgy premiums into differentiated pricing tiers for northern emirate gas buyers.
Pricing Analysis
Digital Oilfield technology-generation pricing gaps separate legacy SCADA-era service contracts from IoT-enabled predictive analytics packages and next-generation unified simulation environments. Contract-based long-term offtake structures dominate sour gas developments, with price differentiation driven by certification level under MOHAP technical standards and volume scale commitments from Ruwais petrochemical complexes. Cost compression in standard-grade artificial lift equipment is intensifying because procurement teams unbundle supply from technical services. Independent operators without ADNOC concession history exhibit highest price sensitivity; integrated service providers with regional certification histories command premium positioning.
Supply Chain Analysis
Upstream feedstock for ultra-sour gas completions draws from specialized metallurgy suppliers in Germany, Japan, and the United States. Nickel-alloy tubulars, high-pressure blowout preventers, and hydrogen sulfide-resistant elastomers constitute critical input dependencies. Single-source vulnerability concentrates in HPHT certification bodies qualified under ADNOC technical standards. Distribution runs through Jebel Ali logistics corridors serving offshore platform fabrication yards and Ruwais processing complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE oil and gas sector is approaching a platform-economics inflection as digital twin convergence collapses the traditional separation between reservoir engineering and production operations, with ADNOC's unified simulation environments establishing interoperability standards that reshape vendor competitive dynamics.
For Market Incumbents: Insulate artificial lift market share by deepening backward integration into predictive analytics software development, countering the threat of technology specialists unbundling equipment margins from outcome-based uptime guarantees. Prioritize certification investment under MOHAP's hardening well integrity standards to maintain procurement access concentration. For New Entrants and Emerging Players: Al Dhafra's underexplored tight gas formations offer first-mover positioning for hydraulic fracturing specialists capable of carbonate-specific stimulation techniques. Target Sharjah's mature Sajaa and Moveyid fields where heterogeneous porosity challenges incumbent recovery economics. Lead with digital twin integration capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from international majors' non-core service contractor portfolios, particularly artificial lift specialists with ADNOC regional track records. Long-term viability centers on gas self-sufficiency capital deployment through the analysis window. Monitor Dolphin Energy's cross-border pipeline utilization rates as the key inflection signal for northern emirate demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | ADNOC's unified simulation environments compress breakeven thresholds across Lower Zakum and Umm Shaif fields. |
| Backward Integration into Predictive Analytics | Oilfield service vendors capture margin pools shifting from equipment throughput to uptime guarantee outcomes. |
| HPHT Certification Investment | Specialized personnel scarcity under MOHAP standards creates procurement barriers favoring incumbent contractors. |
| Al Dhafra Unconventional Block Entry | First-mover hydraulic fracturing specialists address carbonate complexity limiting standard stimulation effectiveness. |
| Sour Gas Processing Capacity Expansion | Ruwais complex alignment with Emirates coal phase-out redirects capital toward strategic gas self-sufficiency priorities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ADNOC technical standards documentation, MOHAP environmental compliance filings, and international oil company concession disclosures. Reservoir engineers, artificial lift procurement managers at operating companies, and oilfield service contract specialists provided structured input. Customs data on nickel-alloy tubular imports, IEA Middle East gas market reports, and project development databases for Belbazem and Nasr fields supplied secondary validation. Bottom-up segmentation modeling triangulates against top-down macroeconomic energy demand projections.
Forecast inputs span upstream type, technology deployment tier, application focus, and end-user segment across the projection horizon. The analytical framework models Enhanced Oil Recovery spend trajectories, Digital Oilfield adoption curves, and Oilfield Services margin evolution. CAGRs derive from regression analysis against historical capital deployment patterns and forward-looking concession award timelines. Sour gas processing capacity buildout schedules and petrochemical feedstock demand elasticity inform scenario weighting.
Practitioners should monitor ADNOC concession renegotiation timelines and MOHAP regulatory amendment cycles for early signals of procurement rule changes. Forecasts reflect assumptions on carbon intensity policy continuity and regional gas pricing arbitration. Cross-checking against IEA World Energy Outlook Middle East supply benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market