
 Equatorial Guinea Oil and Gas Midstream Market | 2026-2036
Equatorial Guinea Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Equatorial Guinea Oil and Gas Midstream Market Foresight
Maintenance and lifecycle service contracts are restructuring how midstream operators monetize pipeline and processing assets in Equatorial Guinea. GEPetrol leverages its state-backed position to dominate onshore storage and terminal operations. Marathon Oil Company anchors deepwater export logistics through its integrated field-to-shore infrastructure. Kosmos Energy differentiates through independent operator models that bypass legacy joint venture structures.
Equatorial Guinea Oil and Gas Midstream encompasses the transportation, storage, and processing infrastructure bridging upstream extraction and downstream refining, with pipeline systems typically engineered for pressures exceeding 100 bar and designed to handle corrosive high-sour gas streams from offshore fields. Pipelines and processing services capture the dominant share of value as offshore field development drives demand for subsea tieback infrastructure and gas treatment capacity. Third-party services represent the fastest-expanding operational model as international independents seek non-integrated access to existing infrastructure.
The Ministry of Mines and Hydrocarbons enforces local content mandates that shape contractor selection and equipment sourcing for midstream projects. The country's national petroleum regulator imposes technical standards on pipeline integrity and gas processing emissions that operators must satisfy to maintain production sharing contract compliance. Stakeholders should monitor how regulatory pressure on gas flaring reduction reshapes investment priorities across processing and transportation infrastructure.
Market Dynamics
Bioko Island's integrated processing cluster concentrates midstream infrastructure ownership, creating asymmetric access for independent operators seeking export capacity. The Ministry of Mines and Hydrocarbons leverages this geographic chokepoint to enforce local content mandates that reshape contractor selection and equipment sourcing patterns.
Growth Catalysts
- Local Content Mandates:The Ministry of Mines and Hydrocarbons requires domestic labor and equipment sourcing for infrastructure projects, redirecting procurement toward local fabrication yards and service providers.
- Offshore Field Development:Subsea tieback infrastructure for deepwater gas discoveries drives demand for high-pressure pipeline systems and gas treatment capacity at Punta Europa processing complex.
- Flare Reduction Enforcement:Regulatory pressure on gas flaring reduction compels investment in gas gathering networks and processing facilities that convert previously vented resources into exportable products.
Market Restraints
- Specialized Equipment Dependence:Corrosion-resistant alloys for sour gas service face limited domestic supply, forcing reliance on European and Asian fabricators with extended lead times.
- Single-Point Infrastructure Concentration:Punta Europa terminal handles the majority of liquefied petroleum gas and condensate exports, creating vulnerability to operational disruptions or force majeure events.
- Joint Venture Legacy Structures:GEPetrol's dominance in onshore storage and terminal operations restricts third-party access to critical infrastructure for independent producers.
Strategic Opportunities
- Third-Party Access Models:International independents seek non-integrated access to existing pipeline and processing infrastructure, creating demand for open-access tariff frameworks.
- Maintenance Contract Restructuring:Lifecycle service agreements for aging pipeline systems offer recurring revenue streams that monetize operational expertise rather than capital deployment.
- Condensate Processing Expansion:Petrochemical plants across West Africa are expanding offtake agreements for processed condensates, diversifying export destinations beyond traditional Atlantic basin markets.
Industry Challenges
- Pipeline Integrity Expertise Gap:High-pressure sour gas pipeline systems require specialized inspection and maintenance capabilities that remain scarce within domestic labor markets.
- Production Sharing Contract Compliance:Operators must satisfy technical standards on pipeline integrity and emissions monitoring to maintain regulatory compliance, creating administrative burden for smaller independents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equatorial Guinea Oil and Gas Midstream Market |
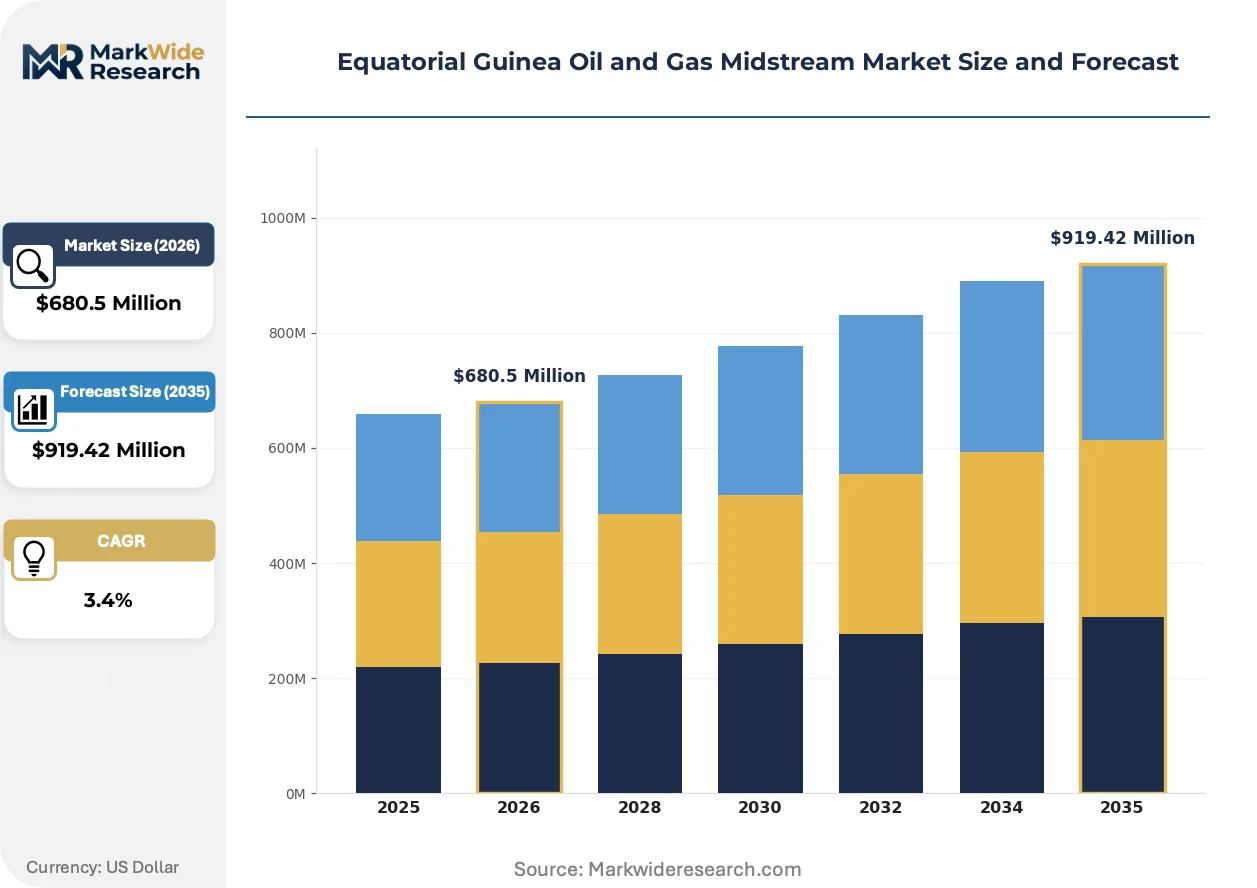
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $919.42 Million |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage Facilities, Transportation Services, Processing Services Operational Model: Integrated Operations, Third-Party Services, Joint Ventures, Independent Operators Energy Source: Natural Gas, Crude Oil, LPG, Condensates End User: Refineries, Petrochemical Plants, Utilities, Industrial Consumers |
| Companies Covered | Sociedad Nacional de GE, ConocoPhillips, Saipem SPA, Trident Energy, GEPetrol, Equatorial Guinea of Petroleum, Marathon Oil Company, Kosmos Energy, Maritime Developments Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equatorial Guinea Oil and Gas Midstream Market Shifts & Advancements
Digital monitoring systems and modular processing architectures are compressing project timelines for midstream infrastructure deployment. These shifts enable faster response to reservoir performance changes and reduce capital lock-up periods for marginal field developments.
Subsea multiphase pumping technology is rewriting field development economics by eliminating surface platform requirements for marginal discoveries. Independent operators including Kosmos Energy are deploying these systems at accelerated pace across offshore blocks. The technology is compressing breakeven thresholds and enabling production from reservoirs previously deemed sub-commercial.
The Ministry of Mines and Hydrocarbons has tightened local content enforcement through mandatory domestic employment quotas and equipment sourcing requirements. Industrial consequence includes extended procurement cycles as operators qualify local fabrication capabilities. Midstream construction segments face the most acute compliance pressure, with contractors restructuring supply chains to incorporate regional steel fabrication and coating services.
Buying patterns among international independents favor unbundled infrastructure access over integrated joint venture structures. Marathon Oil Company and newer entrants are negotiating standalone processing and export agreements that bypass legacy partnership models. This behavioral shift is most visible among deepwater leaseholders seeking operational autonomy from GEPetrol-dominated infrastructure consortia.
Equatorial Guinea Oil and Gas Midstream Market Segmentation
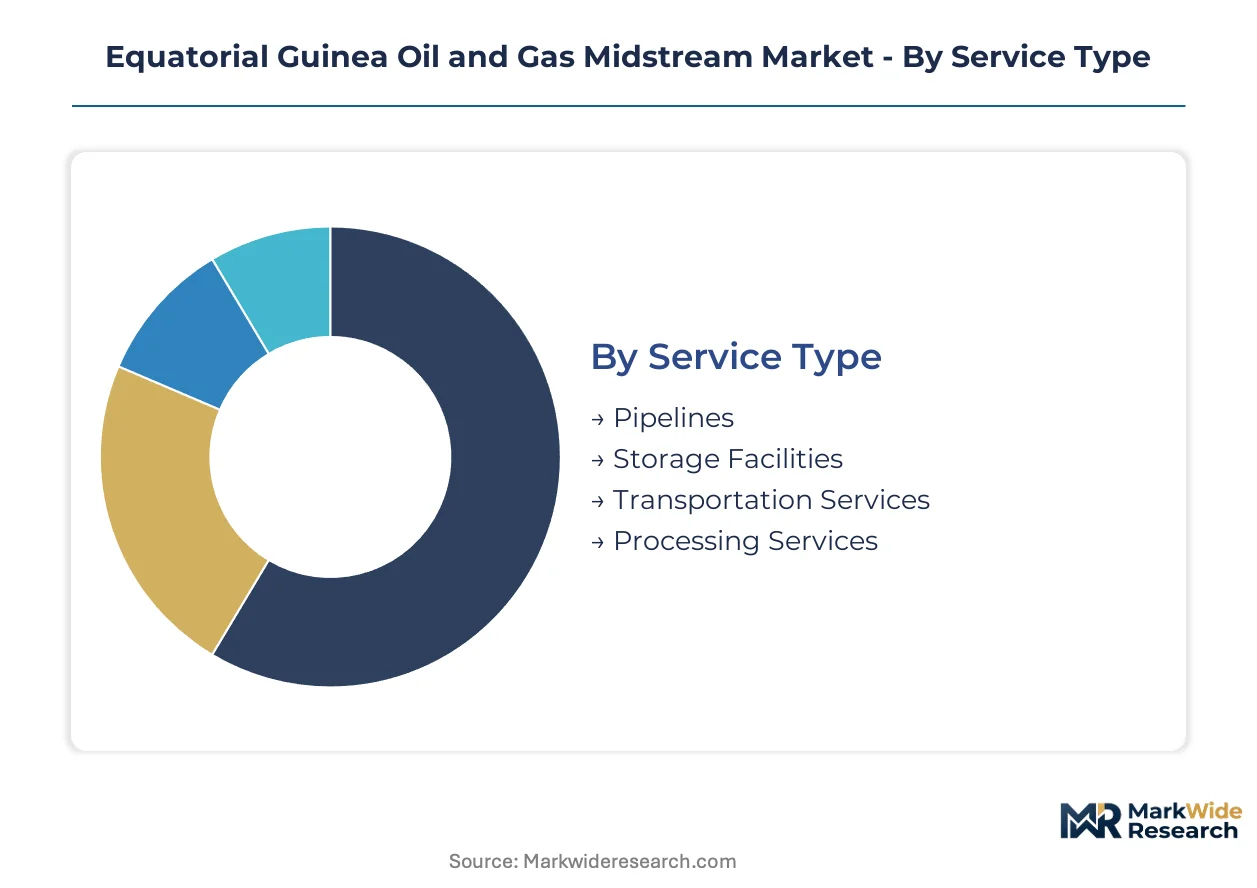
Midstream infrastructure in Equatorial Guinea fragments across service delivery modes, operational ownership structures, and hydrocarbon types. Each segmentation dimension reveals distinct competitive dynamics around Bioko Island's processing cluster and Punta Europa terminal access. Understanding these splits clarifies where GEPetrol dominance yields to third-party opportunity.
Service Type:
Pipelines and processing services command premium margins through technical complexity, while storage and transportation operate as volume-commoditized segments.
- Pipelines:High-pressure steel systems engineered for sour gas service above 100 bar, with subsea tieback infrastructure dominating capital allocation around Alen and Aseng field developments. Punta Europa gathering networks face integrity pressures from corrosive offshore streams.
- Processing Services:Gas treatment trains and condensate stabilization units at Punta Europa complex handle feedstock from Marathon Oil and Kosmos Energy deepwater blocks. Flare reduction mandates are accelerating investment in gas gathering and liquefaction capacity.
- Storage Facilities:Above-ground crude tanks and pressurized LPG spheres concentrated at Malabo terminals.
- Transportation Services:Marine loading arms and vessel chartering for Atlantic basin export routes.
Today's leader: Processing Services. Tomorrow's challenger: Pipelines.
Operational Model:
Joint venture structures concentrate infrastructure control, while independent and third-party models are gaining regulatory favor through local content enforcement.
- Joint Ventures:GEPetrol anchors legacy partnerships with international operators, locking in preferential terminal access and tariff structures that disadvantage newer entrants at Punta Europa.
- Third-Party Services:Open-access frameworks are expanding most quickly as Kosmos Energy and independents negotiate standalone processing agreements outside integrated consortia. The Ministry of Mines and Hydrocarbons is pressuring infrastructure unbundling.
- Integrated Operations:Marathon Oil maintains captive field-to-shore systems across Alba and Aseng blocks.
- Independent Operators:Smaller leaseholders pursuing non-integrated export solutions for marginal discoveries.
Joint ventures still dominate fee generation. Third-party access is climbing the fastest trajectory.
Energy Source:
Natural gas infrastructure attracts disproportionate capital against liquids, reflecting West African LNG demand and domestic power generation requirements.
- Natural Gas:Sour gas processing and LNG liquefaction trains at Punta Europa, with subsea multiphase pumping eliminating platform requirements for marginal deepwater discoveries. Bioko Island's integrated cluster handles feedstock from Alba, Aseng, and Alen fields.
- Condensates:Ultra-light hydrocarbon streams requiring stabilization before petrochemical offtake to West African plants expanding processing agreements.
- Crude Oil:Medium-sweet offshore production routed through single-point moorings.
- LPG:Fractionated propane and butane for regional cooking fuel and industrial feedstock.
Natural gas infrastructure retains revenue concentration. Condensate processing capacity is expanding most quickly.
End User:
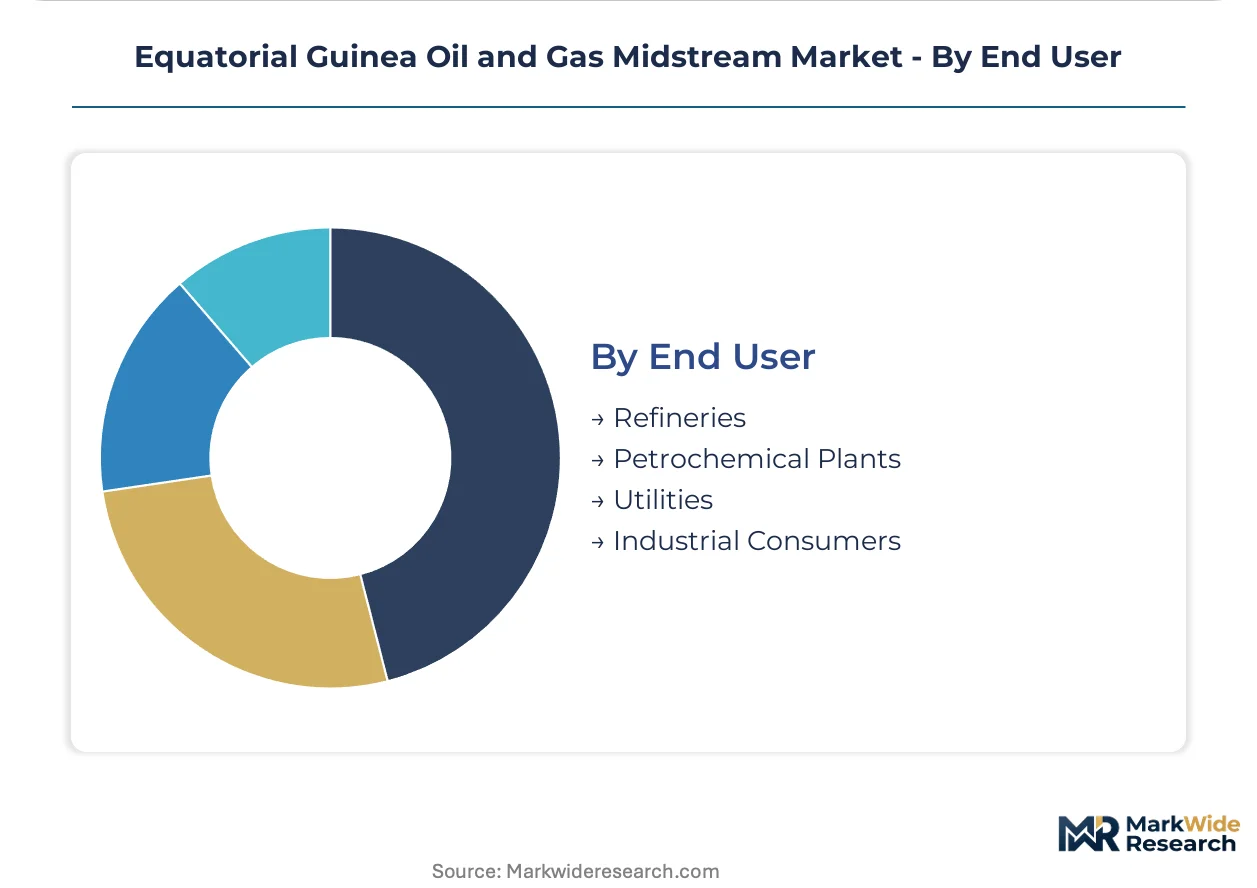
Refinery demand anchors baseline throughput, while petrochemical buyers are diversifying export destinations beyond traditional Atlantic markets.
- Refineries:Punta Europa's small domestic refinery and West African buyers absorb stabilized crude and intermediate products, with limited local upgrading capacity forcing reliance on export markets.
- Petrochemical Plants:Nigerian and regional West African processors are expanding offtake agreements for Equatorial Guinea condensates, creating alternative demand centers beyond European refining.
- Utilities:Power generation feedstock for Bioko Island grid and regional electricity exporters.
- Industrial Consumers:LPG distributors and marine bunkering operations.
Refineries maintain volume leadership. Petrochemical offtake is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equatorial Guinea's midstream infrastructure outpaces neighboring Gabon in gas processing capacity, yet Cameroon commands stronger regional pipeline connectivity into West African markets. Both countries navigate similar local content enforcement patterns.
Litoral Province
Offshore gas discoveries at Alen and Aseng fields drive subsea tieback demand for high-pressure gathering systems. The Ministry of Mines and Hydrocarbons mandates domestic labor quotas for all pipeline construction contracts. Punta Europa processing complex anchors condensate stabilization and LNG liquefaction throughput for Atlantic basin exports.
Bioko Island
Integrated storage terminals and marine loading facilities concentrate export logistics for Marathon Oil and Kosmos Energy production streams. Regulatory pressure on gas flaring reduction accelerates investment in gas gathering networks previously vented to atmosphere. Malabo terminal cluster handles pressurized LPG spheres and crude tankage with force majeure vulnerability from single-point concentration.
Continental Region
Onshore pipeline corridors from Rio Muni basin fields require corrosion-resistant alloys for sour gas service above 100 bar. The national petroleum regulator imposes integrity inspection standards that extend procurement cycles for European and Asian fabricators. Bata industrial zone hosts limited domestic fabrication yards qualifying under local content mandates.
Annobón Province
Isolated offshore positioning creates marginal field development challenges without integrated infrastructure access. Third-party service negotiations bypass legacy GEPetrol joint venture structures for independent operator models. Regional planning envisions subsea multiphase pumping to eliminate platform requirements for sub-commercial reservoirs.
Corisco Bay
Border zone with Gabon generates cross-border pipeline routing discussions for shared reservoir development. Maritime boundary agreements shape joint development authority frameworks for midstream infrastructure spanning territorial waters. Exploration leaseholders evaluate standalone processing agreements outside Punta Europa-dominated consortia.
Equatorial Guinea Oil and Gas Midstream Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators controlling terminal access while independents force unbundling of legacy infrastructure. State-backed entities anchor onshore storage and processing capacity through preferential tariff structures. Three archetypes dominate: national oil companies with regulatory capture, international majors with captive field-to-shore systems, and independents pursuing open-access frameworks. Competitive moves concentrate on third-party processing agreements and maintenance contract restructuring for aging pipeline networks.
Among state-affiliated operators, GEPetrol occupies a position exemplifying integrated infrastructure control through Punta Europa terminal dominance. Marathon Oil Company and Kosmos Energy represent the independent archetype, each negotiating standalone export arrangements that bypass traditional joint venture structures. These three entities collectively illustrate the tension between legacy consolidation and emerging unbundled access models reshaping contractor relationships across Bioko Island's processing cluster.
| Leading Market Players |
|---|
| Sociedad Nacional de GE |
| ConocoPhillips |
| Saipem SPA |
| Trident Energy |
| GEPetrol |
| Equatorial Guinea of Petroleum |
| Marathon Oil Company |
| Kosmos Energy |
| Maritime Developments Ltd |
| Others |
Supply & Pricing Matrix
Henry Hub natural gas futures and Northwest European LNG spot indices cascade through Equatorial Guinea's midstream pricing tiers, compressing margins on standardized processing contracts while preserving premiums for sour-gas-ready infrastructure and expedited condensate stabilization slots. The Ministry of Mines and Hydrocarbons reinforces this stratification through local content multipliers that inflate procurement costs for non-compliant contractors.
Pricing Analysis
Capacity additions in West African petrochemical corridors are reshaping price floors for condensate processing slots at Punta Europa. Contract-based long-term offtake agreements dominate, with price differentiation anchored in corrosion-resistant alloy specifications and Ministry certification tiers. Cost compression in standard gas treatment services is intensifying because Nigerian and Ghanaian buyers are expanding captive processing capacity. National oil companies exhibit lowest price sensitivity due to integrated cost recovery mechanisms, while independent leaseholders face acute margin pressure on marginal field tiebacks.
Supply Chain Analysis
Regional distribution centers for high-pressure pipeline components concentrate in Rotterdam and Singapore, with hub-and-spoke patterns feeding fabrication yards in Douala and Port Harcourt. Sourcing draws from German seamless pipe mills, Japanese valve manufacturers, and South Korean subsea equipment specialists. Nickel-molybdenum alloy plate and multiphase pumping systems remain critical dependencies. Single-source vulnerability persists for subsea umbilical terminations qualified to Punta Europa specifications. Distribution runs through maritime freight corridors into Malabo and Bata terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equatorial Guinea's midstream infrastructure represents a late-cycle quality story as West African petrochemical buyers shift procurement specifications toward low-sulfur condensate grades and guaranteed flare-compliance certifications.
For Market Incumbents: Deploy backward integration into European specialty alloy supply chains to secure corrosion-resistant pipe inventory against extended lead times. Consolidate maintenance contract portfolios for aging Punta Europa gathering networks before third-party service providers qualify under revised local content frameworks. GEPetrol's terminal dominance faces erosion from open-access tariff negotiations pushed by Kosmos Energy and Marathon Oil independents. For New Entrants and Emerging Players: Begin with standalone processing agreements for Annobón Province marginal fields, where subsea multiphase pumping eliminates platform capital requirements and legacy joint venture structures carry less institutional weight. Target condensate stabilization capacity expansion ahead of Nigerian petrochemical feedstock demand growth. Negotiate direct offtake relationships with West African polyolefin producers bypassing integrated export consortia. For Investors and Strategic Acquirers: Asymmetric upside sits with maintenance and lifecycle service specialists holding Punta Europa integrity management contracts. Long-term viability hinges on recurring revenue streams from sour gas pipeline inspection and gas treatment train refurbishment rather than greenfield infrastructure deployment. Monitor Ministry enforcement patterns on local content quotas as the inflection signal for contractor margin compression or qualification barrier reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Condensate Processing Expansion | Captures Nigerian and Ghanaian petrochemical feedstock demand shifting from European refining. |
| Subsea Multiphase Pumping Deployment | Enables Marathon Oil and independents to commercialize marginal Alen and Aseng satellite reservoirs. |
| Local Content Compliance Investment | Qualifies contractors for Ministry-mandated procurement quotas at Punta Europa and Bioko Island terminals. |
| Open-Access Tariff Negotiation | Allows Kosmos Energy to bypass GEPetrol-dominated joint venture structures for export capacity. |
| Pipeline Integrity Service Restructuring | Monetizes operational expertise through recurring maintenance contracts for high-pressure sour gas systems. |
Research Methodology
Direct dialogue with Ministry of Mines and Hydrocarbons officials, GEPetrol infrastructure planners, Marathon Oil deepwater project managers, Kosmos Energy commercial negotiators, and West African petrochemical procurement directors grounded qualitative assessments. Secondary validation drew from national petroleum regulator technical standards, Ministry local content enforcement circulars, Punta Europa terminal throughput disclosures, and West African LNG trade flow databases. Bottom-up field development timelines and top-down regional infrastructure capacity assessments were triangulated against contract award announcements.
Bottom-up modeling of individual block development schedules and top-down regional gas processing capacity constraints were reconciled across the projection horizon. Segmentation dimensions included service type, operational ownership structure, hydrocarbon category, and end-user industry. CAGRs were derived from infrastructure investment pipelines and offtake agreement tenors. Forecast inputs incorporated flare reduction mandate compliance costs and subsea multiphase pumping adoption curves for marginal field economics.
Several conditions sit outside the modeled scope, including maritime boundary arbitration outcomes affecting Corisco Bay cross-border pipeline routing, force majeure events at Punta Europa's single-point terminal concentration, and abrupt shifts in Ministry local content enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market