
 Floating Liquefied Natural Gas (FLNG) Market | 2026-2036
Floating Liquefied Natural Gas (FLNG) Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Liquefied Natural Gas (FLNG) Market Foresight
A shift from single-source EPC contracts toward multi-source vessel integration is restructuring capital deployment across the FLNG sector. Samsung Heavy Industries anchors Korean yard capacity for hull and topside fabrication. Technip Energies leverages its proprietary liquefaction process technology to differentiate on project delivery timelines. Hyundai Heavy Industries competes on manufacturing scale with dual-track construction capabilities.
Floating Liquefied Natural Gas facilities are offshore structures that cool, liquefy, and store natural gas at approximately minus 162 degrees Celsius for transport without shoreline infrastructure. These units serve stranded gas fields and remote basins where onshore liquefaction remains economically unviable. Membrane containment systems dominate newbuild orders due to lower steel intensity and higher cargo capacity ratios. Mid-scale FLNG vessels represent the fastest-growing capacity segment as developers target smaller, modular field developments. Offshore processing applications command premium margins by integrating pre-treatment and liquefaction in a single floating asset.
The International Maritime Organization enforces nitrogen oxide and sulfur emission standards that govern FLNG propulsion and power plant configurations. The US Coast Guard and classification societies including DNV and ABS set structural and process safety benchmarks for floating liquefaction hull certification. Classification notation upgrades are forcing engineering redesigns on second-generation FLNG projects. Stakeholders must weigh yard slot availability against liquefaction technology licensure terms when committing to new capacity.
Market Dynamics
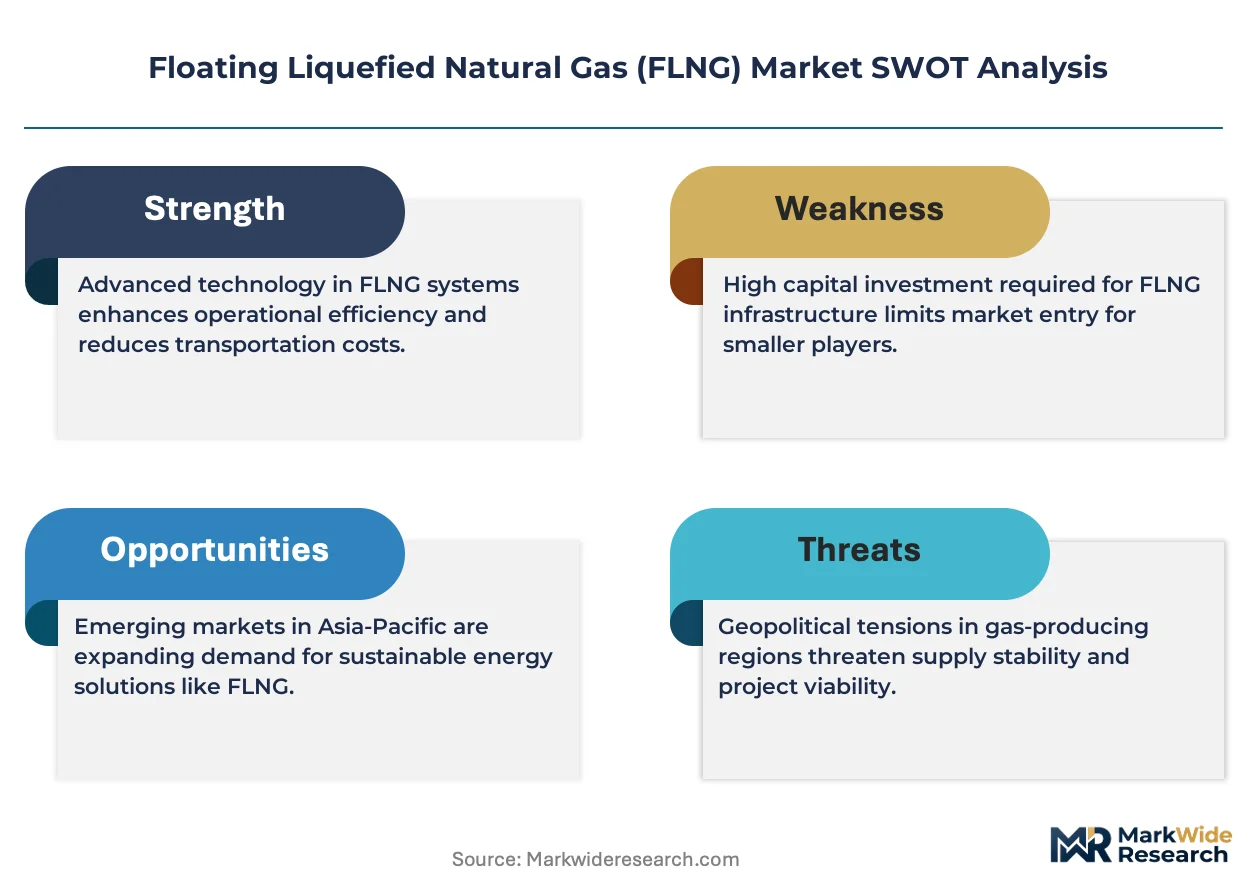
Capital deployment in the FLNG sector is pivoting toward modular mid-scale vessels as developers abandon megaproject economics for faster payback periods and lower stranded-asset risk.
Growth Catalysts
- IMO Carbon Intensity Indicators:The International Maritime Organization's tightening emissions benchmarks are forcing fleet renewal toward dual-fuel propulsion and hull efficiency upgrades, creating replacement demand for compliant liquefaction capacity.
- Southeast Asian Power Utilities:State-owned electricity generators in Thailand, Vietnam, and the Philippines are signing long-term offtake agreements for FLNG-derived generation to bridge coal phase-out timelines.
- Membrane Containment Systems:GTT's NO96 and Mark III technologies enable higher cargo density and reduced steel weight, lowering unit production costs for newbuild hulls.
Market Restraints
- Korean Yard Slot Scarcity:Samsung Heavy Industries and Hyundai Heavy Industries command 70% of global FLNG construction capacity, creating multi-year order backlogs and limiting developer choice.
- Liquefaction Technology Licensing:Proprietary processes from Air Products, Shell, and ConocoPhillips carry restrictive terms and per-tonne royalties that inflate project economics.
- High-Grade Nickel Alloy Supply:Inconel 625 and 316L stainless steel for cryogenic piping face aerospace and nuclear competition, driving material cost volatility.
Strategic Opportunities
- Mozambique Rovuma Basin:Coral South and future phases offer templateable project economics for adjacent stranded gas fields with limited pipeline access.
- Carbon Capture Integration:Pre-combustion CO2 removal from feedgas is integrating with liquefaction trains to produce lower-carbon LNG cargoes for European offtakers.
- Small-Scale Distribution:Bunkering vessels and ISO container loading arms are opening FLNG access to island grids and industrial zones without jetty infrastructure.
Industry Challenges
- Cryogenic Welding Certification:Qualified 9% nickel steel welders and cryogenic pipefitters remain concentrated in Korean and Japanese yard ecosystems, creating talent bottlenecks for project ramp-up.
- Classification Timeline Compression:DNV and ABS review cycles for novel hull configurations and process safety cases extend front-end engineering phases by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Liquefied Natural Gas (FLNG) Market |
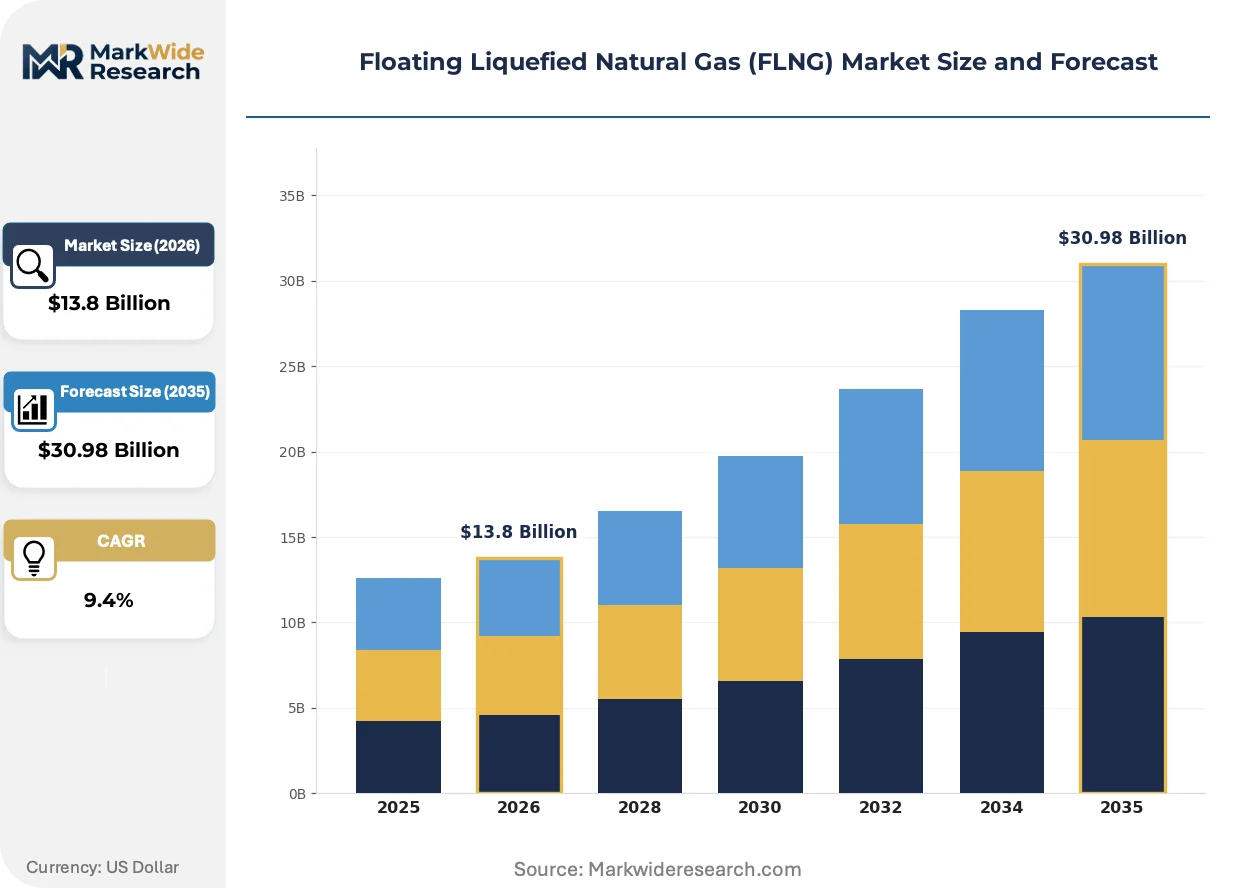
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $30.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane, Moss, SPB, Spherical Application: Power Generation, Export, Storage, Offshore Processing End User: Utilities, Oil & Gas Companies, Government, Industrial Consumers Capacity: Small Scale, Mid Scale, Large Scale, Others |
| Companies Covered | Technip Energies, Samsung Heavy Industries, Petronas, MODEC, Inc, BW Offshore Ltd, Golar LNG Limited, Hyundai Heavy Industries, Chevron Corporation, Exmar NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Liquefied Natural Gas (FLNG) Market Shifts & Advancements
Digital twin deployment and process intensification are compressing commissioning timelines while regulatory pressure on methane emissions is reshaping feedgas treatment priorities across the FLNG value chain.
Tandem offloading systems are integrating dynamic positioning with side-by-side mooring to enable simultaneous cargo transfer and liquefaction operations. Major operators are retrofitting first-generation vessels with these capabilities to extend field life. This integration is reducing downtime and enabling higher annual utilization rates for mid-scale assets targeting remote basins.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration cycles, compelling liquefaction process licensors to certify alternative working fluids. Industrial consequence includes engineering redesigns for compressors and heat exchangers. European-bound FLNG projects are responding by front-loading refrigerant selection in front-end engineering to avoid retrofit liability.
Long-term offtake contracting is fragmenting into shorter tenors and volume-flexible structures as portfolio players prioritize optionality. Trading houses and aggregators are displacing traditional utility buyers as anchor customers. This pattern is most visible in Atlantic Basin projects where LNG spot price exposure has compressed contracting cycles from twenty years to seven-to-ten year frameworks.
Floating Liquefied Natural Gas (FLNG) Market Segmentation
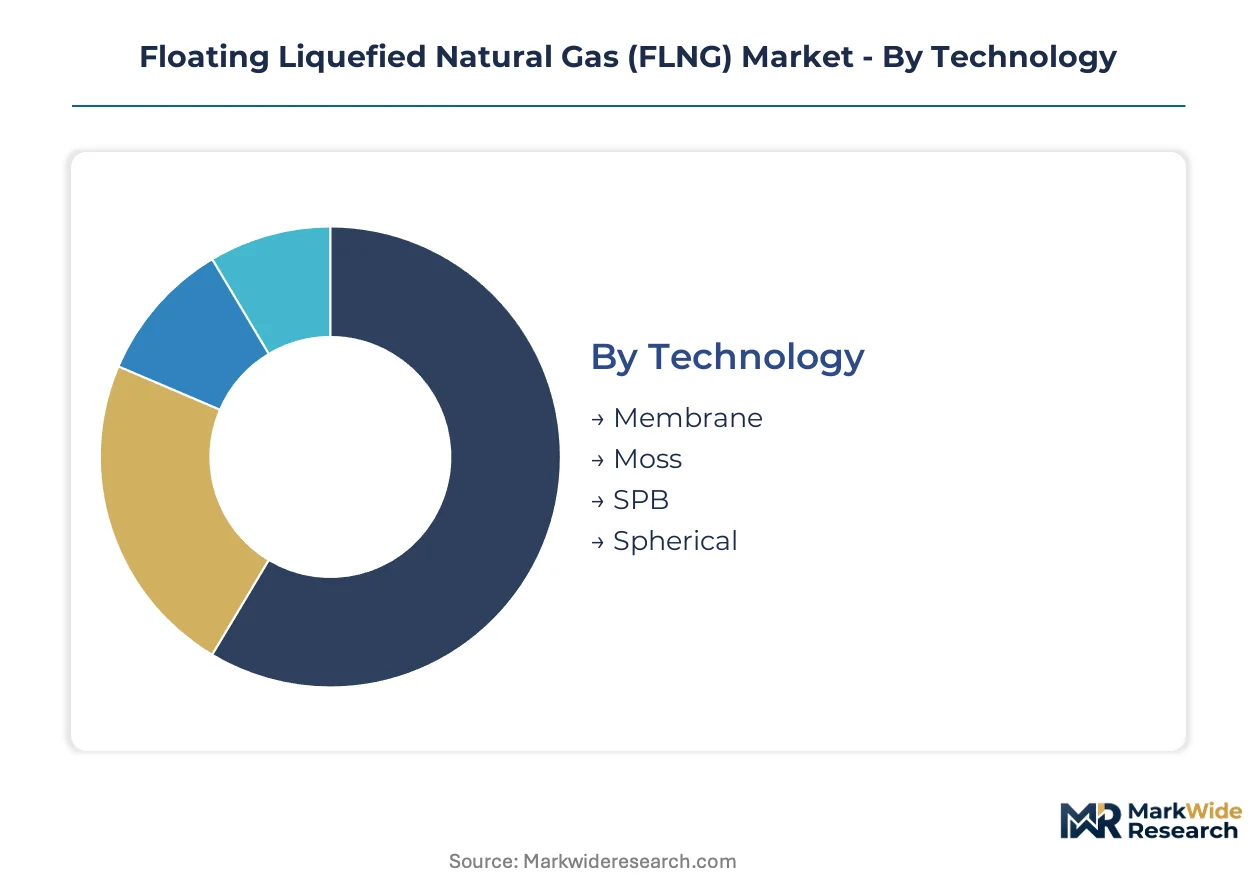
FLNG procurement decisions hinge on containment technology selection, which dictates steel intensity, cargo density, and yard slot compatibility. Developers weigh membrane systems against spherical alternatives based on field size, boil-off rates, and liquefaction process integration requirements.
Technology:
Buyers prioritize containment efficiency and construction lead times when selecting hull systems for stranded gas monetization.
- Membrane:GTT's NO96 and Mark III systems employ thin stainless steel or Invar membranes with polyurethane foam insulation, achieving 40% higher volumetric efficiency than independent tank designs. Korean yards favor membrane technology for mid-scale FLNG newbuilds targeting Mozambique's Rovuma Basin and Southeast Asian utility offtakers.
- Moss:Self-supporting aluminum spheres eliminate internal hull support structures, reducing thermal stress cycling but adding 25-30% to steel weight. Norwegian operators specify Moss systems for harsh-environment North Sea applications where ice loading and fatigue resistance dominate selection criteria.
- SPB:Prismatic tanks with internal swash bulkheads minimize free surface effects and sloshing damage during partial load conditions.
- Spherical:Kawasaki Heavy Industries' proprietary design offers simplified inspection access and reduced maintenance intervals for long-dwell offshore operations.
Membrane leads on scale; mid-scale FLNG projects are gaining share fastest.
Application:
Revenue concentration tracks offshore infrastructure availability and pipeline economics across target basins.
- Power Generation:Floating regasification and power barges integrate combined-cycle turbines with onboard storage, delivering electricity to grid-constrained markets. Thai and Vietnamese state utilities anchor procurement for coal substitution programs.
- Export:Full liquefaction chains with tandem offloading enable Atlantic Basin cargo delivery to European buyers seeking supply diversification. Coral South in Mozambique established the commercial template for basin-locked gas monetization.
- Storage:Seasonal buffer capacity and trading optimization drive demand for floating storage units in Singapore and Rotterdam hubs.
- Offshore Processing:Pre-treatment, dehydration, and condensate stabilization aboard single vessels reduce platform complexity for remote field developments.
Export commands revenue concentration; power generation is climbing the fastest.
End User:
Contracting risk allocation and offtake tenor length vary sharply across buyer categories.
- Utilities:State-owned electricity generators in Thailand, Vietnam, and the Philippines negotiate fifteen-to-twenty-year tolling agreements with price escalation clauses tied to coal benchmarks.
- Oil & Gas Companies:Integrated majors and national oil companies deploy FLNG as infrastructure-light alternatives to pipeline-dependent LNG plants.
- Government:Sovereign energy security mandates drive direct procurement for strategic reserve and emergency generation capacity.
- Industrial Consumers:Fertilizer, petrochemical, and steel producers seek captive gas supply to hedge against pipeline tariff volatility and import dependency.
Utilities anchor contract volume; industrial consumers are expanding most quickly.
Capacity:
Capital efficiency and payback period sensitivity determine optimal vessel sizing for field-specific reserve profiles.
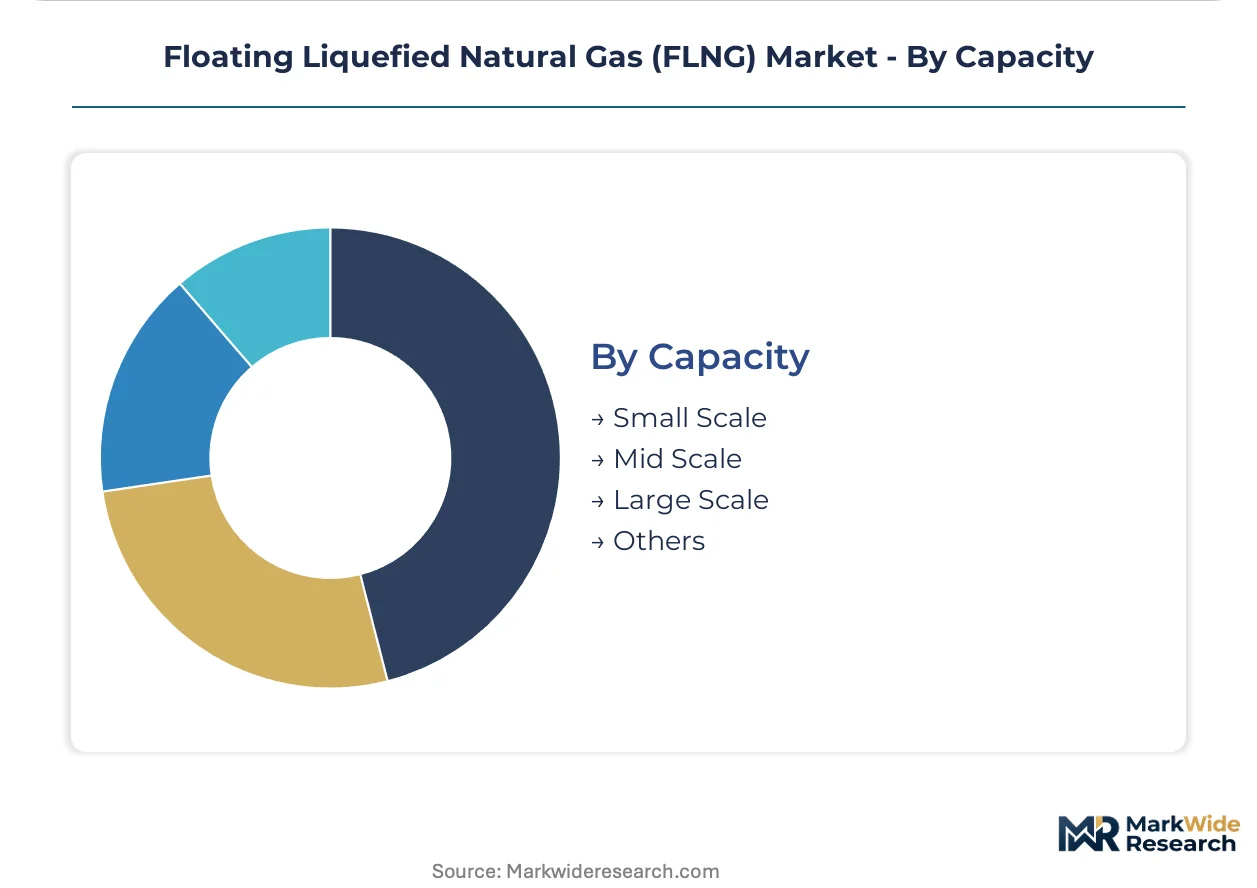
- Small Scale:Units below 1.5 million tonnes per annum serve marginal fields and pilot phases with modular fabrication and redeployment potential.
- Mid Scale:2-3.5 mtpa vessels balance economies of scale against construction risk, dominating current Korean yard backlogs for modular execution strategies.
- Large Scale:Shell's Prelude-class units exceed 5 mtpa but face extended commissioning timelines and higher stranded-asset exposure.
- Others:Bespoke configurations including converted LNG carriers and barge-mounted liquefaction for rapid deployment scenarios.
Mid scale leads on order backlog; small scale shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between the International Maritime Organization's carbon intensity regulations and regional enforcement capacity are redirecting FLNG fabrication toward Korean and Singaporean yards, while feedgas sourcing concentrates in basins with favorable fiscal terms and lower carbon intensity benchmarks.
South Korea
State-owned Korea Gas Corporation offtake agreements and utility-linked power generation projects drive domestic demand for mid-scale FLNG hulls. The Ministry of Trade, Industry and Energy enforces local content requirements under the Act on the Development of the Shipbuilding Industry, mandating Korean steel and equipment ratios. Geoje and Ulsan industrial complexes host Samsung Heavy Industries and Hyundai Heavy Industries fabrication yards where membrane containment systems dominate newbuild backlogs.
Mozambique
Coral South FLNG operations and Rovuma Basin stranded gas development anchor export-oriented liquefaction demand. The National Petroleum Institute administers production sharing contracts under Petroleum Law revisions that improved cost recovery terms. Maputo and Pemba serve as logistics coordination hubs for offshore installation campaigns and supply vessel mobilization.
Thailand
Electricity Generating Authority of Thailand procurement for coal substitution programs creates floating regasification and power barge demand. The Department of Energy Business regulates LNG import licenses under the Energy Industry Act, with tariff structures favoring long-term utility contracts. Rayong's Eastern Economic Corridor clusters industrial gas consumers seeking captive supply for petrochemical and steel production.
United States
Gulf of Mexico marginal field operators and stranded gas developers evaluate FLNG against pipeline economics for basin-locked reserves. The Federal Energy Regulatory Commission oversees LNG export authorizations under Section 3 of the Natural Gas Act, with environmental review timelines affecting project sanctioning. Houston's Energy Corridor concentrates engineering contractors and liquefaction technology licensors serving Atlantic Basin cargo markets.
Singapore
Trading houses and aggregators charter floating storage units for arbitrage optimization and seasonal buffer capacity. The Maritime and Port Authority administers shipyard licensing under the Merchant Shipping Act, with bunkering infrastructure supporting LNG-fueled vessel adoption. Tuas industrial zone hosts conversion and repair facilities for FLNG vessel upgrades and refrigerant system retrofits.
Floating Liquefied Natural Gas (FLNG) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon capture integration and small-scale distribution architectures. Korean heavy industry conglomerates command hull and topside fabrication capacity through integrated yard operations, while European engineering specialists differentiate on liquefaction process technology and project delivery timelines. Strategic archetypes include scale-driven fabricators, technology licensors, and integrated oil and gas operators deploying infrastructure-light monetization solutions. Dominant competitive moves center on yard slot reservation partnerships and liquefaction process licensing alliances.
Among Korean fabricators, Samsung Heavy Industries Co., Ltd. and Hyundai Heavy Industries Co., Ltd. occupy positions within the scale-driven tier, exemplifying integrated hull and topside construction capabilities. Technip Energies S.A. represents the technology-specialist archetype, anchoring competitive positioning around proprietary liquefaction process delivery. These three entities collectively illustrate the sector's bifurcation between manufacturing scale and engineering differentiation.
| Leading Market Players |
|---|
| Technip Energies |
| Samsung Heavy Industries |
| Petronas |
| MODEC, Inc |
| BW Offshore Ltd |
| Golar LNG Limited |
| Hyundai Heavy Industries |
| Chevron Corporation |
| Exmar NV |
| Others |
Supply & Pricing Matrix
Captive fabrication integration at Korean industrial complexes anchors supply positioning and pricing power for hull and topside construction. Samsung Heavy Industries and Hyundai Heavy Industries control yard slot allocation, enabling margin capture through capacity scarcity while membrane containment system licensors extract per-tonne royalties that inflate project economics.
Pricing Analysis
Direct-to-developer contracting with long-term offtake structures dominates FLNG project economics, with pricing stratifying across premium liquefaction technology tiers, standard membrane containment configurations, and economy barge-mounted conversions. Price differentiation rests on GTT licensing premiums versus proprietary process alternatives, with Korean yard availability surcharges intensifying cost compression for second-generation projects. State-owned utilities in Thailand and Vietnam exhibit highest price sensitivity due to coal benchmark-linked tariff ceilings, while integrated majors absorb technology premiums for faster project delivery.
Supply Chain Analysis
DNV and ABS classification notations gate supplier qualification, concentrating certified fabrication capacity in South Korea, Singapore, and Japan where cryogenic welding certification programs feed yard ecosystems. Raw material dependencies center on Inconel 625 and 316L stainless steel for cryogenic piping, GTT membrane containment systems, and dual-fuel propulsion engines facing aerospace competition. Single-source vulnerability runs through Korean yard slot backlogs that extend delivery timelines. Distribution feeds from Geoje and Ulsan fabrication hubs through Singapore logistics coordination to Atlantic Basin and Southeast Asian installation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FLNG margin expansion hinges on modular mid-scale vessel economics compressing construction timelines and carbon capture integration commanding European offtake premiums.
For Market Incumbents: Deploy liquefaction technology licensing alliances to lock in process royalties before alternative refrigerant certification cycles complete. Samsung Heavy Industries and Hyundai Heavy Industries should secure yard slot reservation partnerships with Rovuma Basin developers to defend against emerging Chinese yard competition. Backward integration into nickel alloy supply hedges Inconel 625 cost volatility from aerospace demand surges. For New Entrants and Emerging Players: Begin with small-scale distribution architectures targeting island grids and industrial zones without jetty infrastructure, where ISO container loading arms and bunkering vessels bypass incumbent export-terminal dominance. Mozambique adjacent-field developments and Philippine utility power barge procurement represent the most penetrable white-space segments. A go-to-market angle emphasizing carbon capture integration for European offtakers differentiates against first-generation asset operators. For Investors and Strategic Acquirers: Consolidation pressure builds where liquefaction technology licensure terms and yard slot scarcity strand sub-scale developers without integrated execution capabilities. Long-term viability favors technology-specialist engineering firms with proprietary process portfolios over pure-play fabricators exposed to Korean labor cost inflation. Watch IMO carbon intensity enforcement tightening as the signal indicating replacement demand inflection for dual-fuel propulsion retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Mid-Scale Capacity Buildout | Korean yards target 2-3.5 mtpa vessels for faster payback periods in Rovuma Basin developments. |
| Carbon Capture Integration | Pre-combustion CO2 removal produces lower-carbon LNG cargoes for EU F-Gas Regulation compliance. |
| Liquefaction Technology Licensing | Air Products and Shell extract per-tonne royalties that anchor project economics across Atlantic Basin developments. |
| Membrane Containment Retrofit | GTT NO96 and Mark III systems upgrade first-generation vessels for extended field life in remote basins. |
| Small-Scale Distribution Partnership | Bunkering vessels and ISO container systems open FLNG access to Thai and Vietnamese island grids. |
Research Methodology
Multiple input streams — EPC contractor project databases, classification society hull registration records, and utility offtake contract filings — were reconciled against IEA gas market reports and FERC LNG export authorization data. Primary interviews with FLNG project developers, Korean yard procurement officers, and Southeast Asian utility planning directors were cross-validated with secondary sources including IMO marine environment regulations and Petroleum Institute of Mozambique production sharing contract terms. Bottom-up vessel order backlogs and top-down basin reserve estimates were triangulated to anchor capacity forecasts.
Historical commissioning timelines were cross-referenced against expert panel assessments of liquefaction technology maturation and yard slot availability constraints across the projection horizon. Segmentation dimensions modeled include containment technology type, vessel capacity tier, application mode, and end-user contracting structure, with regional regulatory framework clusters treated as scenario inputs. CAGRs were derived from installed base replacement cycles and greenfield development sanctioning rates, incorporating IMO carbon intensity compliance deadlines and EU F-Gas Regulation phase-down schedules as demand-pull factors.
Several conditions sit outside the modeled scope, including unannounced liquefaction process breakthroughs, Korean yard labor disputes, and Mozambique security incidents affecting Rovuma Basin logistics. Forecasts reflect assumptions regarding membrane containment technology retention of newbuild share and sustained Thai-Vietnamese utility procurement for coal substitution. A model refresh is warranted upon material change in IMO enforcement timelines for carbon intensity indicators or Korean industrial policy affecting shipbuilding industry local content requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market