
 China Oil and Gas Upstream Market | 2026-2036
China Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
China Oil and Gas Upstream Market Outlook
Multi-source equipment procurement is pivoting as state-backed operators diversify beyond captive suppliers. PetroChina Company Ltd leverages its Daqing and Changqing field dominance to sustain plateau production through enhanced recovery pilots. CNOOC anchors deepwater exploration in the South China Sea with semisubmersible drilling programs. Sinopec competes aggressively in shale gas blocks through joint ventures with provincial energy groups.
China Oil and Gas Upstream encompasses crude petroleum and natural gas extraction from subsurface reservoirs, involving well drilling, completion, and primary production operations at depths ranging from 1,000 to 7,000 meters across onshore and offshore concessions. The sector feeds refineries, chemical plants, and city gas distribution networks with raw hydrocarbon feedstock. Conventional oil still occupies the largest revenue share among production type segments, though tight gas and unconventional oil are gaining drilling allocation under national energy security directives. Horizontal drilling and hydraulic fracturing technologies lead capital deployment in Sichuan and Xinjiang shale plays, while enhanced oil recovery methods dominate mature field rejuvenation budgets in the Songliao Basin.
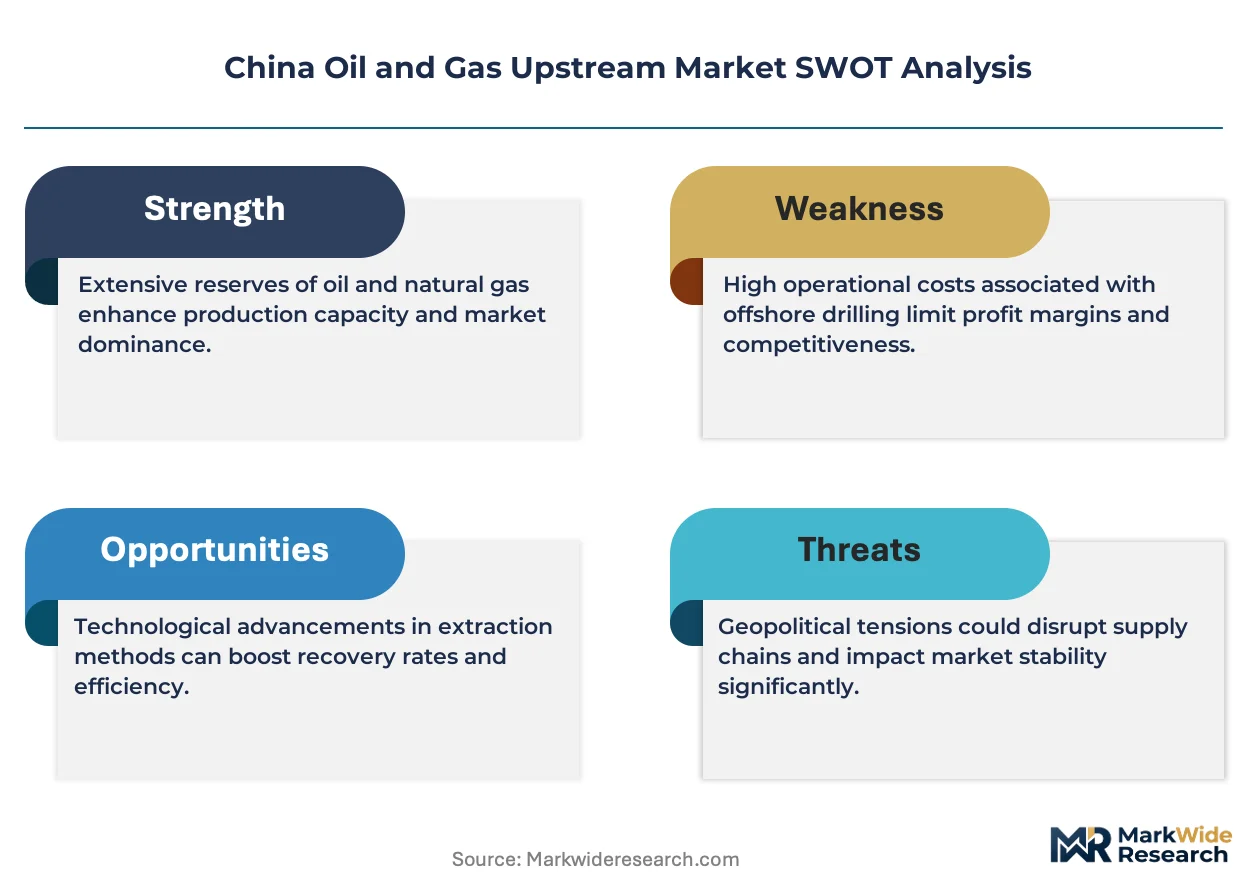
NMPA safety standards, MEE emission caps, and GB standards for wellhead equipment collectively raise compliance costs for exploration phase entrants. MIIT smart oilfield guidelines further mandate IoT sensor deployment and data interoperability across production phase assets. Stakeholders must weigh state-backed consolidation pressure against the technical autonomy required to operate marginal unconventional blocks profitably.
Market Dynamics
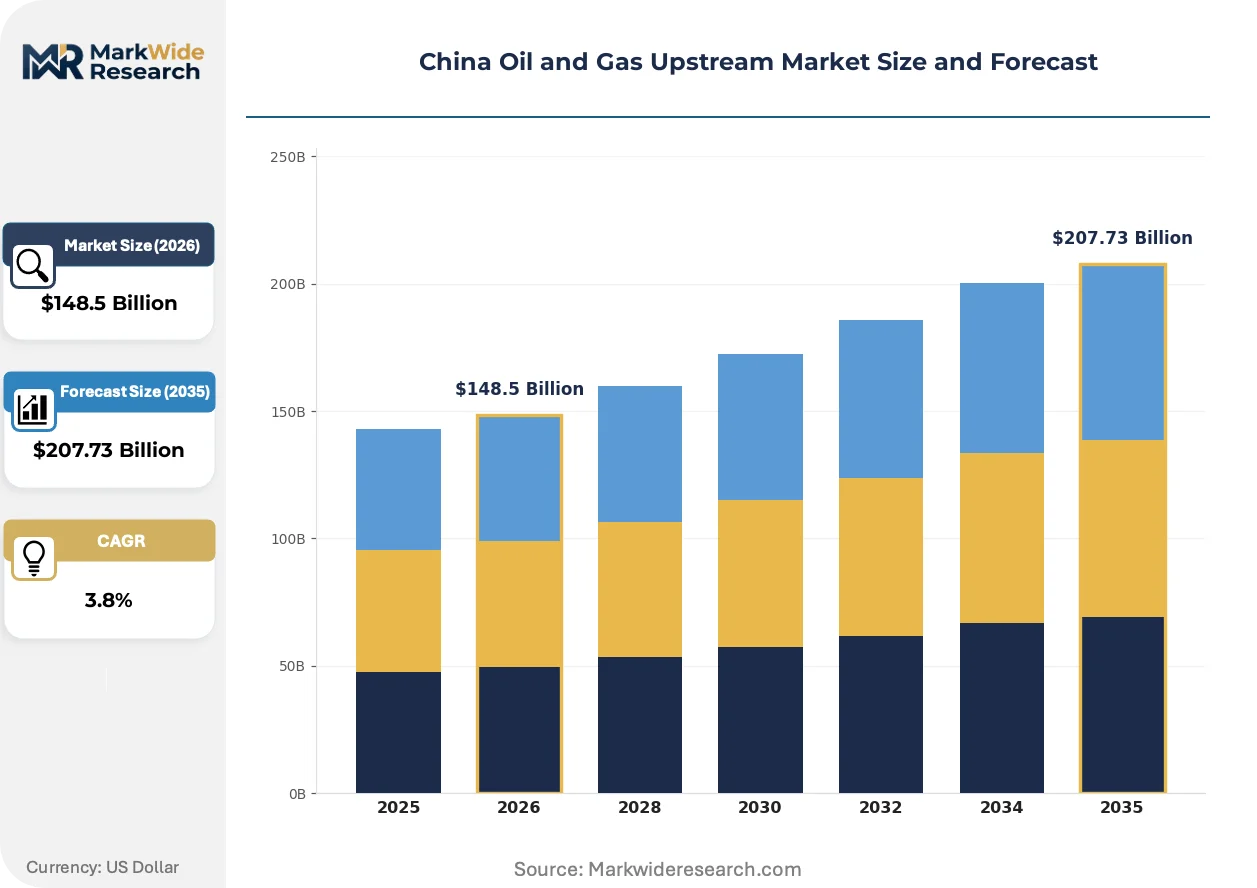
MIIT smart oilfield mandates and NMPA environmental compliance rules are compressing operational timelines while forcing capital redeployment toward digital infrastructure and emission controls across China's mature basins.
Growth Catalysts
- Dual carbon policy targets:National energy security directives prioritize domestic hydrocarbon extraction, accelerating drilling allocation in Sichuan shale plays and Tarim Basin tight gas formations.
- Horizontal drilling advances:Multi-stage hydraulic fracturing technologies unlock commercial flow rates from previously uneconomic reservoirs in Xinjiang and Ordos Basin blocks.
- Petrochemical feedstock pull:Sinopec's downstream complexes expand cracker capacity, creating captive demand for associated gas and light crude fractions from upstream affiliates.
Market Restraints
- Capital intensity barriers:Deepwater semisubmersible programs in the South China Sea require billion-yuan commitments before first oil, freezing out non-state entrants.
- Supply concentration risk:State-backed oilfield service triopolies control premium rig availability, creating queue bottlenecks during exploration campaign windows.
- Substitution acceleration:Grid-scale solar and offshore wind installations in coastal provinces erode long-term city gas demand growth projections.
Strategic Opportunities
- Enhanced recovery expansion:Chemical flooding and CO2 injection pilots in Daqing's mature zones offer low-decline production extensions with existing infrastructure leverage.
- Digital twin deployment:MIIT-mandated IoT sensor networks enable predictive maintenance contracts and real-time reservoir optimization services.
- Provincial joint venture structures:Shale gas blocks in Guizhou and Yunnan invite private capital participation through production-sharing frameworks with local energy groups.
Industry Challenges
- Geosteering expertise scarcity:Horizontal well placement in thin-bed unconventional targets demands specialized directional drilling crews that outstrip current training pipeline output.
- Legacy system integration friction:Smart oilfield data platforms must interface with decades-old SCADA architectures in Songliao Basin fields, delaying real-time analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Oil and Gas Upstream Market |
| Market Size in 2026 | $148.5 Billion |
| Market Size in 2035 | $207.73 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Type: Conventional Oil, Unconventional Oil, Natural Gas, Tight Gas Technology: Vertical Drilling, Horizontal Drilling, Hydraulic Fracturing, Enhanced Oil Recovery End User: Exploration Companies, Production Firms, Service Providers, Government Agencies Investment Stage: Exploration Phase, Development Phase, Production Phase, Decommissioning |
| Companies Covered | PetroChina Company Ltd, Sinochem Holdings, China National Petroleum Corporation (CNPC), Gazprom PJSC, ENN Energy Holdings, China Petroleum & Chemical Corporation (Sinopec), PipeChina, Huajin Aramco Petrochemical Company (HAPCO), China National Offshore Oil Corporation (CNOOC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Oil and Gas Upstream Market Strategic Shifts
Digital infrastructure deployment and extraction technology maturation are compressing development cycles while fragmenting traditional supply relationships across China's upstream sector.
Edge computing architectures for wellhead data processing are decentralizing decision authority from centralized command centers to field operations teams. PetroChina and CNOOC pilot installations in Changqing and Bohai Bay fields demonstrate sub-second latency for choke optimization. This topology shift is decentralizing procurement power toward regional asset managers who specify sensor vendors directly.
NMPA safety standards and MEE emission caps tighten concurrently, forcing simultaneous well integrity upgrades and flare gas recovery installations. Operators face overlapping compliance windows with divergent technical specifications. Unconventional shale blocks in Sichuan absorb the steepest cost impacts as greenfield developments must satisfy both regimes from spud date.
City gas distributors now specify calorific value and sulfur content thresholds in term supply contracts, transferring quality risk upstream. This specification tightening favors integrated operators with in-house processing capacity over pure exploration boutiques. The preference shift is most visible in coastal LNG receiving terminal offtake negotiations where end-user quality audits have become standard.
China Oil and Gas Upstream Market Segmentation
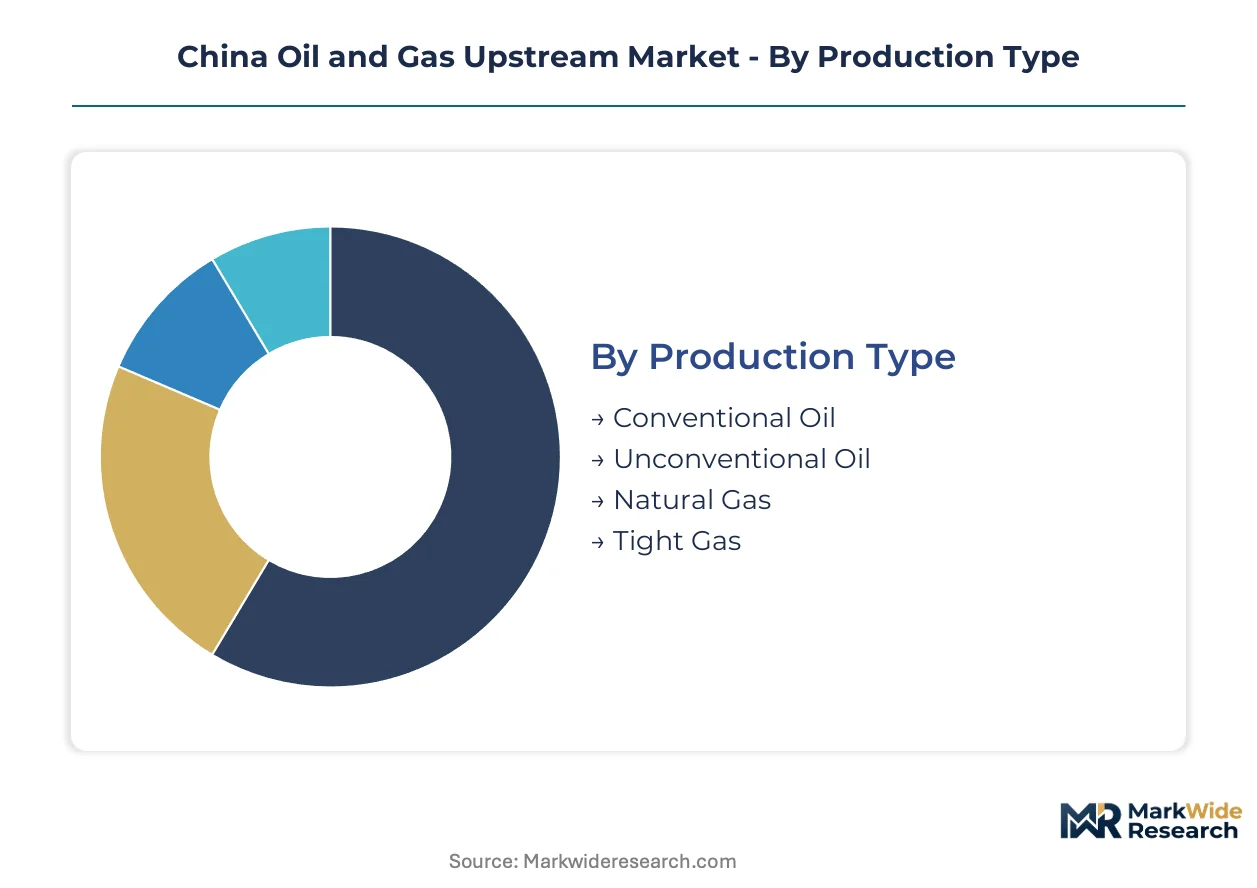
China's upstream hydrocarbon extraction requires precise segmentation alignment with NMPA safety tiers and MIIT digital mandates. Each category maps directly to capital allocation patterns across state-backed operators and provincial joint venture structures.
Production Type:
Standardization dominates conventional extraction while unconventional reservoirs demand bespoke completion designs calibrated to formation-specific geomechanics.
- Conventional Oil:Primary production from sandstone and carbonate reservoirs in Daqing and Changqing fields leverages existing gathering infrastructure. Sinopec's downstream crackers absorb the bulk of light crude fractions under term supply agreements.
- Unconventional Oil:Tight oil formations in Ordos Basin require multi-stage hydraulic fracturing with customized proppant loading schedules. Xinjiang's Junggar Basin absorbs the steepest drilling allocation growth under national energy security directives.
- Natural Gas:Associated gas from Tarim Basin condensate fields feeds West-East pipeline corridors.
- Tight Gas:Low-permeability sandstone targets in Sichuan Basin demand extended-reach horizontal laterals.
Leading the category by volume: Conventional Oil. Expanding most quickly: Unconventional Oil.
Technology:
Cost tiers separate legacy vertical programs from capital-intensive enhanced recovery pilots requiring chemical injection infrastructure.
- Vertical Drilling:Straight-hole completions in mature Songliao Basin fields exploit known reservoir architecture with minimal geosteering risk. Daqing's peripheral blocks sustain baseline production through infill vertical programs.
- Horizontal Drilling:Extended-reach laterals in Sichuan shale plays intersect multiple fracture stages. Changqing's tight gas blocks deploy 2,000-meter laterals to maximize reservoir contact per wellbore.
- Hydraulic Fracturing:Slickwater and hybrid fluid systems dominate Sichuan Basin shale completion designs.
- Enhanced Oil Recovery:CO2 flooding pilots in Daqing's mature zones leverage existing pipeline networks for carbon sequestration credits.
Dominant by deployment frequency: Vertical Drilling. Climbing the fastest: Horizontal Drilling.
End User:
Customer type fragmentation splits procurement authority between centralized state operators and decentralized provincial energy groups.
- Exploration Companies:Seismic survey contractors and wildcat drilling specialists operate under NMPA exploration licenses with 3-year evaluation windows. Bohai Bay Basin deepwater blocks attract specialized offshore exploration consortia.
- Production Firms:Field operating companies manage wellhead automation and artificial lift systems across Changqing's 50,000-plus well inventory. PetroChina's regional subsidiaries control the bulk of onshore production allocation decisions.
- Service Providers:Directional drilling and logging contractors queue for rig availability through state-backed oilfield service triopolies.
- Government Agencies:Provincial energy bureaus in Guizhou and Yunnan regulate shale block licensing through production-sharing frameworks.
Highest procurement volume: Production Firms. Gaining contract share fastest: Service Providers.
Investment Stage:
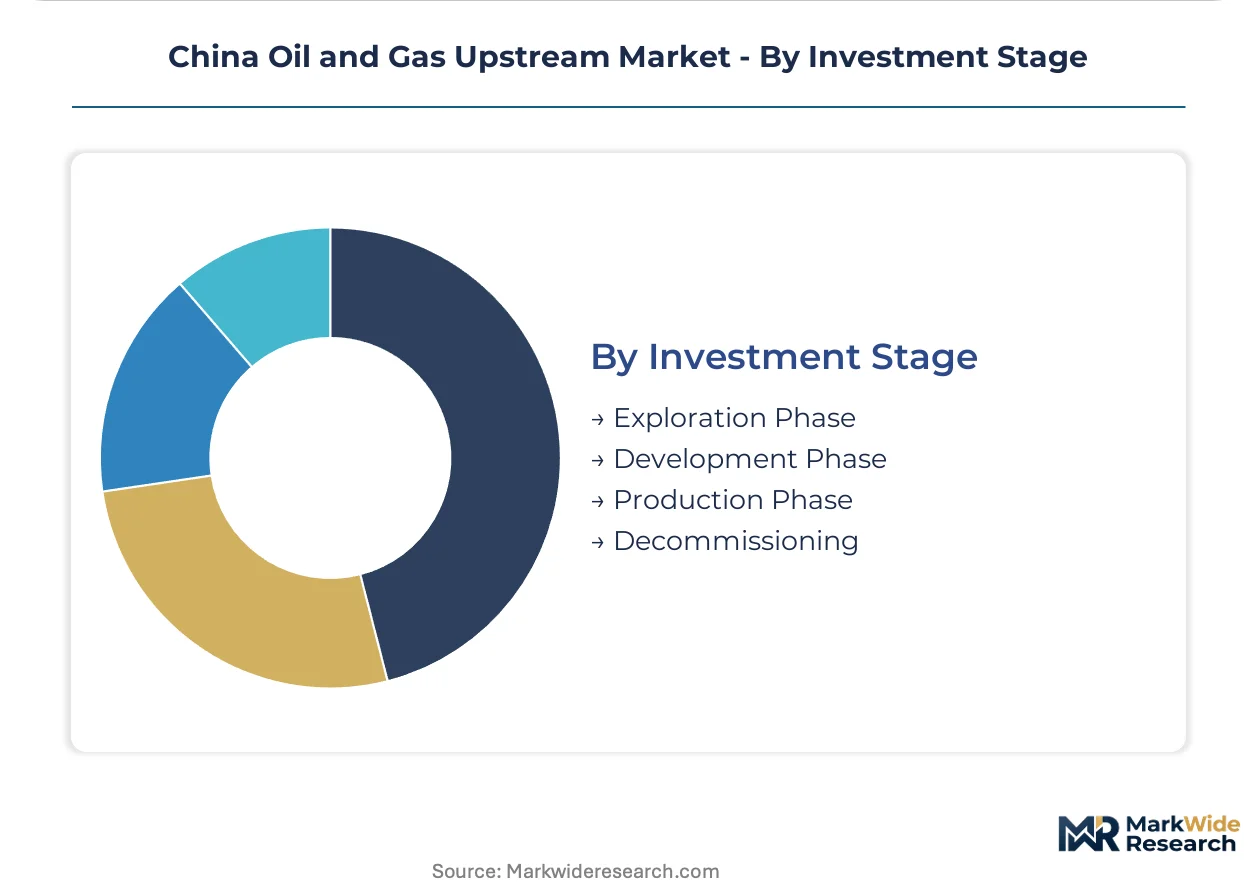
Maturity gradients separate greenfield exploration commitments from brownfield production optimization with divergent risk-return profiles.
- Exploration Phase:Seismic acquisition and wildcat drilling absorb capital with 5-7 year timelines to reserve booking. Tarim Basin deep targets require billion-yuan commitments before commercial flow confirmation.
- Development Phase:Field appraisal and facility construction bridge exploration to production in South China Sea deepwater blocks. CNOOC's semisubmersible programs concentrate capital deployment in this window.
- Production Phase:Operating expenditure dominance characterizes mature Daqing fields with artificial lift and workover programs.
- Decommissioning:Well plugging and platform removal obligations escalate in aging Bohai Bay shallow water assets.
Largest capital deployment: Production Phase. Steepest expansion trajectory: Development Phase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bohai Bay Basin anchors China's upstream production geography, feeding refineries along the northern coast with heavy crude streams while shale gas development concentrates in Sichuan's mountainous terrain.
Sichuan-Chongqing
Shale gas demand from chemical crackers and city gas distributors accelerates drilling in the Fuling and Weiyuan blocks. MEE emission caps force simultaneous flare recovery and methane leak detection investments. Chengdu-based service clusters supply directional drilling crews for extended-reach laterals targeting Longmaxi formation pay zones.
Xinjiang
Tight oil extraction from the Junggar Basin absorbs capital under national energy security directives prioritizing import substitution. NMPA well integrity standards extend to high-pressure high-temperature formations in the Mahu sag. Korla and Karamay field camps host concentrated hydraulic fracturing fleets for multi-stage completion programs.
Shandong Peninsula
Petrochemical feedstock demand from Sinopec's Zibo and Qingdao downstream complexes pulls associated gas and light crude from nearby Bohai Bay platforms. MIIT smart oilfield mandates require IoT retrofitting of legacy Shengli field infrastructure. Dongying service bases coordinate offshore logistics for CNOOC's marginal field redevelopment campaigns.
Shaanxi-Gansu-Ningxia
Changqing's tight gas blocks sustain plateau output through infill drilling and enhanced recovery pilots targeting the Ordos Basin's low-permeability sands. GB standards for wellhead automation accelerate artificial lift upgrades across the 50,000-plus well inventory. Yulin and Jingbian logistics hubs concentrate proppant supply chains for fracturing operations.
Heilongjiang
Daqing's mature oilfields deploy CO2 flooding pilots to flatten decline curves while leveraging existing gathering infrastructure. Dual carbon policy frameworks incentivize carbon sequestration credits from enhanced recovery operations. Daqing city retains concentrated petroleum engineering expertise for chemical flooding design and implementation.
China Oil and Gas Upstream Market Competitive Environment
Backward integration into captive oilfield services dominates the current competitive landscape, with state-backed operators absorbing drilling and completion capabilities to secure queue priority during campaign windows. The market structure concentrates around three national oil companies controlling concession allocation and infrastructure access. Two strategic archetypes prevail: integrated upstream-downstream behemoths with dedicated service arms, and provincial joint venture vehicles pooling local capital with technical partners. Capacity expansion and strategic partnerships represent the dominant competitive moves, as operators secure rig availability through multi-year framework agreements.
Among Beijing-headquartered national champions, PetroChina Company Ltd exemplifies the integrated archetype with basin dominance in Daqing and Changqing. China Petroleum & Chemical Corporation (Sinopec) occupies a position bridging upstream extraction with downstream petrochemical demand pull. China National Offshore Oil Corporation (CNOOC) anchors the offshore specialist tier through South China Sea deepwater programs.
| Leading Market Players |
|---|
| PetroChina Company Ltd |
| Sinochem Holdings |
| China National Petroleum Corporation (CNPC) |
| Gazprom PJSC |
| ENN Energy Holdings |
| China Petroleum & Chemical Corporation (Sinopec) |
| PipeChina |
| Huajin Aramco Petrochemical Company (HAPCO) |
| China National Offshore Oil Corporation (CNOOC) |
| Others |
Value Chain & Pricing Dynamics
Multi-stage hydraulic fracturing adoption in Sichuan Basin shale plays simultaneously inflates completion service costs and consolidates procurement power around state-backed oilfield service triopolies. NMPA well integrity mandates and MIIT digital oilfield requirements layer concurrent compliance investments onto drilling budgets, compressing margins for non-integrated operators while captive service arms capture premium pricing.
Pricing Analysis
Service bundling separates turnkey drilling contracts with embedded warranty coverage from unbundled day-rate rig arrangements. Three-tier pricing structure across premium, standard, and economy levels differentiates PetroChina's integrated service packages from provincial joint venture spot purchases and speculative wildcat programs. Cost compression in standard-tier hydraulic fracturing fleets is intensifying because of proppant oversupply in Xinjiang logistics corridors. Provincial energy groups exhibit highest price sensitivity due to capital constraints, while CNOOC deepwater programs demonstrate lowest sensitivity given billion-yuan pre-commitment structures.
Supply Chain Analysis
Dual-sourcing requirements for critical wellhead equipment mandate simultaneous qualification of domestic GB-standard manufacturers and international API-certified suppliers. Equipment procurement draws from China, USA, and Germany for high-pressure blowout preventers, while proppant supply rests on Xinjiang ceramic capacity and Guizhou sand deposits. Single-source vulnerability concentrates in subsea tree assemblies for South China Sea deepwater blocks. Distribution runs through Sinopec's captive logistics networks for integrated operators and provincial energy bureau tender platforms for joint venture structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horizontal drilling and geosteering automation are displacing legacy vertical programs across China's mature basins, creating capability gaps that reshape competitive entry barriers.
For Market Incumbents: Extend CO2 flooding pilot scale-up in Daqing's mature zones to capture carbon sequestration credits under dual carbon frameworks. Deepen backward integration into directional drilling crew training pipelines to offset geosteering expertise scarcity threatening campaign timelines.
For New Entrants and Emerging Players: The price-point gap between premium integrated service packages and economy-tier provincial joint ventures opens white-space targeting in Guizhou and Yunnan shale blocks. Production-sharing frameworks with local energy groups offer the most penetrable entry path. Lead with digital twin deployment for real-time reservoir optimization as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Exit pathways concentrate in state-backed consolidation of provincial joint venture stakes. Long-term viability hinges on unconventional extraction technology autonomy rather than conventional reserve access. Acquisition target archetype: directional drilling specialists with Sichuan Basin track records. Watch MIIT smart oilfield mandate enforcement timing as inflection indicator for digital infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Scale-Up | CO2 flooding pilots in Daqing leverage existing pipeline networks for dual carbon compliance. |
| Digital Twin Deployment | MIIT-mandated IoT sensor networks enable predictive maintenance contracts across Changqing fields. |
| Provincial Joint Venture Formation | Guizhou and Yunnan production-sharing frameworks pool local capital with technical partners. |
| Deepwater Capacity Buildout | CNOOC semisubmersible programs anchor South China Sea exploration with billion-yuan commitments. |
| Captive Service Arm Integration | State-backed operators absorb drilling capabilities to secure queue priority during campaign windows. |
Study Parameters
Regulatory filings from NMPA, MIIT, and MEE formed the secondary backbone for compliance cost modeling, supplemented by customs data for equipment import flows and provincial energy bureau licensing records. Primary interviews with drilling contractors, reservoir engineers, and procurement leads at state-backed operators validated cost assumptions and technology adoption timelines. Bottom-up well economics and top-down basin production aggregates were triangulated against concession-level disclosure patterns.
Historical trendline analysis across conventional decline curves and unconventional ramp-up profiles established baseline trajectories for the projection horizon. Segmentation dimensions modeled include production type, technology tier, end-user category, and investment stage maturity. CAGRs were derived from elasticity-adjusted demand functions incorporating petrochemical feedstock pull and city gas distribution specifications. Forecast inputs integrated NMPA safety standard implementation schedules and MIIT digital oilfield deployment targets.
Inputs from state-owned enterprise disclosure filings were available through the study window; gaps in provincial joint venture financial transparency introduce uncertainty bands around private capital participation rates. Forecasts reflect documented assumptions regarding dual carbon policy continuity and shale gas well productivity trends. Deviation in MEE emission cap enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market