
 North America Floating Offshore Wind Power Market | 2026-2036
North America Floating Offshore Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
North America Floating Offshore Wind Power Market Insights
Utility procurement is hardening as the dominant demand channel for floating offshore installations. Principle Power leverages its WindFloat platform architecture to anchor early commercial deployments in deep-water zones. Ørsted A/S sustains competitive positioning through its cross-Atlantic project development expertise. Siemens Gamesa Renewable Energy SA specializes in turbine scaling for harsh marine environments, extending its technology leadership in the segment.
Floating offshore wind power denotes electricity generation from turbines mounted on buoyant substructures anchored to seabed mooring systems, typically deployed in water depths exceeding sixty meters where fixed-bottom foundations prove economically unviable. Semisubmersible platforms dominate current engineering preferences due to their stability characteristics and established portside assembly workflows. Among capacity tiers, above-15 MW turbines command concentrated R&D investment as OEMs chase economies of scale. The deployment model segment shows floating installation as the core revenue pool, though onshore support infrastructure captures substantial ancillary value through specialized vessel and port requirements.
The US Bureau of Ocean Energy Management governs lease auctions and environmental review timelines, directly shaping project cadence and developer access to Atlantic and Pacific sites. The Inflation Reduction Act's investment and production tax credits reduce levelized cost thresholds, accelerating utility offtake commitments. Maine's state-level floating wind research program and California's offshore planning zones illustrate how sub-national policy layers interact with federal frameworks. Stakeholders must monitor Bureau of Ocean Energy Management lease schedule density and port infrastructure readiness as the decisive variables for project bankability.
Market Dynamics
The Inflation Reduction Act's offshore wind tax credits are compressing project development timelines and redirecting capital toward deep-water zones previously deemed uneconomical. This fiscal intervention is restructuring developer priorities across the Atlantic and Pacific coastlines.
Growth Catalysts
- IRA Production Tax Credits:The Inflation Reduction Act's enhanced offshore wind credits reduce levelized cost of energy thresholds, accelerating utility offtake commitments for floating projects in federal waters.
- California Deep-Water Zones:State-level offshore planning areas beyond sixty-meter depths create dedicated procurement pipelines where fixed-bottom foundations prove technically unviable.
- Semisubmersible Platform Maturation:Established portside assembly workflows for WindFloat-type architectures reduce deployment risk and attract infrastructure capital.
Market Restraints
- Specialized Vessel Scarcity:Heavy-lift installation ships capable of handling fifteen-megawatt-plus turbines in deep-water conditions concentrate among European and Asian yards.
- Mooring System Steel Costs:Anchor chain and synthetic rope input volatility directly impacts project capital intensity given thousand-meter-plus line lengths per turbine.
- Bureau of Ocean Energy Management Lease Density:Federal auction scheduling constraints create developer queue bottlenecks and extend pre-construction timelines.
Strategic Opportunities
- Maine State Research Program:Dedicated floating wind innovation funding and test-site infrastructure position the Gulf of Maine for early commercial deployment.
- Port Infrastructure Retrofit:Underutilized deep-draft Atlantic and Pacific port facilities offer assembly and staging capacity with targeted capital investment.
- Grid Interconnection Upgrades:FERC-jurisdictional transmission buildouts along coastal load centers enable higher capacity-factor offtake from remote floating arrays.
Industry Challenges
- Marine Electrical Technician Shortage:Specialized offshore maintenance workforce development lags deployment schedules across US coastal states.
- Dynamic Cable Certification:Subsea power export cable testing protocols for floating platform motion environments extend equipment qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Floating Offshore Wind Power Market |
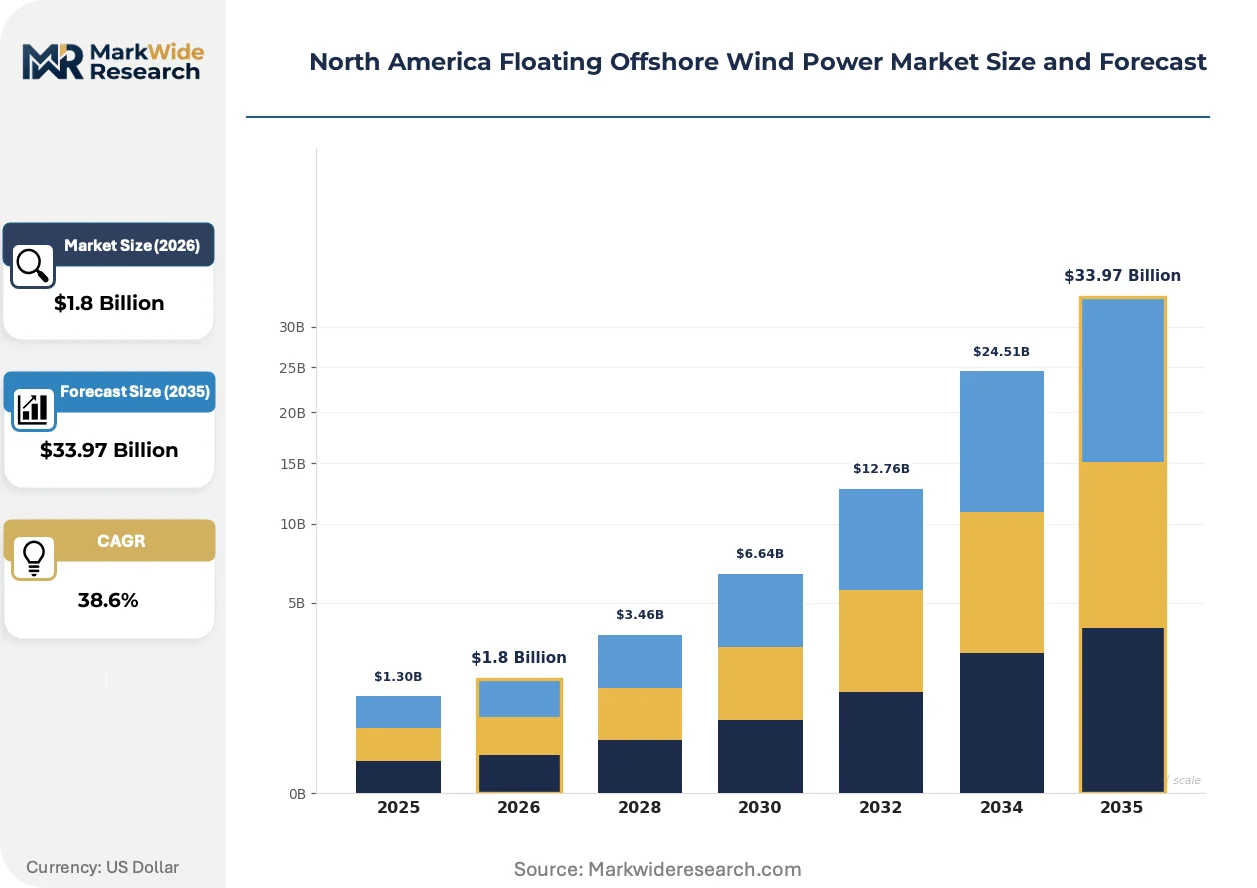
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.97 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Semisubmersible, Spar Buoy, Tension-leg Platform, Floating Wind Turbine End User: Utilities, Independent Power Producers, Offshore Developers, Renewable Energy Companies Deployment Model: Onshore Support, Floating Installation, Hybrid Approach, Remote Monitoring Capacity: 5 MW, 10 MW, 15 MW, Above 15 MW |
| Companies Covered | Vestas Wind Systems A/S, General Electric Company, Siemens Gamesa Renewable Energy SA, Doosan Heavy Industries & Construction, RWE Renewables GmbH, Ørsted A/S, Shell plc, TotalEnergies SE, Principle Power, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Floating Offshore Wind Power Market Trends and Innovations
Technology maturation and policy calibration are converging to unlock commercial-scale floating deployment. Three distinct vectors are compressing cost curves and reshaping competitive positioning in deep-water wind development.
Semisubmersible platform architecture is modularizing across the supply chain, enabling standardized hull fabrication at existing shipyards rather than purpose-built facilities. Tier-one developers are adopting this approach for Pacific Coast projects, reducing capital risk and compressing construction schedules. The technology is modularizing project execution into discrete, replicable work packages that attract broader contractor participation.
The Inflation Reduction Act's domestic content bonus credits are restructuring component sourcing requirements for federal lease holders. Manufacturers must reconfigure supply chains to capture full incentive value, with turbine assembly and steel fabrication facing the steepest compliance ramps. California and Atlantic Coast procurement pipelines are most exposed to these sourcing mandates, driving joint venture formation between US fabricators and European technology licensors.
Utility direct procurement of floating capacity is displacing traditional developer merchant-risk models as offtake structures mature. Pacific Coast utilities with renewable portfolio standard obligations are signing long-term power purchase agreements that transfer construction risk to project sponsors. This pattern concentrates most visibly in California, where load-serving entities face 2045 decarbonization deadlines that fixed-bottom Atlantic projects cannot satisfy.
North America Floating Offshore Wind Power Market Segmentation
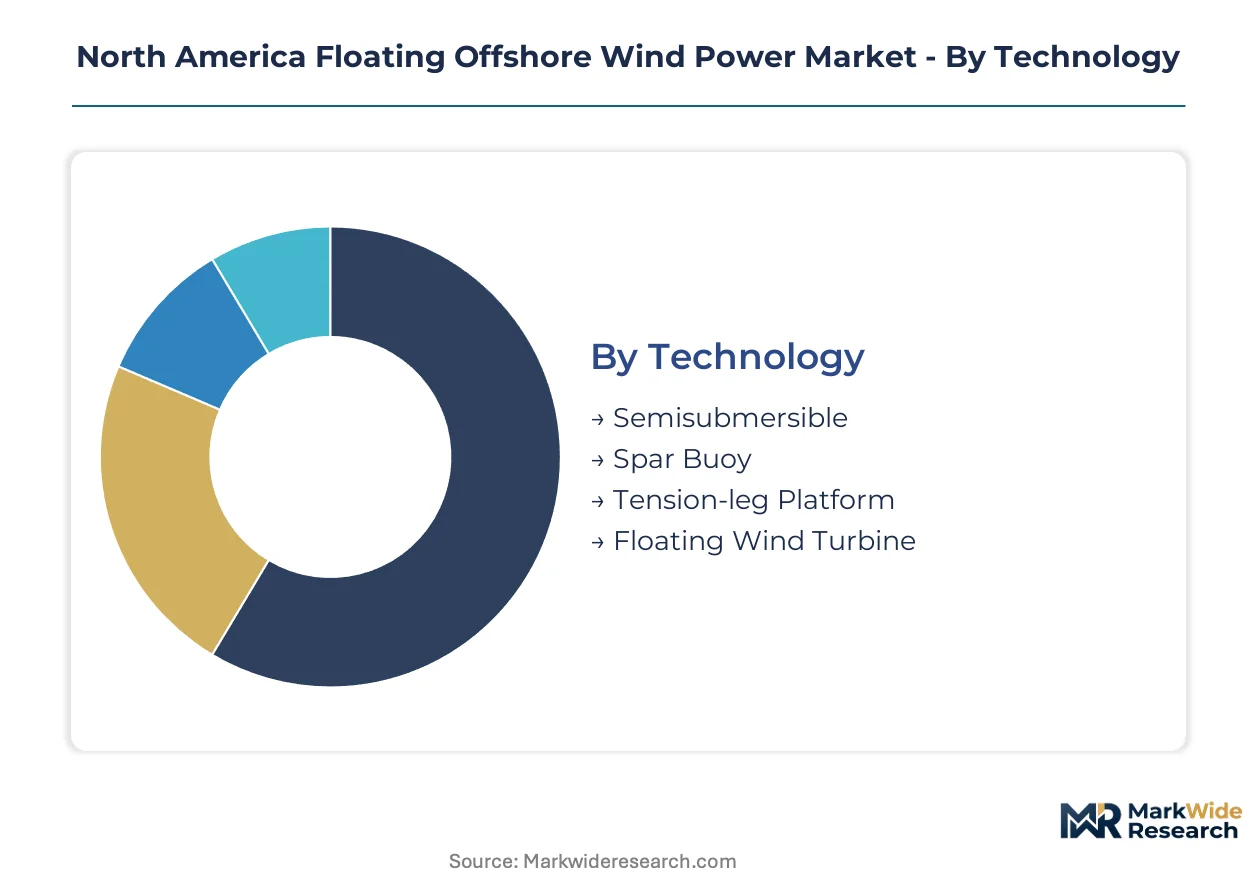
Segmentation in floating offshore wind reveals how certification pathways, procurement scale, and water depth constraints distribute value across technology tiers and customer types. Understanding these partitions exposes where capital concentrates and which regulatory approvals gate market entry.
Technology:
BOEM lease holders face divergent certification burdens by platform type, with ABS and DNV class society approvals required for hull structures while dynamic positioning systems trigger Coast Guard inspection protocols.
- Semisubmersible:Multi-column hull designs with distributed buoyancy enable portside turbine integration and wet-tow deployment. California utilities favor this architecture for Pacific Coast projects where assembly infrastructure remains limited and wave heights demand motion stability.
- Spar Buoy:Single deep-draft cylinder achieves stability through ballast-based center-of-gravity lowering. Gulf of Maine deployments concentrate here due to narrower seasonal weather windows that favor simpler mooring configurations and reduced station-keeping complexity.
- Tension-leg Platform:Vertical mooring tethers eliminate heave motion for turbine efficiency gains. Requires specialized tendon fabrication facilities and geotechnical verification of seabed anchor capacity.
- Floating Wind Turbine:Integrated turbine-platform systems designed for specific wind regimes and dynamic response characteristics. OEMs pursue integrated certification to streamline project delivery timelines.
Leading the category by volume: Semisubmersible. Expanding most quickly: Spar Buoy.
End User:
Procurement scale and offtake duration separate customer tiers, with regulated utilities commanding longest contract tenors and highest credit ratings.
- Utilities:Vertically integrated load-serving entities with renewable portfolio standard obligations drive capacity contracting. Pacific Coast utilities sign twenty-year power purchase agreements that absorb construction risk and establish revenue certainty for project finance.
- Independent Power Producers:Merchant developers without captive demand rely on bilateral contracts and wholesale market exposure. Merchant offtake concentrates in Atlantic Coast lease areas where grid interconnection timelines remain uncertain.
- Offshore Developers:Specialized project sponsors holding federal lease rights through BOEM competitive auctions. Development expertise spans environmental permitting, marine spatial planning, and community engagement.
- Renewable Energy Companies:Diversified clean energy investors allocating capital across technology verticals. Portfolio approach spreads development risk across multiple offshore wind sites and construction phases.
Highest procurement volume: Utilities. Steepest expansion trajectory: Independent Power Producers.
Deployment Model:
Execution risk distributes unevenly across installation approaches, with marine operations carrying highest insurance premiums and weather contingency exposure.
- Onshore Support:Port-based assembly, turbine integration, and logistics staging reduce offshore work duration. California and Maine port authorities compete for this revenue stream through infrastructure investment and dredging commitments.
- Floating Installation:Offshore turbine mounting and platform commissioning at final mooring location. Specialized heavy-lift vessel scarcity elevates day rates and compresses installation seasons.
- Hybrid Approach:Partial assembly at secondary ports with final integration at deep-water sites. Balances infrastructure requirements against marine operation complexity.
- Remote Monitoring:Sensor-based condition monitoring and predictive maintenance systems reduce crew transfer frequency. Digital infrastructure investments concentrate among utility-scale operators with large fleet exposure.
Dominant revenue pool: Floating Installation. Gaining share fastest: Remote Monitoring.
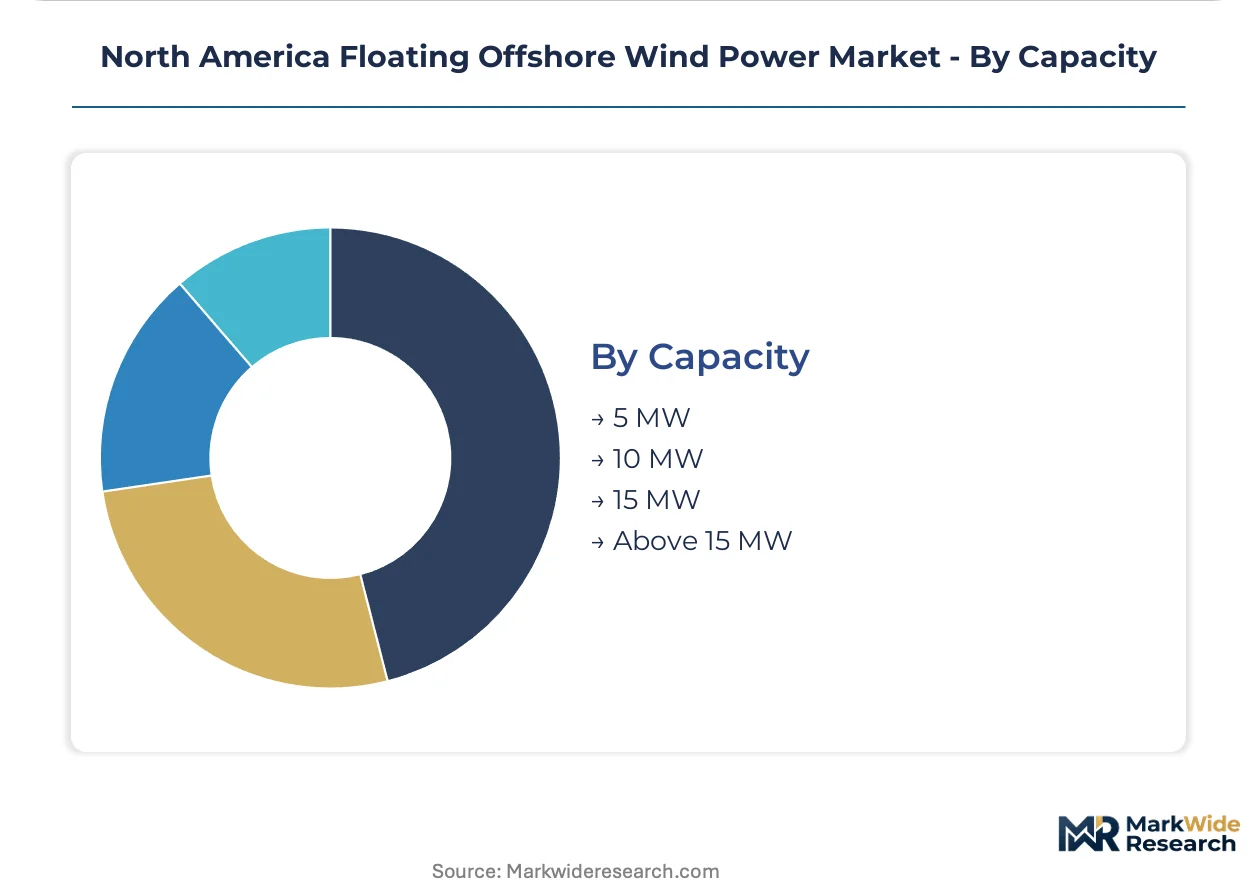
Capacity:
Turbine scale directly determines foundation sizing, mooring line count, and installation vessel specifications.
- 5 MW:Early commercial demonstration scale with established supply chains. Limited new procurement as economies of scale favor larger units.
- 10 MW:Transitional capacity tier bridging demonstration and utility-scale deployment. Maine research program utilizes this scale for technology validation.
- 15 MW:Current industry standard for commercial floating projects. OEMs optimize nacelle designs for semisubmersible motion response at this rating.
- Above 15 MW:Next-generation turbines targeting capital cost reduction through swept area expansion. California procurement pipelines specify these units for projects coming online in the next decade.
Leading by contracted volume: 15 MW. Climbing the fastest: Above 15 MW.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's offshore wind tax credits concentrate floating project development along coastal zones where water depths exceed sixty meters, with federal lease auctions and state-level research programs creating distinct regional pipelines across North American waters.
United States — California
Pacific Coast utilities with renewable portfolio standard obligations drive procurement of above-15 MW turbines for deep-water arrays. The Bureau of Ocean Energy Management's California offshore planning zones enable lease structures where fixed-bottom foundations prove technically unviable. Port infrastructure investments at Humboldt Bay and the Port of Long Beach concentrate assembly and staging capacity for semisubmersible platform deployment.
United States — Maine
The Gulf of Maine's narrow seasonal weather windows favor spar buoy architectures with simpler mooring configurations. Maine's state-level floating wind research program funds technology validation at the 10 MW scale through dedicated test-site infrastructure. Coastal fabrication clusters around Portland and Searsport attract portside assembly workflows for early commercial deployment.
United States — Atlantic Coast
Mid-Atlantic and Northeast load-serving entities face grid interconnection timelines that extend pre-construction schedules for floating projects in federal waters. FERC-jurisdictional transmission buildouts along coastal load centers enable higher capacity-factor offtake from remote arrays. Specialized heavy-lift vessel scarcity from European and Asian yards elevates installation costs for Atlantic lease holders.
Canada
Atlantic Canada provinces evaluate floating foundation suitability for deep-water zones off Nova Scotia and Newfoundland where fixed-bottom economics fail. Provincial renewable energy procurement programs and federal marine spatial planning frameworks shape developer access to Pacific and Atlantic sites. Port infrastructure at Halifax and Saint John competes for turbine integration and logistics staging revenue.
North America Floating Offshore Wind Power Market Competitive Landscape
Top-tier vendors anchor technology licensing and platform architecture development, while project development specialists and integrated energy conglomerates populate the mid-tier. The competitive structure concentrates around three strategic archetypes: turbine OEMs scaling nacelle designs for harsh marine motion environments, platform technology licensors monetizing semisubmersible hull patents, and offshore wind developers holding federal lease rights through BOEM competitive auctions. Dominant competitive moves include joint venture formation between US fabricators and European technology licensors to satisfy domestic content requirements, and strategic partnerships securing port infrastructure access for assembly and staging operations.
Among European-headquartered developers, Ørsted A/S and RWE Renewables GmbH occupy positions exemplifying cross-Atlantic project development expertise, while Principle Power represents the platform technology licensor archetype with its WindFloat architecture. These entities sit within competitive tiers where federal lease holding and technology IP ownership determine market access rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| General Electric Company |
| Siemens Gamesa Renewable Energy SA |
| Doosan Heavy Industries & Construction |
| RWE Renewables GmbH |
| Ørsted A/S |
| Shell plc |
| TotalEnergies SE |
| Principle Power |
| Others |
Pricing and Supply Chain Analysis
Anchor chain and synthetic rope steel costs flow from European and Asian specialty mills through mooring system fabricators to project developers, with thousand-meter-plus line lengths per turbine amplifying any input volatility into capital intensity tiers that separate early-mover utilities from price-constrained merchant developers.
Pricing Analysis
Short-lead-time premiums for heavy-lift installation vessels command substantial day-rate spreads over contracted forward slots, compressing project economics for developers without secured vessel access. Three-tier pricing structure across premium, standard, and economy levels separates BOEM lease holders with locked-in offtake agreements from merchant developers exposed to wholesale market volatility, with after-sales service bundling for dynamic cable maintenance adding differentiation. Pricing pressure stems from specialized vessel scarcity concentrated among European and Asian yards, forcing Atlantic Coast developers toward longer construction windows. Independent power producers exhibit highest price sensitivity due to merchant-risk exposure, while vertically integrated utilities absorb cost premiums for schedule certainty.
Supply Chain Analysis
Mooring system steel supply rests on Norwegian, Korean, and Japanese specialty producers with limited surge capacity for North American project ramps. Turbine nacelles, semisubmersible hull steel, and dynamic export cables constitute the critical component triad, with each drawing from distinct geographic fabrication clusters. Single-source vulnerability concentrates in heavy-lift vessel availability, where European yard backlogs extend delivery timelines for Pacific and Atlantic developers alike. Distribution runs through port-based assembly and staging nodes at Humboldt Bay, Port of Long Beach, and Searsport, with final integration occurring at federal lease sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where BOEM lease queue density and port infrastructure access will force capital-constrained developers toward joint venture or exit.
For Market Incumbents: Deepen backward integration into mooring system fabrication and turbine assembly to capture IRA domestic content bonus credits, while securing exclusive port access agreements at Humboldt Bay and Searsport to block competitor staging capacity. The threat of European developer joint ventures with US fabricators demands rapid supply chain repositioning. Vertical control over heavy-lift vessel forward contracts represents the decisive lever for schedule certainty. For New Entrants and Emerging Players: Digital channel routes through remote monitoring and predictive maintenance platforms offer lower capital barriers than hardware development, with sensor-based condition monitoring representing the most penetrable white-space target among utility-scale operators with large fleet exposure. Target the aftermarket service tier where marine electrical technician scarcity creates immediate procurement gaps, and pursue OEM partnership structures rather than standalone platform development. For Investors and Strategic Acquirers: FERC-jurisdictional transmission interconnection approvals are the leading indicator that floating array bankability has crossed the threshold for institutional capital deployment. Over the coming decade, acquisition targets should concentrate on developers holding BOEM lease rights with secured offtake and permitted grid access, rather than pure technology licensors without project pipelines. The small set of triggers warranting ongoing watch includes Bureau of Ocean Energy Management auction schedule acceleration, Pacific Coast port dredging completions, and dynamic cable certification protocol finalization.| Strategic Initiative | Industry Significance |
|---|---|
| Port Infrastructure Lock-Up | Exclusive staging agreements at Humboldt Bay and Searsport block competitor assembly capacity for Pacific and Gulf of Maine deployments. |
| Domestic Content Compliance | IRA bonus credit capture requires restructured supply chains with US steel fabrication and turbine assembly partnerships. |
| Heavy-Lift Vessel Forward Contracts | Locked vessel schedules compress installation seasons and transfer weather risk from developers to marine contractors. |
| Transmission Interconnection Securement | FERC-jurisdictional queue positions determine revenue start dates and project finance closure timelines. |
| Dynamic Cable Certification Investment | Subsea power export testing protocol advancement accelerates equipment qualification for floating platform motion environments. |
Research Methodology
Multi-period observation of BOEM lease auction schedules, port infrastructure investment commitments, and utility offtake agreement signings anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA generation data, FERC interconnection filings, IEA offshore wind reports, and Bureau of Ocean Energy Management lease records. Bottom-up project pipeline aggregation and top-down regulatory impact assessment were triangulated to establish market sizing.
Input-output matrix framing connected turbine capacity tiers to platform architecture requirements, mooring system specifications, and installation vessel classes across the projection horizon. Segmentation dimensions modeled include technology type, end-user procurement scale, deployment model execution risk, and capacity rating. CAGRs were derived from utility renewable portfolio standard obligation trajectories and federal tax credit phase-down schedules, with project finance cost of capital and steel input price indices as floating offshore wind-specific forecast inputs.
The model holds under sustained IRA credit availability and BOEM auction cadence; deviation in FERC transmission approval timelines or European vessel yard strike activity would shift deployment schedules. Forecasts reflect documented assumptions regarding state-level procurement mandate durability and marine spatial planning finalization. A small set of named triggers warrants ongoing watch: Bureau of Ocean Energy Management lease schedule density, Pacific Coast port dredging completion dates, and dynamic cable certification protocol advancement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market