
 Oil Rig Market | 2026-2036
Oil Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Rig Market Insights
The gap between premium harsh-environment rigs and standard commodity units is shifting contract economics across the offshore drilling sector. Transocean Ltd anchors the premium tier through its fleet of ultra-deepwater drillships rated for 12,000-foot water depths. Valaris Ltd competes across both tiers, leveraging a mixed fleet strategy that spans benign and harsh-environment markets. Seadrill Ltd specializes in high-specification jack-ups for North Sea and Norwegian shelf operations.
An oil rig is a mobile or fixed marine structure equipped with a drilling derrick, power generation systems, and blowout preventers designed to bore exploratory or development wells in subsea geological formations, typically constructed from high-strength steel with dynamic positioning capabilities for water depths exceeding 3,000 meters. Jack-up rigs retain the largest installed base due to their cost efficiency in shallow-water developments, though margin pools have migrated toward ultra-deepwater drillships where dayrates command substantial premiums. The depth capability dimension reveals the steepest structural shift, as operators retire shallow-water fleets and redirect capital toward floating units rated for depths beyond 7,500 feet.
The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce structural and operational standards for rigs in federal waters, while the IMO's MARPOL Annex VI rules constrain emissions from offshore power generation. Brazil's national petroleum regulator ANP mandates local content requirements that shape rig procurement decisions for pre-salt field developments. Stakeholders must weigh fleet renewal timelines against evolving carbon accounting rules that will redefine asset valuations before the decade closes.
Market Dynamics
Dual-fuel propulsion architectures are forcing premature obsolescence across legacy diesel-heavy fleets as the IMO's carbon intensity indicators tighten enforcement timelines for offshore power generation.
Growth Catalysts
- Pre-salt basin expansion:Petrobras maintains aggressive drilling schedules in Brazil's offshore pre-salt formations, sustaining demand for ultra-deepwater drillships rated beyond 10,000-foot capabilities.
- MARPOL Annex VI enforcement:The IMO's strengthened carbon intensity regulations are accelerating rig owner investment in dual-fuel engines and battery-hybrid power systems to avoid operational penalties.
- Subsea tieback technology maturation:Operators deploy smaller, reusable wellhead systems that reduce development cycle times and improve economics in marginal deepwater fields.
Market Restraints
- High-grade steel supply concentration:Specialized high-strength steel plate for harsh-environment jack-up legs concentrates among a narrow supplier base in East Asia, creating input cost volatility and delivery risk.
- Dual-fuel retrofit capex burden:Converting existing drillships to methanol or LNG dual-fuel operation requires capital outlays that compress returns on aging assets nearing depreciation endpoints.
- Shallow-water fleet stranding:Jack-up rigs rated below 400-foot water depth face accelerating retirement as exploration budgets migrate to deepwater frontiers, eroding secondary market liquidity.
Strategic Opportunities
- West African frontier basins:Underexplored deepwater blocks offshore Senegal, Mauritania, and Côte d'Ivoire offer contract opportunities for high-specification drillships as licensing rounds advance.
- Offshore wind turbine installation:Jack-up rig owners repurpose existing hulls for offshore wind foundation work, accessing adjacent energy infrastructure demand with modified cantilever systems.
- EU Green Deal industrial funding:European offshore contractors access transition financing for zero-emission rig designs, accelerating hydrogen fuel cell and ammonia combustion pilot programs.
Industry Challenges
- Dynamic positioning officer scarcity:Specialized marine crew with DP-3 certification command premium wages, constraining fleet activation speed and inflating operating costs.
- Blowout preventer recertification bottlenecks:OEM service capacity limitations extend BOP stack inspection timelines, forcing rigs into unplanned downtime during contract gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Rig Market |
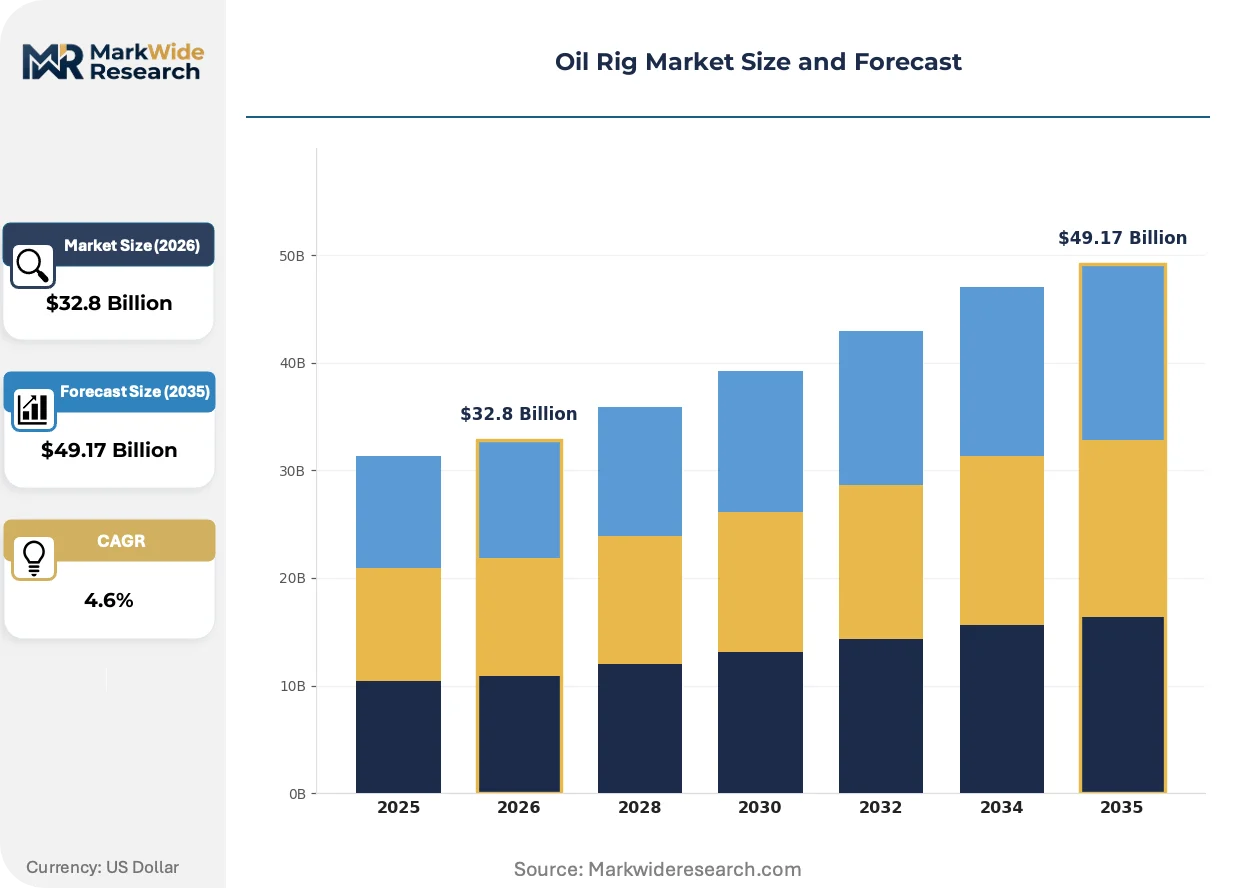
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Jack-up, Semi-submersible, Drillship, Floating Production Storage and Offloading End User: Offshore Operators, Oilfield Services, Government Agencies, Energy Companies Depth Capability: Shallow Water, Deep Water, Ultra Deep Water, Mid Water Service Type: Drilling, Maintenance, Inspection, Decommissioning |
| Companies Covered | China Oilfield Services Limited, Transocean Ltd, Valaris Ltd, Seadrill Ltd, Noble Corporation plc, Schlumberger NV, Saipem, Seatrium Limited, Nabors Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Rig Market Trends and Innovations
Digital twin implementations and autonomous drilling systems are compressing well construction timelines while regulatory pressure on emissions intensifies capital allocation toward next-generation hull designs.
Condition-based monitoring systems using fiber-optic sensing arrays are decentralizing maintenance scheduling across floating rig fleets. Transocean and Seadrill deploy these systems to shift from calendar-based overhauls to predictive interventions. This architecture reduces drydock frequency and extends operational availability in harsh North Sea and Norwegian shelf environments.
EPA enforcement of the Outer Continental Shelf Lands Act is tightening air quality standards for rigs operating in US federal waters. The agency's updated emissions monitoring requirements affect diesel-powered jack-ups most severely. Operators respond by accelerating dual-fuel engine orders and testing battery-peak-shaving configurations to limit generator runtime.
Charterers increasingly demand integrated drilling-services packages that bundle rig provision with managed-pressure drilling and completions expertise. This consolidation displaces traditional dayrate-only contracting in Brazil's pre-salt developments. Petrobras and international majors now source through single-point accountability structures that transfer more subsurface risk to drilling contractors.
Oil Rig Market Segmentation
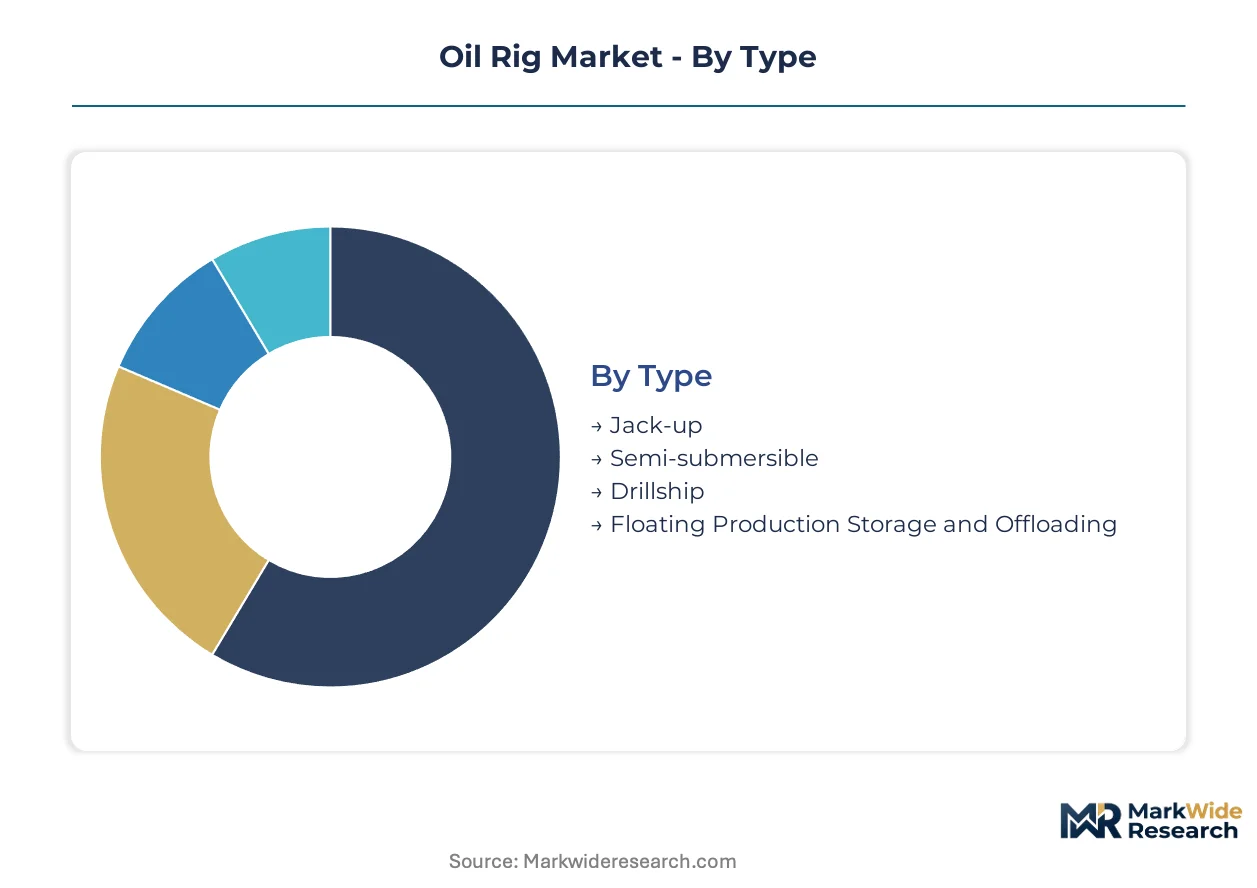
Segmentation in the oil rig market exposes how regulatory certification burdens, water depth economics, and service specialization stratify procurement decisions. Operators select rig types based on IMO emissions compliance requirements, ANP local content mandates in Brazil, and BSEE safety certifications for US federal waters.
Type:
Certification requirements diverge sharply across rig architectures, with dynamic positioning systems and blowout preventer configurations triggering distinct US Coast Guard and flag-state approval pathways.
- Jack-up:Self-elevating platforms with open-truss or columnar legs anchor in shallow-water developments through seabed penetration. Demand concentrates in the Middle East's Persian Gulf fields where Saudi Aramco and ADNOC maintain active shallow-water programs, though IMO carbon intensity rules now pressure these diesel-heavy fleets toward dual-fuel retrofits.
- Semi-submersible:Twin-hull floating platforms with pontoons and columns provide stability in harsh North Sea and Norwegian shelf environments through low center-of-gravity design. Petrobras and Equinor deploy these units in Brazil's pre-salt and Barents Sea frontiers where station-keeping demands exceed jack-up capabilities but drillship economics underperform.
- Drillship:Monohull vessels with dynamic positioning systems deliver maximum mobility and water depth capability for ultra-deepwater exploration.
- Floating Production Storage and Offloading:Integrated production, storage, and offloading units convert exploratory discoveries into producing assets without pipeline infrastructure.
Leading the category by volume: Jack-up. Growing fastest: Drillship.
End User:
Procurement authority and risk allocation patterns separate these customer types, with national oil companies wielding distinct local content leverage versus international oil majors.
- Offshore Operators:Integrated exploration and production companies that own development rights and charter rigs directly. Supermajors like Shell and BP in the US Gulf of Mexico and TotalEnergies in Angola drive demand for high-specification drillships through operated-asset strategies.
- Oilfield Services:Schlumberger, Halliburton, and Baker Hughes bundle rig provision with managed-pressure drilling and completions expertise, displacing dayrate-only contracting in Brazil's pre-salt developments where Petrobras demands single-point accountability.
- Government Agencies:State-owned petroleum regulators and national oil companies that rig procurement through sovereign wealth mechanisms.
- Energy Companies:Diversified utilities and independent power producers entering offshore exploration through farm-in arrangements.
Contract concentration: Offshore Operators. Procurement innovation: Oilfield Services.
Depth Capability:
Margin pools migrate decisively with water depth, as steel specifications, dynamic positioning redundancy, and blowout preventer ratings escalate certification complexity.
- Ultra Deep Water:Rigs rated beyond 7,500 feet access Brazil's pre-salt formations, Gulf of Mexico Lower Tertiary, and West African frontier basins. Transocean and Valaris command premium dayrates here as Petrobras, ExxonMobil, and BP compete for limited high-specification drillship availability.
- Deep Water:1,000 to 7,500-foot capability serves established basins in Angola, Nigeria, and Malaysia where development drilling sustains semi-submersible and mid-water drillship demand.
- Shallow Water:Jack-up rigs dominate shelf developments under 400 feet, though fleet retirement accelerates as exploration budgets migrate deeper.
- Mid Water:Transitional depths between 400 and 1,000 feet where older semi-submersibles compete with high-specification jack-ups.
Highest dayrate premiums: Ultra Deep Water. Steepest fleet decline: Shallow Water.
Service Type:
Revenue stability and contract duration vary across the well lifecycle, with decommissioning obligations creating counter-cyclical demand buffers.
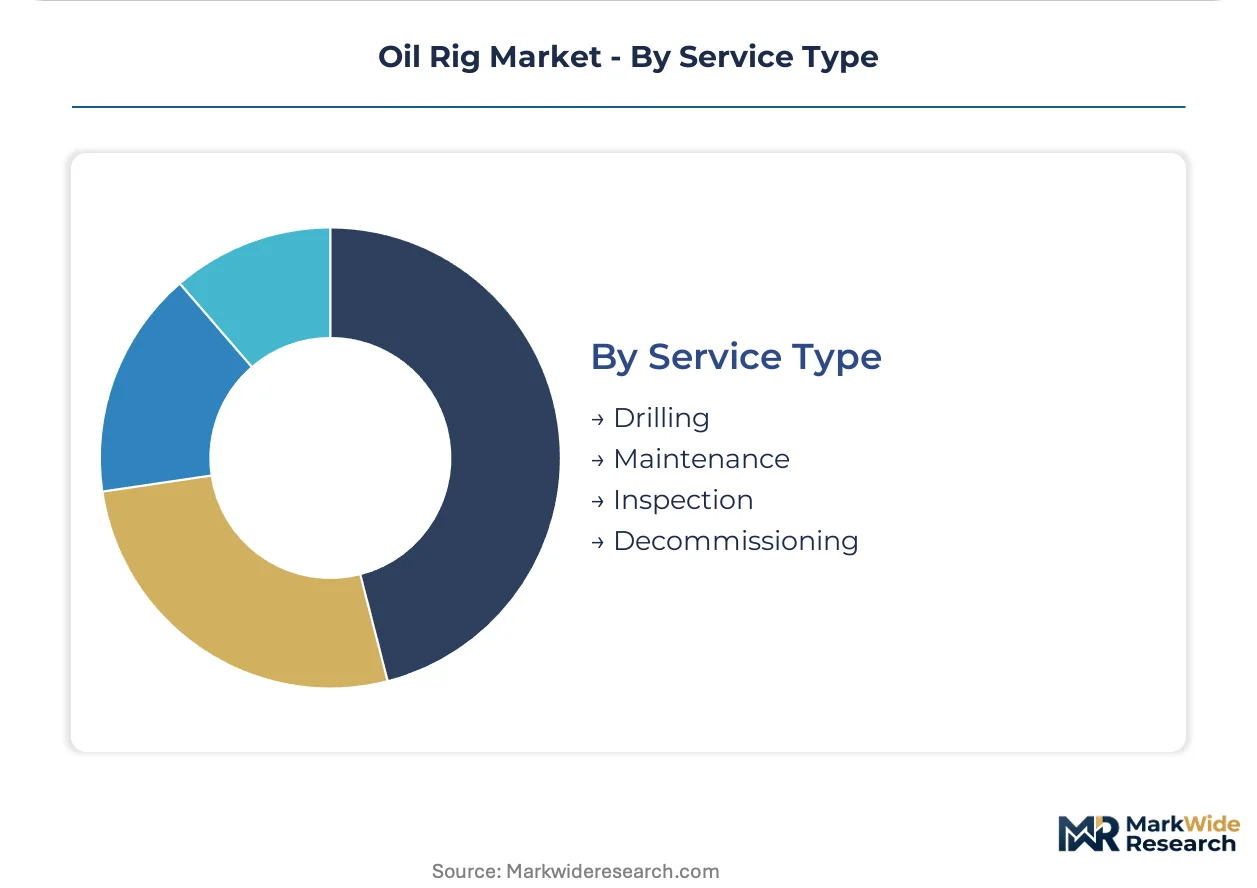
- Drilling:Exploratory and development well construction generates the largest revenue pool, with Brazil's pre-salt and Guyana-Suriname basin driving ultra-deepwater demand. Integrated drilling-services packages now bundle rig provision with managed-pressure drilling, transferring subsurface risk from operators to contractors.
- Maintenance:Well intervention and workover services sustain jack-up and platform rig utilization between drilling campaigns, particularly in the UK's mature North Sea fields where well integrity requirements intensify.
- Inspection:Regulatory-mandated structural surveys, blowout preventer recertification, and subsea equipment verification create specialized vessel demand.
- Decommissioning:Platform removal, well plugging, and site restoration obligations in the UK and US Gulf of Mexico repurpose jack-up rigs and heavy-lift vessels.
Revenue concentration: Drilling. Counter-cyclical buffer: Decommissioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the world's largest concentration of offshore drilling contractors, with the Gulf of Mexico serving as the primary testbed for ultra-deepwater drillship deployments. Singapore and South Korea host the dominant shipyard clusters fabricating high-specification hulls for international operators.
United States
The Gulf of Mexico Lower Tertiary and Permian Basin offshore extensions sustain demand for dynamically positioned drillships rated beyond 12,000 feet. The Bureau of Safety and Environmental Enforcement enforces blowout preventer certification standards that exceed IMO baselines, elevating compliance costs for non-US-flagged units. Houston's Energy Corridor houses Transocean and Valaris headquarters, with fabrication support from Port Fourchon supply bases.
Brazil
Petrobras maintains the world's most aggressive ultra-deepwater drilling schedule across the Santos and Campos basin pre-salt formations. ANP local content mandates require 55-65% Brazilian sourcing for rig construction and services, reshaping procurement patterns for international contractors. The Macaé logistics cluster in Rio de Janeiro state serves as the primary marshaling point for pre-salt operations.
Norway
Equinor and Aker BP drive harsh-environment semi-submersible demand in the Barents Sea and mature North Sea fields. The Norwegian Petroleum Directorate enforces CO2 intensity limits on offshore power generation that accelerate dual-fuel engine adoption ahead of IMO timelines. Stavanger and Bergen host specialized marine engineering clusters focused on Arctic-capable hull designs.
Singapore
Jurong Shipyard and Sembcorp Marine facilities construct 70% of global ultra-deepwater drillship hulls, with Seatrium Limited consolidating fabrication capacity. The Maritime and Port Authority of Singapore enforces emissions monitoring for vessels in territorial waters, pressuring yard customers toward battery-hybrid power architectures. Tuas industrial zone expansion targets zero-emission rig construction by 2030.
Saudi Arabia
Saudi Aramco's long-term drilling contracts sustain jack-up utilization in Persian Gulf shallow-water fields while expanding Red Sea frontier exploration. The Saudi Standards, Metrology and Quality Organization mandates equipment certification aligned with API specifications for all offshore installations. Dhahran's King Salman Energy Park anchors supply chain localization under Vision 2030 industrial targets.
Oil Rig Market Competitive Landscape
Capital-heavy rig owners compete with asset-light drilling management contractors across tiered service models. The market structure concentrates around five publicly traded fleet operators controlling 60% of ultra-deepwater drillship capacity, with remaining share fragmented across regional jack-up specialists and national oil company captive fleets. Three archetypes dominate: premium harsh-environment specialists, mixed-fleet diversified operators, and shallow-water jack-up focused contractors. Competitive moves center on fleet renewal through newbuild orders and M&A consolidation of distressed assets.
Among premium-tier harsh-environment specialists, Transocean Ltd and Seadrill Ltd exemplify the high-specification drillship and North Sea jack-up archetypes respectively. Valaris Ltd occupies a diversified position spanning both premium and standard fleet tiers. These three entities anchor the competitive structure through distinct water depth and environmental capability positioning.
| Leading Market Players |
|---|
| China Oilfield Services Limited |
| Transocean Ltd |
| Valaris Ltd |
| Seadrill Ltd |
| Noble Corporation plc |
| Schlumberger NV |
| Saipem |
| Seatrium Limited |
| Nabors Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Captive fabrication capacity at Singapore's Jurong Shipyard and South Korea's DSME anchors both supply security and pricing power for ultra-deepwater drillship owners. This vertical integration into hull construction insulates fleet operators from spot-market steel volatility while compressing delivery timelines for newbuild orders.
Pricing Analysis
Dayrate premiums tied to operational uptime and water depth capability anchor contract economics across the offshore drilling sector. Three-tier pricing structure across premium harsh-environment, standard mid-water, and economy shallow-water tiers separates Transocean's 12,000-foot drillships from commodity jack-ups. Pricing pressure stems from IMO carbon intensity penalties accelerating dual-fuel retrofit demands. National oil companies exhibit lowest price sensitivity due to local content mandates, while independent offshore operators negotiate hardest on standby rates.
Supply Chain Analysis
High-strength steel plate for jack-up legs rests on a concentrated supplier base spanning Japan, South Korea, and China. Specialized inputs include dynamic positioning systems from European marine automation houses, blowout preventer stacks from US OEMs, and dual-fuel engine packages from Finnish and German manufacturers. Single-source vulnerability concentrates in DP-3 certification training capacity for marine officers. Distribution runs through Houston's Energy Corridor procurement hubs and Singapore's Tuas logistics zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore drilling sector is consolidating around backward integration into specialized steel fabrication and forward integration into integrated drilling-services bundling. Players capturing both levers will define the next competitive frontier.
For Market Incumbents: Deploy dual-fuel engine pre-orders to lock yard slots before IMO enforcement tightens. Acquire distressed jack-up fleets at scrap-adjacent valuations for offshore wind conversion. Carbon intensity penalties from MARPOL Annex VI threaten diesel-heavy legacy units with premature obsolescence. For New Entrants and Emerging Players: Decommissioning contractors in the UK North Sea represent an underserved buyer archetype with counter-cyclical demand buffers. Target well plug-and-abandonment campaigns where supermajors seek single-point accountability for liability transfer. Partner with European fabrication yards accessing EU Green Deal transition financing for zero-emission hull pilots. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to national oil company captive fleets seeking operational control over pre-salt drilling programs. Five-to-ten year viability hinges on fleet age distribution and remaining drydock intervals. Watch ANP local content threshold adjustments as the inflection signal for Brazilian contract flow redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Renewal Through Newbuild Orders | Secures IMO-compliant dual-fuel capacity before carbon intensity penalties activate. |
| Backward Integration Into Steel Supply | Captive plate sourcing from Japanese mills insulates against East Asian supply bottlenecks. |
| Integrated Services Bundling | Combines rig provision with managed-pressure drilling to meet Petrobras single-point accountability demands. |
| Offshore Wind Conversion Program | Repurposes shallow-water jack-ups for turbine foundation installation using modified cantilever systems. |
| DP-3 Certification Pipeline Investment | Captures scarce marine officer capacity through captive training partnerships with Norwegian maritime academies. |
Research Methodology
Independent corroboration across rig fleet operators, classification society surveyors, and national oil company procurement directors underwrites the qualitative findings. Primary interviews with drilling contractors, marine superintendents, shipyard project managers, and BSEE compliance officers combined with secondary validation from IHS Markit offshore rig databases, Bureau of Safety and Environmental Enforcement incident reports, and ANP production disclosure filings. Bottom-up rig-by-rig utilization modeling and top-down basin-level demand aggregation provided cross-check triangulation.
Comparable-period anchoring to historical fleet deployment patterns from 2019 through 2024 established baseline utilization and dayrate trajectories across the projection horizon. Segmentation dimensions modeled include rig architecture type, water depth capability tier, service category across the well lifecycle, and regional regulatory framework cluster. CAGRs derived from rig supply-demand balance projections incorporating Petrobras drilling schedule commitments and IMO enforcement phase-in timelines.
Revisions become necessary when ANP local content mandates shift, dual-fuel engine delivery schedules slip, or pre-salt exploration results disappoint. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Offshore Oilfield Services Market