
 Middle East Offshore MRO Market | 2026-2036
Middle East Offshore MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Offshore MRO Market Insights
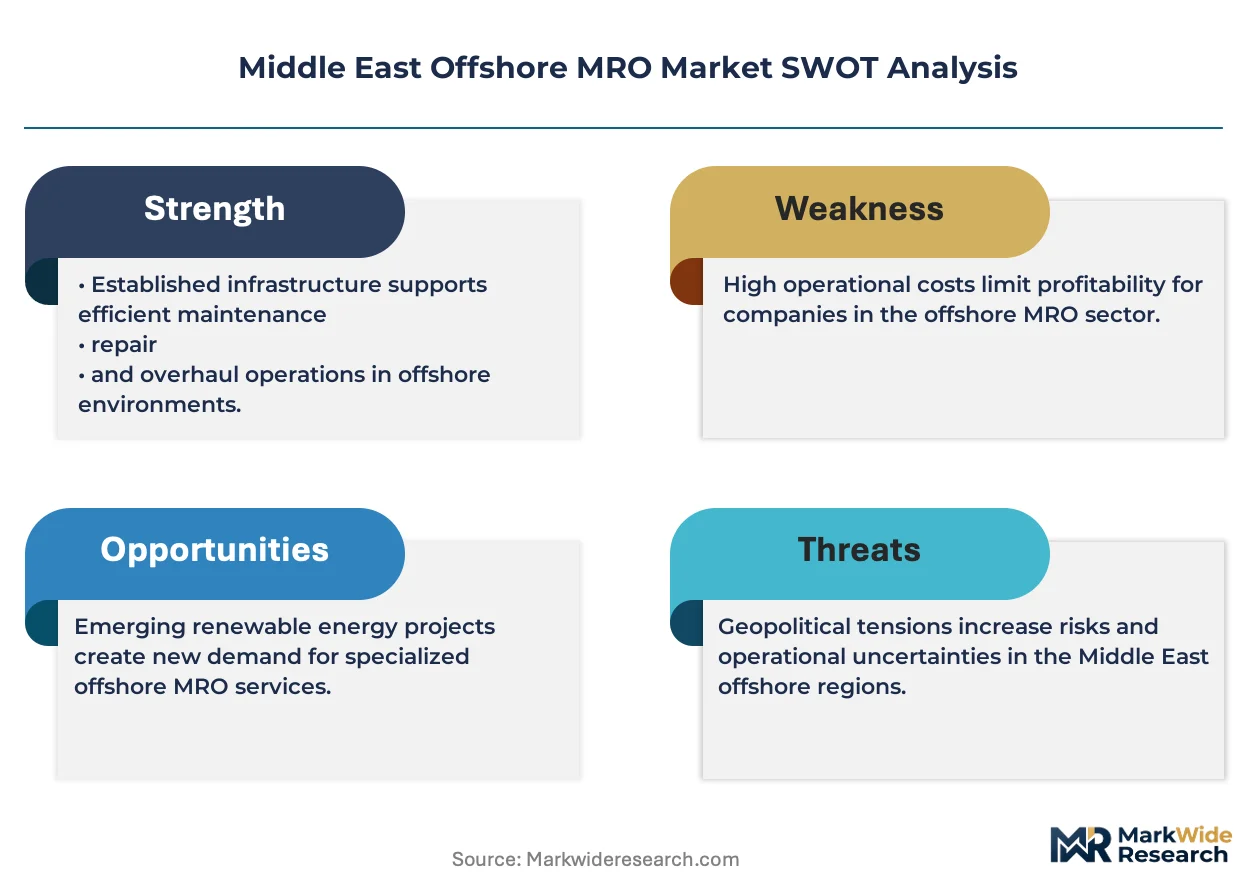
IMO 2023 greenhouse gas strategy is hardening emission benchmarks for offshore support vessels operating in Middle East waters. Rolls-Royce plc leverages its Bergen engine portfolio to compete on dual-fuel retrofit packages for platform supply vessels. Wärtsilä Corporation anchors its position through integrated propulsion service contracts tied to long-term rig operator agreements. MAN Energy Solutions SE specializes in turbocharger overhaul networks stretching from Dubai to Dammam.
Offshore MRO encompasses the technical servicing, component replacement, and system restoration of drilling rigs, production platforms, and marine support vessels operating beyond coastal boundaries, typically requiring ABS or DNV certification compliance for structural repairs and machinery overhauls. Hydraulic Systems maintenance commands the largest revenue pool among technology segments due to the continuous cycling of blowout preventer control units and subsea crane mechanisms. Predictive Maintenance offerings within the service portfolio are expanding fastest as rig operators deploy sensor arrays to forecast pump failures and reduce unplanned downtime in high-temperature Arabian Gulf conditions.
SFDA equipment certification requirements intersect with IMO safety conventions to shape spare parts sourcing and workshop qualification standards across Saudi Arabia and the UAE. The country's national maritime regulator enforces port state control inspections that determine which MRO providers gain docking access for emergency repairs. Stakeholders must monitor how Gulf national oil companies bundle long-term service contracts with local content mandates, as these procurement structures will determine which technology segments and service tiers capture incremental spending.
Market Dynamics
Aramco's fleet expansion and the International Maritime Organization's greenhouse gas strategy are forcing rig operators to accelerate maintenance spending and energy-efficiency retrofits across Arabian Gulf waters.
Growth Catalysts
- SFDA Equipment Certification:Saudi Arabia's national maritime regulator enforces port state control inspections that expand qualified MRO provider access for emergency repairs. Workshop qualification standards tighten, elevating certified service tiers.
- Jack-up Rig Aging:Oil and gas companies across the Arabian Gulf expand maintenance budgets for aging jack-up rigs. Inspection and overhaul cycles compress as structural fatigue accelerates in high-salinity conditions.
- Dual-fuel Retrofit Mandates:IMO 2023 greenhouse gas strategy hardens emission benchmarks for offshore support vessels. Platform supply vessel operators invest in engine conversion packages to maintain charter eligibility.
Market Restraints
- Specialized Labor Scarcity:ABS and DNV certification requirements for structural repairs limit the pool of qualified welders and inspection engineers. Training timelines stretch 18-24 months for critical offshore certifications.
- Spare Parts Supply Concentration:Turbocharger overhaul networks cluster between Dubai and Dammam. Geographic concentration creates single-point vulnerability for urgent rig repairs outside these corridors.
- High-temperature Equipment Degradation:Arabian Gulf operating conditions accelerate hydraulic seal failure and electronic component thermal stress. Replacement frequencies exceed temperate-climate baselines by 40 percent.
Strategic Opportunities
- Predictive Maintenance Sensor Deployment:Rig operators deploy sensor arrays to forecast pump failures. Machine learning integration with existing SCADA systems reduces unplanned downtime in Saudi offshore fields.
- UAE Local Content Procurement:MOHAP equipment certification intersects with national oil company bundling requirements. Foreign MRO providers must form joint ventures to capture incremental overhaul contracts.
- Subsea Crane Mechanism Overhaul:Hydraulic systems maintenance commands the largest technology segment. Specialized service capacity for blowout preventer control units remains underdeveloped outside Dammam and Abu Dhabi.
Industry Challenges
- Certification Timeline Compression:ABS and DNV structural repair approvals require extensive documentation and witness testing. Emergency repair windows often expire before certification completion.
- Legacy System Integration:Sensor-based predictive maintenance must interface with 1990s-era rig control architectures. Protocol translation and data standardization consume implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Offshore MRO Market |
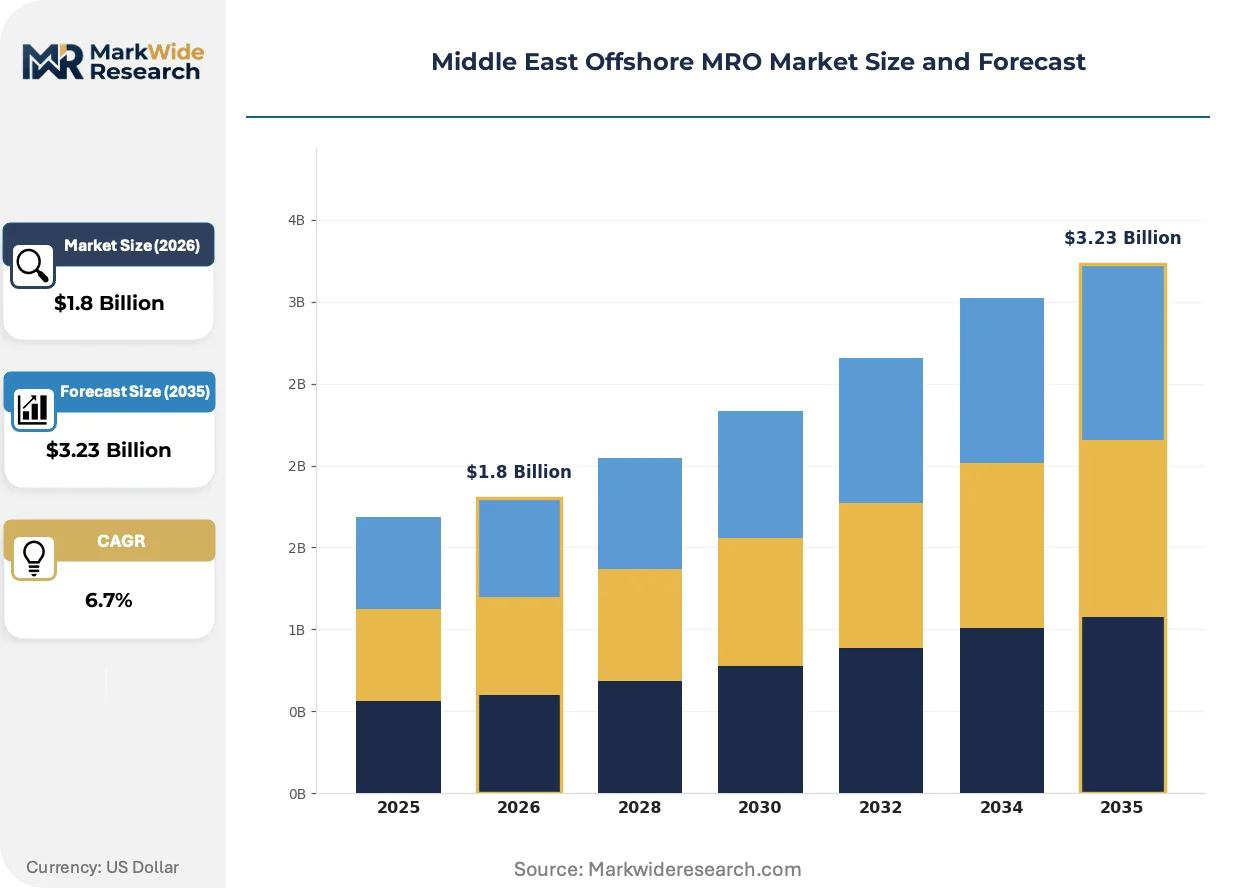
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Inspection Technology: Hydraulic Systems, Electrical Systems, Control Systems, Navigation Systems End User: Oil & Gas Companies, Shipping Firms, Rig Operators, Marine Contractors Offering: Predictive Maintenance, Emergency Repairs, Scheduled Servicing, Upgrades |
| Companies Covered | BAE Systems, General Dynamics, Huntington Ingalls Industries, Lockheed Martin Corporation, Northrop Grumman Corporation, Rolls-Royce plc, Wärtsilä Corporation, MAN Energy Solutions SE, Caterpillar, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Offshore MRO Market Trends and Innovations
Digital condition monitoring and regulatory emission mandates are compressing maintenance cycles while elevating technical service requirements for offshore asset operators.
Sensor-based predictive maintenance is absorbing capital allocation from scheduled overhaul programs. Rig operators in Saudi Arabia deploy vibration and thermal monitoring arrays on critical pumps and compressors. The technology is absorbing maintenance budget share as unplanned downtime costs exceed preventive service premiums in high-temperature Arabian Gulf conditions.
IMO 2023 greenhouse gas strategy mandates carbon intensity reductions for offshore support vessels. Engine manufacturers develop dual-fuel retrofit packages enabling LNG or methanol operation. Platform supply vessel fleets in UAE and Saudi waters face charter renewal deadlines that compress installation timelines.
Long-term service contracting is displacing transactional repair procurement among national oil companies. Aramco bundles inspection, overhaul, and spare parts provisioning into multi-year agreements. This pattern concentrates vendor relationships and marginalizes small workshop operators lacking integrated capability portfolios.
Middle East Offshore MRO Market Segmentation
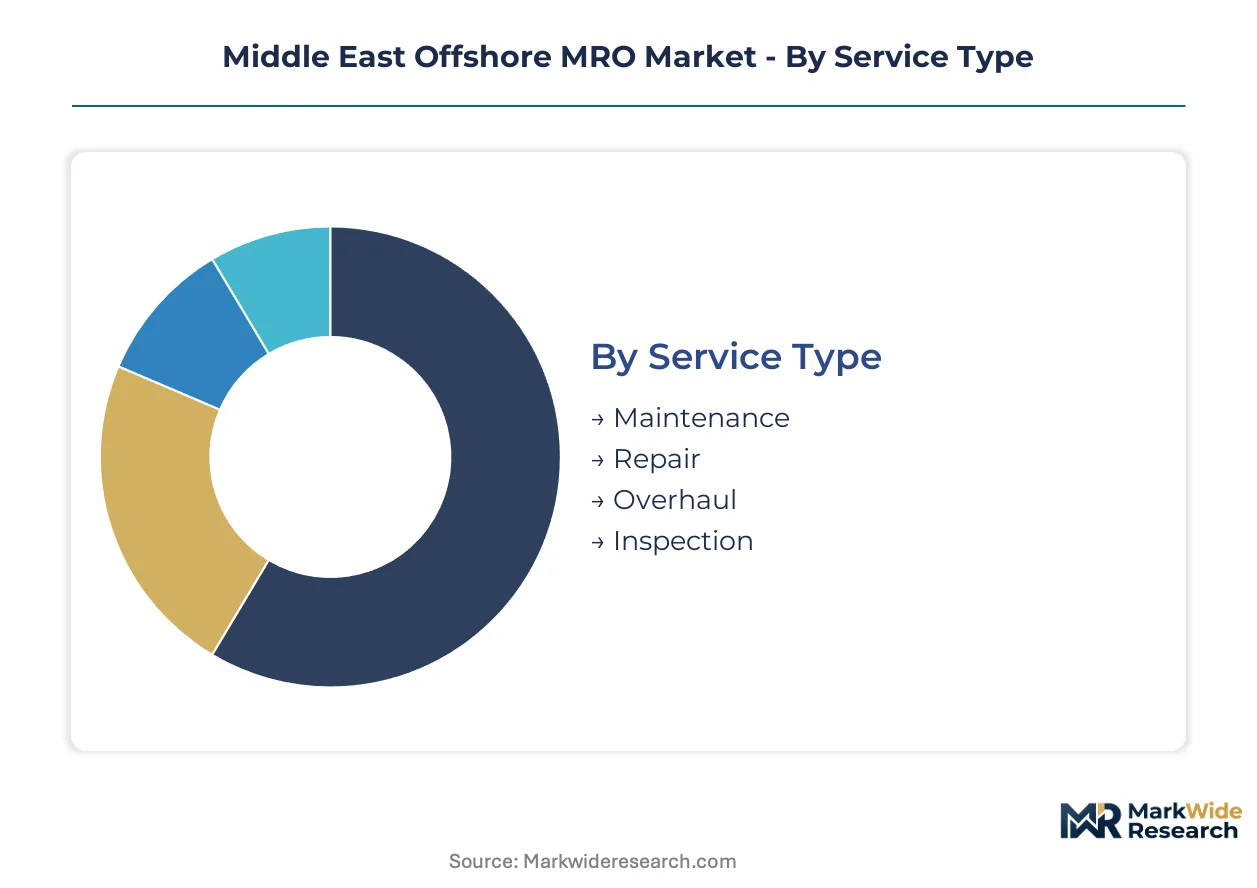
Offshore MRO procurement patterns vary sharply across service tiers and asset classes. Saudi Aramco's bundled contracting and IMO retrofit mandates reshape how operators allocate maintenance budgets across technology segments.
Service Type:
Standardization dominates routine interventions while emergency response demands bespoke mobilization protocols.
- Maintenance:Scheduled interventions on blowout preventer control units and subsea crane mechanisms follow manufacturer-prescribed intervals. Aramco's long-term service agreements concentrate demand in Dammam workshops with SFDA certification.
- Repair:Structural fatigue remediation on aging jack-up rigs requires ABS or DNV witness testing. High-salinity Arabian Gulf conditions compress repair windows and elevate certified welder utilization rates.
- Overhaul:Complete system restoration of platform supply vessel propulsion.
- Inspection:Port state control examinations enforced by Saudi Arabia's national maritime regulator.
Most installed capacity flows through Maintenance. Expansion is steepest in Repair.
Technology:
Hydraulic infrastructure absorbs the largest share of labor hours due to continuous cycling demands.
- Hydraulic Systems:Blowout preventer control units and subsea crane mechanisms require seal replacement frequencies 40 percent above temperate baselines. Thermal stress in Arabian Gulf operations drives spare parts consumption.
- Control Systems:Legacy SCADA architecture integration challenges constrain sensor-based predictive maintenance deployment. Protocol translation consumes implementation resources on 1990s-era rig platforms.
- Electrical Systems:Generator and switchgear servicing for offshore power distribution.
- Navigation Systems:Dynamic positioning equipment calibration and gyrocompass maintenance.
Hydraulic Systems command the dominant revenue pool. Control Systems are climbing the fastest on digital retrofit demand.
End User:
Procurement scale separates national oil companies from fragmented marine contractor fleets.
- Oil & Gas Companies:Aramco's offshore fleet expansion drives inspection and overhaul spending through multi-year bundled agreements. Local content mandates force foreign MRO providers into joint venture structures.
- Rig Operators:Jack-up rig aging accelerates structural repair procurement. Charter renewal deadlines compress maintenance windows for platform drilling contractors.
- Shipping Firms:Offshore support vessel emission compliance retrofits.
- Marine Contractors:Project-based maintenance for subsea installation spreads.
Oil & Gas Companies anchor volume procurement. Rig Operators are expanding most quickly on asset renewal cycles.
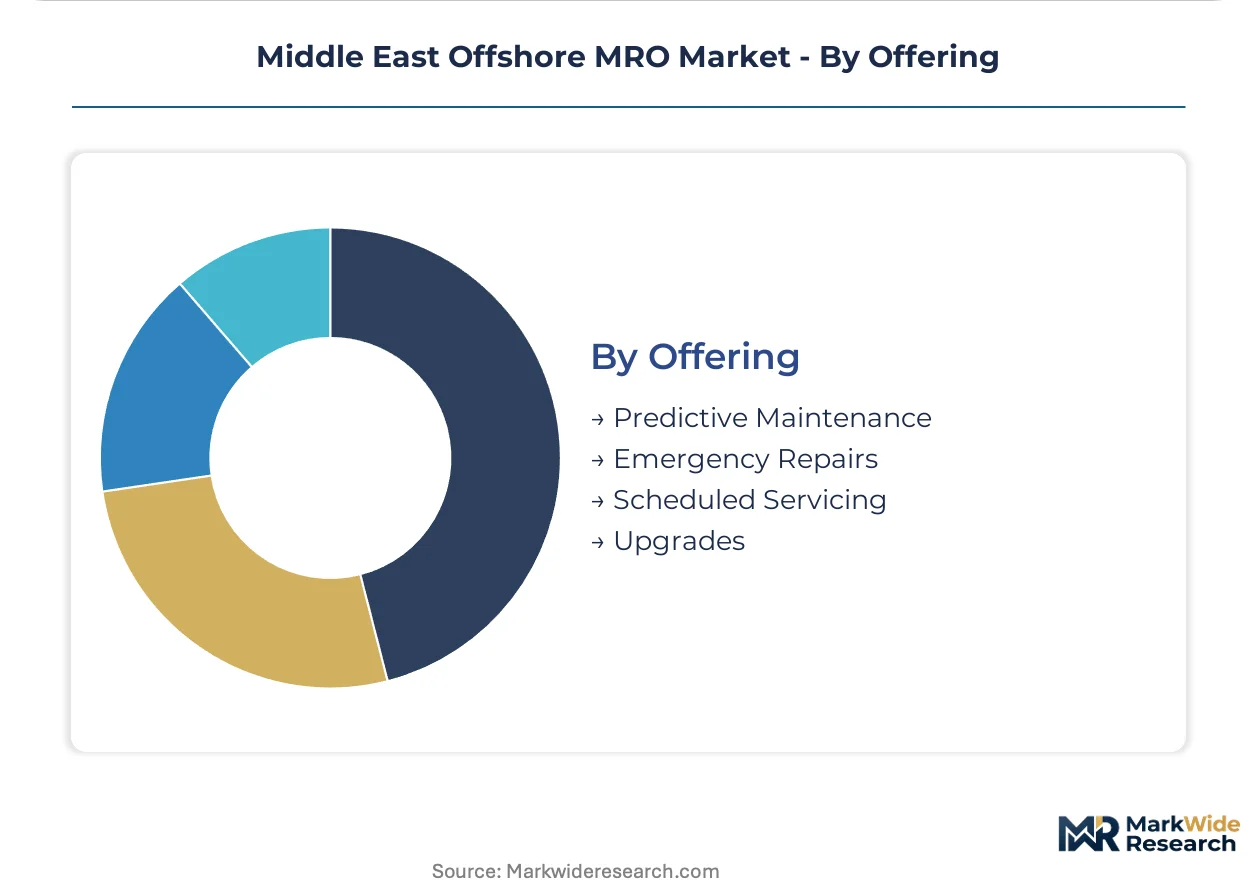
Offering:
Outcome-based contracting is displacing transactional repair procurement among integrated operators.
- Predictive Maintenance:Vibration and thermal monitoring arrays on critical pumps reduce unplanned downtime costs. Machine learning integration with existing SCADA systems absorbs capital allocation from scheduled overhaul programs.
- Scheduled Servicing:Calendar-based interventions on class-certified machinery. Workshop qualification standards under SFDA and MOHAP frameworks determine provider eligibility.
- Emergency Repairs:Port state control inspection-triggered mobilization.
- Upgrades:Dual-fuel engine conversion packages for IMO compliance.
Scheduled Servicing retains the largest contract volume. Predictive Maintenance is gaining share fastest on sensor deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welders and DNV-qualified inspection engineers cluster in Dammam, Dubai, and Abu Dhabi, anchoring the Middle East's offshore MRO technical workforce. Aramco's fleet expansion and UAE port state control regimes concentrate demand in these three metropolitan zones.
Saudi Arabia
Aramco's jack-up rig aging and offshore platform renewal cycles drive hydraulic system overhaul demand. SFDA equipment certification and port state control inspections determine which workshops gain emergency repair access. Dammam's industrial corridor hosts the densest concentration of ABS-certified structural repair facilities serving Arabian Gulf operations.
United Arab Emirates
Dubai and Abu Dhabi compete for platform supply vessel retrofit contracts tied to IMO emission deadlines. MOHAP equipment certification intersects with local content mandates that force foreign providers into joint venture structures. Jebel Ali's maritime cluster specializes in turbocharger overhaul networks stretching across the Gulf.
Qatar
North Field expansion projects sustain demand for subsea crane mechanism servicing and blowout preventer maintenance. The national petroleum operator bundles long-term service agreements that favor integrated MRO providers with predictive maintenance capabilities. Ras Laffan's industrial zone attracts hydraulic specialists serving offshore construction spreads.
Kuwait
Kuwait Oil Company's offshore fleet modernization compresses inspection cycles for aging production platforms. The national maritime authority enforces classification society witness testing requirements that elevate certified workshop standards. Al-Ahmadi's maintenance corridor concentrates electrical system and generator overhaul capacity.
Middle East Offshore MRO Market Competitive Landscape
Capital-heavy engine manufacturers compete with asset-light service integrators for platform supply vessel retrofit contracts. The vendor base organizes into three tiers: original equipment manufacturers with captive service networks, independent hydraulic specialists, and regional workshop operators seeking SFDA certification. Consolidation pressures intensify as Aramco's bundled procurement favors multi-capability portfolios over single-service vendors. Dominant competitive moves include long-term service contracting and joint venture formation to satisfy local content mandates.
Among European-origin engine and propulsion specialists, Rolls-Royce plc and Wärtsilä Corporation exemplify the integrated service archetype, while MAN Energy Solutions SE occupies a position within the component overhaul tier. These entities anchor competitive positioning through dual-fuel retrofit packages and turbocharger network density rather than transactional repair capture.
| Leading Market Players |
|---|
| BAE Systems |
| General Dynamics |
| Huntington Ingalls Industries |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Rolls-Royce plc |
| Wärtsilä Corporation |
| MAN Energy Solutions SE |
| Caterpillar |
| Others |
Pricing and Supply Chain Analysis
Turbocharger casting alloys and specialized welding wire move from European foundries through Dubai's Jebel Ali corridor into tiered service pricing that separates ABS-certified emergency repairs from scheduled workshop overhauls. Aramco's bundled procurement concentrates volume discounts among integrated providers while marginalizing single-service operators.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across Arabian Gulf offshore MRO. Long-term service agreements with Aramco command premium rates through guaranteed capacity reservation and SFDA-certified workshop access. Price differentiation hinges on certification tier—ABS/DNV witness testing elevates structural repair premiums—and geographic delivery cost to remote rig locations. Cost compression in standard maintenance tiers intensifies as regional workshop operators compete for scheduled servicing contracts. Independent rig operators exhibit highest price sensitivity due to charter renewal pressures, while national oil companies prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Workforce availability constraints in South Korea, Germany, and Japan shape original equipment manufacturer lead times for critical propulsion components. Hydraulic seal production draws from Japanese polymer specialists and German precision molding facilities. Single-source vulnerability concentrates in turbocharger core assemblies manufactured by a narrow supplier base. Distribution runs through Dammam's industrial corridor for Saudi-bound rig fleets and Jebel Ali's maritime cluster for UAE platform supply vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in predictive maintenance sensor deployment and dual-fuel retrofit certification, where technical differentiation commands pricing power above commodity repair rates.
For Market Incumbents: Cement market position through captive turbocharger overhaul networks stretching from Dubai to Dammam and integrated propulsion service contracts tied to multi-year rig operator agreements. SFDA certification investment creates defensive moats against emerging regional workshop operators. Sensor-based predictive maintenance capabilities differentiate from transactional repair competitors.
For New Entrants and Emerging Players: Joint venture structures with established UAE maritime clusters unlock access to MOHAP-certified procurement channels. Subsea crane mechanism overhaul capacity remains underdeveloped outside Dammam and Abu Dhabi, presenting white-space opportunity. Target predictive maintenance integration services for legacy SCADA architectures on 1990s-era jack-up rigs.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional workshop operators lack bundled service portfolios to meet Aramco's multi-year contracting requirements. Long-term viability favors integrated MRO providers with SFDA/MOHAP dual certification and sensor deployment capabilities. Watch for IMO emission deadline acceleration as inflection indicator for dual-fuel retrofit demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Sensor Deployment | Machine learning integration with SCADA systems reduces unplanned downtime in Saudi offshore fields. |
| Dual-Fuel Retrofit Certification | IMO 2023 compliance packages maintain platform supply vessel charter eligibility in UAE waters. |
| Joint Venture Formation | Local content mandates force foreign MRO providers into UAE partnership structures for workshop access. |
| Turbocharger Network Expansion | Geographic density between Dubai and Dammam captures urgent rig repair demand outside core corridors. |
| SFDA Certification Investment | Workshop qualification standards determine emergency repair access to Saudi Arabia's port state control regime. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from rig maintenance directors, SFDA certification officers, hydraulic systems engineers, and Aramco procurement leads. Secondary validation drew from ABS classification records, DNV technical reports, Saudi customs trade data, and IMO greenhouse gas strategy documentation. Bottom-up service tier sizing and top-down national oil company spending estimates were cross-referenced for triangulation.
Comparable historical maintenance cycles anchored the projection framework across the analysis window. Segmentation modeling incorporated service type, technology segment, end-user procurement scale, and regulatory certification tier. CAGRs were derived from expenditure pattern analysis across hydraulic systems, control systems, and propulsion overhaul categories. Forecast inputs included jack-up rig age profiles, IMO compliance deadlines, and sensor deployment economics in high-temperature operating conditions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SFDA regulatory enforcement intensity and dual-fuel engine technology maturation. Forecasts reflect documented assumptions regarding Aramco fleet expansion timelines and UAE local content mandate evolution. Material deviation in IMO emission benchmark acceleration or Gulf national oil company procurement restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market