
 Deep Water Drilling Market | 2026-2036
Deep Water Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Water Drilling Market Outlook
Brazilian ultra-deepwater pre-salt development is realigning global floater deployment schedules. Transocean Ltd. dominates high-specification drillship operations across the Santos Basin, leveraging its 12,000-foot capability fleet. Schlumberger Limited sustains integrated drilling services through its pressure management and logging-while-drilling technology portfolio. Baker Hughes Company competes in subsea wellhead systems and BOP control architecture for harsh-environment fields.
Deep water drilling encompasses well construction in water depths exceeding 400 meters, utilizing dynamically positioned drillships and semi-submersible rigs rated for 10,000+ psi wellbore pressures to access hydrocarbon reservoirs beneath salt layers and complex geologies. The primary commercial purpose is to extract crude oil and natural gas from offshore fields where conventional shelf platforms prove technically or economically unviable. Rotary drilling remains the foundational method, though managed pressure drilling commands premium contracting rates where narrow margin windows between pore pressure and fracture gradient constrain conventional approaches. Drillships represent the fastest-growing equipment category, displacing older semi-submersibles in water depths beyond 1,500 meters where station-keeping precision determines commercial viability.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape capital allocation toward redundant shear ram systems. Brazil's National Petroleum Agency imposes local content requirements that structure supply chain localization for foreign operators bidding pre-salt concessions. The International Maritime Organization's greenhouse gas strategy is forcing fuel transition planning across deepwater fleets, with dual-fuel engine retrofits emerging as a compliance pathway. Stakeholders must weigh rig dayrate sensitivity against carbon intensity benchmarks when contracting assets for multi-year development programs.
Market Dynamics
Managed pressure drilling systems are compressing the operational envelope for ultra-deepwater wells, forcing contractors to retire conventional rigs and reallocate capital toward dual-gradient capable assets. Brazil's pre-salt licensing rounds and the US Bureau of Safety and Environmental Enforcement's post-Macondo well control mandates are synchronizing to reshape fleet composition.
Growth Catalysts
- Brazil's pre-salt auction schedule:The National Petroleum Agency's regular licensing rounds for Santos Basin blocks sustain rig demand from international operators seeking high-volume crude reservoirs beneath salt layers.
- Managed pressure drilling adoption:Narrow margin drilling windows in West African deepwater corridors are accelerating contractor uptake of closed-loop circulation systems for wellbore stability.
- Dual-fuel engine retrofits:The International Maritime Organization's greenhouse gas strategy is compelling fleet operators to convert diesel-electric rigs to LNG-capable propulsion for charter compliance.
Market Restraints
- High-specification rig supply concentration:South Korean and Singaporean shipyards control newbuild construction for 12,000-foot capable drillships, creating queue bottlenecks during demand surges.
- Blowout preventer certification delays:The US Bureau of Safety and Environmental Enforcement's shear ram testing protocols extend commissioning timelines for newly delivered rigs.
- Geopolitical licensing uncertainty:Ghanaian and Angolan petroleum fiscal terms fluctuate with election cycles, deterring multi-year development program commitments.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil-led consortium discoveries are creating demand for harsh-environment floaters in a previously dormant deepwater province.
- Integrated service contracting:National oil companies in West Africa are bundling drilling, completions, and subsea installation under single-source agreements to reduce interface risk.
- Digital twin deployment:Real-time wellbore modeling combined with predictive maintenance analytics is enabling condition-based rig chartering rather than fixed-term fixtures.
Industry Challenges
- Deepwater drilling engineer scarcity:Experienced personnel capable of managing narrow-margin pressure regimes in salt-subsalt geology command premium compensation, constraining crew rotation.
- Legacy semi-submersible integration:Contractors face technical complexity retrofitting 1990s-era rigs with managed pressure drilling packages and redundant shear ram systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Water Drilling Market |
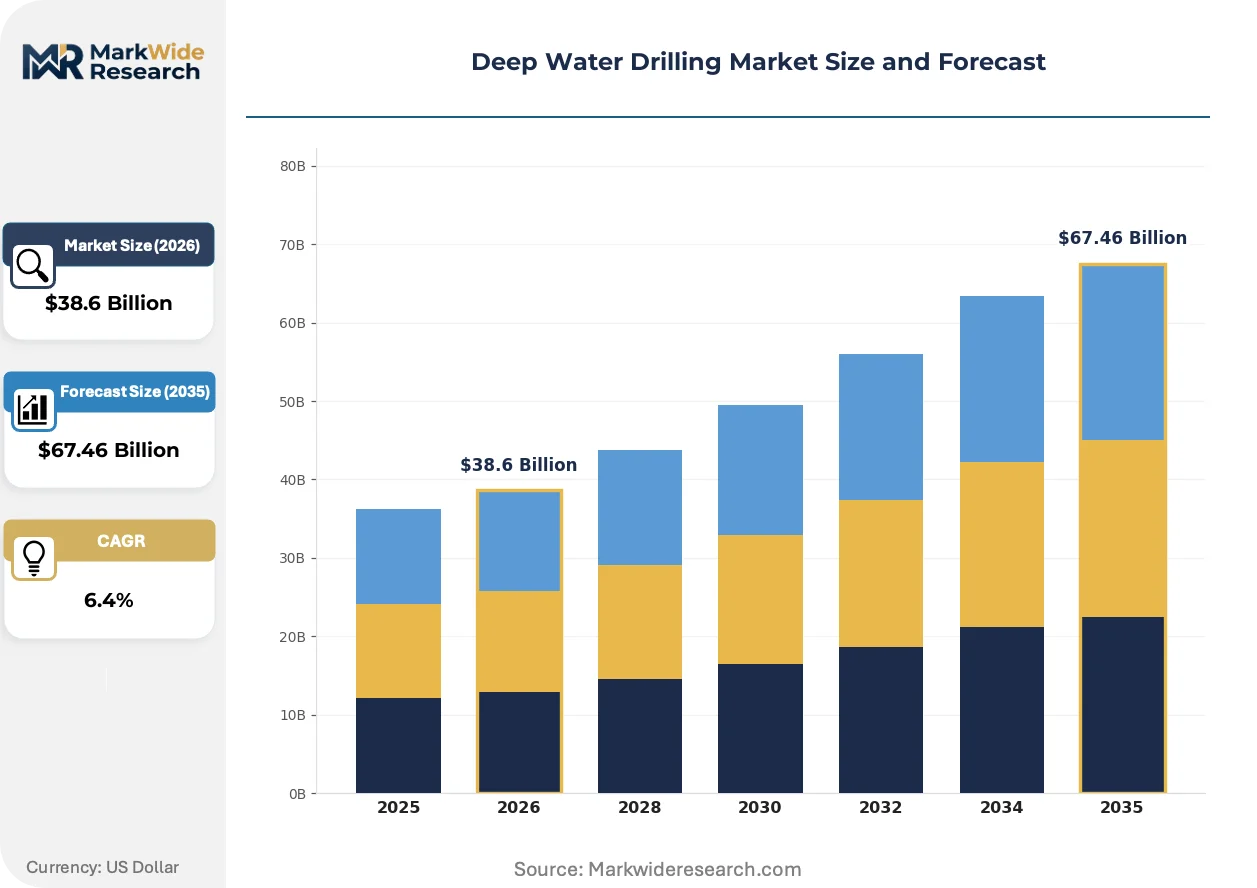
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Rotary Drilling, Managed Pressure Drilling, Dual Gradient Drilling, Automated Drilling End User: Oil & Gas Companies, Government Agencies, Offshore Contractors, Research Institutions Equipment Type: Drillships, Semi-Submersibles, Jack-Up Rigs, Submersibles Application: Exploration, Production, Well Completion, Reservoir Management |
| Companies Covered | Transocean Ltd., Schlumberger Limited, Halliburton Company, Baker Hughes Company, Valaris plc, Noble Corporation plc, Seadrill Limited, Saipem S.p.A., China Oilfield Services Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Water Drilling Market Strategic Shifts
Digital automation and pressure management technologies are compressing the skill threshold for ultra-deepwater operations while regulatory carbon intensity benchmarks are forcing propulsion architecture redesigns. Equipment modularity and service unbundling are simultaneously reshaping how contractors configure assets and how operators procure them.
Subsea BOP control systems are modularizing to enable rapid reconfiguration between drilling and completion modes without dry-dock intervention. Contractors operating across Brazil's Santos Basin are adopting these stack designs to minimize mobilization downtime between pre-salt wells. The technology is modularizing contractor fleet economics by extending the productive window of mid-life assets without full replacement.
The International Maritime Organization's greenhouse gas strategy is mandating carbon intensity indicator compliance for offshore vessels above 5,000 gross tonnage. Deepwater drillship operators are responding with battery-hybrid power packs and shore-power connection capability during port calls. Dual-fuel LNG-diesel engine retrofits are concentrating in the US Gulf of Mexico fleet where charterers face the most stringent environmental scrutiny.
Dayrate contracting is fragmenting into performance-linked structures where operators pay premium rates only for mechanical uptime and target rate-of-penetration achievements. National oil companies in Angola and Ghana are piloting these models to transfer operational risk to drilling contractors. West African deepwater corridors are displaying the fastest uptake of outcome-based pricing as project finance requirements tighten capital efficiency standards.
Deep Water Drilling Market Segmentation
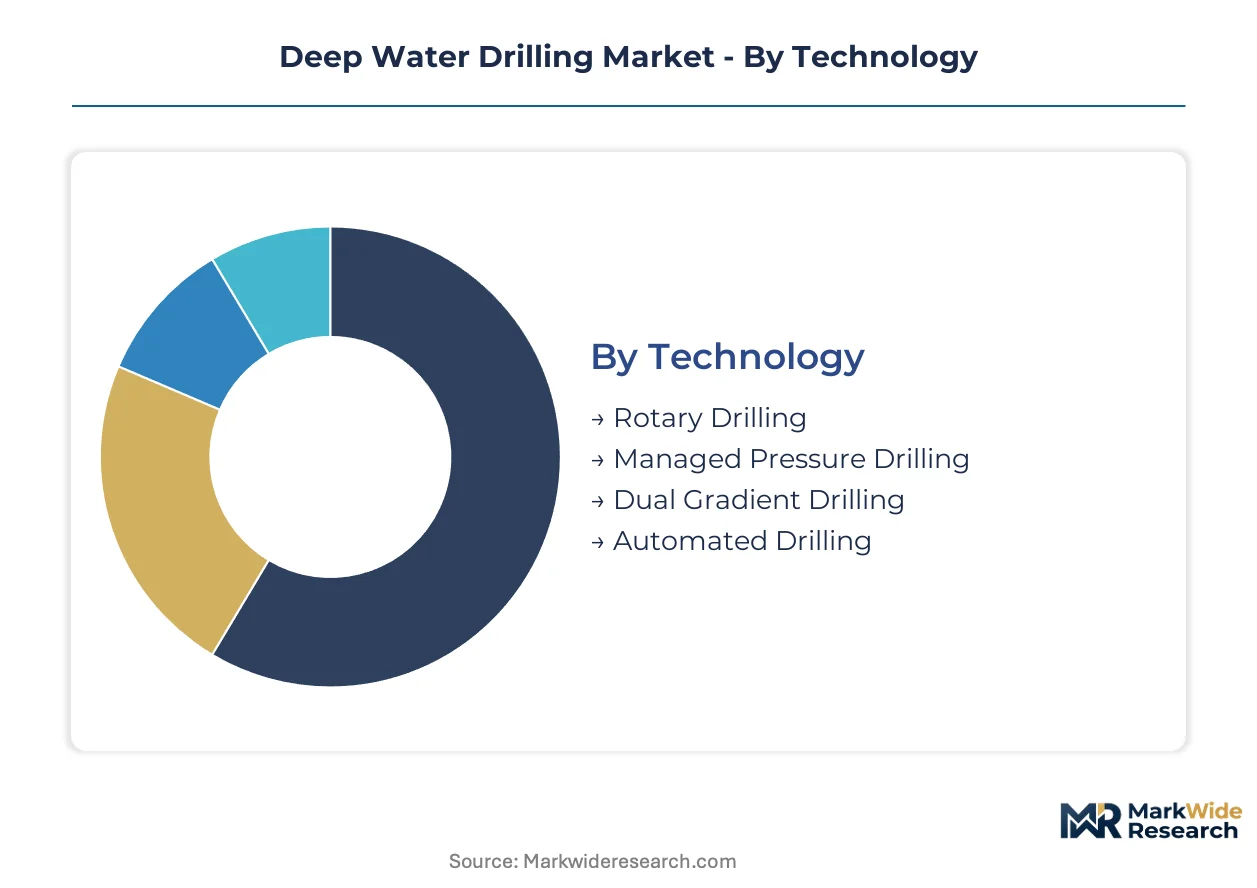
Deep water drilling market segmentation reveals distinct capital allocation patterns across technology tiers, equipment categories, and operator types. Each dimension carries specific investment intensity thresholds that structure contractor fleet strategies and national oil company procurement decisions.
Technology:
Capital intensity peaks with closed-loop circulation architectures requiring redundant pressure control systems and real-time telemetry infrastructure.
- Managed Pressure Drilling:Closed-loop circulation systems maintain constant bottom-hole pressure through automated choke manipulation. Demand concentrates in Brazil's Santos Basin pre-salt wells where narrow margins between pore pressure and fracture gradient prevent conventional techniques. The US Bureau of Safety and Environmental Enforcement's well control mandates accelerate contractor adoption of these systems for Gulf of Mexico ultra-deepwater programs.
- Dual Gradient Drilling:Seawater-based riser systems decouple wellbore hydrostatics from riser column weight, enabling access to geopressured reservoirs beneath salt layers. West African deepwater corridors—particularly Ghanaian and Angolan blocks—drive fleet conversion toward dual-gradient capable assets as exploration targets deepen below 3,000 meters.
- Rotary Drilling:Conventional rotary table and top-drive systems remain the baseline technology for stable pressure regimes above 1,500 meters water depth.
- Automated Drilling:Robotic pipe handling and autonomous directional control reduce crew exposure in harsh-environment floaters.
Most installed capacity flows through Rotary Drilling. Expansion is steepest in Managed Pressure Drilling.
Equipment Type:
Unit economics diverge sharply between dynamically positioned vessels and moored platforms, with dayrate spreads reflecting station-keeping precision requirements.
- Drillships:Dynamically positioned monohull vessels with dual-derrick configurations achieve 12,000-foot water depth ratings and 10,000+ psi wellhead pressure containment. Brazil's pre-salt development programs anchor global demand for seventh-generation drillships, while Guyana-Suriname basin discoveries create incremental fixture requirements for harsh-environment units.
- Semi-Submersibles:Twin-pontoon platforms with anchored or dynamic positioning provide superior motion characteristics in North Atlantic and Barents Sea conditions. West African operators favor these assets for their lower fuel consumption and reduced carbon intensity profiles under International Maritime Organization compliance frameworks.
- Jack-Up Rigs:Self-elevating platforms with mat or independent leg systems operate in water depths below 150 meters.
- Submersibles:Bottom-founded platforms with limited water depth range serve niche shelf-edge applications.
Dayrate premiums concentrate in Drillships. Fleet renewal is accelerating fastest in Semi-Submersibles.
End User:
Contracting structures vary by counterparty risk profile, with national oil companies demanding longer-term fixtures than independent operators.
- Oil & Gas Companies:International majors and national oil companies charter floating rigs on multi-year development programs, with Brazil's Petrobras and Angola's Sonangol representing the largest single-source demand concentrations. These operators specify integrated service contracts bundling drilling, completions, and subsea installation to reduce interface risk.
- Offshore Contractors:Transocean, Seadrill, and Valaris operate as rig owners leasing assets to upstream operators, bearing mechanical uptime risk and regulatory compliance burdens. Their capital allocation decisions—newbuild versus retrofit—shape fleet composition across the Santos Basin and US Gulf of Mexico.
- Government Agencies:Regulatory bodies and research ministries fund frontier exploration in underexplored basins.
- Research Institutions:Academic and governmental research programs utilize modified drilling platforms for scientific ocean drilling.
Contract volume concentrates with Oil & Gas Companies. Procurement innovation is advancing most quickly through Offshore Contractors.
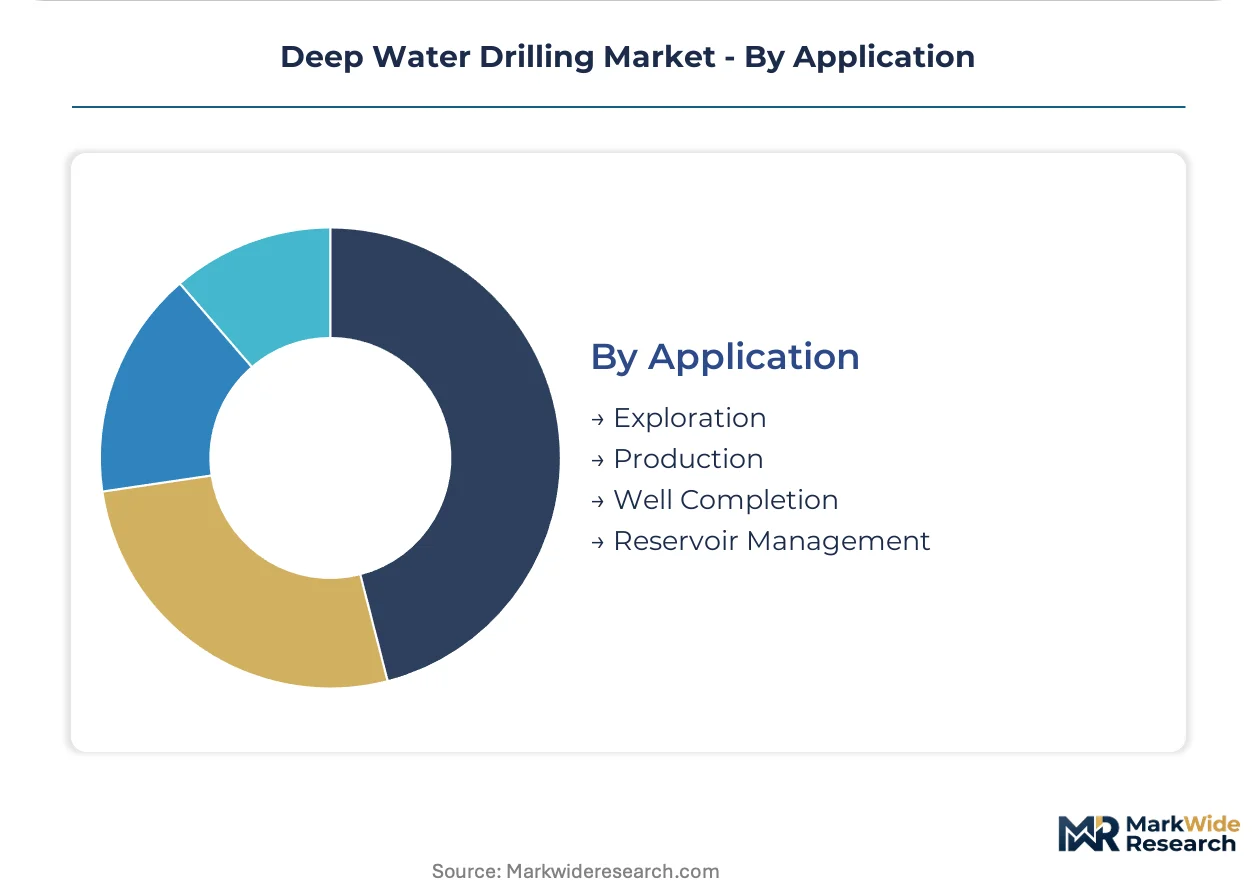
Application:
Revenue visibility differs across the well lifecycle, with production-phase contracts offering longer duration but lower dayrate elasticity than exploration-phase fixtures.
- Exploration:Wildcat and appraisal drilling in frontier basins carries high technical risk and intermittent fixture demand. Guyana-Suriname basin discoveries have reactivated exploration contracting for harsh-environment floaters, while Ghanaian and Angolan licensing rounds sustain West African exploration activity.
- Production:Development drilling and sidetrack operations from subsea templates generate recurring demand with 3-5 year contract horizons. Brazil's pre-salt production phase anchors the largest single-application demand concentration globally.
- Well Completion:Casing, cementing, and perforation operations following drilling phase.
- Reservoir Management:Injection well drilling and monitoring for enhanced recovery programs.
Fixed rig inventory deploys predominantly into Production. Activity growth is sharpest in Exploration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting deepwater capital toward jurisdictions with streamlined permitting and lower local-content burdens. Operators migrate drilling programs away from stringent well-control jurisdictions toward frontier basins offering fiscal certainty and faster project cycles.
United States
Gulf of Mexico ultra-deepwater exploration sustains fixture demand for 12,000-foot capable drillships. The US Bureau of Safety and Environmental Enforcement enforces blowout preventer testing protocols that extend rig commissioning timelines. Houston anchors the largest concentration of drilling contractors and service company headquarters managing Americas offshore programs.
Brazil
Pre-salt production drilling generates the world's largest single-market demand for high-specification floaters. Brazil's National Petroleum Agency imposes local content requirements structuring supply chain localization for foreign operators. The Santos Basin offshore Rio de Janeiro concentrates seventh-generation drillship deployment for salt-subsalt reservoir development.
Angola
Deepwater block licensing rounds attract international operators seeking lower-cost African frontier exposure. Sonangol's petroleum fiscal terms fluctuate with political cycles, creating contract duration uncertainty. The Lower Congo Basin offshore Cabinda hosts semi-submersible operations targeting post-salt carbonate reservoirs.
Guyana
ExxonMobil-led consortium discoveries are creating first-generation deepwater demand in a previously dormant province. The country's petroleum regulator establishes production-sharing frameworks without legacy infrastructure burdens. The Stabroek Block offshore Georgetown concentrates harsh-environment floater fixtures for Lower Cretaceous sandstone targets.
Norway
Arctic and Barents Sea frontier exploration sustains demand for harsh-environment semi-submersibles. The Norwegian Petroleum Directorate enforces stringent well integrity standards shaping contractor equipment specifications. Stavanger anchors North Sea drilling contractor headquarters managing Norwegian Continental Shelf development programs.
Deep Water Drilling Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated service bundling and digital automation vectors. The vendor base concentrates around three operational archetypes: asset-heavy rig owners bearing mechanical uptime risk, technology-integrated service providers, and national oilfield services with captive domestic markets. Competitive positioning crystallizes through fleet specialization strategies and regional licensing partnerships. Market participants execute capacity repositioning toward dual-fuel capable assets and outcome-based contracting structures.
Among Switzerland-based rig owners, Transocean Ltd. and Valaris plc exemplify the asset-heavy archetype with globally deployed floater fleets. Schlumberger Limited anchors the technology-integrated service tier through pressure management and logging-while-drilling capabilities. These three entities represent distinct competitive positions: Transocean Ltd. and Valaris plc concentrate capital in high-specification drillship ownership, while Schlumberger Limited occupies the bundled services vector where drilling technology and reservoir characterization converge.
| Leading Market Players |
|---|
| Transocean Ltd. |
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Valaris plc |
| Noble Corporation plc |
| Seadrill Limited |
| Saipem S.p.A. |
| China Oilfield Services Limited |
| Others |
Value Chain & Pricing Dynamics
The International Maritime Organization's greenhouse gas strategy gates qualified supply for dual-fuel capable drillships and commands premium-tier dayrate access for compliant assets. Operators without LNG-ready propulsion face contracting exclusion from charter pools, compressing pricing power toward shipyards with certified dual-fuel construction capability.
Pricing Analysis
Contractor-to-operator direct fixtures dominate, with dayrate spreads reflecting mechanical uptime guarantees and performance-linked rate-of-penetration clauses. Premium-mid-economy pricing differentiation separates seventh-generation drillships with 12,000-foot ratings from retrofitted semi-submersibles and legacy assets. Cost compression in standard-tier fixtures is intensifying as Brazilian pre-salt demand concentrates fixture volume with Petrobras and international majors. National oil companies in West Africa exhibit highest price sensitivity, while integrated majors in the US Gulf of Mexico accept premium rates for redundant shear ram certification.
Supply Chain Analysis
Specialized welder and marine engineer scarcity in South Korean and Singaporean shipyards extends delivery queues for high-specification drillships. Hull steel, subsea BOP control systems, and dynamic positioning thrusters draw from Japanese, German, and US supplier bases. Single-source vulnerability concentrates in blowout preventer shear ram actuators subject to US Bureau of Safety and Environmental Enforcement certification delays. Distribution runs through rig owner fleet management centers in Houston, Stavanger, and Singapore coordinating mobilization to named field locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as pre-salt reservoir development programs in Brazil sustain multi-year fixture demand with limited fleet elasticity. Capital deployment into compliant assets generates durable contracting visibility.
For Market Incumbents: Anticipate regulatory escalation in well control mandates by accelerating redundant BOP system retrofits across mid-life semi-submersibles. Consolidate supply chain positioning through captive relationships with South Korean shipyards before queue bottlenecks intensify. Dual-fuel conversion investment represents the critical lever for charter pool access under tightening International Maritime Organization carbon intensity benchmarks. For New Entrants and Emerging Players: Launch via integrated service contracting models bundling managed pressure drilling with completions and subsea installation for West African national oil companies. The Guyana-Suriname basin offers the most penetrable geography as ExxonMobil-led consortium activity creates first-generation demand without incumbent fleet saturation. Digital twin deployment for condition-based chartering provides differentiated go-to-market positioning against fixed-term fixture incumbents. For Investors and Strategic Acquirers: Roll-up economics work for mid-specification semi-submersible operators because fleet consolidation generates scale advantages in crew rotation and spare parts logistics across West African and Brazilian corridors. Target asset-heavy rig owners with convertible orderbook positions at Asian shipyards. Watch managed pressure drilling fixture penetration rates as the inflection signal for technology-mandated fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engine Retrofit Program | International Maritime Organization compliance secures charter access for seventh-generation drillships in premium basins. |
| Managed Pressure Drilling Integration | US Bureau of Safety and Environmental Enforcement mandates compress operational envelopes for ultra-deepwater well control. |
| Brazil Local Content Partnership | National Petroleum Agency requirements structure supply chain localization for pre-salt concession bidding. |
| Digital Twin Platform Deployment | Real-time wellbore modeling enables condition-based chartering replacing fixed-term fixtures with outcome pricing. |
| West Africa Integrated Service Contract | Angolan and Ghanaian national oil companies bundle drilling, completions, and subsea installation to reduce interface risk. |
Study Parameters
Multiple input streams — drilling contractor fleet managers, offshore operator procurement leads, shipyard project directors, and regulatory compliance officers — were reconciled against customs records, rig fixture databases, and national petroleum agency licensing round disclosures. Secondary validation drew from International Maritime Organization vessel registration data, US Bureau of Safety and Environmental Enforcement incident reports, and Brazilian National Petroleum Agency local content compliance filings. Bottom-up rig-by-rig fixture analysis and top-down basin-level demand estimation were triangulated to establish market sizing.
Data-stream reconciliation anchored volume projections across technology, equipment type, end user, and application dimensions with water depth rating and pressure capability as industry-specific stratifiers. CAGRs were derived from rig delivery schedules, retirement assumptions for pre-Macondo assets, and pre-salt production drilling campaign commitments. Forecast inputs incorporated dual-fuel conversion capex curves, managed pressure drilling adoption rates, and carbon intensity indicator compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Brazilian licensing suspension or accelerated International Maritime Organization emission enforcement. Projections reflect assumptions regarding pre-salt reservoir productivity, West African fiscal term stability, and shipyard delivery reliability. Material deviation in blowout preventer certification timelines or dual-fuel engine supply constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market