
 Calcium Silicate Boards Market | 2026-2036
Calcium Silicate Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Silicate Boards Market Outlook
Industrial facility managers is bifurcating demand away from general contractors as process safety budgets expand across petrochemical and power generation sites. Promat International NV dominates high-temperature fireproofing specifications through captive testing protocols and metallurgical partnerships. Saint-Gobain SA leverages its gypsum-to-insulation platform to cross-sell calcium silicate systems into European retrofit pipelines. Tianjin North Fine Ceramics anchors Asian supply through integrated raw material sourcing and kiln technology leadership.
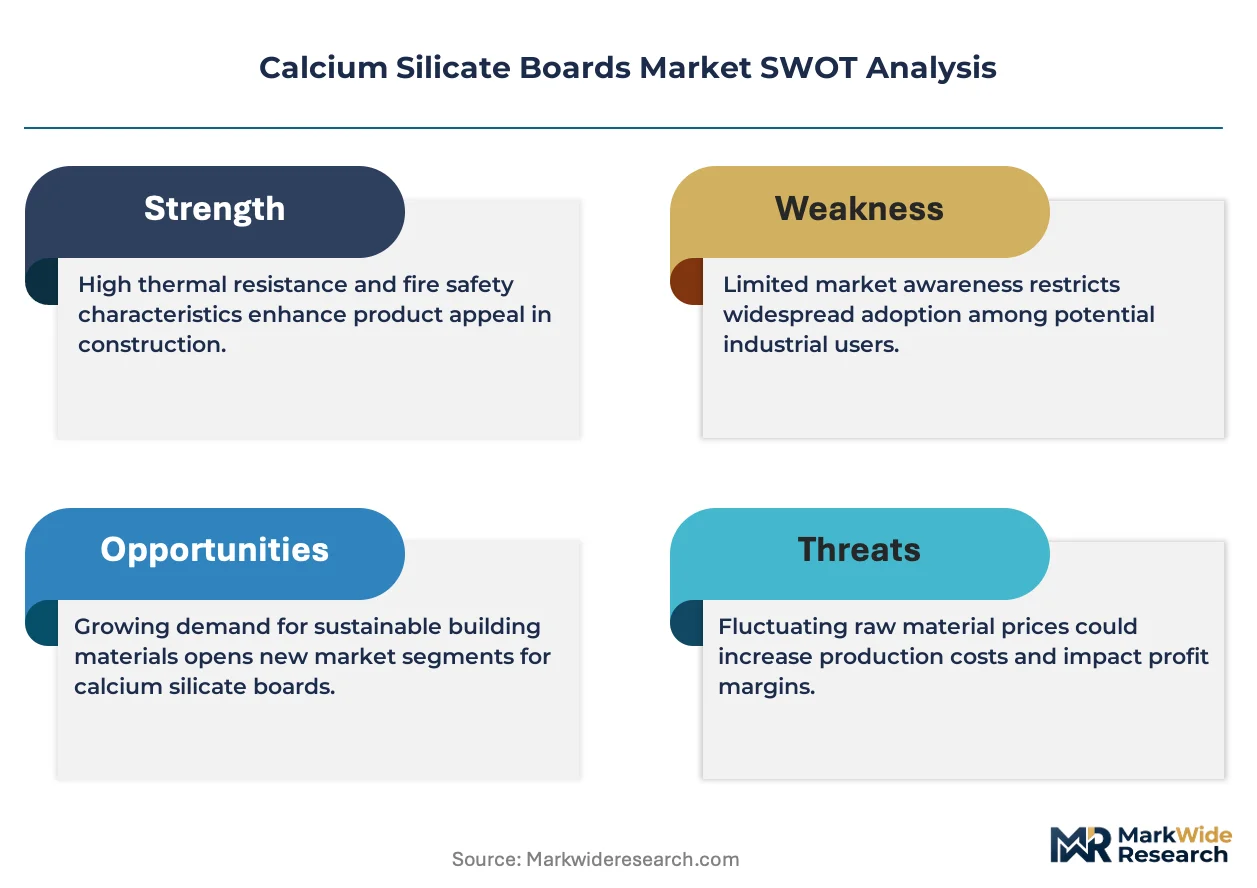
Calcium silicate boards are rigid, non-combustible panels manufactured from lime, silica, and reinforcing fibers through autoclave curing, typically rated for continuous service temperatures exceeding 1,000°C and engineered for thermal insulation, fire containment, and dimensional stability in industrial and commercial envelopes. Fire-Resistant Boards occupy the dominant value share due to mandatory passive fire protection in high-rise construction and tunnel infrastructure, while Thermal Insulation Boards represent the fastest-expanding category as building envelope codes tighten across temperate climates. Moisture-Resistant Boards command premium positioning in marine, food processing, and coastal applications where hydrothermal cycling degrades conventional alternatives.
The US EPA and OSHA jointly shape product compliance through emissions standards for fiber reinforcement and workplace exposure limits during installation, while the EU Green Deal and REACH framework restrict hazardous additives and mandate embodied carbon disclosure for construction materials imported into Europe. China's GB standards and MIIT industrial policy directives enforce domestic content thresholds and energy efficiency benchmarks that favor local calcium silicate manufacturers. Stakeholders must monitor evolving fire-test protocol harmonization between NFPA and EN standards, as divergence in certification requirements continues to fragment cross-border product qualification timelines and capital allocation decisions.
Market Dynamics
Passive fire protection mandates in high-rise construction and petrochemical infrastructure are compressing specification cycles and consolidating procurement authority among industrial facility managers away from general contractors.
Growth Catalysts
- EU Green Deal embodied carbon disclosure:REACH framework restrictions on hazardous additives accelerate material substitution toward calcium silicate systems in European retrofit pipelines.
- China infrastructure buildout:Massive domestic manufacturing scale and GB standards enforcement concentrate demand within Chinese high-temperature process equipment markets.
- Petrochemical process safety budgets:Facility managers expand specification of rigid non-combustible panels for fire containment in power generation and refining sites.
Market Restraints
- Lime and silica feedstock volatility:Energy-intensive autoclave curing processes expose manufacturers to input cost swings from cement and mineral sourcing.
- Asian supply concentration:Kiln technology leadership and integrated raw material sourcing in China create geographic dependency risk for non-domestic buyers.
- Mineral wool substitution threat:Lower-cost fiber-based alternatives erode specification share in sub-800°C thermal insulation applications where fire ratings permit.
Strategic Opportunities
- US IRA energy efficiency incentives:Tax credits for building envelope upgrades create pull-through demand for thermal insulation boards in commercial retrofits.
- Marine and coastal moisture-resistant positioning:Hydrothermal cycling resistance opens specification in shipbuilding and food processing where conventional alternatives degrade.
- Digital specification platforms:BIM-integrated material libraries streamline architect and engineer selection of pre-certified fire-rated systems.
Industry Challenges
- NFPA-EN fire-test protocol divergence:Non-harmonized certification requirements fragment cross-border product qualification timelines and capital allocation decisions.
- Skilled installation labor scarcity:Workplace exposure limits during fiber-reinforced board cutting and fitting constrain project velocity in tight construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Silicate Boards Market |
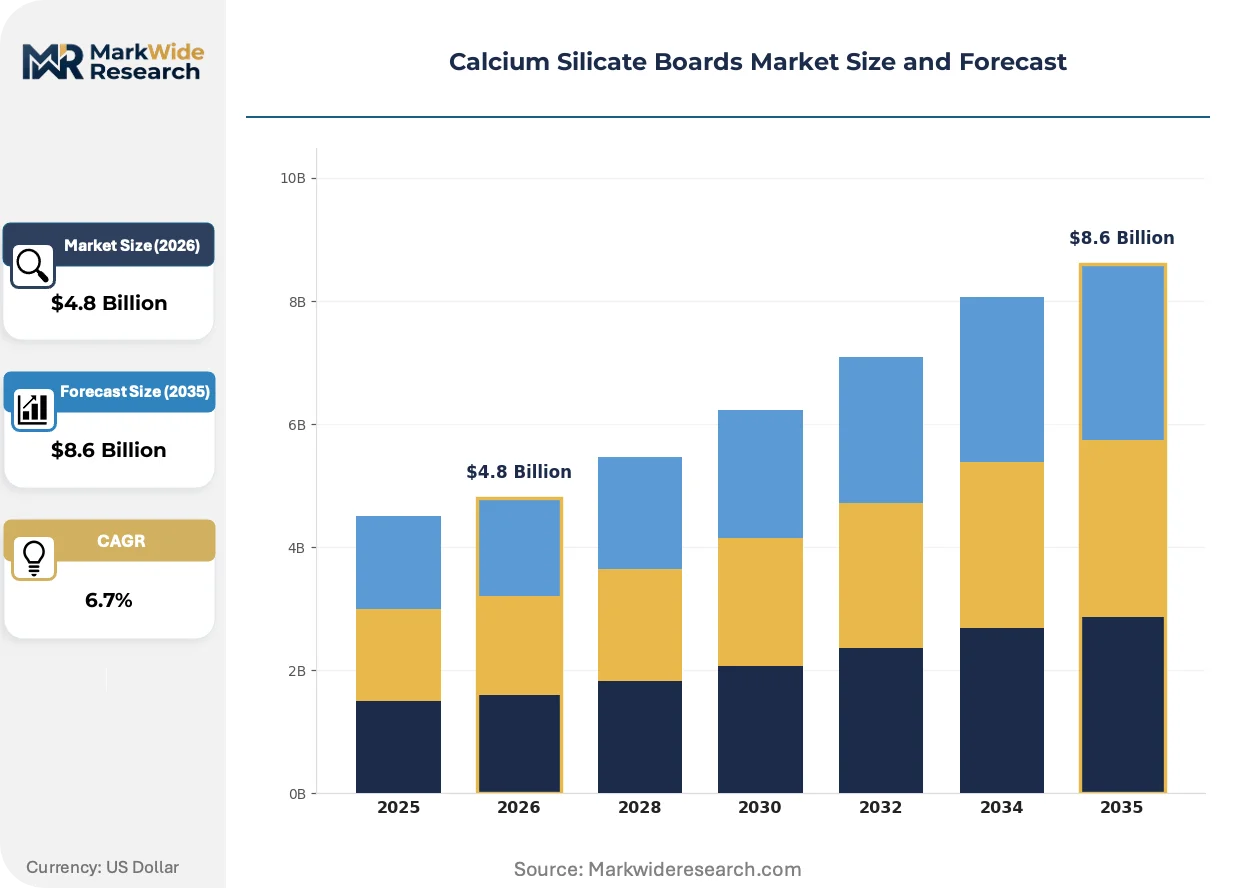
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Resistant Boards, Moisture-Resistant Boards, Thermal Insulation Boards, Acoustical Boards End User: Commercial Buildings, Industrial Applications, Residential Buildings, Infrastructure Projects Application: Exterior Wall Sheathing, Interior Partitions, Ceiling Applications, Fireproofing Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | USG Corporation, Everest Industries Limited, Promat International NV, Tianjin North Fine Ceramics, Qingdao Kangde Xin Composite Material, Saint-Gobain SA, Morgan Advanced Materials, Changzhou Sinofiber New Material, Owens Corning Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Silicate Boards Market Strategic Shifts
Specification digitization and regulatory carbon accounting are compressing traditional material selection cycles while elevating performance-verified systems over commodity alternatives.
Low-density microporous calcium silicate formulations are displacing conventional dense boards in steam pipe and turbine insulation applications where thermal efficiency targets have tightened. Industrial facility engineers in European power generation sites specify these materials to reduce heat loss and envelope mass. The shift is displacing legacy mineral wool wraps in continuous-service environments above 650°C.
REACH authorization procedures and EU Green Deal embodied carbon disclosure mandates now govern construction material imports into Europe. Manufacturers must document additive compositions and lifecycle emissions to maintain market access. Fire-Resistant Boards face the steepest compliance burden given their fiber reinforcement content and high-rise application liability exposure.
Facility managers now consolidate procurement authority through engineered specifications rather than delegating to general contractors. This concentration compresses vendor qualification to pre-approved product lists and captive testing protocols. Petrochemical site operators in the US Gulf Coast and North Sea clusters drive this pattern most aggressively.
Calcium Silicate Boards Market Segmentation
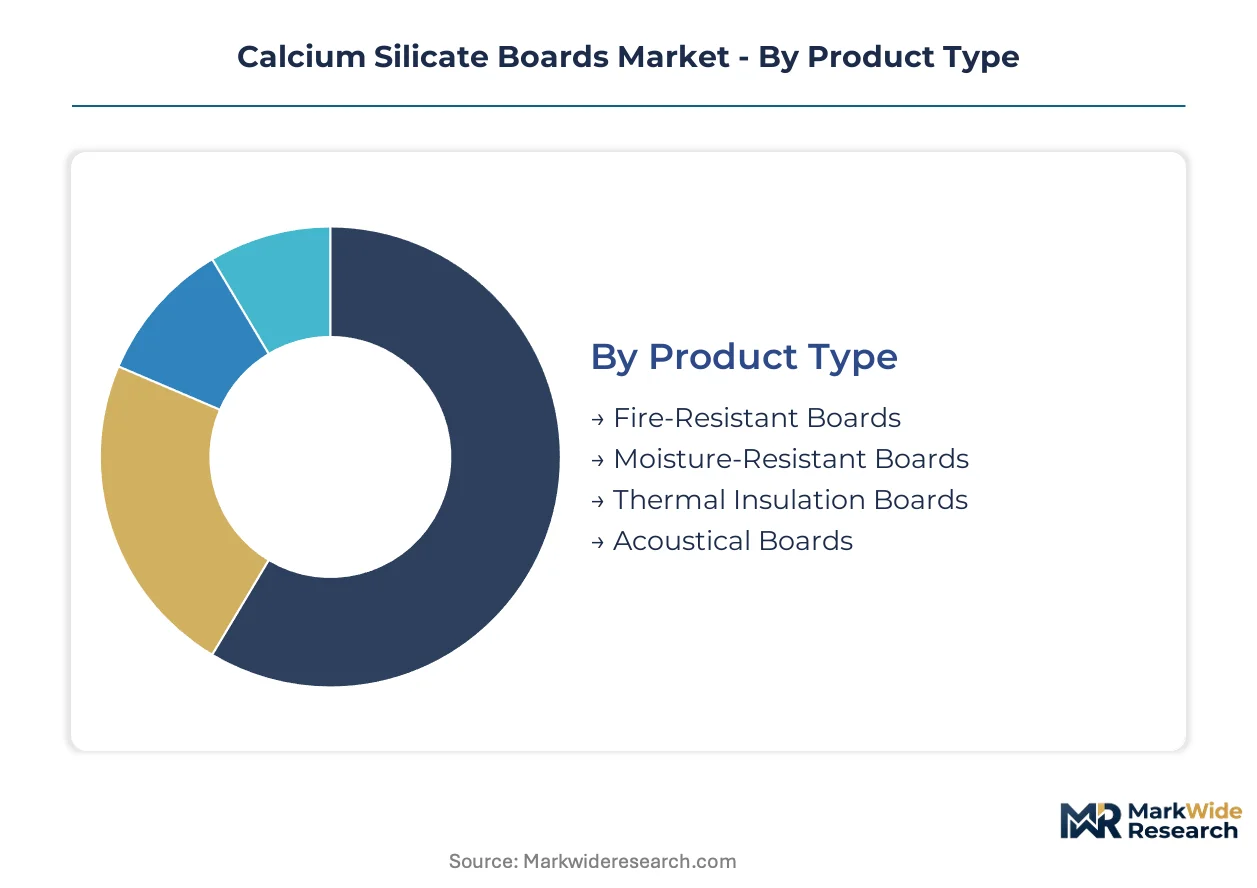
Calcium silicate board manufacturers align product portfolios against distinct performance specifications and procurement channels. Segmentation reveals where technical differentiation commands premium positioning versus commodity competition.
Product Type:
Margin pools concentrate in formulations requiring specialized curing protocols and extended fire-rating certifications.
- Fire-Resistant Boards:Dense autoclaved panels reinforced with selected mineral fibers achieve multi-hour fire ratings mandated in high-rise structural protection. Facility managers in Chinese infrastructure projects and European tunnel systems specify these boards where passive fire protection carries liability exposure. REACH authorization procedures and GB standards enforcement elevate compliance costs that filter weaker suppliers.
- Thermal Insulation Boards:Lower-density microporous formulations target steam pipe and turbine envelope applications where heat loss reduction drives operational savings. US Gulf Coast petrochemical operators and North Sea power generation sites specify these materials to displace legacy mineral wool above 650°C service conditions. IRA tax credits for building envelope upgrades accelerate retrofit demand.
- Moisture-Resistant Boards:Hydrophobic surface treatments and modified pore structures withstand hydrothermal cycling in marine and food processing environments.
- Acoustical Boards:Engineered porosity and density gradients deliver sound attenuation in commercial interior fit-outs where fire-rated ceiling assemblies are required.
The dominant share belongs to Fire-Resistant Boards, while Thermal Insulation Boards are gaining share fastest.
End User:
Procurement authority patterns diverge sharply between owner-operated facilities and speculative construction.
- Industrial Applications:Petrochemical refineries and power generation sites consolidate specification authority through captive engineering teams and pre-approved vendor lists. Process safety budgets expand across US OSHA-regulated facilities and EU Seveso III sites where fire containment failures carry catastrophic liability. Facility managers demand metallurgical partnership credentials and project-specific testing protocols.
- Infrastructure Projects:Government-funded tunnel, transit, and utility construction in China and selected European corridors specify calcium silicate systems for combined fire and thermal performance. MIIT industrial policy directives and EU Green Deal procurement rules favor documented embodied carbon performance.
- Commercial Buildings:Developer-driven high-rise construction specifies fire-rated envelope systems where code minimums drive material selection.
- Residential Buildings:Multi-family mid-rise construction adopts calcium silicate sheathing where local amendments restrict combustible exterior claddings.
Industrial Applications capture the deepest margin pools, though Infrastructure Projects show the steepest expansion trajectory.
Application:
Installation complexity and code inspection intensity determine where specialized labor commands premium pricing.
- Fireproofing:Structural steel encasement and penetration sealing require tested assembly listings from NFPA or EN protocols. US high-rise construction and European tunnel infrastructure mandate these applications with third-party witnessed installation. Divergent certification timelines between jurisdictions fragment vendor qualification.
- Exterior Wall Sheathing:Continuous insulation and fire-resistive barrier integration faces accelerated wind-load and moisture-management testing. Coastal US jurisdictions and Northern European climates specify these assemblies where hydrothermal cycling degrades conventional alternatives.
- Interior Partitions:Fire-rated shaft walls and corridor separations specify standard-density boards where hourly ratings govern selection.
- Ceiling Applications:Acoustical tile substrates and fire-resistive ceiling membranes compete with mineral fiber alternatives on installed cost.
Fireproofing maintains the largest volume position, while Exterior Wall Sheathing is climbing the fastest.
Distribution Channel:
Channel economics reflect specification complexity and project scale fragmentation.
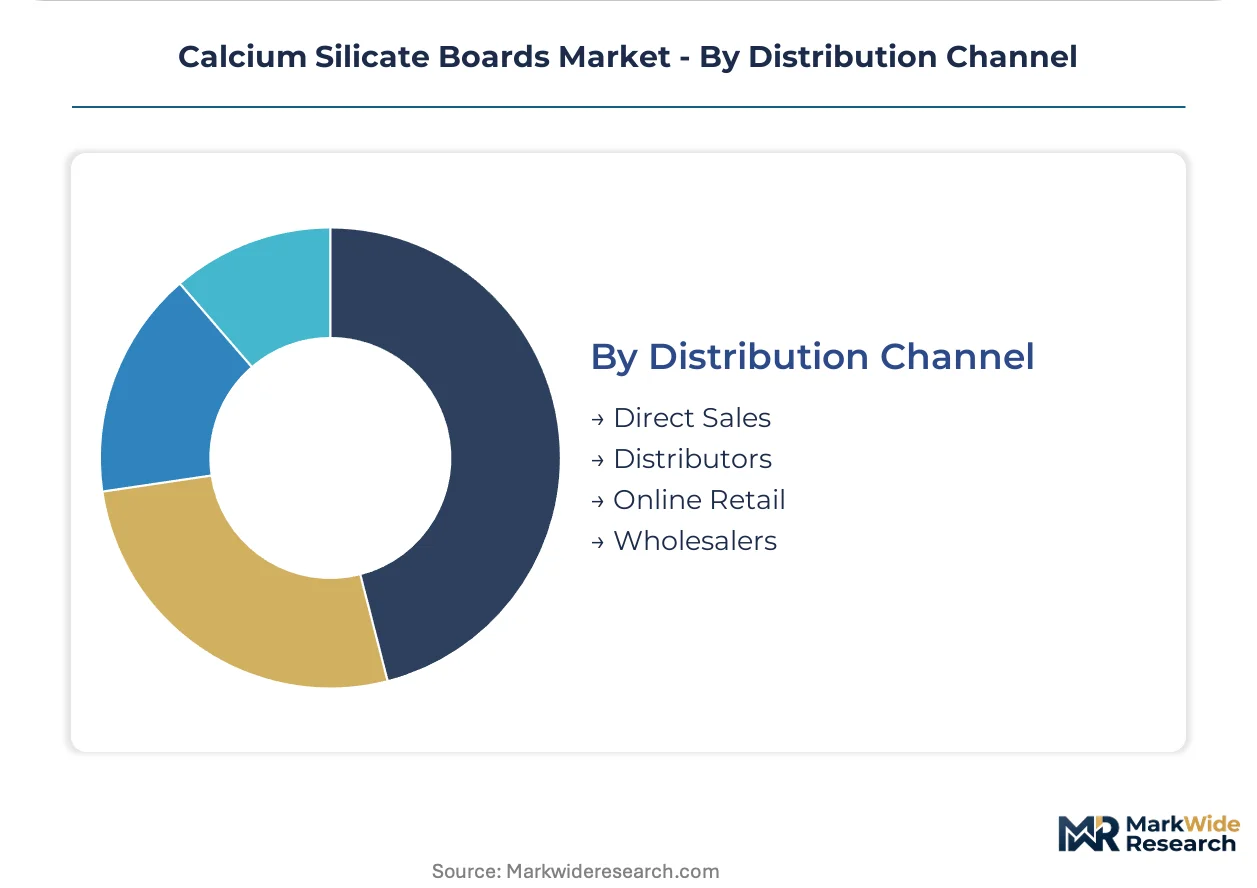
- Direct Sales:Large industrial accounts and infrastructure contractors negotiate frame agreements with manufacturers for volume pricing and dedicated technical support. Promat International NV and Saint-Gobain SA deploy direct sales teams for petrochemical and power generation specifications where captive testing protocols lock out distributors.
- Distributors:Regional construction supply houses stock standard fire-rated boards for commercial contractor spot purchasing. Tianjin North Fine Ceramics leverages domestic Chinese distribution density for infrastructure project penetration.
- Wholesalers:Bulk volume aggregation serves mid-size contractors with less stringent technical support requirements.
- Online Retail:Limited to small-format boards and accessory products where specification authority is delegated to installation contractors.
Direct Sales commands the highest margin contribution, though Distributors handle the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export calcium silicate boards to European retrofit markets and Gulf petrochemical sites, creating a trade-flow corridor that concentrates supply-side leverage in Tianjin and Qingdao while demand fragments across multiple regulatory jurisdictions.
United States
OSHA process safety mandates and IRA tax credits for building envelope upgrades drive specification of thermal insulation boards. The EPA enforces emissions standards for fiber reinforcement content. Gulf Coast petrochemical clusters in Texas and Louisiana consolidate procurement authority through captive engineering teams.
China
MIIT industrial policy directives and GB standards enforcement favor domestic manufacturers in high-temperature process equipment applications. The dual carbon goals program tightens energy efficiency benchmarks for construction materials. Yangtze River Delta infrastructure buildout concentrates demand in Shanghai-Nanjing corridor tunnel systems.
Germany
REACH authorization procedures and EU Green Deal embodied carbon disclosure requirements govern construction material imports. The ECHA restricts hazardous additives in fiber-reinforced formulations. Ruhr industrial belt power generation sites specify low-density microporous boards for steam pipe insulation above 650°C.
United Kingdom
Seveso III site safety regulations and building safety post-Grenfell amendments tighten passive fire protection specifications. The HSE enforces workplace exposure limits during board installation. London high-rise construction and Crossrail tunnel infrastructure mandate multi-hour fire-rated structural protection.
Saudi Arabia
SABIC petrochemical expansion and NEOM giga-project construction create demand for moisture-resistant boards in coastal environments. The Saudi Standards, Metrology and Quality Organization adopts fire-test protocols aligned with NFPA and EN harmonization efforts. Eastern Province industrial cities specify rigid non-combustible panels for refining site fire containment.
Calcium Silicate Boards Market Competitive Environment
Player mix skews toward integrated material conglomerates and specialized fire-protection fabricators. The structure concentrates around three to four vertically positioned suppliers with captive testing protocols and metallurgical partnerships. Two strategic archetypes dominate: multinational building-material platforms with cross-selling capabilities, and regional kiln-technology specialists with raw material integration. Capacity expansion and strategic partnerships constitute the primary competitive moves, as qualification timelines for fire-rated systems create sticky specification relationships.
Within the multinational platform tier, Saint-Gobain SA and Promat International NV exemplify archetypes leveraging gypsum-to-insulation and captive fire-testing capabilities respectively. Among China-based fabricators, Tianjin North Fine Ceramics occupies a position reflecting integrated raw material sourcing and domestic infrastructure scale. These three entities anchor the competitive structure across distinct geographic and specification vectors.
| Leading Market Players |
|---|
| USG Corporation |
| Everest Industries Limited |
| Promat International NV |
| Tianjin North Fine Ceramics |
| Qingdao Kangde Xin Composite Material |
| Saint-Gobain SA |
| Morgan Advanced Materials |
| Changzhou Sinofiber New Material |
| Owens Corning Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Chinese kiln operators and Gulf Coast petrochemical facility managers lock in autoclave capacity access while stabilizing lime and silica feedstock pricing visibility across volatile energy markets. These contracts compress spot market liquidity for non-integrated buyers and anchor premium positioning for REACH-certified formulations serving European retrofit pipelines.
Pricing Analysis
Current-generation dense autoclaved boards command substantial premiums over prior-generation mineral-fiber composites in fireproofing applications above 800°C, while next-generation microporous formulations target steam pipe insulation with value-based pricing tied to operational heat-loss savings. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant European imports from domestic Chinese GB-standard production and unbranded regional supply. Cost compression in economy-grade thermal insulation is intensifying because mineral wool substitution threatens specification share in sub-650°C service conditions. Commercial building developers exhibit the highest price sensitivity, whereas petrochemical facility managers prioritize metallurgical partnership credentials over unit cost.
Supply Chain Analysis
Port congestion at Tianjin and Qingdao container terminals elevates inbound logistics costs for European buyers sourcing calcium silicate boards from Yangtze River Delta manufacturing clusters. Production gravity centers on China, Germany, and the United States, with kiln technology leadership concentrated in Tianjin and autoclave curing expertise anchored in the Ruhr industrial belt. Raw material dependencies rest on high-purity silica sand, quicklime from cement industry offshoots, and selected mineral fiber reinforcements subject to EPA emissions scrutiny. Single-source vulnerability from Chinese integrated raw material sourcing creates geographic concentration risk for non-domestic procurement. Distribution runs through direct sales teams for industrial accounts and regional construction supply houses for commercial contractor spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive fire-testing protocol expertise represents the scarcest capability in this market, separating qualified specification holders from commodity suppliers vulnerable to REACH authorization delays and NFPA-EN certification divergence.
For Market Incumbents: Shield specification relationships through metallurgical partnership investments with SABIC and US Gulf Coast petrochemical operators while accelerating captive testing protocol expansion to lock out distributor-dependent challengers. Prioritize backward integration into lime calcination capacity to offset energy-intensive autoclave curing cost volatility. Mineral wool substitution in sub-800°C thermal insulation applications demands defensive R&D into hybrid formulations that preserve fire-rating performance at lower density. For New Entrants and Emerging Players: UL/EN fast-track certification programs for fire-resistant board assemblies offer the most penetrable entry path for challengers lacking legacy metallurgical partnerships. Target moisture-resistant board specifications in Saudi coastal environments and European marine retrofit pipelines where hydrothermal cycling resistance commands premium positioning unclaimed by incumbent mineral wool suppliers. Lead with BIM-integrated material libraries to streamline architect selection workflows and bypass entrenched direct sales channels. For Investors and Strategic Acquirers: Regional kiln-technology specialists with integrated raw material sourcing and dormant GB-to-REACH certification pathways present the most compelling acquisition target archetype for platform consolidation plays. Long-term viability hinges on positioning for post-2030 embodied carbon disclosure mandates tightening across EU Green Deal procurement rules and China's dual carbon goals program. Watch for NFPA-EN fire-test protocol harmonization announcements as the critical inflection signal that would compress cross-border vendor qualification timelines and unlock trapped value in multi-certified manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lime Calcination | Captive quicklime supply from cement industry offshoots insulates autoclave operators from energy cost volatility. |
| REACH Certification Fast-Track Investment | Pre-authorized additive documentation accelerates European market access before ECHA restriction expansion. |
| BIM-Integrated Specification Platform Launch | Digital material libraries compress architect selection cycles and displace distributor-dependent incumbent channels. |
| Moisture-Resistant Formulation Scale-Up | Hydrophobic surface treatments capture marine and food processing specifications where mineral wool degrades. |
| Metallurgical Partnership Expansion | Project-specific testing protocols with SABIC and US Gulf operators create sticky specification relationships. |
Study Parameters
Operator-level perspectives from petrochemical facility managers, power generation maintenance directors, construction procurement leads, and fire-protection engineering consultants anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from customs trade data, SEC 10-K filings of listed building materials conglomerates, MIIT industrial policy directives, and ECHA REACH authorization databases. Bottom-up volume estimates from autoclave capacity utilization across Chinese kiln clusters triangulated against top-down demand projections from infrastructure buildout pipelines and petrochemical expansion schedules.
Sensitivity analysis across feedstock cost scenarios, regulatory timeline variations, and substitution elasticity parameters shaped the projection framework. Segmentation dimensions modeled include product density tier, fire-rating certification level, end-use industry vertical, and regional regulatory cluster across the analysis window. CAGRs derived from installed base replacement cycles, code amendment adoption curves, and energy efficiency incentive program trajectories. Industry-specific forecast inputs incorporated OSHA process safety mandate enforcement intensity and EU Green Deal embodied carbon disclosure implementation pace.
Decision-makers should treat outputs as directional under base assumptions of continued NFPA-EN protocol divergence and sustained Chinese domestic manufacturing scale; material deviation would warrant model refresh. Specific risks that could revise projections include sudden REACH authorization expansion to additional fiber reinforcements, rapid mineral wool formulation advancement threatening calcium silicate thermal efficiency positioning, or unexpected Sino-Gulf trade flow disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramics Market
Ceramics
Quartz Powder Market
Ceramics
Mullite Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Clay Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Cerium Nitride Market
Ceramics
Calcium Silicate Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
High Temperature Ceramics Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Titanium Carbide Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Ceramic Lining Market