
 Ceramic and Natural Stone Tiles Market | 2026-2036
Ceramic and Natural Stone Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic and Natural Stone Tiles Market Intelligence
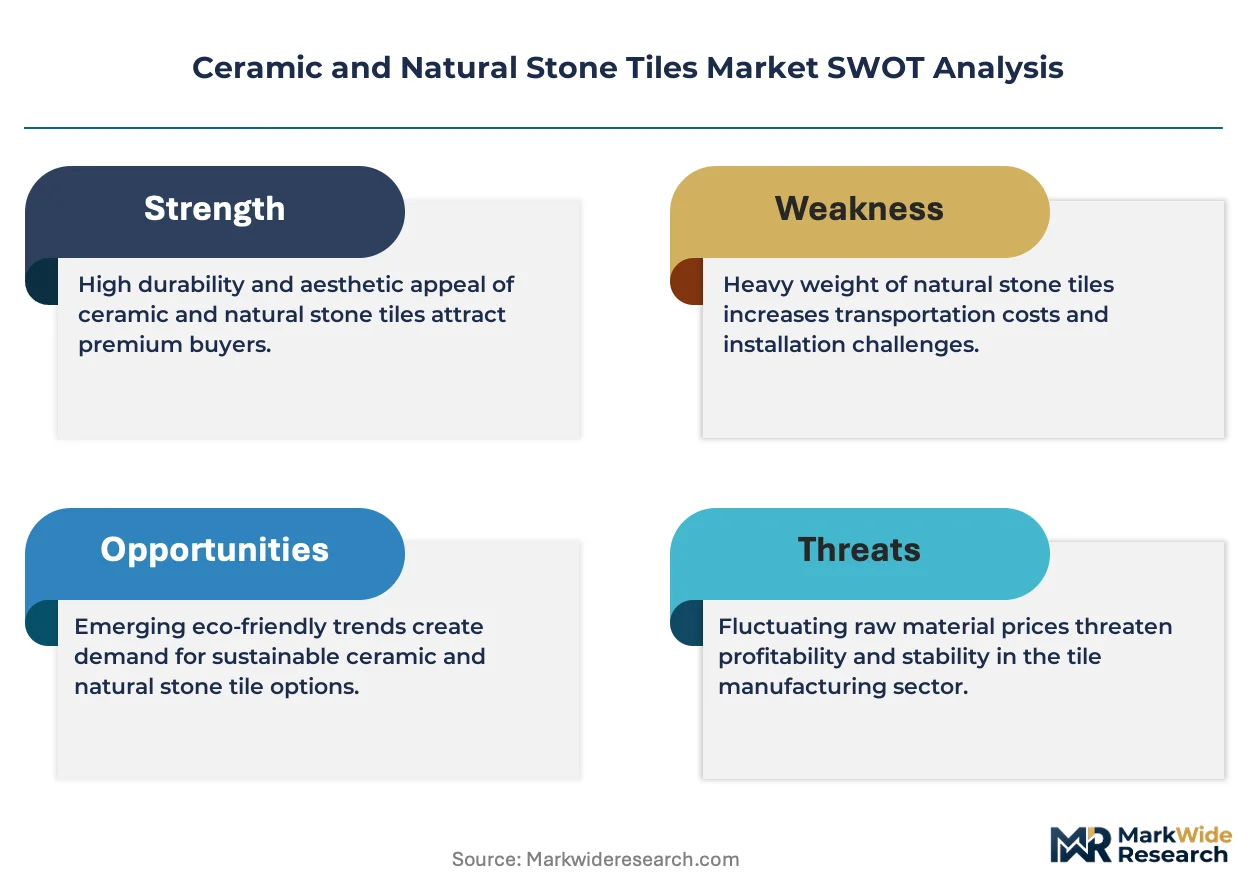
Large-format porcelain is shifting competitive economics away from traditional ceramic in high-traffic commercial specifications. Mohawk Industries leverages captive raw-material sourcing across North American shale deposits to sustain margin stability. Panariagroup Industrie Ceramiche S.p.A. anchors Mediterranean design positioning through controlled distribution in European premium retail channels. Kajaria Ceramics Limited dominates India's organized tile sector via manufacturing scale at its Gujarat and Andhra Pradesh plants.
Ceramic and natural stone tiles are fired-clay or quarried-mineral surfacing materials, typically specified by water-absorption rates below 0.5 percent for porcelain grades and by Mohs hardness ratings for natural stone durability in commercial wear applications. Their primary purpose spans protective-decorative flooring, vertical cladding, and wet-area surfacing across built environments. Porcelain tiles command the dominant value share within product type segmentation due to through-body color consistency and frost resistance specifications that penetrate exterior applications. Wall cladding represents the fastest-expanding application segment as architects specify thin-profile large panels for vertical surfaces in commercial towers across Middle Eastern and Asian developments.
ISO 13006 ceramic classification standards, ECHA REACH substance restrictions on glaze formulations, and India's BIS 15622 product certification collectively shape material compliance costs and cross-border market access for tile manufacturers. The EU Green Deal's embodied-carbon tracking requirements are forcing European importers to document quarry-to-site emissions for natural stone sourcing. Stakeholders must monitor evolving regulatory divergence between Asian production hubs and European consumption markets when configuring supply chain and certification investments.
Market Dynamics
The market is reconfiguring around embodied-carbon accountability, with the EU Green Deal's quarry-to-site emissions documentation forcing importers to reconstruct natural stone supply chains or pivot toward lower-carbon porcelain alternatives.
Growth Catalysts
- Southeast Asian Residential Construction:Vietnam's urban corridor from Ho Chi Minh City to Da Nang is channeling investment into high-rise housing stock, accelerating specification of glazed ceramic for wet-area surfacing.
- BIS 15622 Certification Mandates:India's quality thresholds are consolidating the organized sector, pushing unorganized manufacturers toward compliance investment or exit.
- Thin-Profile Large Panels:Architects in Middle Eastern commercial towers are specifying porcelain slabs for vertical cladding, expanding addressable square footage per project.
Market Restraints
- Natural Gas Cost Volatility:Firing energy represents 25-35% of ceramic production cost, exposing margins to European and Asian spot-price fluctuations.
- Quarry Concentration Risk:Premium marble and travertine deposits cluster in specific Mediterranean and Middle Eastern extraction zones, creating single-source vulnerability.
- ECHA REACH Glaze Restrictions:Heavy-metal limits on traditional lead-based formulations are forcing reformulation R&D without immediate cost pass-through mechanisms.
Strategic Opportunities
- India's Organized Sector Consolidation:BIS enforcement is creating acquisition targets among sub-scale Gujarat and Rajasthan producers lacking certification infrastructure.
- Digital Inkjet Decoration Convergence:Combination of high-resolution printing with through-body porcelain is enabling natural-stone visual replication at lower embodied carbon.
- Direct-to-Project Distribution:Large-format logistics complexity is opening bypass channels for manufacturers with captive fleet capacity to serve commercial developers directly.
Industry Challenges
- ISO 13006 Testing Bottlenecks:Certification backlogs at accredited laboratories are extending product launch timelines by 4-8 months for export-focused manufacturers.
- Legacy Kiln Retrofit Requirements:Transitioning from batch to continuous roller-kiln technology demands capital deployment that mid-tier producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic and Natural Stone Tiles Market |
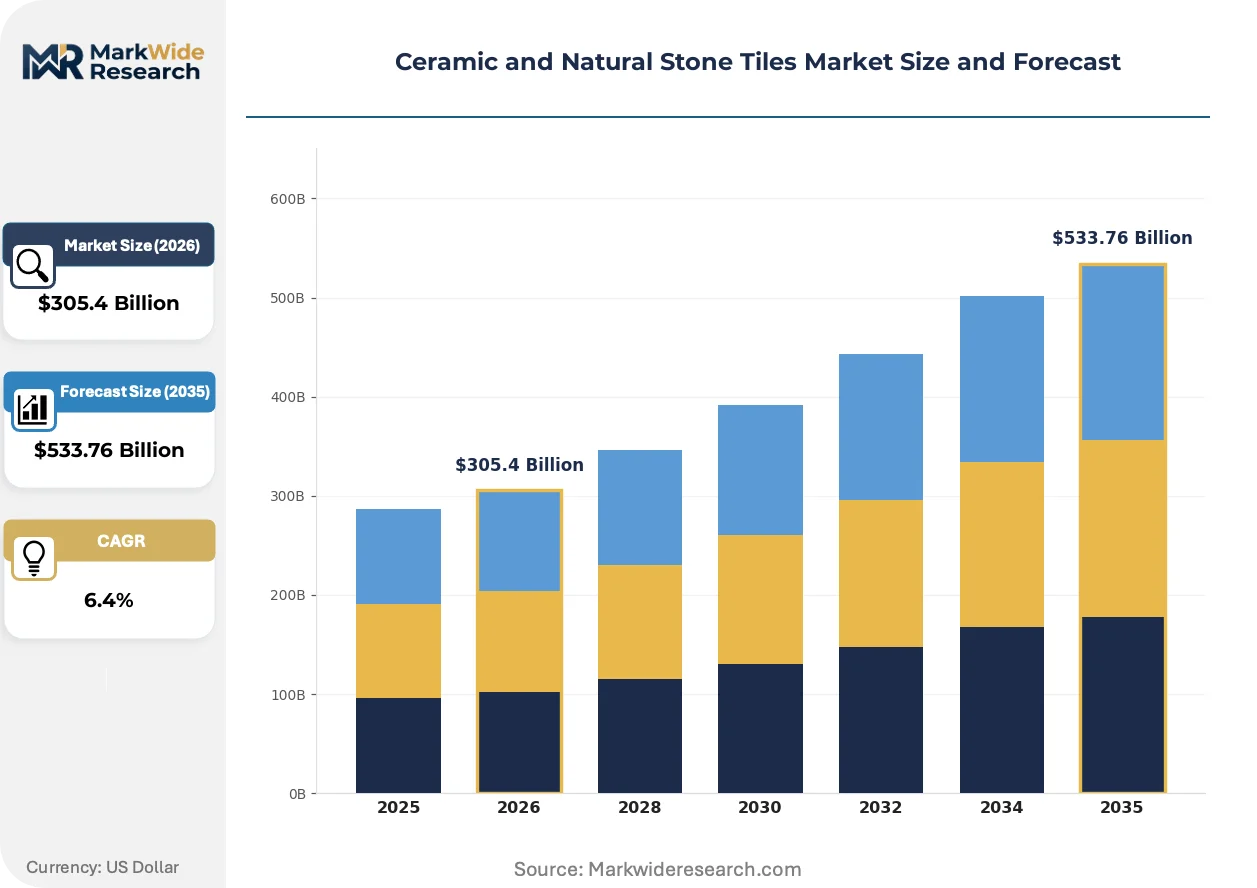
| Market Size in 2026 | $305.4 Billion |
| Market Size in 2035 | $533.76 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tiles, Porcelain Tiles, Natural Stone Tiles, Mosaic Tiles End Use: Residential, Commercial, Institutional, Industrial Application: Flooring, Wall Cladding, Countertops, Backsplashes Shape: Square, Rectangular, Hexagonal, Random |
| Companies Covered | Polycor, Panariagroup Industrie Ceramiche S.p.A, Mohawk Industries, Daltile, Levantina Group, Emser Tile, Marazzi USA, Kajaria Ceramics Limited, Stonepeak Ceramics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic and Natural Stone Tiles Market Strategic Shifts & Innovations
Digital decoration technology and carbon-accounting infrastructure are converging to redefine product differentiation, compressing the premium attached to quarried stone while elevating performance-certified porcelain.
Full-body digital inkjet systems are absorbing the decorative function previously reserved for natural stone, applying mineral-oxide suspensions that penetrate porcelain bodies to simulate veining depth. Hotel and retail developers in Dubai and Riyadh are specifying these surfaces for lobbies and atriums at volumes that now match natural marble procurement. The technology is absorbing market share from quarried travertine in commercial specifications where frost resistance and stain immunity outweigh authenticity signaling.
REACH substance restrictions on glaze formulations are compelling European manufacturers to eliminate lead and cadmium-based fluxes from traditional recipes. Industrial consequence includes higher firing temperatures and reformulated engobes that increase energy consumption per square meter. Italian and Spanish producers are responding by consolidating glaze R&D into shared technical centers to distribute compliance cost across cooperative networks.
Architect specification behavior is rotating toward performance-certified product categories, with LEED and BREEAM point eligibility now filtering tile selection before aesthetic review. Distributors in Germany and France are reorganizing showrooms around certification badges rather than origin narratives, compressing the traditional country-of-origin premium for Italian marble. This pattern is most visible in Nordic public-sector procurement, where municipal tender documents now mandate EPD disclosure as a pass-fail criterion.
Ceramic and Natural Stone Tiles Market Segmentation
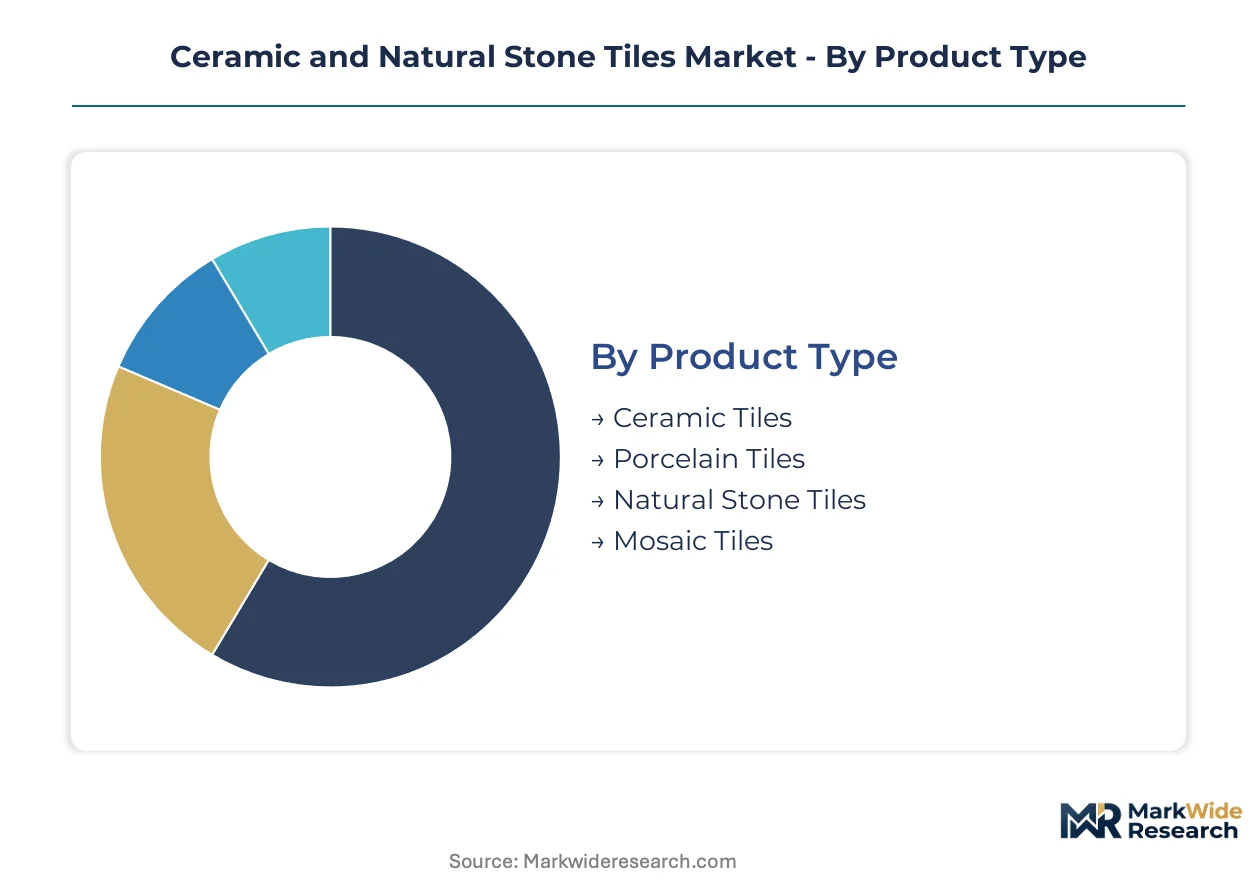
Tile specification behavior splits sharply between embedded surfacing systems and standalone aesthetic statements. Understanding these integration patterns reveals where margin pools concentrate and which manufacturing capabilities command premium positioning.
Product Type:
Integration depth varies dramatically: porcelain functions as structural skin in high-performance envelopes, while mosaic remains decorative overlay requiring secondary substrate support.
- Porcelain Tiles:Through-body color consistency and sub-0.5% water absorption enable frost-resistant exterior cladding without protective sealants. Demand concentrates in Vietnam's Ho Chi Minh City to Da Nang corridor where high-rise residential towers specify large-format panels for wet-area surfacing and balcony soffits. BIS 15622 certification mandates in India are consolidating procurement toward ISO 13006-compliant producers with captive testing infrastructure.
- Natural Stone Tiles:Quarried travertine and marble carry embodied-carbon documentation burdens under EU Green Deal quarry-to-site tracking requirements. German and French distributors now reorganize showrooms around EPD disclosure badges rather than Italian origin narratives, compressing traditional country-of-origin premiums.
- Ceramic Tiles:Glazed earthenware dominates Southeast Asian residential wet-area specification at accessible price points.
- Mosaic Tiles:Small-format tesserae persist in luxury hospitality bathroom accents and swimming pool waterline courses.
Porcelain leads volumes today; natural stone is losing share fastest to digitally replicated alternatives.
End Use:
Cost tier stratification separates specification authority: commercial developers wield capital-project budgets while residential selection fragments across individual homeowners.
- Commercial:Hotel and retail developers in Dubai and Riyadh specify full-body digital inkjet porcelain for lobbies and atriums at volumes matching former natural marble procurement. LEED and BREEAM point eligibility now filters tile selection before aesthetic review in Nordic public-sector tendering.
- Residential:India's organized sector consolidation under BIS enforcement channels investment toward Kajaria-scale Gujarat and Andhra Pradesh manufacturing plants. Natural gas cost volatility at 25-35% of production cost exposes margin stability to spot-price fluctuations.
- Institutional:Municipal procurement in Germany mandates EPD disclosure as pass-fail criterion, favoring performance-certified categories.
- Industrial:Heavy-traffic manufacturing floors specify Mohs hardness-rated surfaces with chemical resistance priorities.
Commercial commands premium pricing today; residential is expanding most quickly across Southeast Asian urban corridors.
Application:
Surface orientation determines technical specification: horizontal wear resistance versus vertical anchorage engineering and gravity load calculations.
- Wall Cladding:Thin-profile large panels for vertical surfaces in Middle Eastern commercial towers represent the steepest expansion trajectory. Architects specify porcelain slabs expanding addressable square footage per project while reducing grout-line visual interruption.
- Flooring:High-traffic commercial specifications rotate toward large-format porcelain as competitive economics displace traditional ceramic. Mohawk Industries leverages captive North American shale deposit sourcing to sustain margin stability against energy cost volatility.
- Countertops:Kitchen work surfaces demand stain immunity and thermal shock resistance from through-body materials.
- Backsplashes:Wet-area protection behind cooking and washing zones favors glazed ceramic for cost-efficient moisture barriers.
Wall cladding is climbing the fastest; flooring retains the largest installed base.
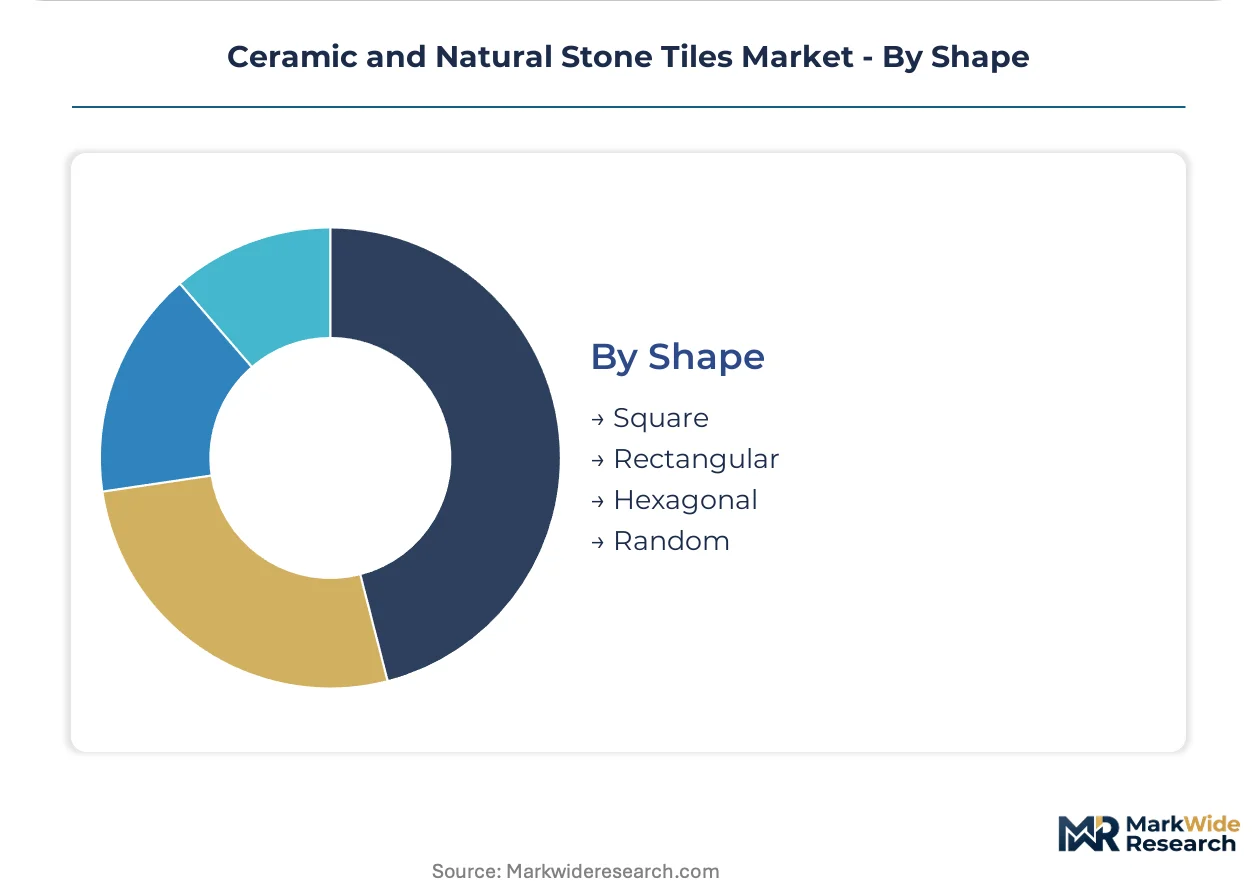
Shape:
Manufacturing process complexity and cutting waste ratios separate standardized rectilinear production from custom polygonal fabrication.
- Rectangular:Large-format planks dominate contemporary commercial specification with minimized joint lines and accelerated installation coverage rates.
- Square:Traditional modular dimensions persist in residential replacement cycles and heritage restoration matching.
- Hexagonal:Geometric tessellation patterns command design premiums in boutique hospitality and retail interiors.
- Random:Irregular flagstone layouts replicate quarried stone aesthetics for exterior hardscaping applications.
Rectangular formats dominate current specification; hexagonal shapes are gaining share fastest in premium design segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ho Chi Minh City to Da Nang corridor channels Southeast Asia's steepest residential construction acceleration, with glazed ceramic specifications dominating high-rise wet-area surfacing and balcony soffits.
United States
Commercial tower developments in Dallas and Miami specify large-format porcelain for lobby and atrium applications at volumes rivaling former natural stone procurement. EPA emissions tracking under evolving state-level building codes pressures importers toward documented supply chain transparency. Mohawk Industries leverages captive shale deposit sourcing across Tennessee and Kentucky to insulate margin stability against natural gas volatility.
India
Organized sector consolidation accelerates under BIS 15622 certification mandates, channeling procurement toward ISO 13006-compliant producers with captive testing infrastructure. The Bureau of Indian Standards tightens quality thresholds for ceramic wall and floor tiles, pushing sub-scale Gujarat and Rajasthan manufacturers toward compliance investment or exit. Kajaria Ceramics Limited anchors manufacturing scale at plants in Gujarat and Andhra Pradesh, consolidating distribution across the organized sector.
Germany
Municipal tender documents now mandate EPD disclosure as pass-fail criterion, favoring performance-certified porcelain categories over traditional country-of-origin narratives. ECHA REACH substance restrictions on glaze formulations compel elimination of lead and cadmium-based fluxes, increasing firing energy consumption per square meter. Distributors in Frankfurt and Munich reorganize showrooms around certification badges rather than Italian marble provenance.
Italy
Full-body digital inkjet systems absorb decorative functions previously reserved for quarried travertine, penetrating commercial specifications where frost resistance outweighs authenticity signaling. EU Green Deal quarry-to-site emissions documentation forces natural stone importers toward supply chain reconstruction or pivot toward lower-carbon porcelain alternatives. Sassuolo industrial district producers consolidate glaze R&D into shared technical centers to distribute compliance cost across cooperative networks.
Saudi Arabia
Hotel and retail developers in Riyadh and Jeddah specify digitally replicated marble surfaces for luxury hospitality interiors at procurement volumes matching former natural stone. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for ceramic products align with ISO 13006 classification standards, streamlining import certification for Gulf Cooperation Council market access. King Abdullah Economic City construction clusters accelerate specification of thin-profile large panels for vertical cladding in commercial towers.
Ceramic and Natural Stone Tiles Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and distribution reach, producing a tiered structure where captive raw-material sourcing separates margin-stable leaders from energy-exposed followers. Three archetypes dominate: integrated shale-to-slab producers controlling upstream mineral deposits; design-positioned Mediterranean specialists anchoring premium retail channels; and organized-sector consolidators leveraging compliance infrastructure to absorb unorganized competitor share. Competitive moves concentrate on kiln technology retrofit partnerships and direct-to-project logistics investments that bypass traditional distributor markups.
Among North American integrated producers, Mohawk Industries exemplifies the shale-captive archetype through in-house mineral sourcing. Panariagroup Industrie Ceramiche S.p.A. occupies a position within the Mediterranean design-specialist tier, while Kajaria Ceramics Limited represents the organized-sector consolidator model in South Asian markets. These three anchors illustrate how divergent strategic foundations—upstream resource control, aesthetic positioning, and regulatory compliance scale—generate differentiated competitive trajectories without converging on identical capability sets.
| Leading Market Players |
|---|
| Polycor |
| Panariagroup Industrie Ceramiche S.p.A |
| Mohawk Industries |
| Daltile |
| Levantina Group |
| Emser Tile |
| Marazzi USA |
| Kajaria Ceramics Limited |
| Stonepeak Ceramics Inc. |
| Others |
Cost & Logistics Intelligence
Natural gas futures at European and Asian trading hubs cascade through kiln-firing economics to stratify tile pricing across premium ISO 13006-certified porcelain, standard glazed ceramic, and unorganized-sector economy grades. This input-cost architecture concentrates margin stability with producers holding captive mineral deposits or long-term fuel hedging, while exposing spot-market buyers to volatile energy pass-through.
Pricing Analysis
Input-cost pass-through operates asymmetrically across the value chain, with BIS 15622 certification and ISO 13006 compliance emerging as price differentiation drivers that separate organized-sector premiums from unorganized competition. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with project-based contract pricing dominating commercial specifications. Cost compression in economy-grade glazed ceramic is intensifying because natural gas spot volatility at 25-35% of production cost lacks hedging mechanisms for mid-tier producers. Residential replacement cycles in Southeast Asia exhibit highest price sensitivity, while Middle Eastern commercial developers prioritize performance certification over unit cost.
Supply Chain Analysis
Freight cost escalation on large-format porcelain slabs from Sassuolo industrial district to Middle Eastern project sites is restructuring procurement geography toward regional manufacturing hubs. Supply concentrates in Italy, Spain, India, and Vietnam, with raw material dependencies on North American shale deposits for kaolin, Mediterranean limestone for engobes, and zirconium silicate for opacifiers. Single-source vulnerability clusters around premium marble and travertine extraction zones in specific Mediterranean and Middle Eastern quarry sites. Distribution runs through project-direct channels for commercial towers, bypassing traditional distributor markups where manufacturers deploy captive fleet capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on digital inkjet decoration convergence compressing natural stone premiums, alongside BIS enforcement in India consolidating procurement toward compliant producers with testing infrastructure scale.
For Market Incumbents: Acquire sub-scale Gujarat and Rajasthan ceramic manufacturers lacking BIS 15622 certification infrastructure to absorb organized-sector consolidation benefits. Secure captive mineral sourcing across North American shale deposits or Indian feldspar belts to insulate margin stability against natural gas volatility. Defend against digitally replicated marble substitutes by anchoring Mediterranean design positioning through controlled European premium retail channels. For New Entrants and Emerging Players: Capture Vietnam's Ho Chi Minh City to Da Nang urban corridor residential construction acceleration with glazed ceramic wet-area specifications at accessible price points. Target India's unorganized sector exiters with compliance-as-a-service partnerships or toll-manufacturing arrangements leveraging existing kiln capacity. Deploy direct-to-project distribution for large-format logistics complexity, bypassing traditional distributor markups to commercial developers. For Investors and Strategic Acquirers: Asymmetric upside sits with organized-sector consolidators possessing captive BIS testing infrastructure and ISO 13006 certification backlogs. Long-term viability over the projection horizon favors producers with backward integration into raw material deposits and digital decoration technology scale. Watch for EPD disclosure mandates spreading beyond German municipal procurement as the inflection signal for embodied-carbon accountability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Deposits | Mohawk Industries leverages captive North American shale sourcing to sustain margin stability against energy volatility. |
| Digital Inkjet Decoration Scale-Up | Full-body mineral-oxide suspension systems absorb decorative function from quarried travertine in Dubai and Riyadh commercial specifications. |
| BIS 15622 Certification Infrastructure Investment | Kajaria Ceramics consolidates Indian organized sector procurement through captive testing labs at Gujarat and Andhra Pradesh plants. |
| Direct-to-Project Distribution Channel | Large-format logistics complexity opens bypass channels for manufacturers with captive fleet capacity serving Middle Eastern commercial developers. |
| Shared Technical Center Consolidation | Italian and Spanish producers distribute REACH glaze reformulation R&D costs across cooperative networks to manage compliance investment. |
Research Approach
Direct dialogue with ceramic plant managers, procurement leads at commercial developers, distribution channel partners, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from BIS certification databases, ECHA REACH substance restriction filings, EU Green Deal embodied-carbon tracking disclosures, and customs/trade data on tile import flows. Bottom-up and top-down triangulation cross-referenced production capacity surveys with end-use demand modeling across residential, commercial, and institutional segments.
Bottom-up volume and value outputs reflect facility-level capacity utilization, product mix shifts, and regional pricing differentials across the analysis window. Segmentation dimensions modeled include product type (porcelain, natural stone, ceramic, mosaic), end-use sector, application orientation, and shape format, with ISO 13006 compliance tier as an industry-specific overlay. CAGRs were derived from trend extrapolation of construction activity indices, regulatory enforcement timelines, and technology adoption curves for digital decoration systems.
Natural gas price volatility, BIS enforcement pace variations, and EPD mandate geographic expansion are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect assumptions about kiln technology retrofit rates, certification backlog resolution, and trade flow reconfiguration under evolving emissions documentation requirements. Stakeholders should weight assumptions against their own operating context and hedging capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Lithium Zirconate Market
Ceramics
Global Ceramic Balls Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Mullite Market
Ceramics
Ceramic Proppant Market
Ceramics
Global Barium Carbonate Market
Ceramics
Global Ceramic Foams Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Methyl Silicate Market
Ceramics
Ceramic Lining Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Optical Ceramics Market
Ceramics
Strontium Carbonate Market
Ceramics
Spain Ceramic Tiles Market