
 Nanoceramic Powder Market | 2026-2036
Nanoceramic Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoceramic Powder Market Foresight
The capital-intensity divergence between integrated oxide producers and specialty powder converters is collapsing as furnace-scale requirements for sub-100 nanometer control rise. Saint-Gobain leverages captive fused alumina assets to anchor European supply for abrasive and refractory grades. Tosoh Corporation sustains leadership in high-purity zirconia through proprietary hydrothermal synthesis routes. Nanophase Technologies Corporation competes on precision precipitation methods for non-oxide ceramic precursors.
Nanoceramic powder comprises inorganic, non-metallic particulate matter with crystallite dimensions typically below 100 nanometers, produced via sol-gel, hydrothermal, or flame spray pyrolysis methods to achieve controlled surface area, phase purity, and sintering reactivity. These powders serve as feedstock for dense ceramic components, thermal barrier coatings, and electronic substrates where conventional micron-scale materials fail on strength, dielectric performance, or biocompatibility. Alumina powder occupies the largest volume position across structural and electrical applications, while zirconia commands premium pricing in dental and biomedical segments due to transformation-toughening properties. Titania powder represents the fastest-growing category, propelled by photocatalytic coating demand and solid-oxide fuel cell electrode development.
EPA emissions guidelines and OSHA respirable crystalline silica limits in the United States shape workplace exposure controls and wet-process migration among domestic producers. REACH registration requirements and the EU Green Deal industrial emissions framework in Europe mandate detailed substance characterization and carbon footprint disclosure for imported ceramic powders. The analysis indicates stakeholders must monitor evolving purity certifications from semiconductor fabs and battery cell makers, as these end users tighten particulate contamination thresholds faster than regulatory minimums.
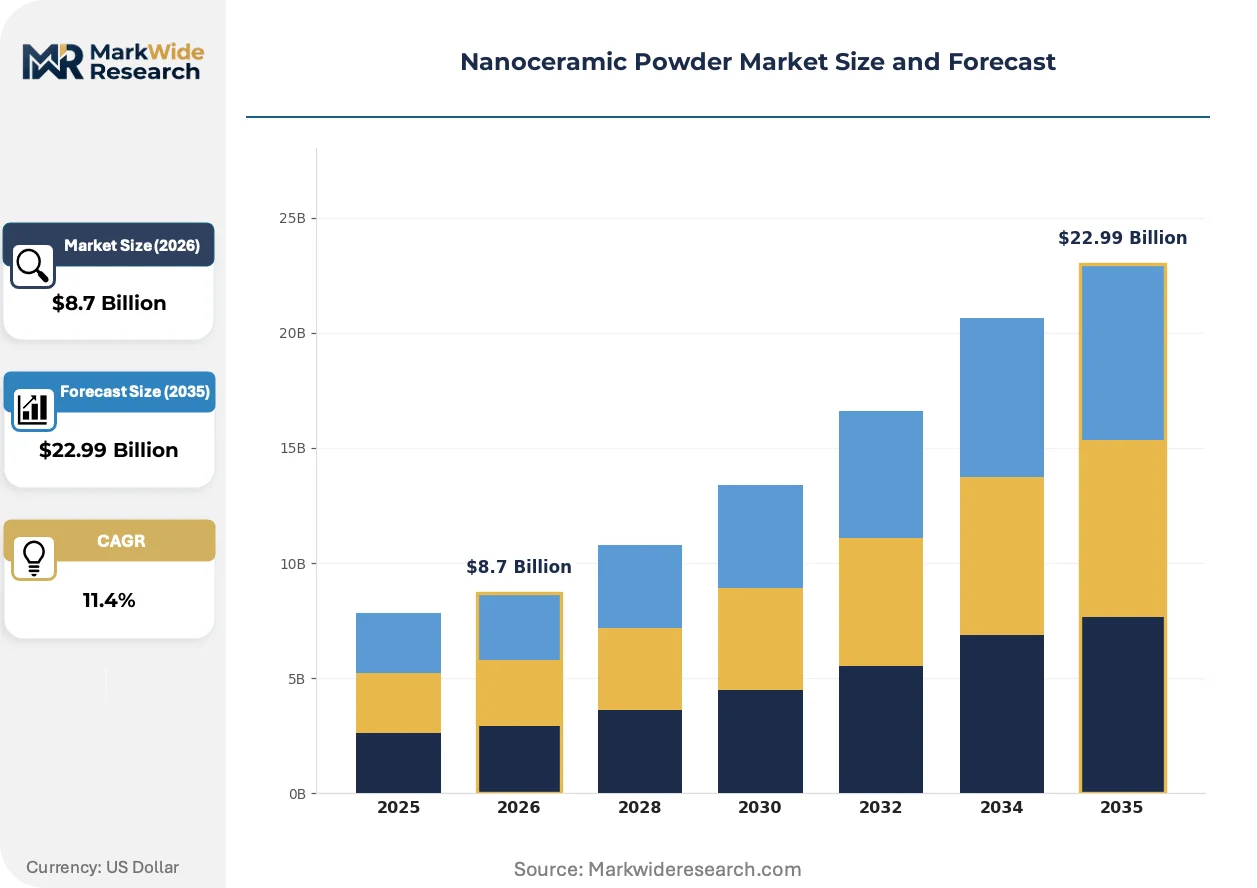
Market Dynamics
Sub-100 nanometer furnace control requirements are collapsing the historical capital-intensity gap between integrated oxide producers and specialty powder converters, forcing consolidation across the supply chain.
Growth Catalysts
- Solid-oxide fuel cell electrode development:Titania powder demand from energy storage manufacturers in Germany and Japan is accelerating as grid-scale battery deployment expands.
- Semiconductor packaging investments:China's domestic fab construction is driving alumina procurement for thermal interface materials and ceramic substrates.
- REACH substance characterization mandates:European importers must now disclose carbon footprints and purity benchmarks, favoring certified suppliers with established hydrothermal synthesis capabilities.
Market Restraints
- Energy input cost volatility:Natural gas and electricity price swings in Germany directly impact plasma spray and flame pyrolysis operating economics.
- Chinese supply concentration:Over 60% of high-purity zirconia precursor refining occurs in Shandong and Jiangsu provinces, creating single-source vulnerability.
- Respirable crystalline silica exposure limits:OSHA's tightened workplace standards in the United States are forcing wet-process migration and capital retooling among legacy dry-milling operations.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic cell manufacturing incentives are opening battery ceramic separator demand for imported nanoceramic feedstock.
- Photocatalytic building coatings:Titania-enabled self-cleaning facades represent underpenetrated construction sector demand in Mediterranean climate zones.
- AI-assisted particle size distribution control:Machine learning convergence with hydrothermal reactor monitoring is enabling real-time quality optimization previously unavailable at commercial scale.
Industry Challenges
- PhD-level materials synthesis talent scarcity:Sol-gel and precipitation process engineering expertise concentrates in Japanese and German research institutes, limiting workforce expansion elsewhere.
- Semiconductor fab contamination threshold acceleration:TSMC and Samsung are tightening particulate specifications faster than ISO 14644-1 cleanroom standards evolve, forcing supplier recertification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoceramic Powder Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Zirconia, Titania, Others Application: Aerospace, Electronics, Medical, Automotive End User: Manufacturers, Research Institutions, Healthcare Providers, Defense Form: Powder, Coating, Composite, Granulate |
| Companies Covered | Saint-Gobain, Tosoh Corporation, Nanophase Technologies Corporation, 3M Company, Kyocera Corporation, CeramTec GmbH, CoorsTek Inc., Resonac Corporation, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoceramic Powder Market Shifts & Advancements
Plasma-enabled synthesis routes and digital quality control systems are compressing batch-to-batch variation while regulatory disclosure requirements reshape competitive positioning across the value chain.
Flame spray pyrolysis with in-line laser diffraction monitoring is displacing conventional sol-gel methods for alumina and titania production in high-volume electronics applications. Korean multilayer ceramic capacitor manufacturers have adopted these systems at scale since 2022. The technology is displacing batch-process incumbents who cannot match throughput consistency for sub-50 nanometer distributions.
REACH registration requirements and the EU Green Deal industrial emissions framework now mandate substance-level carbon footprint disclosure for all imported ceramic powders entering European customs territories. German and French customs authorities are enforcing these provisions through enhanced import documentation checks. Battery cell makers sourcing zirconia and alumina precursors are accelerating supplier audits to preempt compliance delays.
Direct long-term contracting between semiconductor packaging houses and specialty powder converters is fragmenting traditional distributor channels in East Asia. Samsung and SK Hynix now negotiate three-year supply agreements specifying particle morphology and surface chemistry rather than purchasing through regional trading houses. This pattern is most visible in South Korea's Gyeonggi-do cluster, where fab proximity drives just-in-time inventory models.
Nanoceramic Powder Market Segmentation
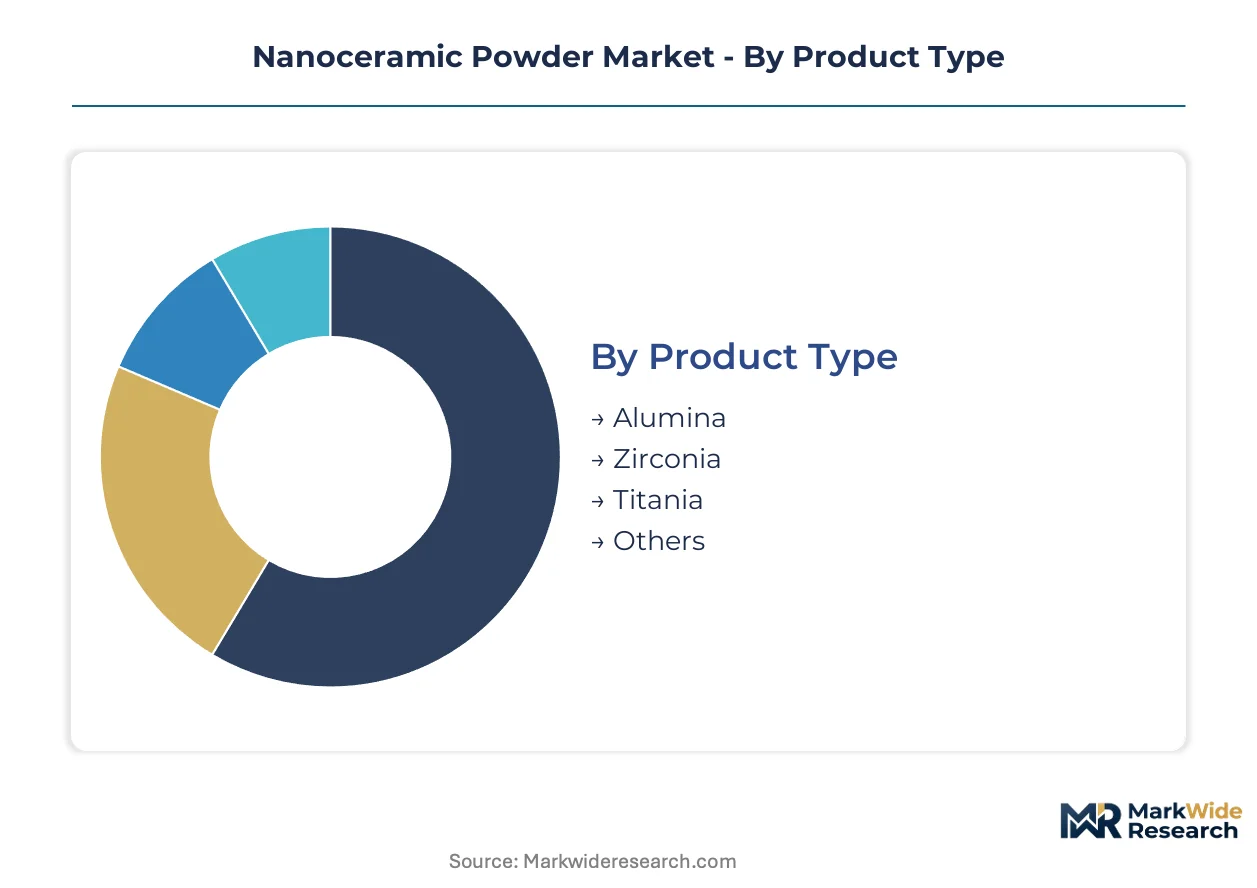
Segmentation in nanoceramic powders reveals how technical specifications, regulatory exposure, and end-use certification requirements fragment procurement patterns across supply chains. Buyers in semiconductor packaging, solid-oxide fuel cells, and biomedical implant manufacturing operate under incompatible purity and documentation standards.
Product Type:
Domestic consumption in China and Japan absorbs the majority of alumina and titania volumes, while European and North American buyers drive zirconia imports for dental and biomedical applications.
- Alumina:Alpha-phase aluminum oxide powders with sub-100 nanometer crystallite dimensions serve as feedstock for multilayer ceramic capacitors and thermal interface substrates. Procurement concentrates in China's Yangtze River Delta for domestic semiconductor packaging expansion, constrained by EPA respirable crystalline silica limits forcing wet-process migration among legacy suppliers.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal achieves transformation toughening for dental crowns and hip implants. European demand from German and French dental laboratories outpaces domestic precursor refining capacity in Shandong province, creating import dependency for high-purity hydrothermal grades.
- Titania:Anatase-phase titanium dioxide powders with engineered surface area enable photocatalytic self-cleaning coatings and solid-oxide fuel cell electrodes.
- Others:Silica carbide and boron nitride precursors address niche thermal management and abrasive applications with limited commercial scale.
Alumina commands the established base. The steepest expansion runs through titania.
Application:
Cost tier stratification separates aerospace and medical segments with qualification-heavy procurement from electronics buyers prioritizing throughput consistency.
- Electronics:Multilayer ceramic capacitor manufacturers in South Korea's Gyeonggi-do cluster specify particle morphology and surface chemistry in direct three-year supply agreements, bypassing traditional distributor channels. REACH carbon footprint disclosure mandates favor certified hydrothermal synthesis suppliers.
- Medical:Dental restoration and orthopedic implant fabricators require ISO 13485 quality management and biocompatibility testing documentation. German dental laboratories drive premium pricing for transformation-toughening zirconia grades.
- Aerospace:Thermal barrier coating applications demand plasma spray-compatible powder flowability and phase stability.
- Automotive:Catalytic converter washcoat and sensor substrate applications compete on cost with established micron-scale ceramic suppliers.
Electronics anchors volume procurement. Medical delivers margin expansion through certification barriers.
End User:
Volume concentration sits with integrated manufacturers, while research institutions and defense buyers fragment demand across small-batch specialty grades.
- Manufacturers:Samsung, SK Hynix, and domestic Chinese packaging houses negotiate direct long-term contracts specifying sub-50 nanometer particle distributions. Flame spray pyrolysis with in-line laser diffraction monitoring displaces batch-process incumbents who cannot match throughput consistency.
- Healthcare Providers:Hospital procurement of dental and orthopedic ceramics flows through specialized distributors requiring MDR compliance documentation in European markets.
- Research Institutions:National laboratories and university materials science departments drive demand for non-oxide ceramic precursors and custom precipitation methods.
- Defense:Armor and thermal protection applications require ITAR-controlled supply chains with limited supplier pools.
Manufacturers absorb production scale. Healthcare providers impose the steepest documentation burden.
Form:
Supply chain configuration separates powder feedstock commoditization from value-added coating and composite integration services.
- Powder:Dry and slurry formulations for sintering, thermal spray, and powder metallurgy feedstock dominate volume shipments. OSHA workplace exposure controls favor wet-process slurry migration in United States facilities.
- Coating:Pre-dispersed suspensions for dip-coating and spray deposition eliminate customer-side formulation risk. Korean multilayer ceramic capacitor manufacturers adopted these systems at scale since 2022.
- Composite:Polymer-matrix and metal-matrix nanoceramic blends address thermal management and wear resistance in automotive underhood applications.
- Granulate:Spray-dried agglomerates with controlled porosity for pressing and extrusion operations serve structural ceramic fabricators.
Powder forms the volume foundation. Coating integration is climbing fastest as electronics manufacturers outsource formulation risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb volume at price-sensitive terms for semiconductor packaging feedstock, while German dental laboratories and South Korean electronics manufacturers accept steep premiums for certified hydrothermal grades and sub-50 nanometer specifications.
China
Domestic fab construction in the Yangtze River Delta and Pearl River Delta drives alumina procurement for thermal interface materials and ceramic substrates. MEE enforcement of dual carbon goals tightens emissions benchmarks for precursor refining operations. Shandong and Jiangsu provinces concentrate over 60% of high-purity zirconia precursor capacity, creating single-source vulnerability for European importers.
United States
OSHA respirable crystalline silica limits force wet-process migration among legacy dry-milling operations in Ohio and Pennsylvania industrial corridors. EPA emissions guidelines shape workplace exposure controls and solvent-use restrictions across domestic production. Greater Boston and Pacific Northwest research clusters demand non-oxide ceramic precursors for defense and national laboratory applications under ITAR-controlled supply chains.
Germany
REACH registration requirements and EU Green Deal industrial emissions frameworks mandate carbon footprint disclosure for imported ceramic powders entering Hamburg and Bremerhaven customs territories. Natural gas price volatility directly impacts plasma spray and flame pyrolysis economics at Ruhr Valley production sites. Bavarian dental laboratories drive premium pricing for transformation-toughening zirconia grades exceeding domestic precursor refining capacity.
South Korea
Samsung and SK Hynix negotiate direct three-year supply agreements specifying particle morphology and surface chemistry, bypassing traditional distributor channels. MFDS alignment with MDR documentation requirements shapes biocompatibility certification for medical-grade imports. The Gyeonggi-do cluster anchors just-in-time inventory models where fab proximity eliminates buffer stock tolerance.
India
PLI scheme incentives for domestic cell manufacturing open battery ceramic separator demand for imported nanoceramic feedstock. BIS purity benchmarks lag semiconductor fab requirements, forcing reliance on certified foreign suppliers for electronics applications. Gujarat and Maharashtra industrial corridors concentrate pilot-scale precipitation capacity unable to match East Asian throughput consistency.
Nanoceramic Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with hydrothermal synthesis specialists commanding premium positioning against scale-driven fused oxide producers. The market structure consolidates around three tiers: integrated mining-to-powder conglomerates with captive raw material positions, mid-cap specialists with proprietary reactor designs, and regional toll processors serving commodity grades. Strategic moves center on backward integration into precursor refining and forward integration into pre-dispersed coating formulations.
Within the technology-specialist tier, Tosoh Corporation and Nanophase Technologies Corporation exemplify divergent synthesis approaches—hydrothermal routes versus precision precipitation methods—each anchoring distinct certification pathways for semiconductor and biomedical end users. Saint-Gobain occupies a scale-driven position leveraging captive fused alumina assets across European abrasive and refractory supply chains. CeramTec GmbH and CoorsTek Inc. represent integrated fabricators with in-house powder conversion and dense ceramic component manufacturing, capturing margin across multiple value chain stages.
| Leading Market Players |
|---|
| Saint-Gobain |
| Tosoh Corporation |
| Nanophase Technologies Corporation |
| 3M Company |
| Kyocera Corporation |
| CeramTec GmbH |
| CoorsTek Inc. |
| Resonac Corporation |
| Sumitomo Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Flame spray pyrolysis displacement of legacy sol-gel methods simultaneously relocates production gravity toward South Korean electronics clusters and compresses price premiums for sub-50 nanometer alumina and titania grades. This substitution dynamic collapses the historical margin buffer enjoyed by European batch-process incumbents while amplifying volume leverage for East Asian toll processors.
Pricing Analysis
After-sales revenue from technical service contracts and particle morphology customization drives lifetime value for hydrothermal synthesis specialists. Three-tier pricing structure across premium, standard, and economy levels separates certified semiconductor-grade zirconia from industrial abrasive alumina and commodity refractory feedstock. Cost compression in standard-tier alumina is intensifying because Chinese Yangtze River Delta producers are expanding furnace capacity. Electronics manufacturers in Gyeonggi-do exhibit the least price sensitivity due to fab proximity requirements, while Indian battery ceramic separator buyers under PLI scheme constraints face acute cost pressure.
Supply Chain Analysis
Just-in-time inventory models dominate South Korea's Gyeonggi-do cluster where Samsung and SK Hynix maintain zero buffer stock tolerance, contrasting with European dental laboratories that strategic-stockpile yttria-stabilized zirconia to hedge Shandong province supply interruptions. Raw material dependencies center on high-purity zirconium oxychloride, aluminum hydroxide, and titanium tetrachloride feedstocks. Single-source vulnerability concentrates in Jiangsu province precursor refining for transformation-toughening zirconia grades. Distribution runs through direct long-term contracts fragmenting traditional regional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where AI-assisted particle size distribution control systems are creating interoperability standards between hydrothermal reactor monitoring and semiconductor fab quality management platforms.
For Market Incumbents: Secure backward integration into high-purity precursor refining to defend against Chinese supply concentration vulnerability. Lock in three-year direct contracting with Samsung and SK Hynix before flame spray pyrolysis toll processors capture Gyeonggi-do cluster share. Prioritize REACH carbon footprint certification investment to preempt German customs documentation enforcement. For New Entrants and Emerging Players: Differentiate on photocatalytic building coating formulations for Mediterranean climate zone construction sectors where titania-enabled self-cleaning facades remain underpenetrated. Target India's PLI scheme battery ceramic separator demand where BIS purity benchmark gaps force reliance on certified foreign suppliers. Pursue pre-dispersed coating suspension partnerships with Korean multilayer ceramic capacitor manufacturers seeking formulation risk outsourcing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap hydrothermal synthesis specialists in Japan and Germany holding proprietary reactor designs but lacking scale for semiconductor fab qualification. Long-term viability hinges on five-to-ten year fab construction cycles in China and India sustaining alumina procurement expansion. Watch for TSMC and Samsung contamination threshold acceleration crossing supplier recertification cost barriers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Captures margin from Shandong province zirconium oxychloride concentration and reduces REACH disclosure risk. |
| AI-Assisted Reactor Monitoring Deployment | Enables real-time particle size distribution control matching Samsung sub-50 nanometer specifications. |
| Long-term Supply Agreement with Fab Proximity | Locks in Gyeonggi-do just-in-time inventory commitment bypassing distributor channel fragmentation. |
| Pre-dispersed Coating Formulation Launch | Eliminates customer-side formulation risk for Korean multilayer ceramic capacitor manufacturers. |
| REACH Carbon Footprint Certification Investment | Preempts Hamburg and Bremerhaven customs enforcement delays for European zirconia imports. |
Research Methodology
Cross-validation between primary interviews with hydrothermal synthesis plant managers, semiconductor packaging procurement leads, German dental laboratory technical directors, and Indian battery cell manufacturing executives anchors the qualitative findings. Secondary validation draws from customs trade data, SEC 10-K filings of listed specialty chemical producers, ECHA REACH registration databases, and Korean MFDS biocompatibility certification records. Bottom-up volume estimates from individual furnace capacity and top-down demand segmentation from end-use application analysis were triangulated to constrain forecast variance.
Sensitivity analysis across natural gas price volatility scenarios, OSHA respirable crystalline silica compliance cost assumptions, and Chinese dual carbon goal enforcement intensity shapes the analytical framework. Segmentation dimensions modeled include powder type, application sector, end-user category, and geographic production hub across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating semiconductor fab construction pipelines and solid-oxide fuel cell electrode development trajectories. Plasma spray economics and hydrothermal reactor yield rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA emissions guidelines, REACH substance characterization mandates, and OSHA workplace exposure standards; material policy shifts would require re-modeling. Revision becomes warranted when Chinese MEE enforcement of dual carbon goals crosses thresholds forcing Shandong province precursor refining capacity reductions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Methyl Silicate Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
US Kaolin Market
Ceramics
Calcined Alumina Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Graphite Crucibles Market
Ceramics
Lithium Silicate Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
North America Barium Carbonate Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Japan Ceramic Tiles Market