
 Earthenware Market | 2026-2036
Earthenware Market Size, Share, and Industry Trends Forecast 2026-2036
Earthenware Market Analysis
The EU Green Deal is repositioning earthenware demand toward low-carbon kiln technologies and certified non-toxic glazes across European tableware procurement. Shanxi Xianglong Black Pottery Handicraft Co., Ltd leverages ancestral firing methods to sustain premium positioning in heritage ceramics. Poterie Lorraine anchors French artisanal output through controlled regional appellation practices. Yixing Wankun dominates the purple clay teaware segment with deep geographic lock-in around Yixing city.
Earthenware denotes porous, low-fire ceramic ware fired below 1,150°C, composed primarily of natural clay with fluxing agents that yield water-absorbent bodies suited to decorative and culinary vessels. Its primary commercial purpose spans functional table service, horticultural containers, and ornamental objects where thermal shock resistance matters less than aesthetic character. Terra cotta garden applications lead volume due to established landscaping demand, while porcelain commands the highest unit margins in specialty retail channels. Kitchenware competes most intensely as direct-to-consumer brands and craft stores split the end-user base.
REACH and RoHS frameworks in Europe constrain heavy-metal migration from colored glazes, compelling reformulation across export-oriented kilns. China's GB standards and SAMR oversight enforce parallel domestic safety benchmarks that shape product access for both local and foreign producers. Stakeholders must monitor evolving dual carbon compliance timelines and glaze chemistry substitution costs to preserve margin structures.
Market Dynamics
REACH compliance deadlines are forcing wholesale glaze reformulation across export-oriented kilns, compressing margins for producers dependent on legacy lead-based colorants while opening certification premiums for early movers.
Growth Catalysts
- Boutique hospitality procurement:Independent restaurants and small hotel chains are sourcing handmade kitchenware directly from artisan clusters, bypassing traditional wholesale distributors and building transparent supply relationships.
- EU Green Deal kiln incentives:Subsidies for low-carbon firing technologies are accelerating electric and biomass kiln adoption among European producers seeking carbon footprint certification for tableware exports.
- Shandong-Jiangsu cluster density:Concentrated raw material access and specialized labor pools in these Chinese provinces sustain cost-competitive production for volume gardenware and decorative segments.
Market Restraints
- Flux mineral price volatility:Feldspar and nepheline syenite costs fluctuate with construction-grade ceramic demand, squeezing input budgets for mid-tier producers without long-term mining contracts.
- Single-source glaze chemistry dependency:Reformulation to meet REACH and RoHS limits has consolidated supplier relationships around a handful of certified compounders, creating bottleneck risk.
- Porcelain substitution in premium tableware:Vitrified ceramics command higher unit margins in specialty retail, diverting investment from earthenware capacity expansion.
Strategic Opportunities
- Heritage tourism channel development:Direct-to-visitor sales at firing sites in France's Lorraine region and China's Yixing city capture margin otherwise lost to retail intermediaries.
- Carbon-neutral certification premium tier:Third-party verified low-emission production protocols command price premiums from sustainability-focused procurement officers in Northern European food service.
- Biophilic design integration:Unglazed terra cotta vessels for indoor plant cultivation are penetrating urban residential markets through home décor specialty retailers.
Industry Challenges
- Master craftsperson succession gaps:Traditional throwing and firing expertise concentrated among aging practitioners in heritage-producing regions threatens quality consistency for premium positioning.
- Dual certification timeline compression:Simultaneous compliance with EU REACH and China's SAMR GB standards requires parallel testing protocols that strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthenware Market |
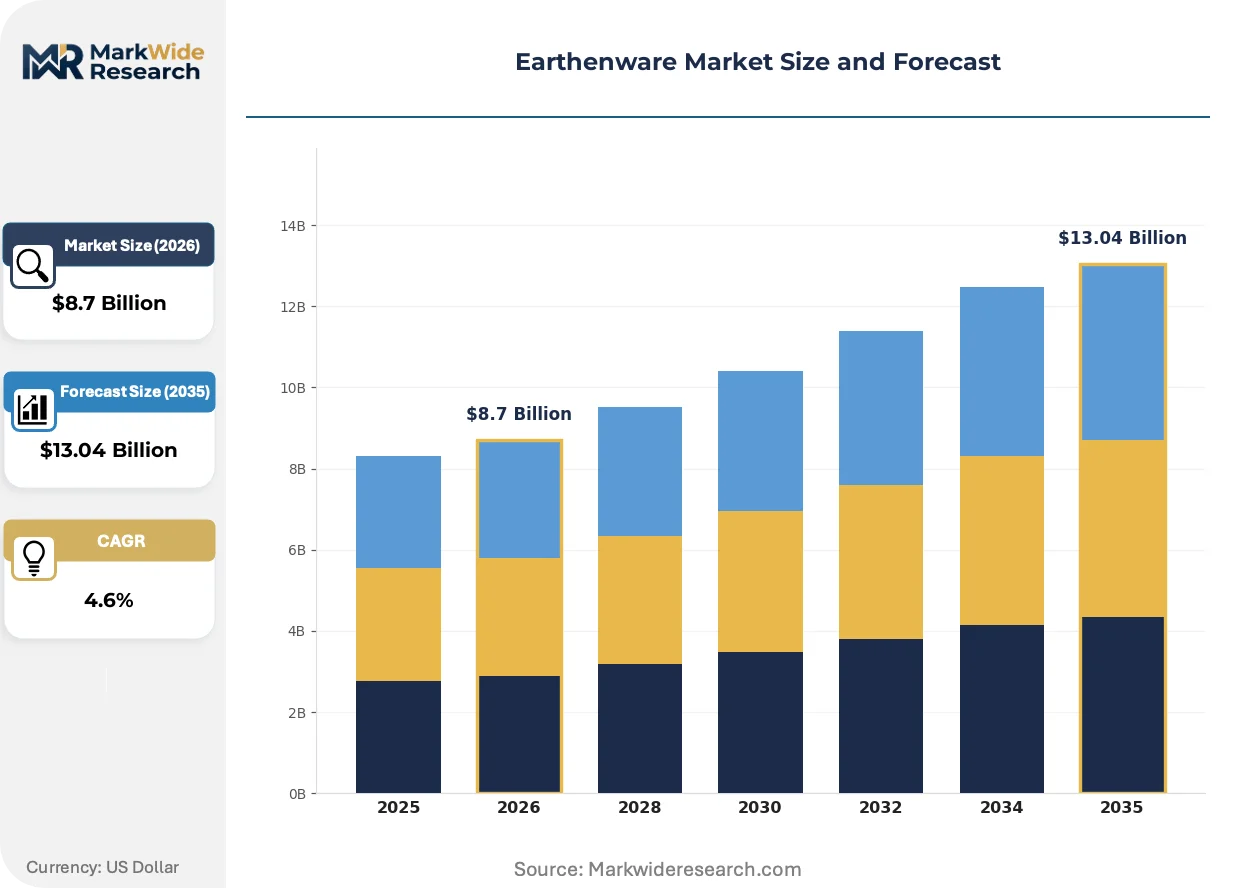
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stoneware, Porcelain, Terra Cotta, Earthen Pottery Application: Home Decor, Kitchenware, Garden, Artisanal End User: Retail Customers, Wholesalers, Artists, Craft Stores Distribution Channel: Online Retail, Specialty Stores, Home Improvement, Farmers Markets |
| Companies Covered | Shanxi Xianglong Black Pottery Handicraft Co., Ltd, Liangzi Black Pottery, Yixing Wankun, Jiangsu Sheng Yixing Red Pottery Arts Factory, Jinan Longshan Longyuan Black Pottery Art Co., Ltd, Hongshan Flowerpot, Qihe Longshan Black Pottery Technology Co., Ltd, Poterie Lorraine, Linyi Lijun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthenware Market Emerging Trajectories
Digital design tools and automated forming equipment are penetrating production floors previously dependent on manual skill, while regulatory chemistry constraints and shifting hospitality procurement models reshape competitive positioning.
Electrical resistance and gas-muffle hybrid kilns are consolidating firing control among medium-scale producers who previously relied on wood or coal combustion. Boutique hospitality buyers now require batch-level temperature documentation for food-contact certification. This technology shift is consolidating quality variance reduction as a baseline competitive requirement rather than a premium differentiator.
REACH Annex XVII restrictions on lead and cadmium migration are tightening permissible limits in colored glazes across European import channels. Kilns serving export markets must maintain dual formulation inventories or abandon pigment-intensive decorative lines. Tableware segments with heritage color palettes face the steepest compliance costs and longest reformulation timelines.
Direct sourcing contracts between artisan producers and restaurant groups are displacing traditional wholesale-distributor relationships in specialty kitchenware. Buyers seek provenance documentation and small-batch customization previously unavailable through mass retail channels. France and Italy exhibit the most advanced development of this procurement model, with chef-producer collaborations driving limited-edition tableware releases.
Earthenware Market Segmentation
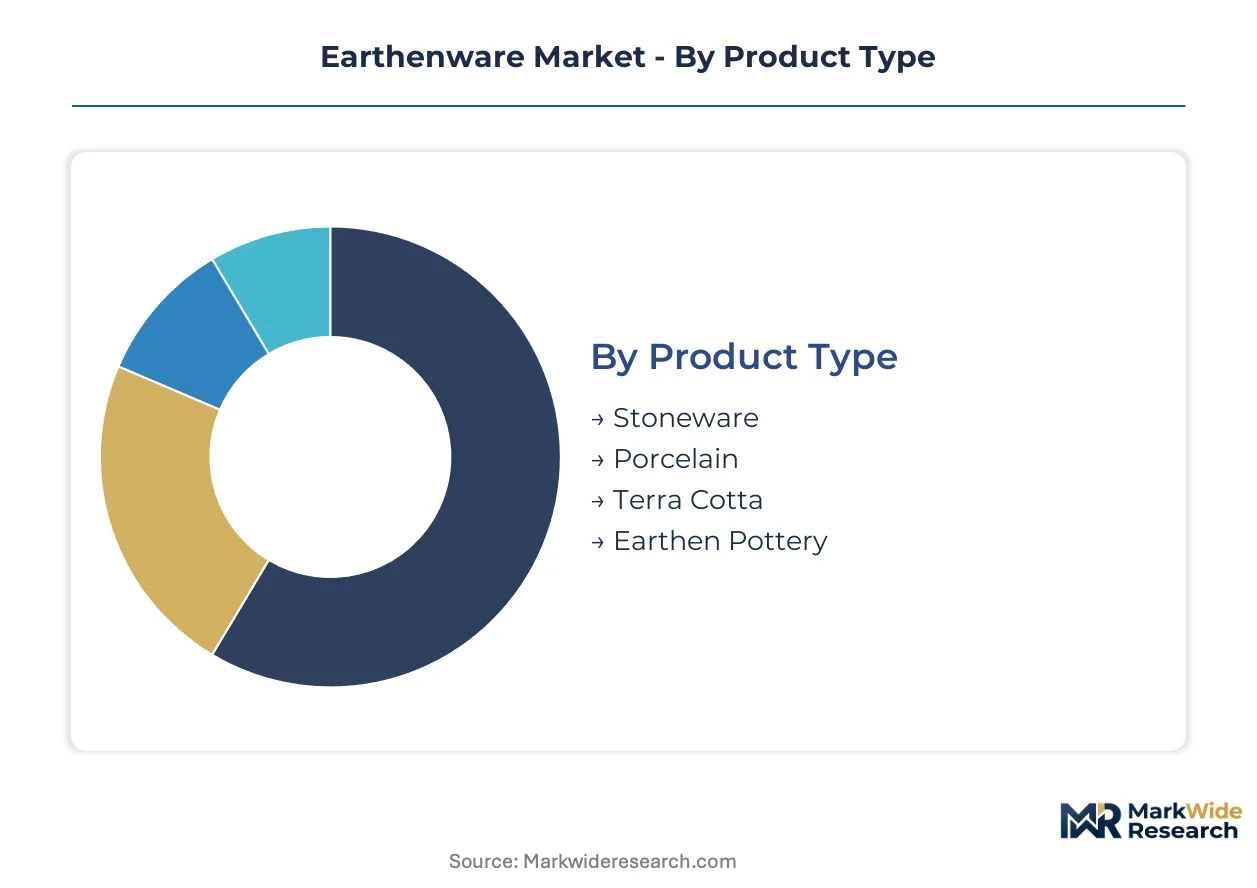
Earthenware demand fragments across firing temperatures, glaze chemistry, and end-use durability requirements. Each segment carries distinct margin profiles and regulatory exposure that reshape procurement priorities for kiln operators and distributors.
Product Type:
Terra cotta dominates volume throughput while porcelain commands the steepest unit premiums in specialty retail channels.
- Stoneware:Fired at 1,200-1,300°C with vitrified, non-porous bodies suited to oven-safe tableware. Restaurant procurement in France and Italy concentrates here for durability under thermal cycling. Reformulation costs for lead-free glazes compress margins for mid-tier producers without long-term compounder contracts.
- Porcelain:Kaolin-based, high-fire ceramic achieving translucency and near-zero water absorption. Yixing city kilns and Limoges manufacturers anchor heritage output for luxury hospitality tableware. SAMR GB standards and REACH Annex XVII impose parallel testing burdens that strain quality assurance resources.
- Terra Cotta:Unglazed, porous earthenware for horticultural containers and architectural cladding. Shandong province clusters supply volume gardenware through Home Improvement channels.
- Earthen Pottery:Low-fire decorative and functional vessels with traditional glaze palettes. Heritage tourism sales in Lorraine and Yixing bypass retail intermediaries.
Today's leader: Terra Cotta. Tomorrow's challenger: Porcelain.
Application:
Functional durability requirements separate commercial kitchen procurement from ornamental residential purchasing.
- Kitchenware:Food-contact tableware and cooking vessels requiring migration-tested glazes under FDA and EFSA frameworks. Direct sourcing contracts between artisan producers and boutique restaurant groups displace traditional wholesale-distributor relationships.
- Garden:Frost-resistant planters and landscaping elements where porosity aids root aeration. Jiangsu province kilns feed volume demand through home improvement retailers.
- Home Decor:Ornamental vessels and sculptural objects prioritizing aesthetic character over thermal performance. Biophilic design trends are accelerating unglazed terra cotta penetration through specialty décor channels.
- Artisanal:Limited-batch heritage pieces with provenance documentation for collector markets. Master craftsperson succession gaps in traditional throwing techniques threaten quality consistency.
Kitchenware claims the steepest expansion trajectory as hospitality procurement shifts toward transparent supply relationships.
End User:
Volume scale and customization depth determine channel access and margin capture for kiln operators.
- Retail Customers:Individual purchasers seeking functional tableware and decorative objects through online and specialty store channels. Carbon-neutral certification premiums attract sustainability-focused buyers in Northern Europe.
- Wholesalers:Traditional distributors consolidating volume orders for mass-market gardenware and standard tableware lines. Margin compression from flux mineral price volatility pressures procurement terms.
- Artists:Studio practitioners purchasing raw clay bodies and glaze compounds for independent production. Single-source glaze chemistry dependency creates bottleneck risk for small-batch compound access.
- Craft Stores:Curated retail channels emphasizing handmade provenance and regional heritage narratives. Direct-to-visitor sales at firing sites capture margin otherwise lost to these intermediaries.
Retail Customers anchor current revenue. Artists represent the fastest-climbing engagement tier as maker-culture expands.
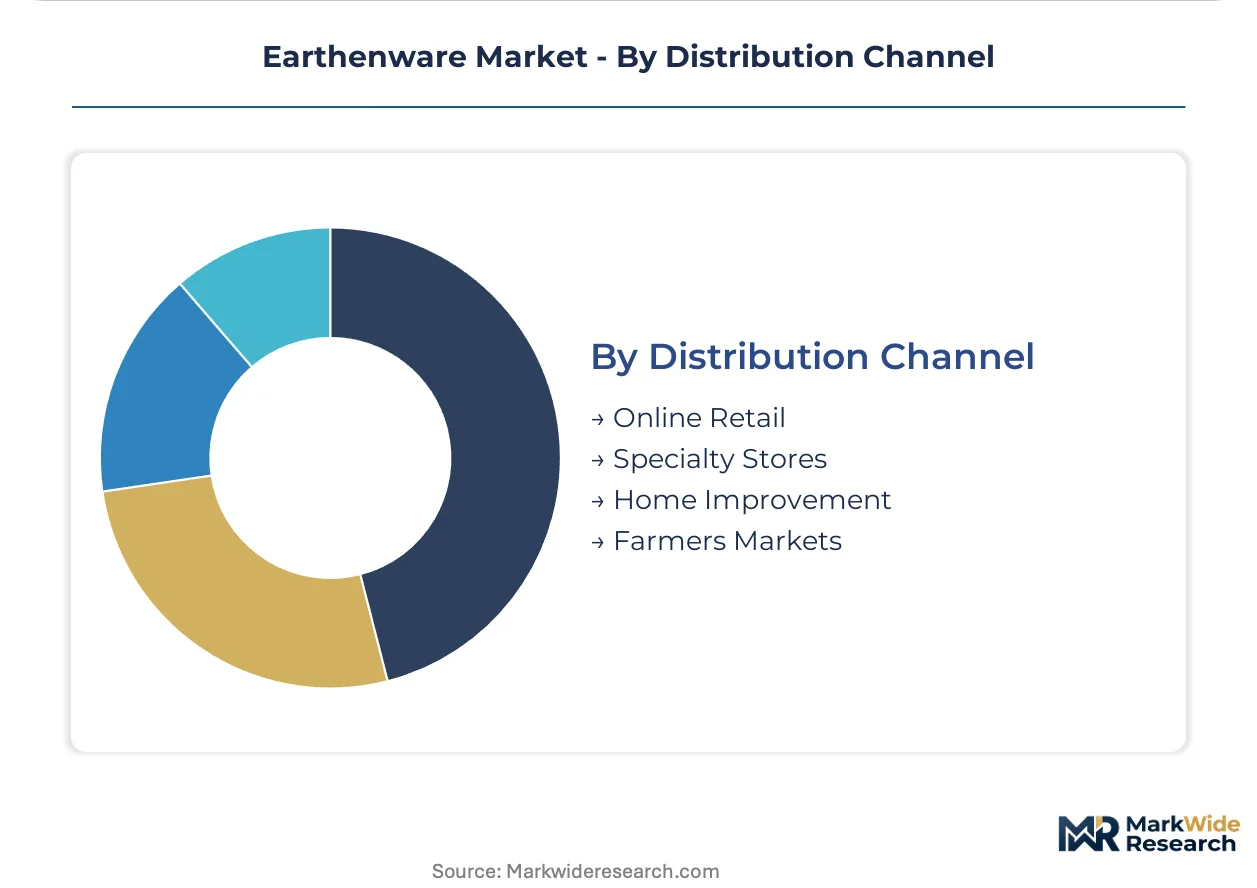
Distribution Channel:
Provenance transparency and batch documentation reshape channel economics across hospitality and residential segments.
- Online Retail:Direct-to-consumer platforms enabling artisan producers to bypass wholesale markups. EU Green Deal kiln incentives support carbon footprint certification for tableware exports through these channels.
- Specialty Stores:Curated brick-and-mortar retailers emphasizing heritage narratives and limited editions. Chef-producer collaborations in France and Italy drive exclusive releases.
- Home Improvement:Volume retailers for standardized gardenware and functional kitchen basics. Shandong-Jiangsu cluster density sustains cost-competitive supply.
- Farmers Markets:Local producer-direct sales with minimal intermediation for artisanal and heritage pieces. Regional appellation practices in Lorraine reinforce geographic authenticity claims.
Specialty Stores dominate premium positioning. Online Retail gains share fastest as direct sourcing models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Earthenware production traces its commercial lineage to Mesopotamian kilns and Chinese Neolithic traditions, with contemporary manufacturing clustering where clay deposits, artisan knowledge, and export infrastructure converge. Modern demand patterns reflect this geographic inheritance.
China
Shandong and Jiangsu province clusters supply volume gardenware and decorative segments through concentrated raw material access and specialized labor pools. SAMR GB standards enforce domestic safety benchmarks that shape product access for both local and foreign producers. Yixing city maintains deep geographic lock-in for purple clay teaware heritage production.
France
Boutique hospitality procurement drives demand for artisanal tableware with provenance documentation in the Lorraine region. EU Green Deal kiln incentives accelerate electric and biomass firing adoption among producers seeking carbon footprint certification. Poterie Lorraine anchors French output through controlled regional appellation practices that reinforce geographic authenticity claims.
Italy
Restaurant procurement concentrates on stoneware durability for thermal cycling resistance in commercial kitchen environments. EFSA frameworks govern food-contact migration testing requirements for export-oriented kilns. Chef-producer collaborations in Emilia-Romagna and Tuscany drive limited-edition tableware releases through direct sourcing contracts.
Germany
REACH Annex XVII restrictions on lead and cadmium migration compel glaze reformulation across export-oriented producers serving European import channels. Dual carbon compliance timelines pressure quality assurance resources for kilns maintaining parallel testing protocols. Bavarian craft associations coordinate heritage tourism channel development to capture margin from direct-to-visitor sales.
United States
FDA migration-tested glaze requirements shape food-contact tableware procurement from specialty retail channels. Biophilic design trends accelerate unglazed terra cotta penetration through home décor specialty retailers in urban residential markets. Studio practitioners in California and the Pacific Northwest drive maker-culture expansion through craft store and farmers market channels.
Earthenware Market Vendor Landscape
Premium-margin players sit above commodity-margin players across heritage certification and carbon-neutral production protocols, with pricing stratifying across provenance-documented artisan lines and volume gardenware. The vendor base distributes across three strategic archetypes: heritage ateliers with master craftsperson succession, scale-driven cluster producers in Shandong-Jiangsu, and boutique hospitality specialists with chef collaboration programs. Capacity expansion and direct-to-consumer channel development represent the dominant competitive moves as wholesale-distributor relationships erode.
Among Chinese heritage fabricators, Shanxi Xianglong Black Pottery Handicraft Co., Ltd and Yixing Wankun occupy positions exemplifying ancestral firing method preservation and purple clay teaware specialization respectively. Poterie Lorraine represents the European appellation-controlled archetype, anchoring French artisanal output through geographic authenticity practices that sustain premium positioning against commodity imports.
| Leading Market Players |
|---|
| Shanxi Xianglong Black Pottery Handicraft Co., Ltd |
| Liangzi Black Pottery |
| Yixing Wankun |
| Jiangsu Sheng Yixing Red Pottery Arts Factory |
| Jinan Longshan Longyuan Black Pottery Art Co., Ltd |
| Hongshan Flowerpot |
| Qihe Longshan Black Pottery Technology Co., Ltd |
| Poterie Lorraine |
| Linyi Lijun |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-compliant heritage lines and commodity gardenware creates parallel supply ecosystems. Premium ateliers absorb dual-testing costs for EU and Chinese markets while Shandong-Jiangsu cluster producers optimize for volume throughput without migration documentation.
Pricing Analysis
Three-tier pricing structure across heritage-certified, standard-compliant, and unglazed economy levels governs transaction dynamics. Price differentiation rests on glaze chemistry certification and provenance documentation depth. Cost compression in mid-tier decorative lines is intensifying because flux mineral contracts favor scale buyers. Boutique hospitality procurement shows least price sensitivity; home improvement retail channels exhibit maximum elasticity.
Supply Chain Analysis
Single-source vulnerability sits with certified glaze compounders concentrated in Germany and China. Raw material dependencies include Yixing purple clay deposits, Shandong feldspar reserves, and Lorraine regional kaolin. Supply chain risk centers on REACH reformulation bottlenecks forcing parallel inventory maintenance. Distribution runs through direct-to-restaurant contracts, heritage tourism sites, and home improvement retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU compliance costs exceed Chinese domestic certification burdens by meaningful margins, rewarding dual-registered producers with premium channel access.
For Market Incumbents: Anticipate porcelain substitution pressure in tableware by deepening heritage craftsperson apprenticeship pipelines and securing long-term compounder contracts before REACH Annex XVII tightening. Carbon-neutral kiln certification represents the priority defensive lever against sustainability-focused procurement officers.
For New Entrants and Emerging Players: Enter via unglazed terra cotta biophilic design segments where regulatory burden remains minimal and urban residential demand is accelerating. Target direct-to-consumer online channels with batch-level firing documentation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where master craftsperson succession gaps threaten quality consistency in heritage-producing regions. Five-to-ten year viability favors ateliers with captive clay deposits and established chef collaboration programs. Watch for SAMR enforcement intensity as the inflection signal for Chinese export competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Craftsperson Apprenticeship Program | Yixing and Lorraine ateliers secure generational knowledge transfer against succession risk. |
| Dual-Certification Testing Investment | Parallel REACH and SAMR compliance opens premium EU and Chinese procurement channels simultaneously. |
| Carbon-Neutral Kiln Retrofit | Electric and biomass firing adoption captures EU Green Deal subsidies and sustainability premiums. |
| Direct-to-Restaurant Supply Contract | Bypassing wholesale distributors captures margin otherwise lost to intermediaries in France and Italy. |
| Regional Clay Deposit Acquisition | Captive Yixing purple clay or Shandong kaolin access insulates against raw material price volatility. |
Methodological Framework
Direct dialogue with kiln operators, glaze compounders, boutique hospitality procurement officers, and heritage craft association directors grounded qualitative assessment. Secondary validation drew from SAMR GB standard filings, ECHA REACH restriction updates, EU Green Deal implementation documents, and customs trade records. Bottom-up capacity surveys across Shandong-Jiangsu clusters were triangulated against top-down demand modeling.
Top-down macroeconomic drivers were cross-checked against bottom-up segment trajectories across the analysis window. Modeled dimensions include firing temperature tier, glaze chemistry compliance grade, end-use durability requirement, and distribution channel type. CAGRs were derived from segment-level growth rate synthesis. Forecast inputs incorporated kiln technology adoption curves and regulatory timeline compression effects.
Inputs from primary field contacts and published regulatory filings were available through the study window; gaps in real-time flux mineral contract pricing introduce uncertainty bands around margin projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Iran Ceramic Tiles Market
Ceramics
Global Functional Ceramics Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Fire Clay Market
Ceramics
White Fused Alumina Market
Ceramics
Wollastonite Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Titanium Carbide Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Global Alumina Market
Ceramics
Lithium Silicate Market
Ceramics
United States Ceramic Tiles Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Ceramic Proppant Market