
 Heavy Duty Dewatering Pumps Market | 2026-2036
Heavy Duty Dewatering Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Dewatering Pumps Market Insights
Predictive maintenance subscriptions is repositioning how OEMs monetize dewatering assets. Grundfos leverages its digital service platform to lock in recurring revenue from remote monitoring contracts. Flowserve anchors its position through aftermarket parts agreements that extend equipment life cycles. Weir Group competes by embedding IoT sensors directly into pump housings for real-time vibration analysis.
Heavy duty dewatering pumps are high-capacity fluid-handling machines engineered to extract water, slurry, or abrasive mixtures from excavations, underground workings, and flooded industrial sites, typically achieving flow rates exceeding 1,000 gallons per minute and heads above 100 meters. Submersible pumps dominate rental fleets for construction dewatering due to their portability and reduced suction lift constraints. Electric drive technology is gaining share fastest in underground mining applications where ventilation economics favor zero-emission equipment over diesel alternatives.
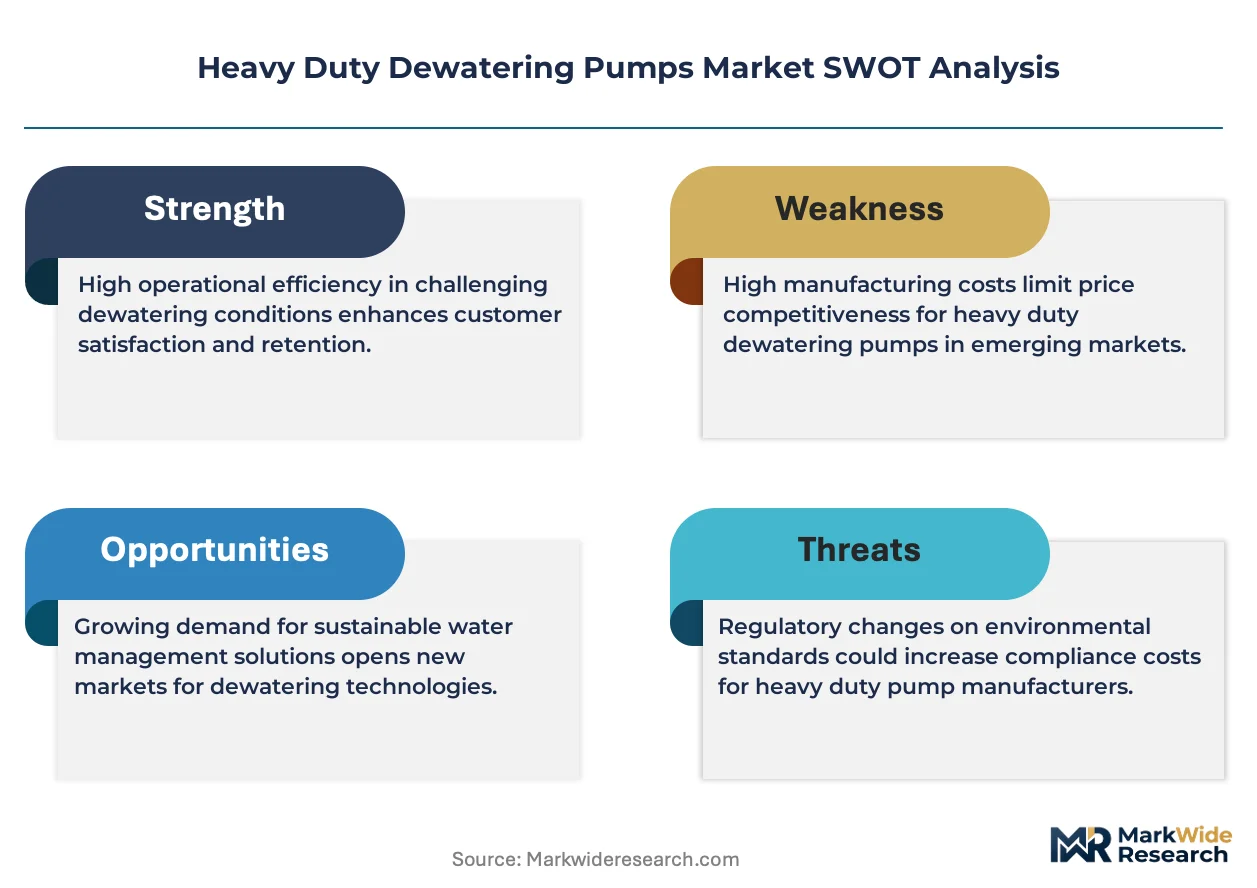
EPA Tier 4 Final regulations in the United States restrict diesel particulate emissions from portable pumping equipment, while EU F-Gas Regulation phases down fluorinated refrigerants used in cooling systems integrated with certain pump packages. China's MEE enforces wastewater discharge standards that mandate higher-efficiency dewatering systems at mine sites. Stakeholders must weigh electrification capex against tightening emissions enforcement when refreshing fleet portfolios.
Market Dynamics
The electrification of underground mining fleets is compressing replacement cycles for diesel-driven dewatering equipment, forcing OEMs to restructure product portfolios around zero-emission architectures and thermal management systems.
Growth Catalysts
- EPA Tier 4 Final:Diesel particulate emission limits in the United States are accelerating capital deployment into electric-drive submersible units across construction rental fleets.
- Pilbara iron ore expansion:Western Australia's mining corridor is generating concentrated demand for high-head slurry pumps capable of handling abrasive tailings at depth.
- Submersible motor cooling:Advances in oil-filled motor technology are extending mean time between failures in geothermal and tunneling applications.
Market Restraints
- Copper winding supply:Electric motor manufacturers face input cost volatility from concentrated Chilean and Peruvian cathode production.
- Foundry capacity:Ductile iron casting for pump housings concentrates in a limited supplier base across China's Hebei province.
- EU F-Gas phase-down:Refrigerant restrictions on cooling-integrated pump packages are creating compliance friction for diesel-hybrid product lines.
Strategic Opportunities
- India's coal belt modernization:Jharkhand and Odisha mine operators are retrofitting legacy open-pit dewatering infrastructure with automated pump stations.
- Predictive maintenance convergence:Vibration sensing and cloud analytics are unifying into subscription revenue models for OEM service divisions.
- Indonesia nickel rush:Sulawesi and Halmahera processing facilities require corrosion-resistant submersible systems for acidic leachate handling.
Industry Challenges
- ATEX certification timelines:Explosion-proof motor testing for underground coal applications faces backlog at notified bodies in Germany and the United Kingdom.
- Legacy control integration:SCADA retrofit compatibility is extending commissioning periods for smart pump deployments at aging mine sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Dewatering Pumps Market |
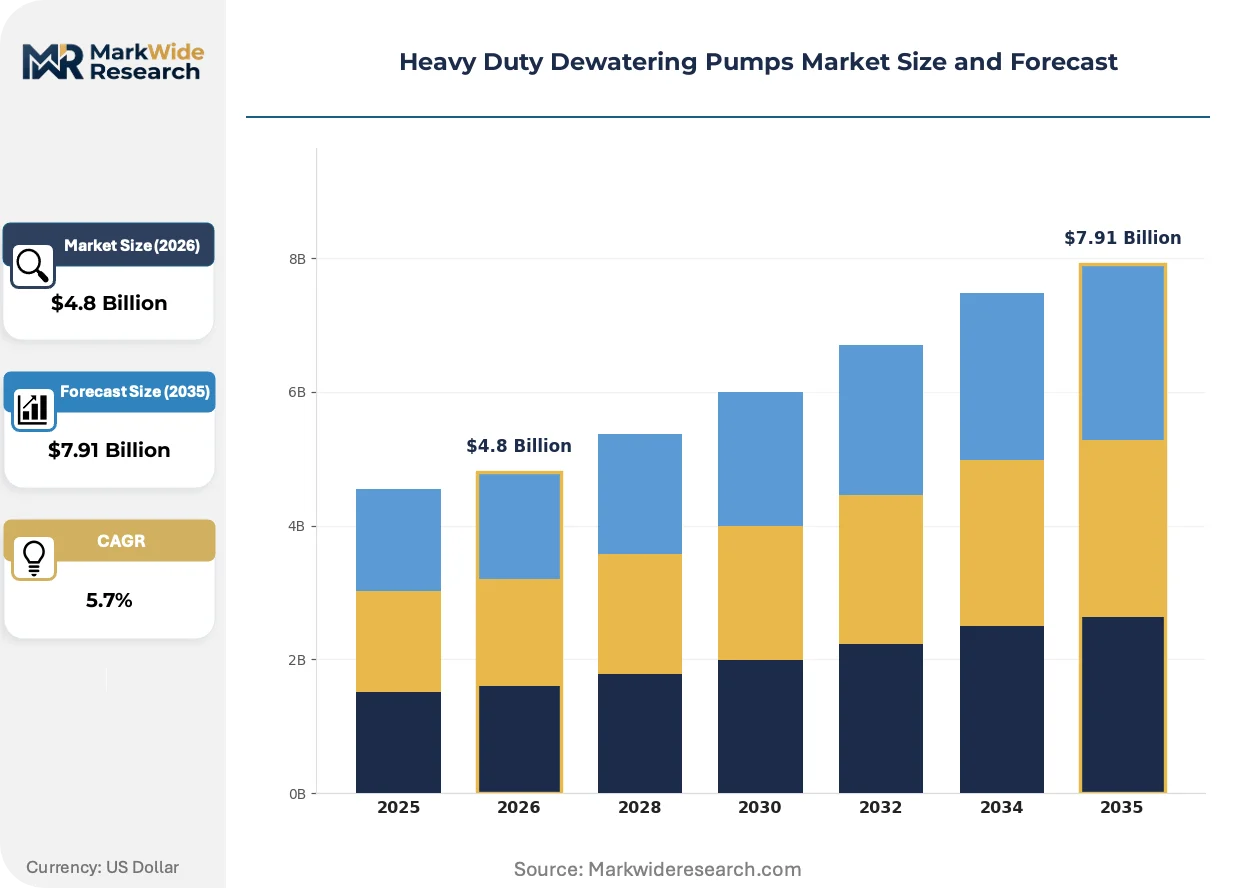
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Axial Flow Pumps, Diaphragm Pumps, Vacuum Pumps Technology: Hydraulic Drive, Electric Drive, Diesel Engine, Solar Powered, Pneumatic Application: Construction Sites, Mining Operations, Municipal Water Management, Oil & Gas Extraction, Shipbuilding End User: Contractors, Mining Companies, Municipal Authorities, Energy Producers, Marine Operators |
| Companies Covered | Grundfos, Flowserve, Eddy Pump Corporation, Weir Group, ITT Goulds Pumps, DAE Pumps, Koshin, Ebara Corporation, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Dewatering Pumps Market Trends and Innovations
Digital service architectures are displacing transactional equipment sales as the primary revenue mechanism, with real-time monitoring capabilities becoming standard rather than premium features across industrial pump portfolios.
Permanent magnet synchronous motor technology is unifying power density and efficiency in submersible dewatering units. Underground hard-rock miners in Canada and Sweden are specifying these systems for ventilation-constrained shafts. The technology is unifying pump and motor into compact single-unit designs that reduce installation footprint by half compared to conventional split configurations.
China's MEE wastewater discharge standards are tightening suspended solids limits for mine effluent. Surface and underground operations must now deploy multi-stage filtration ahead of final discharge points. Western Australia's gold and lithium producers are investing in automated chemical dosing systems integrated with pump control logic to maintain continuous compliance.
Rental fleet operators are unbundling maintenance from equipment lease agreements and selling monitoring access as standalone subscriptions. Construction contractors in the United States and Germany are purchasing telemetry-only contracts while sourcing hardware through third-party lessors. The model is most visible in urban tunneling projects where pump deployment duration is uncertain at contract inception.
Heavy Duty Dewatering Pumps Market Segmentation
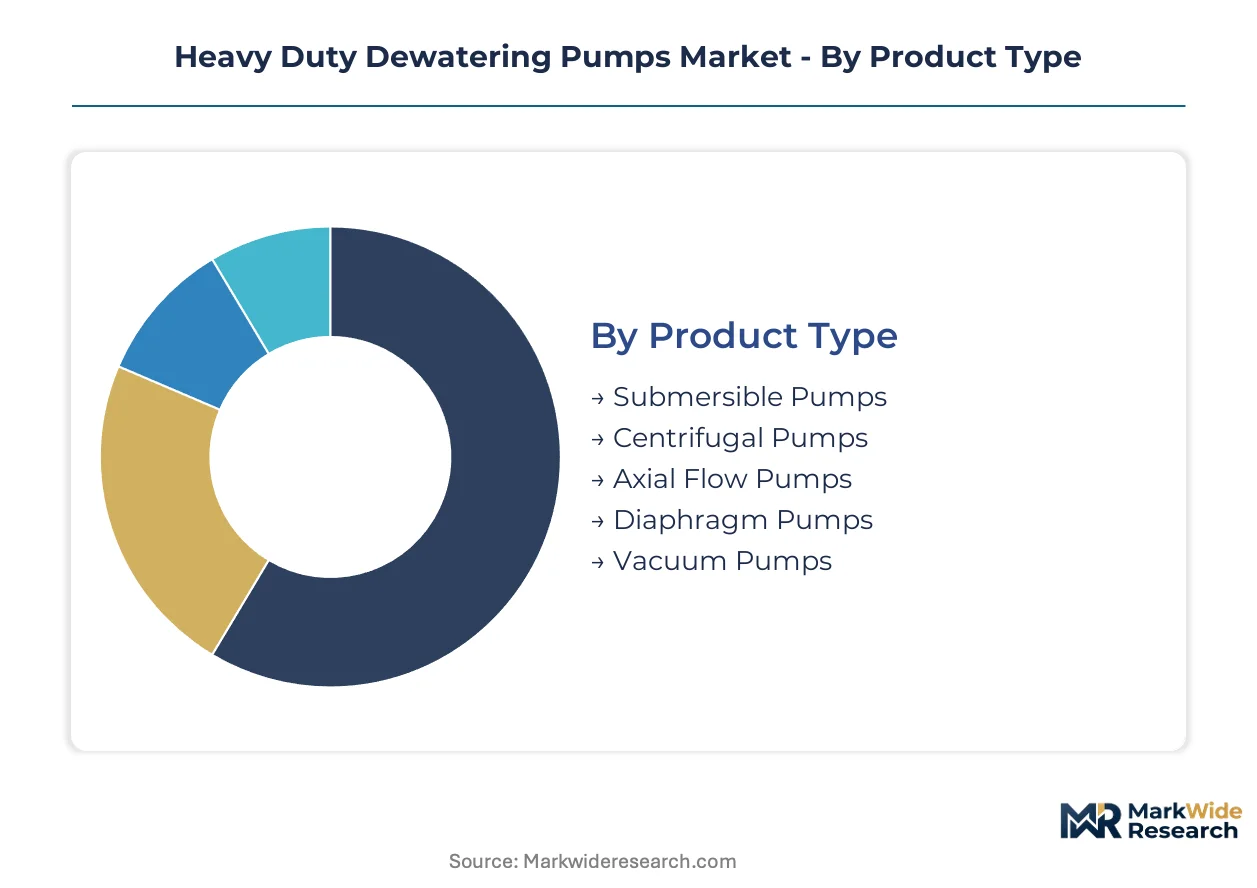
Segmentation in heavy duty dewatering pumps reveals how equipment specifications align with operational constraints across extraction depths, power availability, and fluid abrasiveness. Understanding these divides helps OEMs allocate R&D resources between rental fleet standardization and custom engineered solutions.
Product Type:
Volume concentration sits with portable submersible units, while premium margins attach to engineered centrifugal systems for permanent installations.
- Submersible Pumps:These units integrate motor and pump into a sealed housing that operates fully immersed, eliminating suction lift limitations and enabling deployment in confined excavations. Australia's Pilbara iron ore miners specify high-head variants for pit dewatering where diesel ventilation costs favor electric submersibles.
- Centrifugal Pumps:Impeller-driven designs generate pressure through rotational energy transfer, achieving flow rates exceeding 1,000 gallons per minute in surface-mounted configurations. Municipal water authorities in Germany and Japan deploy these for flood control infrastructure where continuous duty cycles demand hardened bearing assemblies.
- Axial Flow Pumps:Propeller-type mechanisms move large water volumes at low heads, common in coastal drainage applications.
- Diaphragm Pumps:Positive displacement action handles viscous slurries and debris-laden flows in tunneling operations.
- Vacuum Pumps:Suction-based systems supplement primary dewatering for localized groundwater control at shallow depths.
Today's leader: Submersible Pumps. Tomorrow's challenger: Centrifugal Pumps.
Technology:
Application context determines power source selection, with ventilation economics and emissions enforcement reshaping technology mix in underground settings.
- Electric Drive:Grid-connected or battery-powered motors eliminate exhaust emissions and reduce thermal loading in confined shafts. Canadian hard-rock miners specify permanent magnet synchronous variants for ventilation-constrained operations where EPA-equivalent standards apply provincially.
- Diesel Engine:Self-contained power enables rapid deployment at remote sites lacking grid infrastructure. US construction rental fleets face Tier 4 Final compliance costs that compress residual values for non-retrofitted units.
- Hydraulic Drive:External power packs isolate motors from flooded environments in deep foundation work.
- Solar Powered:Photovoltaic arrays with battery storage serve intermittent dewatering needs at off-grid mine reclamation sites.
- Pneumatic:Compressed air systems operate in explosive atmospheres where electrical ignition risks are prohibitive.
Electric Drive commands current procurement momentum; Diesel Engine retains installed base dominance in emerging markets.
Application:
Mining and construction split the addressable market by project duration, with permanent municipal installations representing annuity revenue streams.
- Mining Operations:Continuous dewatering of pit floors and underground workings demands corrosion-resistant materials for acidic leachate. Indonesia's Sulawesi nickel processors specify duplex stainless steel housings for acidic tailings handling.
- Construction Sites:Temporary groundwater control for foundations and tunnels favors rental fleet flexibility over capital ownership. German urban tunneling contractors purchase telemetry subscriptions while leasing hardware through third-party lessors.
- Municipal Water Management:Flood control and sewer bypass operations require rapid-deployment trailer-mounted systems.
- Oil & Gas Extraction:Produced water handling at well pads integrates with separation equipment for regulatory compliance.
- Shipbuilding:Dry dock dewatering and bilge systems employ compact submersible units with marine-grade coatings.
Mining Operations anchor equipment margins; Construction Sites drive fleet utilization rates.
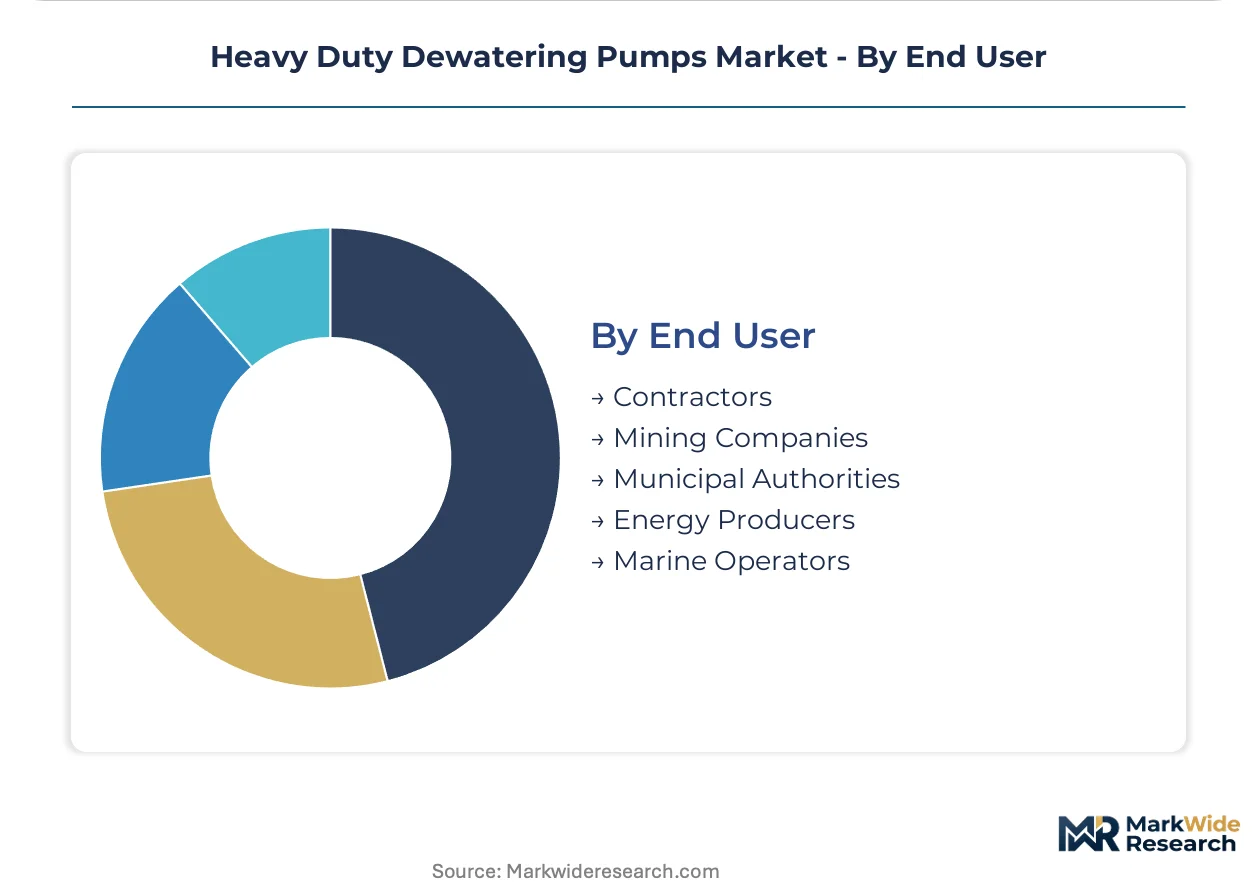
End User:
Procurement sophistication varies sharply between specification-driven mining companies and price-sensitive municipal tender processes.
- Mining Companies:Technical buyers evaluate total cost of ownership across 15-year mine life cycles, prioritizing mean time between failures over initial capital outlay. Western Australia's gold and lithium producers invest in automated chemical dosing integrated with pump control logic.
- Contractors:Project-based operators optimize for mobilization speed and rental rate competitiveness. US and German construction firms unbundle maintenance from lease agreements to reduce fixed cost exposure.
- Municipal Authorities:Public procurement cycles favor established suppliers with certified service networks.
- Energy Producers:Power plant cooling water and ash pond management require continuous-duty configurations.
- Marine Operators:Port authorities and shipyards specify corrosion-resistant materials for saltwater exposure.
Mining Companies set performance benchmarks; Contractors determine rental fleet composition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as OEMs relocate assembly to jurisdictions with lighter emissions enforcement, while end-users in strict-regulation markets absorb premium pricing for compliant equipment.
Australia
Western Australia's Pilbara iron ore corridor generates concentrated demand for high-head electric submersibles as miners expand pit dewatering capacity. The country's national environmental regulator enforces strict mine effluent standards that mandate continuous monitoring systems. Perth-based engineering clusters are integrating predictive maintenance platforms with pump control logic for remote site operations.
United States
Construction rental fleets in Texas and the Mountain West are accelerating diesel-to-electric retrofits ahead of EPA Tier 4 Final deadlines. The Environmental Protection Agency restricts particulate emissions from portable pumping equipment at federal worksites. Chicago-area distributors are unbundling maintenance contracts from hardware leases to capture recurring telemetry revenue.
China
Hebei province's foundry concentration supplies ductile iron castings for pump housings serving domestic mining modernization programs. The Ministry of Ecology and Environment enforces wastewater discharge standards with tightened suspended solids limits at mine sites. Shandong Peninsula manufacturers are expanding permanent magnet synchronous motor production for ventilation-constrained underground applications.
Germany
Ruhr Valley industrial services firms are retrofitting legacy coal mine dewatering infrastructure with automated pump stations. The EU F-Gas Regulation phases down fluorinated refrigerants used in cooling-integrated pump packages. Bavarian engineering specialists are clearing ATEX certification backlogs for explosion-proof motors bound for underground coal applications.
Indonesia
Sulawesi and Halmahera nickel processing facilities require corrosion-resistant submersible systems for acidic leachate handling in hydrometallurgical circuits. The country's national environmental ministry enforces tailings management standards at coastal processing plants. Jakarta-based procurement offices are specifying duplex stainless steel housings for new mine developments.
Heavy Duty Dewatering Pumps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line OEMs commanding specification-driven mining accounts while regional fabricators capture construction rental volume. The vendor base concentrates around three strategic archetypes: integrated pump-motor specialists, aftermarket service platforms, and rental fleet suppliers. Competitive intensity is manifesting through vertical integration into motor manufacturing and subscription-based service model proliferation.
Within the integrated technology tier, Grundfos and Weir Group exemplify the convergence of hardware and digital service architectures. Ebara Corporation anchors the Asia-Pacific manufacturing footprint for submersible motor production. These three occupy positions that represent divergent strategic bets on electrification timing and predictive maintenance monetization.
| Leading Market Players |
|---|
| Grundfos |
| Flowserve |
| Eddy Pump Corporation |
| Weir Group |
| ITT Goulds Pumps |
| DAE Pumps |
| Koshin |
| Ebara Corporation |
| Xylem Inc. |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper cathode pricing cascades through electric motor manufacturing into three distinct equipment tiers, with mining procurement teams absorbing premium markups for permanent magnet synchronous configurations while construction rental fleets negotiate volume discounts on standard submersible units.
Pricing Analysis
Distributor margins on aftermarket parts agreements anchor the pricing architecture across premium, standard, and economy tiers. Certification grade differentiation separates ATEX-rated explosion-proof units from general industrial configurations, with brand premiums attaching to predictive maintenance platform bundling. Cost compression in the standard tier intensifies as Chinese foundries expand ductile iron casting capacity. Municipal authorities exhibit highest price sensitivity due to public tender cycles, while mining companies prioritize mean time between failures over capital outlay.
Supply Chain Analysis
Container freight rates from China's Hebei province to Western Australia mining corridors feed directly into landed cost calculations for pump housing castings. Manufacturing concentration rests on China for ductile iron foundries, Chile and Peru for copper cathode, and Germany for precision bearing assemblies. Single-source vulnerability concentrates in oil-filled motor cooling system suppliers. Distribution runs through regional distributor networks with certified service capabilities for aftermarket parts and field commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electrification mandates across underground mining operations force replacement of diesel-driven fleets with premium zero-emission architectures.
For Market Incumbents: Acquire permanent magnet synchronous motor production capabilities to secure supply chain control over the fastest-growing technology segment. Consolidate aftermarket service networks in Western Australia's Pilbara region where predictive maintenance subscriptions are displacing transactional equipment sales. Defend against emerging electric-drive specialists by embedding IoT sensors directly into pump housings for real-time vibration analysis.
For New Entrants and Emerging Players: The price-point gap between premium predictive maintenance bundles and economy rental fleet units offers entry opportunity in India's Jharkhand and Odisha coal belt modernization. Target automated pump station retrofits at aging open-pit mines where legacy SCADA integration extends commissioning periods for established OEMs. Partner with Jakarta-based procurement offices for corrosion-resistant duplex stainless steel systems in Indonesia's nickel processing corridor.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier OEMs possessing ATEX certification capabilities and established foundry relationships. Five-to-ten year viability hinges on electrification capex cycles in ventilation-constrained mining jurisdictions. Monitor EPA enforcement intensity at federal worksites as the inflection signal for diesel-to-electric retrofit acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive supply of permanent magnet synchronous motors insulates against copper cathode volatility from Chilean and Peruvian sources. |
| Predictive Maintenance Platform Launch | Remote monitoring subscriptions lock in recurring revenue from Australian iron ore miners expanding pit dewatering capacity. |
| ATEX Certification Investment | Explosion-proof motor capabilities unlock underground coal applications in Germany and the United Kingdom where notified body backlogs constrain supply. |
| Regional Service Network Expansion | Perth-based engineering clusters integrate predictive maintenance with pump control logic for remote Western Australia operations. |
| Corrosion-Resistant Materials Partnership | Duplex stainless steel sourcing agreements with Indonesian nickel processors address acidic leachate handling requirements in hydrometallurgical circuits. |
Research Methodology
Multiple input streams — maintenance directors at Australian iron ore operations, procurement leads at German tunneling contractors, aftermarket service heads at North American rental fleets, and plant engineers at Indonesian nickel processing facilities — were reconciled against customs records, EPA enforcement databases, and mining equipment import manifests. Secondary validation drew from SEC filings of listed pump manufacturers, MEE wastewater discharge compliance reports, and EU F-Gas Regulation implementation tracking. Bottom-up equipment deployment counts and top-down mining capex projections were triangulated to establish market sizing.
Historical shipment data was cross-referenced against panel input from OEM product managers and regional distributor principals across the analysis window. Segmentation modeling incorporated product type, drive technology, application context, and end-user procurement sophistication. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance deadline mapping. Forecast inputs included electrification mandates in ventilation-constrained mining jurisdictions and foundry capacity expansion timelines in China's Hebei province.
Caveats apply where copper cathode price volatility, ATEX certification backlog resolution, or diesel emission enforcement intensity could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Rotating Equipment Market