
 Seawater Cooling Pumps Market | 2026-2036
Seawater Cooling Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Seawater Cooling Pumps Market Analytics
IMO 2023 carbon intensity regulations is recalibrating the cost-of-entry calculus for pump suppliers serving marine cooling retrofits. Ebara Corporation leverages its titanium-alloy casting expertise to dominate Japanese shipyard specifications. Grundfos anchors its position through modular variable-frequency drive integration that cuts parasitic load in portside installations. Sulzer competes via localized service networks spanning Mediterranean and Southeast Asian repair hubs.
Seawater cooling pumps are engineered centrifugal, positive displacement, or submersible systems constructed from duplex stainless steel, super duplex alloys, or titanium to resist chloride-induced pitting in raw seawater circuits; they circulate thermal discharge fluid through heat exchangers serving power generation, petrochemical refining, and vessel propulsion cooling loops. Centrifugal pumps occupy the dominant installed base due to their compatibility with high-volume, low-head thermal transfer duties in coastal power plants. Submersible configurations represent the fastest-growing product category as floating LNG terminals and deep-water aquaculture operations require immersion-rated motors that eliminate suction lift constraints. The application split reveals power generation commanding the largest revenue pool while marine applications carry the highest replacement frequency due to biofouling and cavitation wear.
The EU F-Gas Regulation and IMO DCS carbon reporting framework shape product roadmaps by mandating energy efficiency documentation and refrigerant leak prevention in integrated cooling systems. Japan's METI enforces JIS marine equipment standards that dictate minimum corrosion allowances for pumps installed in territorial waters. Stakeholders must monitor how China's GB standards for offshore equipment and the EPA's Clean Water Act Section 316(b) thermal discharge rules in the United States will redefine material specifications and monitoring instrumentation requirements across export markets.
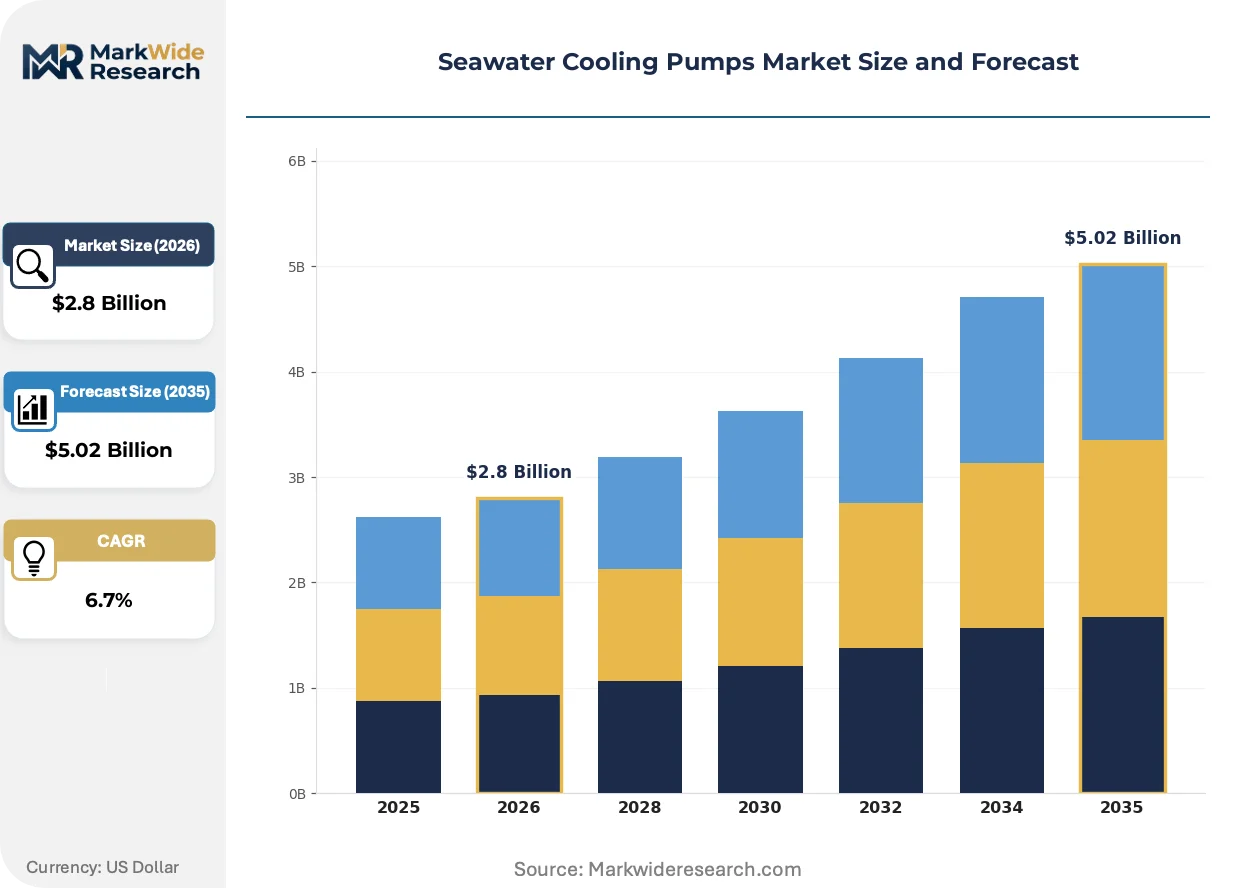
Market Dynamics
Corrosion-resistant metallurgy and variable-frequency drive integration are compressing replacement cycles while elevating performance thresholds for coastal thermal management infrastructure.
Growth Catalysts
- IMO 2023 Carbon Intensity Standards:Maritime operators in Singapore, Rotterdam, and Shanghai are retrofitting auxiliary cooling loops to meet CII grades, triggering wholesale pump replacements ahead of dry-dock schedules.
- Floating LNG Terminal Proliferation:Submersible pump configurations rated for deep-water immersion are capturing newbuild contracts as Gulf of Mexico and West African projects advance.
- Titanium Casting Scale Economies:Japanese and Korean foundries have reduced billet costs for pump housings, extending service intervals beyond 80,000 operating hours in chloride-rich environments.
Market Restraints
- Nickel Alloy Price Volatility:Super duplex stainless steel feedstock costs fluctuate with Indonesian ore export quotas, squeezing margin visibility for long-lead pump contracts.
- EU F-Gas Regulatory Friction:Integrated cooling systems face extended certification timelines when refrigerant circuits interface with seawater heat exchangers, delaying project commissioning.
- Submersible Motor Supplier Concentration:Hermetic motor-winding capabilities concentrate in German and Swiss specialty manufacturers, creating single-source vulnerability for deep-rated configurations.
Strategic Opportunities
- India Port Modernization:Jawaharlal Nehru Port Trust and Visakhapatnam expansion plans specify high-flow submersible arrays for berth-side thermal management.
- Variable-Frequency Drive Convergence:Integration of permanent magnet motors with edge-computing load optimization is opening premium retrofit tiers in aging Mediterranean power plants.
- China Offshore Nuclear Cooling:State-backed floating reactor programs require corrosion-resistant circulation systems for jacket water loops in territorial waters.
Industry Challenges
- Titanium Welding Certification Bottlenecks:Qualified orbital welders for duplex alloy pump fabrication remain scarce in Southeast Asian shipyards, extending fabrication lead times.
- Legacy Control System Integration:Digital twin diagnostics for predictive maintenance face protocol mismatches with 1990s-era SCADA installations in coastal power generation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seawater Cooling Pumps Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Electric Pumps Application: Industrial Cooling, Power Generation, Marine Applications, Aquaculture End User: Power Plants, Shipping Companies, Water Treatment Facilities, Oil & Gas Installation Type: Onshore, Offshore, Fixed, Mobile |
| Companies Covered | Ebara Corporation, Grundfos, Sulzer, Flowserve, Xylem, KSB, Torishima Pump, Desmi, Sundyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seawater Cooling Pumps Market Evolving Landscape
Digital instrumentation layered onto mechanical pumping systems is compressing maintenance intervals while enabling condition-based overhaul scheduling previously unavailable to marine operators.
Additive manufacturing of titanium impeller geometries is rewriting hydraulic efficiency benchmarks for high-flow, low-head applications. Singaporean shipyards are qualifying laser-powder-bed-fusion components for class society approval. This capability is compressing lead times for custom hydraulic profiles while reducing cavitation erosion rates in abrasive seawater service.
EPA Clean Water Act Section 316(b) thermal discharge monitoring is mandating real-time temperature logging at cooling water outfalls. Coastal power plants from California to Texas are retrofitting pump skids with embedded fiber-optic sensors. The instrumentation segment is capturing service revenue previously allocated to mechanical overhaul contracts.
Lifecycle service contracting is displacing transactional spare parts procurement in European port authorities. Rotterdam and Hamburg maintenance depots now specify ten-year availability guarantees for critical cooling pump assemblies. This model transfers inventory risk to OEM service networks while locking out third-party repair specialists.
Seawater Cooling Pumps Market Segmentation
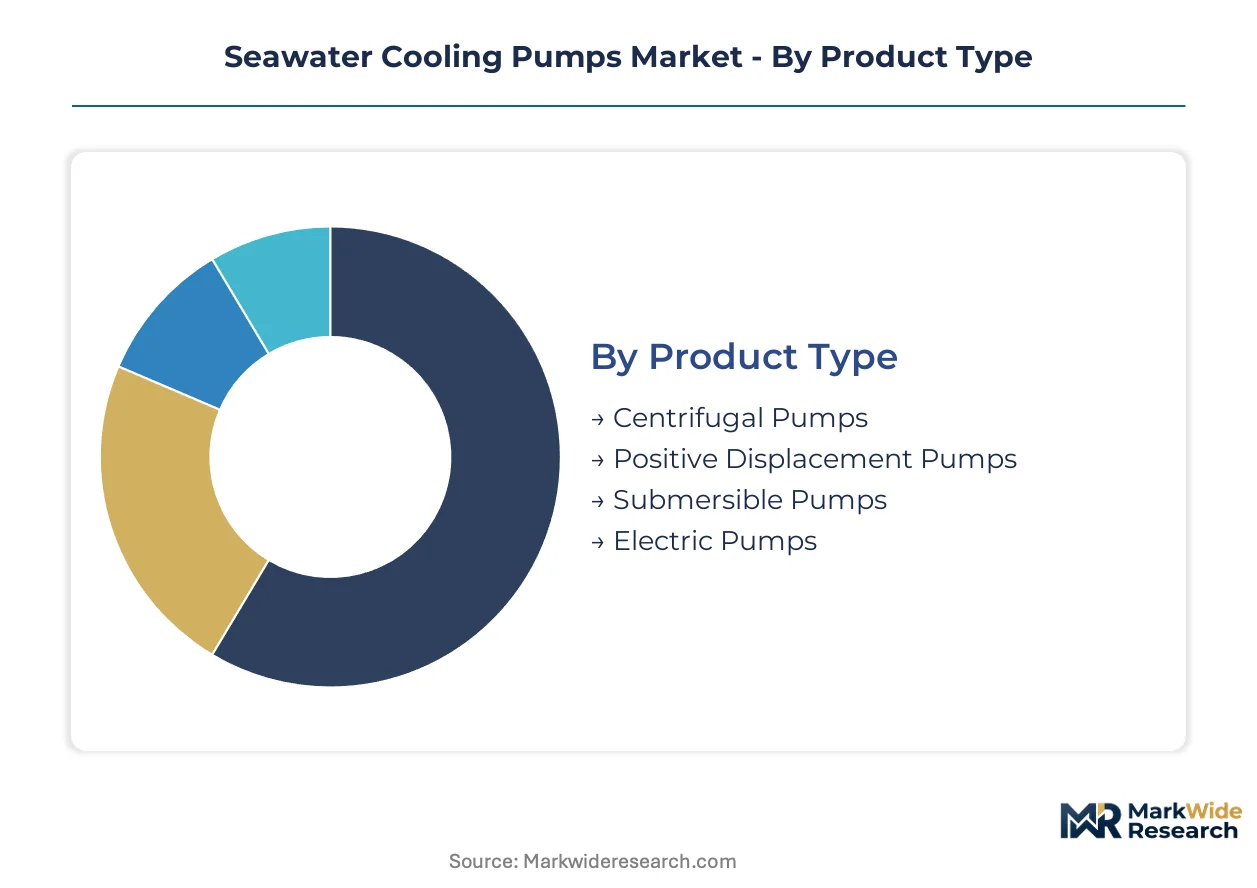
Seawater cooling pump procurement hinges on matching metallurgical specifications to chloride exposure severity and thermal duty cycles. Buyers segment selections by hydraulic configuration, corrosion resistance tier, and integration complexity with existing heat exchanger networks.
Product Type:
Capital expenditure tolerance and operational continuity requirements determine pump technology selection across coastal infrastructure portfolios.
- Centrifugal Pumps:Single-stage or multistage radial flow configurations dominate high-volume, low-head thermal transfer duties in coastal power plants. Procurement concentrates in China and India where state-backed generation capacity additions specify duplex stainless steel casings for 20-year service life.
- Submersible Pumps:Immersion-rated motors eliminate suction lift constraints in floating LNG terminals and deep-water aquaculture operations. Gulf of Mexico and West African project pipelines are driving specification of titanium-wet-end configurations rated for 300-meter submergence depth.
- Positive Displacement Pumps:Screw and lobe configurations handle high-viscosity cooling fluids with entrained solids in petrochemical refining loops.
- Electric Pumps:Standard induction motor drives serve auxiliary cooling circuits where variable-frequency control delivers marginal efficiency gains.
Centrifugal pumps lead on scale; submersible pumps lead on momentum.
Application:
Regulatory pressure on thermal discharge limits and vessel carbon intensity ratings is fragmenting demand across cooling duty specifications.
- Power Generation:Once-through cooling systems in coastal thermal plants require corrosion-resistant circulation pumps rated for continuous 8,000-hour annual operation. Procurement in China and Saudi Arabia focuses on super duplex alloy impellers resisting chloride-induced pitting at elevated temperatures.
- Marine Applications:Auxiliary cooling loops in cargo vessels and cruise ships face accelerated replacement cycles due to biofouling and cavitation wear. Singapore and Rotterdam shipyards are retrofitting pump skids to meet IMO 2023 carbon intensity grades ahead of dry-dock schedules.
- Industrial Cooling:Petrochemical and refining complexes specify heavy-duty configurations for process heat rejection duties.
- Aquaculture:Deep-water fish farm operations require low-maintenance submersible arrays for temperature regulation in offshore pens.
Power generation commands installed base volume; marine applications drive replacement frequency.
End User:
Contracting models and lifecycle cost accounting methods vary sharply across buyer categories with differing technical sophistication.
- Power Plants:State-owned utilities and independent power producers negotiate long-term service contracts with availability guarantees. Procurement in India and China emphasizes localized spare parts stocking and 24-hour response commitments.
- Oil & Gas:Offshore platform operators prioritize compact skid-mounted configurations minimizing footprint and weight. North Sea and Gulf of Mexico project specifications mandate API 610 compliance for critical cooling services.
- Shipping Companies:Container lines and tanker operators balance capital constraints against fuel efficiency gains from optimized cooling loop performance.
- Water Treatment Facilities:Desalination plant operators specify pumps compatible with high-salinity intake conditions and intermittent duty cycles.
Power plants lead on contract value; oil and gas leads on specification stringency.
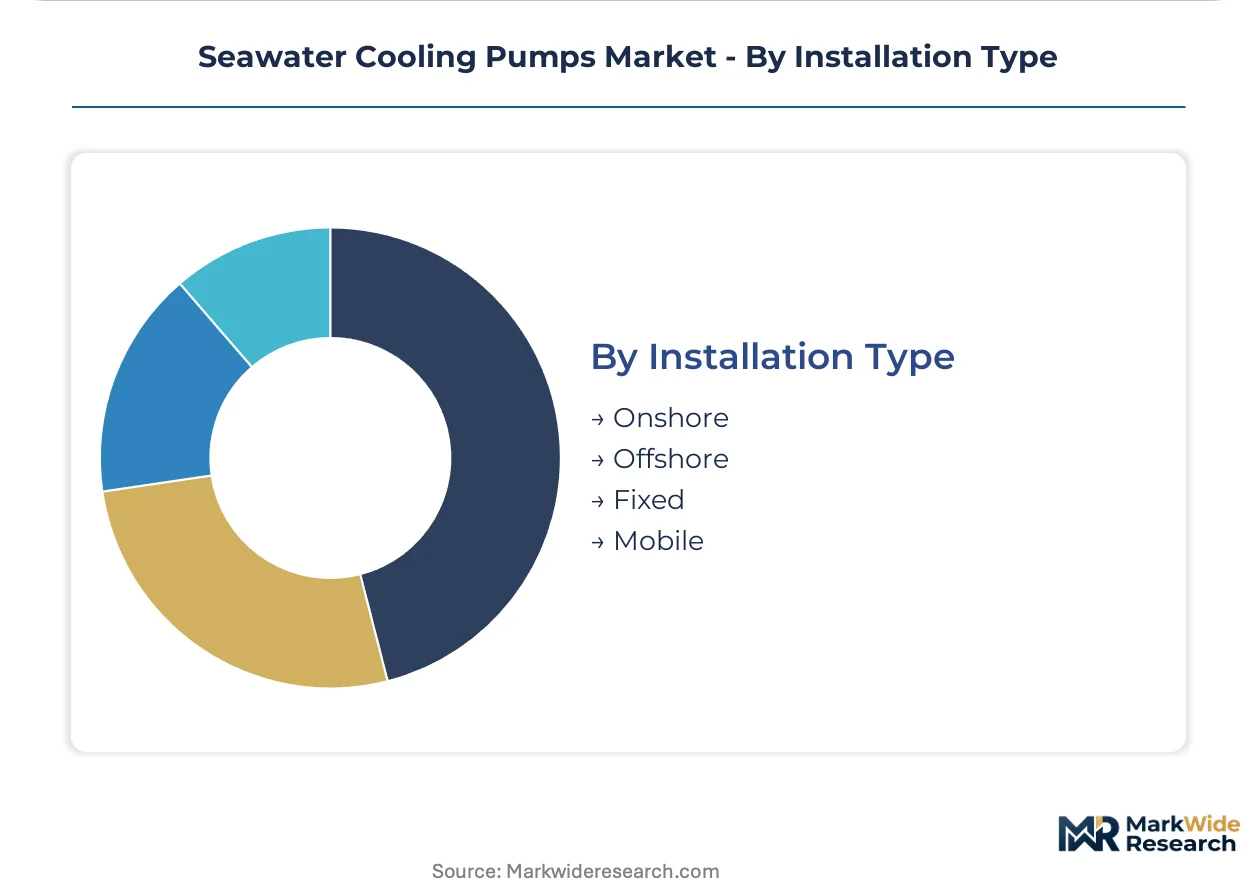
Installation Type:
Site constraints and mobility requirements dictate foundation, access, and maintenance protocol differences.
- Offshore:Platform-mounted and floating configurations require explosion-proof motor enclosures and corrosion protection systems rated for salt spray exposure. North Sea regulatory regimes mandate redundant pump arrangements for safety-critical cooling duties.
- Fixed:Permanent concrete foundation installations in coastal power plants optimize for vibration isolation and long-term alignment stability.
- Onshore:Land-based installations at port terminals and industrial parks allow conventional maintenance access and standard electrical supply configurations.
- Mobile:Trailer-mounted or barge-transportable pump skids serve temporary cooling needs during plant outages and emergency thermal management.
Fixed installations lead on cumulative revenue; offshore configurations lead on technical complexity premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seawater cooling pump manufacturing originated in European and Japanese heavy engineering clusters during the post-war expansion of coastal thermal power and maritime trade. These regions established the metallurgical and hydraulic design foundations that now define global product specifications.
China
State-backed port expansions in Ningbo-Zhoushan and nuclear cooling projects in Fujian province drive procurement of high-flow submersible configurations. The country's GB standards for offshore equipment mandate corrosion allowances that exceed legacy API specifications. Shanghai shipyards are retrofitting pump skids to meet IMO 2023 carbon intensity grades ahead of dry-dock schedules.
Japan
Titanium-alloy casting expertise concentrated in Osaka-Kobe industrial corridor supplies pump housings rated for 80,000 operating hours in chloride-rich environments. METI enforces JIS marine equipment standards that dictate minimum wall thicknesses for pumps installed in territorial waters. Yokohama and Nagasaki shipyards specify Japanese-origin pumps for auxiliary cooling loop retrofits.
United States
EPA Clean Water Act Section 316(b) thermal discharge rules are mandating real-time temperature logging at cooling water outfalls from California to Texas. Gulf of Mexico floating LNG terminals specify submersible configurations rated for 300-meter submergence depth. Port Arthur and Corpus Christi petrochemical complexes are retrofitting pump skids with embedded fiber-optic sensors.
Germany
Hermetic motor-winding capabilities for deep-rated submersible pumps concentrate in Baden-Württemberg and Bavarian specialty manufacturers. The EU F-Gas Regulation extends certification timelines for integrated cooling systems with refrigerant circuits interfacing seawater heat exchangers. Hamburg and Rotterdam maintenance depots now specify ten-year availability guarantees for critical cooling pump assemblies.
India
Jawaharlal Nehru Port Trust and Visakhapatnam expansion plans specify high-flow submersible arrays for berth-side thermal management. The Central Electricity Authority mandates localized spare parts stocking and 24-hour response commitments for coastal power plant contracts. Mundra and Hazira industrial corridors are scaling procurement of duplex stainless steel casings for 20-year service life.
Seawater Cooling Pumps Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive metallurgical capabilities. Japanese and European engineering groups anchor the premium tier through titanium casting expertise and modular drive integration. Mid-scale specialists compete on localized service networks spanning Mediterranean and Southeast Asian repair hubs. Dominant competitive moves include strategic partnerships with shipyard operators and geographic expansion through regional maintenance depot licensing.
Among diversified pump manufacturers, Ebara Corporation exemplifies the metallurgical-specialist archetype through its Japanese industrial heritage. Grundfos and Sulzer occupy positions within the European engineering tier, with Grundfos representing modular drive integration capabilities and Sulzer anchoring service-network breadth across coastal maintenance corridors. These three companies illustrate how competitive positioning fragments between material-science differentiation and aftermarket service density.
| Leading Market Players |
|---|
| Ebara Corporation |
| Grundfos |
| Sulzer |
| Flowserve |
| Xylem |
| KSB |
| Torishima Pump |
| Desmi |
| Sundyne |
| Others |
Value Network & Pricing Analysis
Orbital welders certified for duplex alloy fabrication cluster in Osaka-Kobe and Hamburg-Stuttgart corridors, creating labor-cost spreads that separate premium titanium-cast pump assemblies from standard duplex configurations.
Pricing Analysis
Project-based contracting with long-term service bundling dominates procurement for coastal power plants and floating LNG terminals. Price differentiation rests on metallurgical grade—super duplex impellers command premiums over standard duplex—and certification tier under JIS marine standards versus generic API compliance. Cost compression in mid-tier configurations is intensifying because Korean foundries have expanded titanium billet capacity. State-owned utilities in India and China exhibit highest price sensitivity due to localized spare parts mandates, while North Sea offshore operators show lowest sensitivity given API 610 compliance requirements.
Supply Chain Analysis
Refurbishment flows for hermetic submersible motors return to Baden-Württemberg and Swiss specialty manufacturers, creating reverse-logistics dependencies for deep-rated pump configurations. Manufacturing concentrates in Japan, Germany, and China, with titanium casting anchored in Osaka-Kobe and hermetic motor winding in southern Germany. Raw material feeds draw from Indonesian nickel ore, South African chromium, and Australian titanium sponge. Single-source vulnerability in hermetic motor suppliers creates structural risk. Distribution runs through shipyard-direct channels for marine retrofits and EPC contractor networks for power generation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
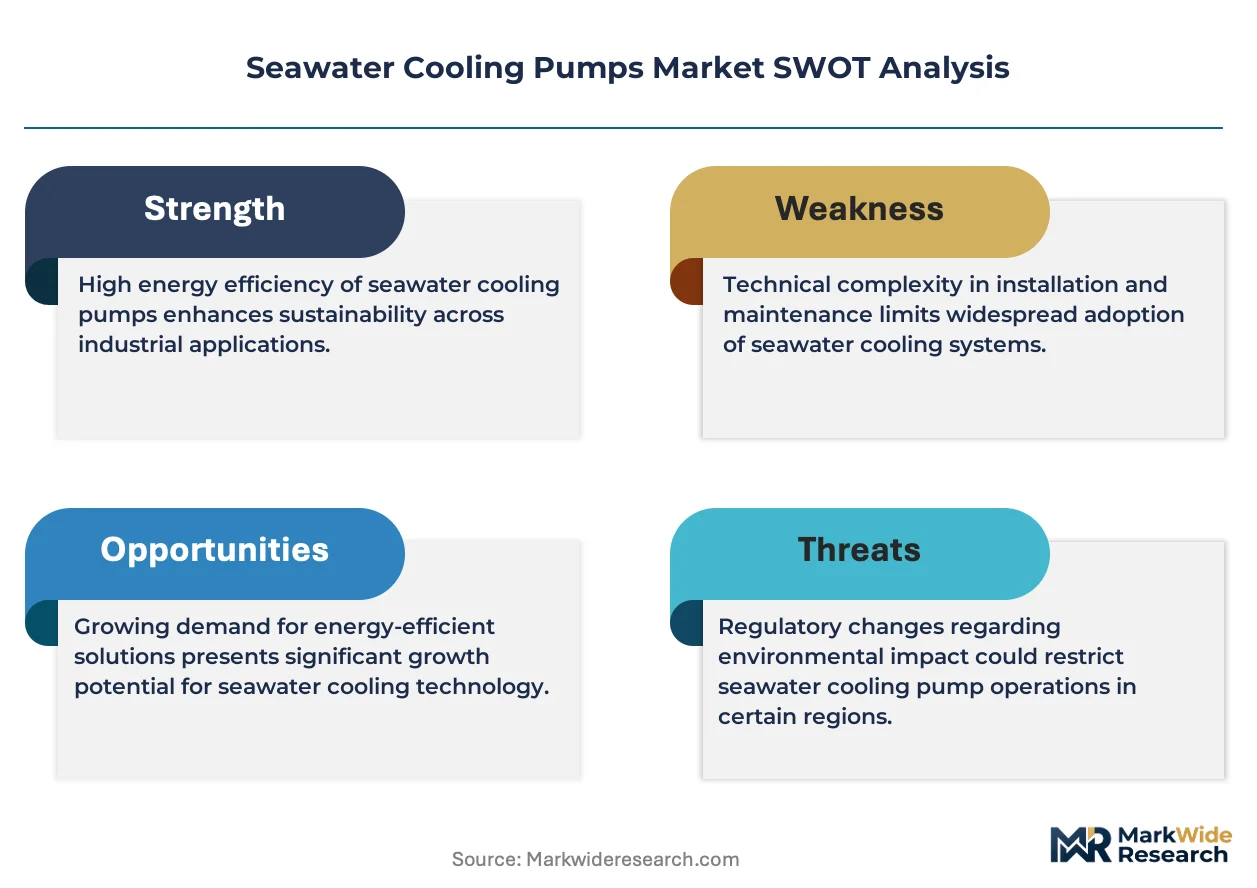
Titanium casting scale economies and permanent magnet motor integration are expanding margin capture in premium pump tiers, compressing cost structures for corrosion-resistant configurations.
For Market Incumbents: Deepen captive titanium-alloy casting capacity to defend against Korean foundry cost advantages in chloride-resistant pump housings. Extend localized service depot licensing across Mediterranean and Southeast Asian repair hubs to lock out third-party specialists. METI corrosion allowance mandates and EPA Section 316(b) thermal discharge rules favor incumbents with established certification pathways. For New Entrants and Emerging Players: Direct-to-shipyard digital procurement platforms offer lowest-friction entry for auxiliary cooling loop retrofits in Singapore and Rotterdam corridors. Target India's Jawaharlal Nehru Port Trust expansion specifications for high-flow submersible arrays. Partner with additive manufacturing specialists for laser-powder-bed-fusion impeller qualification to bypass titanium welding certification bottlenecks. For Investors and Strategic Acquirers: Diversified industrial conglomerates with captive metallurgical capabilities are the most active acquirer in this space, consolidating Japanese and European engineering groups. Five-to-ten year viability hinges on floating LNG terminal buildout momentum and offshore nuclear cooling program advancement. Monitor China state-backed floating reactor procurement announcements and Gulf of Mexico submersible pump contract awards as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Casting | Captive billet supply secures 80,000-hour service life ratings for Japanese shipyard specifications. |
| Permanent Magnet Motor Integration | Variable-frequency drive convergence cuts parasitic load in Mediterranean portside installations. |
| Additive Manufacturing Qualification | Singaporean laser-powder-bed-fusion capabilities compress custom hydraulic profile lead times. |
| Localized Service Depot Licensing | Ten-year availability guarantees in Rotterdam and Hamburg transfer inventory risk from port authorities. |
| Digital Twin Diagnostics Development | Predictive maintenance protocols overcome SCADA protocol mismatches in 1990s-era coastal power plants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged pump OEM product managers, shipyard procurement directors, coastal power plant maintenance engineers, and EPC contractor technical leads. Secondary validation drew from IMO DCS carbon reporting filings, EPA Clean Water Act Section 316(b) compliance databases, METI JIS standard publications, and customs trade records for titanium alloy and super duplex stainless steel billet flows. Bottom-up project pipeline aggregation and top-down industrial capacity assessment were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to documented installation cycles and regulatory compliance deadlines across maritime and power generation sectors. Segmentation dimensions modeled include pump configuration type, metallurgical grade tier, application duty cycle, and regional regulatory cluster. CAGRs were derived from installed base replacement frequency analysis and newbuild contract flow tracking. Forecast inputs incorporated IMO 2023 carbon intensity grade enforcement timelines and floating LNG terminal project advancement rates.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing of titanium impellers would alter the outlook. Forecasts reflect assumptions regarding nickel alloy price stability and hermetic motor supplier concentration. Practitioners should monitor Indonesian ore export quota announcements and China offshore nuclear cooling program procurement triggers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market