
 Industrial Pumps Market | 2026-2036
Industrial Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Pumps Market Intelligence
The EU Green Deal's focus on industrial energy efficiency is restructuring the cost-of-entry, favoring manufacturers capable of producing high-performance, low-emission pumps. Xylem leverages its deep expertise in water and wastewater applications to meet these evolving standards. Sulzer Ltd differentiates with specialized solutions for demanding chemical processing and energy sector environments. KSB SE & Co. KGaA sustains its market position with a comprehensive product portfolio serving diverse industrial end-users across multiple geographies.
Industrial pumps are mechanical devices that transfer fluids by converting rotational energy into hydraulic flow. Their construction often involves materials like stainless steel or specialized polymers to handle corrosive or abrasive substances at specific pressure and temperature ratings. Centrifugal pumps represent the largest product segment, widely used in water treatment and power generation. In contrast, positive displacement pumps, such as diaphragm and gear types, are critical for chemical processing where precise fluid metering is essential.
Regulatory frameworks, including EPA guidelines in the United States and the EU's Machinery Directive, govern pump safety and energy efficiency. Concurrently, standards like ISO 5199 and API 610 set stringent technical specifications for pumps used in demanding oil refining and chemical processing applications. The key decision for procurers involves assessing total cost of ownership, weighing upfront capital expenditure against long-term energy and maintenance expenses.
Market Dynamics
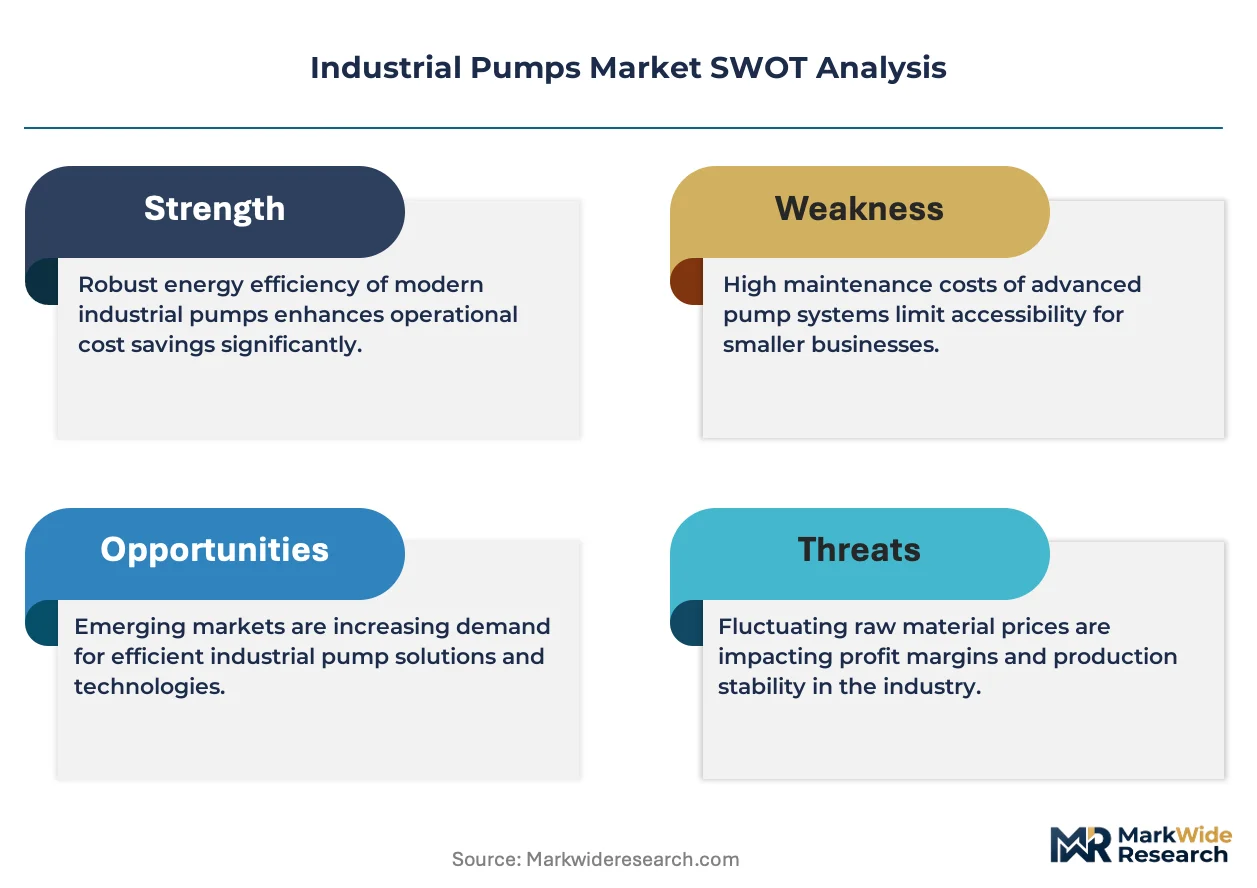
The industrial pump market's evolution is governed by a fundamental tension between rising energy efficiency mandates and the capital investment cycles of heavy industry. This dynamic forces manufacturers to innovate on hydraulic performance while compelling end-users to adopt a total cost of ownership model.
Growth Catalysts
- Water Infrastructure Modernization:Government-led initiatives to upgrade and expand municipal water and wastewater treatment facilities, particularly in developing Asian economies, create a consistent demand for centrifugal and positive displacement pumps.
- Stringent Environmental Regulations:Policies like the EU's F-Gas Regulation and Industrial Emissions Directive compel operators in chemical and power generation sectors to invest in newer, low-leakage and high-efficiency pump systems to meet compliance targets.
- Chemical Sector Expansion:Sustained growth in China's specialty chemical processing industry creates a significant demand for corrosion-resistant pumps capable of handling aggressive and hazardous fluids with high precision.
Market Restraints
- High Input Material Cost Volatility:Fluctuations in the prices of raw materials such as stainless steel, nickel alloys, and specialized polymers directly impact manufacturing costs and can compress profit margins for pump producers.
- Long Replacement Cycles in Brownfield Sites:The high cost and operational disruption associated with retrofitting legacy industrial facilities with modern, dimensionally different pump systems slows the adoption rate of new technologies.
- Intense Price Competition:The presence of numerous regional and local manufacturers for standard pump configurations creates intense price pressure, particularly in the general industrial and agricultural segments.
Strategic Opportunities
- Pumps for Energy Transition:The development of applications like green hydrogen production, carbon capture and storage (CCUS), and battery manufacturing creates new demand for specialized pumps designed for novel fluids and extreme operating conditions.
- Digitalization and Service-Based Models:Integrating sensors and IoT connectivity into pumps enables predictive maintenance and performance optimization services, creating recurring revenue streams beyond the initial hardware sale.
- High-Purity Pharmaceutical Applications:Growth in biopharmaceutical manufacturing requires highly specialized, sterile, and sanitary pumps, opening a high-margin niche for manufacturers who can meet stringent validation and certification requirements.
Industry Challenges
- Skilled Labor Shortages:A widening gap exists for technicians skilled in installing, maintaining, and diagnosing issues with modern, electronically controlled smart pump systems, impacting after-sales service quality.
- Navigating Global Standards:Manufacturers face complexity and high costs in certifying products to meet a diverse array of international and regional standards, such as API 610 for oil and gas and ISO 5199 for chemical processing.
- System Integration Complexity:Integrating advanced smart pumps and their proprietary control software with existing, often decades-old, plant-level automation and SCADA systems presents a significant technical hurdle for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Pumps Market |
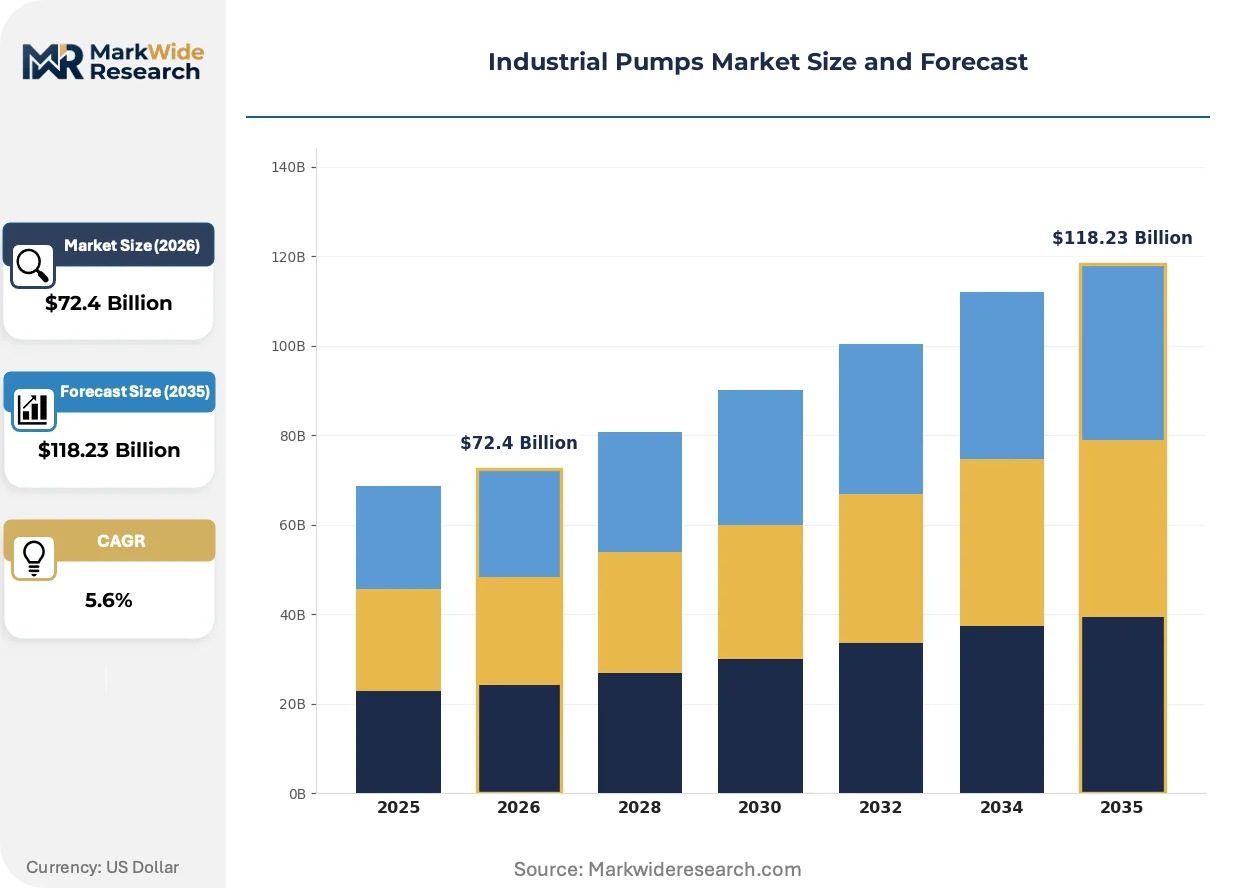
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $118.23 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Diaphragm, Gear, Piston, Vane, Lobe Technology: Magnetic Drive, Mechanical Seal, Submersible, Vertical Turbine, Positive Displacement, Seal-less Application: Water Treatment, Chemical Processing, HVAC Systems, Oil Refining, Power Generation, Food Processing End User: Manufacturing Plants, Municipal Facilities, Energy Providers, Construction Firms, Agro-industries, Pharmaceutical Producers |
| Companies Covered | KSB SE & Co. KGaA, Flowserve Corporation, Ingersoll Rand, Pentair, Grundfos Holding A/S, Xylem, Ebara Corporation, The Weir Group, Sulzer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Pumps Market Strategic Shifts & Innovations
The convergence of advanced materials science, digital controls, and fluid dynamics modeling is redefining pump performance. This evolution is driven by industrial end-users' dual imperatives to reduce energy consumption and improve process reliability through data-driven insights.
Smart pumps incorporate onboard sensors and variable frequency drives (VFDs) to dynamically optimize performance based on real-time system demand. The water and wastewater treatment sector is a primary adopter, seeking to minimize energy costs which are a major operational expense. This advanced mechanical functionality is converging with cloud-based IIoT platforms, enabling fleet-wide remote monitoring and predictive failure analysis.
Regulations focused on energy efficiency are a primary market accelerator. The European Union's Ecodesign Directive, for example, establishes stringent minimum efficiency requirements for various types of water pumps sold within the bloc. This forces manufacturers to innovate in hydraulic design and motor technology, effectively removing less efficient products from the market. The building services and light industrial sectors are most impacted, driving a significant replacement cycle for older, non-compliant equipment.
A notable shift in buyer behavior is the move toward evaluating equipment based on Total Cost of Ownership (TCO) over initial purchase price. This trend diminishes the influence of traditional distribution channels focused on volume and price, favoring direct engagement with manufacturers who can provide verifiable data on long-term energy and maintenance costs. This TCO-centric procurement model is most prevalent within the mining and municipal water industries, where pump energy consumption is a critical operational expenditure.
Industrial Pumps Market Segmentation
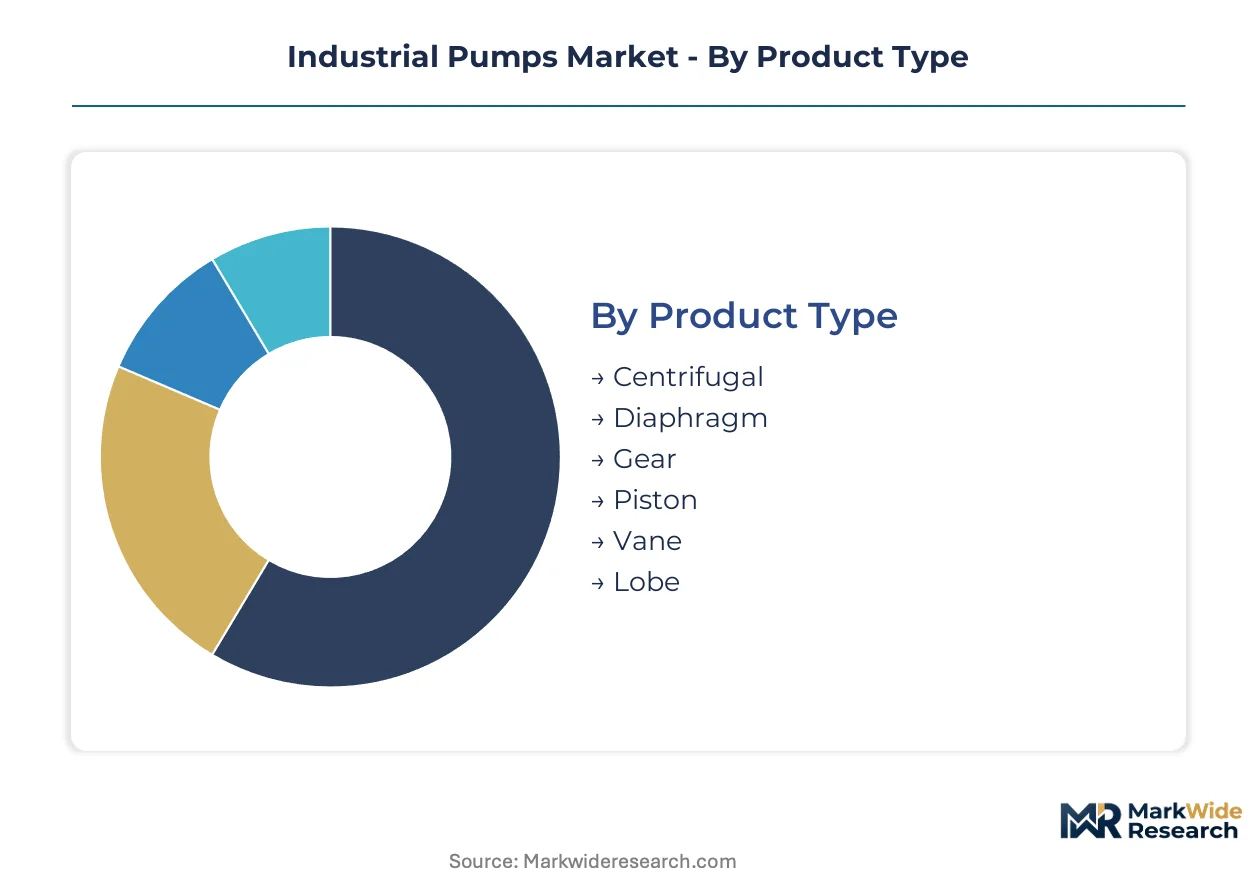
The industrial pumps market segmentation offers a granular view of product diversity, technological advancements, and end-user demands. Understanding these distinctions is critical for manufacturers to tailor their offerings and for procurers to optimize their total cost of ownership. This analysis highlights the specialized requirements across various industrial applications.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, general-purpose pumps to custom-engineered solutions for specific fluid dynamics. This differentiation dictates manufacturing complexity and market reach for industrial pump producers.
- Centrifugal:These pumps use an impeller to impart velocity to fluid, converting kinetic energy into pressure. Widely used in municipal water treatment facilities, they support large-scale fluid transfer.
- Diaphragm:Diaphragm pumps employ a reciprocating diaphragm to displace fluid, offering precise metering and chemical resistance. Demand concentrates in China's chemical processing industry for aggressive fluids.
- Gear:Gear pumps use rotating gears to transfer viscous fluids, applied in oil and gas for lubrication.
- Piston:Piston pumps use a reciprocating piston for high-pressure applications, common in hydraulic systems.
- Vane:Vane pumps use a rotating rotor with vanes to move low-viscosity fluids in fuel transfer.
- Lobe:Lobe pumps feature rotating lobes for gentle handling of shear-sensitive fluids, important in food processing.
Most installed capacity flows through Centrifugal pumps. Expansion is steepest in Diaphragm pumps.
Technology:
Performance characteristics define the technology segments, ranging from basic sealing mechanisms to advanced fluid handling systems. Manufacturers invest in these technologies to meet evolving operational demands and regulatory compliance.
- Magnetic Drive:Magnetic drive pumps eliminate mechanical seals, using magnetic coupling to prevent leakage. EU's F-Gas Regulation drives demand for these low-leakage, high-efficiency systems.
- Seal-less:Seal-less pump designs prevent fluid escape, crucial for hazardous liquids. These technologies gain traction in chemical processing for stringent emissions and operational safety.
- Mechanical Seal:Mechanical seal technology uses rotating and stationary faces to contain fluid, a common sealing solution.
- Submersible:Submersible pumps operate fully immersed in fluid, used in wastewater pumping stations and deep wells.
- Vertical Turbine:Vertical turbine pumps feature a long shaft and multiple impellers for high-volume water supply.
- Positive Displacement:Positive displacement technology traps a fixed amount of fluid, ensuring precise flow control in chemical metering.
Innovation within these technologies primarily targets energy efficiency. Demand is shifting towards Seal-less and Magnetic Drive systems.
Application:
Application segments reflect the diverse and specific operational needs across various industrial sectors. Each application demands tailored pump characteristics for fluid compatibility, pressure, and flow rates.
- Water Treatment:This application involves pumping water through purification and distribution stages. The water treatment sector adopts smart pumps to minimize energy costs, a major operational expense.
- Chemical Processing:Chemical processing requires pumps to handle corrosive, abrasive, and hazardous chemicals at specific temperatures. Growth in China's specialty chemical industry drives demand for corrosion-resistant pump solutions.
- HVAC Systems:HVAC systems use pumps for circulating chilled or heated water in commercial buildings.
- Oil Refining:Oil refining demands robust pumps handling crude oil and process fluids under high pressure, adhering to API 610 standards.
- Power Generation:Power generation facilities utilize pumps for cooling water, boiler feed, and ash handling, requiring high reliability.
- Food Processing:Food processing applications require sanitary pumps meeting strict hygiene standards for transferring edible liquids.
The largest volume of pumps serves Water Treatment. Specialized requirements are driving growth in Chemical Processing.
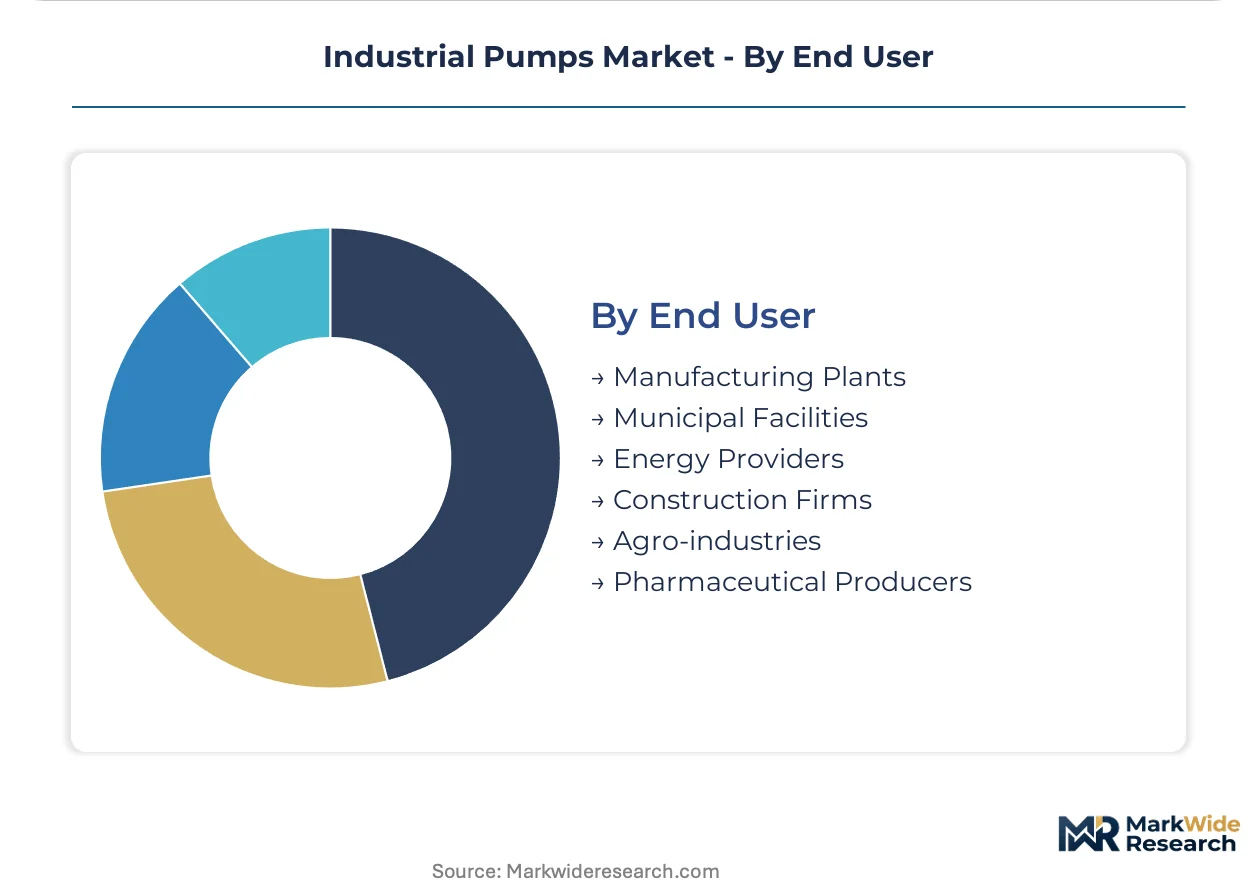
End User:
End-user categories delineate the scale and complexity of pump deployments, from large-scale municipal infrastructure to precision-driven pharmaceutical production. Each end-user group prioritizes different factors, including capital cost, reliability, and maintenance.
- Municipal Facilities:Municipal facilities manage public water supply, wastewater treatment, and storm drainage. Government initiatives to upgrade water infrastructure drive consistent pump demand.
- Pharmaceutical Producers:Pharmaceutical producers require highly specialized, sterile, and sanitary pumps for drug manufacturing, demanding stringent validation. Biopharmaceutical growth creates a high-margin niche.
- Manufacturing Plants:Manufacturing plants use pumps for process fluid transfer and utility services, requiring versatile equipment.
- Energy Providers:Energy providers use pumps for critical fluid movement in production and cooling systems.
- Construction Firms:Construction firms deploy pumps for dewatering excavations and concrete pumping on job sites.
- Agro-industries:Agro-industries use pumps for irrigation, fertilizer application, and livestock watering.
Significant procurement volumes originate from Municipal Facilities. High-value niches are emerging within Pharmaceutical Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial pump market's foundational technologies, particularly early centrifugal designs, first scaled significantly with the advent of large-scale manufacturing and municipal water systems in the 19th century. Early innovators in Europe and North America established initial production hubs. This historical lineage continues to influence regional market dynamics.
United States
Demand for industrial pumps accelerates from ongoing infrastructure projects, particularly in municipal water and wastewater treatment. EPA guidelines and the Infrastructure Investment and Jobs Act drive significant investments in upgrading aging systems. Large-scale water utilities and industrial complexes across states like California and Texas require a continuous supply of specialized pumps.
Germany
Europe's largest economy, Germany, maintains a strong demand for high-efficiency and low-emission pumps, driven by its robust manufacturing sector. The EU Ecodesign Directive mandates stringent energy efficiency standards for industrial equipment, including pumps. Industrial clusters in Bavaria and North Rhine-Westphalia are key procurement centers for advanced pumping solutions.
China
Growth in China's chemical processing and water infrastructure sectors creates substantial demand for industrial pumps. China's dual carbon goals and stricter environmental protection laws compel industries to adopt more efficient and compliant pumping systems. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta drive significant pump installations and replacements.
India
India's rapid urbanization and industrialization fuel the demand for pumps in water management, power generation, and manufacturing. Government initiatives like the Jal Jeevan Mission and "Make in India" incentivize domestic production and infrastructure development. Major industrial corridors in Maharashtra and Gujarat are experiencing heightened activity in pump procurement.
Japan
Precision manufacturing and an aging infrastructure base contribute to a steady demand for high-quality and reliable industrial pumps. METI regulations and ISO standards ensure a focus on energy efficiency and operational safety across industries. Advanced manufacturing facilities in the Kanto and Kansai regions prioritize pumps with long service lives and minimal maintenance.
Industrial Pumps Market Key Industry Players
The competitive structure tilts toward established global players offering comprehensive product portfolios and specialized engineering expertise. The industrial pumps market exhibits a tiered structure, with large multinational corporations dominating high-value segments and numerous regional manufacturers competing in standard configurations. Portfolio diversification and strategic partnerships are dominant competitive moves among the larger entities, seeking to expand their reach into emerging applications.
Within the global tier, companies like KSB SE & Co. KGaA and Flowserve Corporation exemplify manufacturers with extensive product ranges and deep application knowledge across diverse industrial end-users. Sulzer Ltd occupies a position as a specialist, providing highly engineered solutions for demanding environments such as chemical processing and energy sectors. These entities leverage their long-standing reputations and global distribution networks to maintain their market positions, often serving as preferred suppliers for critical infrastructure projects and advanced industrial applications globally.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| Flowserve Corporation |
| Ingersoll Rand |
| Pentair |
| Grundfos Holding A/S |
| Xylem |
| Ebara Corporation |
| The Weir Group |
| Sulzer Ltd |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and publicly traded corporations influence the industrial pump market's supply behavior and pricing discipline. Their investment strategies in R&D and manufacturing capacity directly impact market stability.
Pricing Analysis
Hybrid project-based and contract-based pricing structures define the industrial pump market. Price differentiation stems from specialized certifications like API 610 and ISO 5199, customization for demanding applications, and bundled after-sales service. Intense price competition in standard pump configurations exerts downward pressure on margins. Municipal Facilities and general industrial segments exhibit higher price sensitivity compared to Pharmaceutical Producers or chemical processing.
Supply Chain Analysis
Raw material supply for industrial pumps relies heavily on global sources for stainless steel, nickel alloys, and specialized polymers. Production concentration for advanced pump components is strongest in Germany, China, and Japan. Commodity price volatility for these critical inputs presents a significant supply chain risk. Distribution runs through a dual model, with direct engagement for specialized solutions and traditional channels for standard products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial pumps market acts as a regulatory compounder, with the EU Green Deal's focus on energy efficiency driving consistent demand for high-performance, low-emission systems. Stricter environmental rules compel continuous investment in compliant pump technologies.
For Market Incumbents: Cement market leadership through targeted R&D in smart pump technologies and advanced materials for extreme conditions. Diversify product portfolios to address new energy transition applications like green hydrogen production. Investing in certifications for emerging standards helps counter margin pressure from intense price competition. Vertical integration into critical component manufacturing can mitigate raw material cost volatility.
For New Entrants and Emerging Players: Capture niche opportunities by developing highly specialized pumps for high-purity pharmaceutical applications, a segment with stringent validation requirements. Penetrate underserved regional markets in developing Asian economies with cost-effective, energy-efficient solutions for municipal water infrastructure. A service-based model focusing on predictive maintenance and performance optimization offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional manufacturers with strong intellectual property in niche applications but limited global reach. The long-term viability of the market is underpinned by continuous infrastructure modernization and evolving environmental mandates. Acquisition targets should focus on specialists in digitalization capabilities or advanced material science. The signal to watch is the acceleration of green hydrogen or CCUS project funding, indicating new high-value pump demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addressing growing demand from China's chemical processing industry requires increased manufacturing output. |
| Green Manufacturing Transition | Adhering to the EU Ecodesign Directive mandates sustainable production processes for pumps. |
| Joint Venture | Partnering with IoT specialists enhances smart pump capabilities for predictive maintenance services. |
| Technology Licensing | Acquiring licenses for advanced hydraulic designs improves pump energy efficiency and performance. |
| Certification Investment | Securing API 610 or ISO 5199 compliance opens access to demanding oil refining and chemical processing markets. |
Research Approach
Direct dialogue with plant managers, OEM procurement teams, and aftermarket service heads provided qualitative grounding for this study. This primary research was validated through extensive secondary data from industry association reports, government regulatory filings, and academic journals. Bottom-up data aggregation and top-down market sizing ensured comprehensive and accurate market insights.
Volume and value projections were generated across the analysis window through a robust quantitative modeling framework. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected technological adoption rates. Infrastructure spending data and raw material price forecasts served as key inputs.
Raw material price volatility, shifts in environmental regulations, and global economic slowdowns are the dominant revision risks for market forecasts. Projections reflect current market conditions and documented assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market