
 Water Desalination Pumps Market | 2026-2036
Water Desalination Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Water Desalination Pumps Market Outlook
The capital-intensity divergence between integrated manufacturers and component assemblers is unwinding competitive stability in water desalination pumps. Xylem Inc. leverages its vertical control over smart monitoring systems to command premium positioning in reverse osmosis installations. Ebara Corporation anchors its presence through specialized high-pressure centrifugal designs optimized for Middle Eastern salinity conditions. Flowserve Corporation competes by sustaining engineering-intensive service networks across coastal industrial zones.
Water desalination pumps are mechanical devices engineered to deliver pressurized seawater or brackish water through membrane or thermal separation systems, typically operating at discharge pressures exceeding 55 bar for reverse osmosis trains and constructed from super-duplex stainless steel or titanium alloys to withstand chloride corrosion. Centrifugal pumps dominate installed capacity due to their scalability across municipal and power generation applications, while positive displacement configurations capture specialized niches in high-pressure, variable-salinity environments. Reverse osmosis technology commands the largest technology segment share because of its energy efficiency relative to thermal distillation methods. Submersible pump designs are gaining traction in offshore intake structures and deep-well brackish sources where surface footprint constraints apply.
The EPA regulates concentrate discharge and intake structure impingement under the Clean Water Act, compelling U.S. operators to specify pumps with reduced ecological impact and enhanced efficiency metrics. In Europe, the Ecodesign Directive and REACH chemical compliance frameworks shape material selection and motor efficiency standards for pump manufacturers serving Mediterranean desalination plants. Saudi Arabia's Saline Water Conversion Corporation and Australia's National Water Commission enforce procurement standards that favor energy recovery integration. Stakeholders must monitor how evolving efficiency mandates and carbon-border adjustments will reshape supplier qualification criteria across major desalination corridors.
Market Dynamics
Energy recovery device integration is compressing the total cost of ownership for high-pressure pump systems, forcing manufacturers to redesign hydraulic architectures around isobaric chamber technology rather than standalone centrifugal units.
Growth Catalysts
- EPA discharge mandates:Tighter Clean Water Act standards for concentrate management are compelling U.S. coastal utilities to upgrade intake and brine handling infrastructure.
- Saudi Arabia's megaproject pipeline:Saline Water Conversion Corporation procurement schedules are sustaining demand for large-capacity high-pressure trains across Jubail and Yanbu industrial clusters.
- Super-duplex metallurgy advances:Improved casting techniques for chloride-resistant alloys are extending mean time between failures in Red Sea and Arabian Gulf installations.
Market Restraints
- Super-alloy supply concentration:Super-duplex stainless steel production concentrates in European and Japanese specialty mills, exposing pump fabricators to nickel and molybdenum price volatility.
- Membrane fouling interdependency:Pump performance degrades nonlinearly with pretreatment failures, creating warranty liability disputes between pump OEMs and membrane suppliers.
- Thermal distillation legacy lock-in:Existing multi-stage flash capacity in Kuwait and Qatar slows reverse osmosis retrofit cycles despite superior energy efficiency.
Strategic Opportunities
- Offshore floating desalination:Submersible pump architectures for deep-water intake structures are opening deployment models beyond coastal land constraints.
- EU Green Deal industrial water:Carbon-border adjustment mechanisms are incentivizing Mediterranean chemical processors to replace freshwater abstraction with treated seawater.
- Digital twin integration:Real-time hydraulic modeling combined with predictive vibration analytics is creating aftermarket service revenue streams.
Industry Challenges
- Corrosion engineering specialization:The shallow talent pool for super-duplex welding and cavitation-resistant impeller design extends commissioning timelines.
- Cross-supplier system integration:Energy recovery devices from independent vendors require proprietary control interfaces, complicating SCADA harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Desalination Pumps Market |
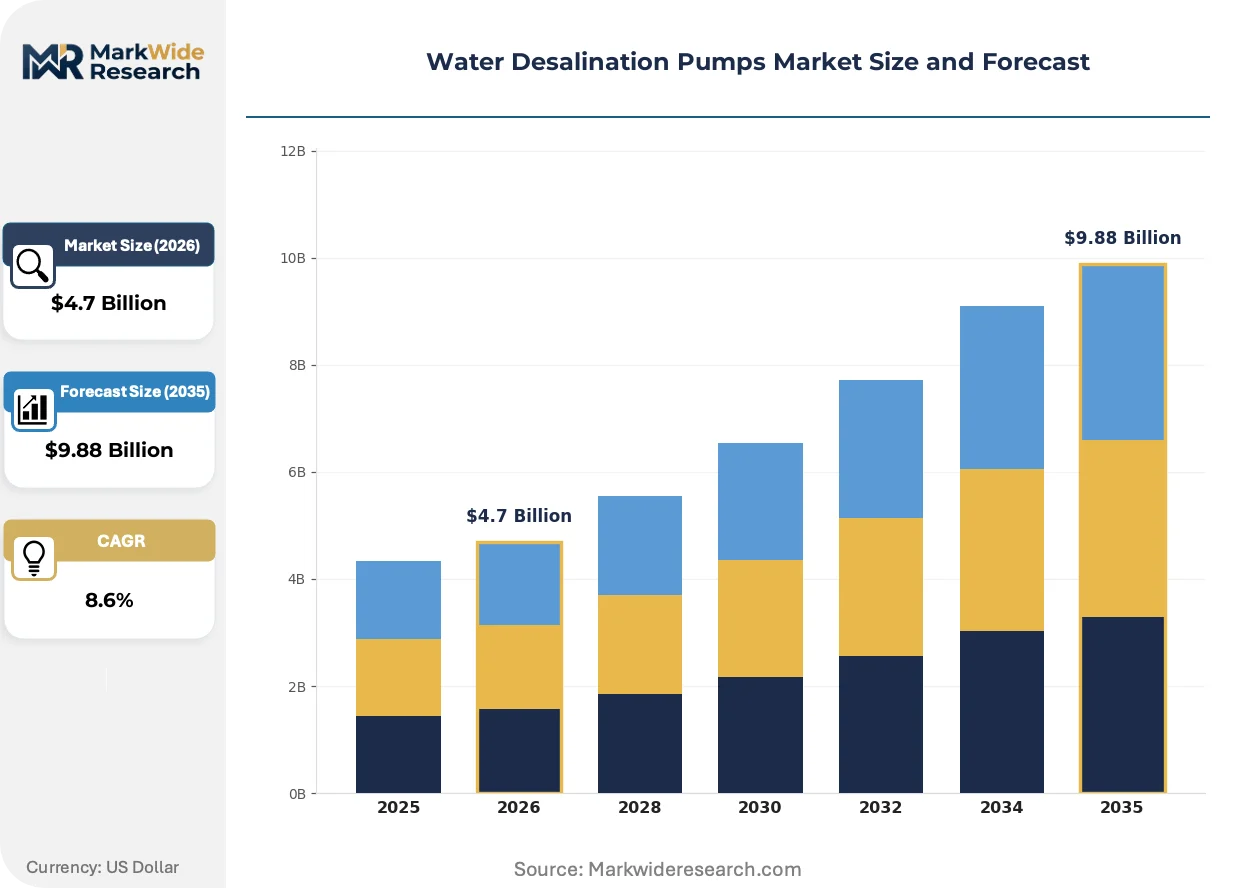
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Positive Displacement, Centrifugal, Submersible, Diaphragm Application: Municipal, Industrial, Agricultural, Power Generation End User: Utility Providers, Oil & Gas, Mining, Agriculture Technology: Reverse Osmosis, Multi-Stage Flash, Multi-Effect Distillation, Electrodialysis |
| Companies Covered | Xylem Inc., Ebara Corporation, Flowserve Corporation, GEA Group, Weir Group, Grundfos, KSB, Alfa Laval AB, Sulzer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Desalination Pumps Market Strategic Shifts
Digitalization of hydraulic performance monitoring is converging with materials science advances to redefine reliability benchmarks. Equipment buyers now specify integrated condition-monitoring as a procurement prerequisite rather than an aftermarket add-on.
Isobaric energy recovery devices are displacing traditional Pelton wheel turbines in large-scale reverse osmosis trains. Saudi Arabia's SWCC and California's coastal utilities specify isobaric chambers for newbuild projects above ten million gallons per day capacity. The technology is displacing conventional high-pressure pump configurations by reducing specific energy consumption below two kilowatt-hours per cubic meter.
REACH chemical compliance frameworks are restricting hexavalent chromium surface treatments for pump housings and fasteners. European fabricators are migrating to trivalent chrome and plasma electrolytic oxidation coatings for Mediterranean plant deliveries. The Ecodesign Directive's extended motor efficiency tiers are accelerating permanent magnet synchronous motor adoption in Spanish and Italian desalination corridors.
Lifecycle service contracting is replacing transactional spare parts procurement among Middle Eastern operators. Saudi Aramco and ADNOC subsidiary water utilities now bundle twenty-year pump maintenance into initial capital awards. This model concentrates vendor selection authority with engineering-procurement-construction firms rather than municipal procurement departments.
Water Desalination Pumps Market Segmentation
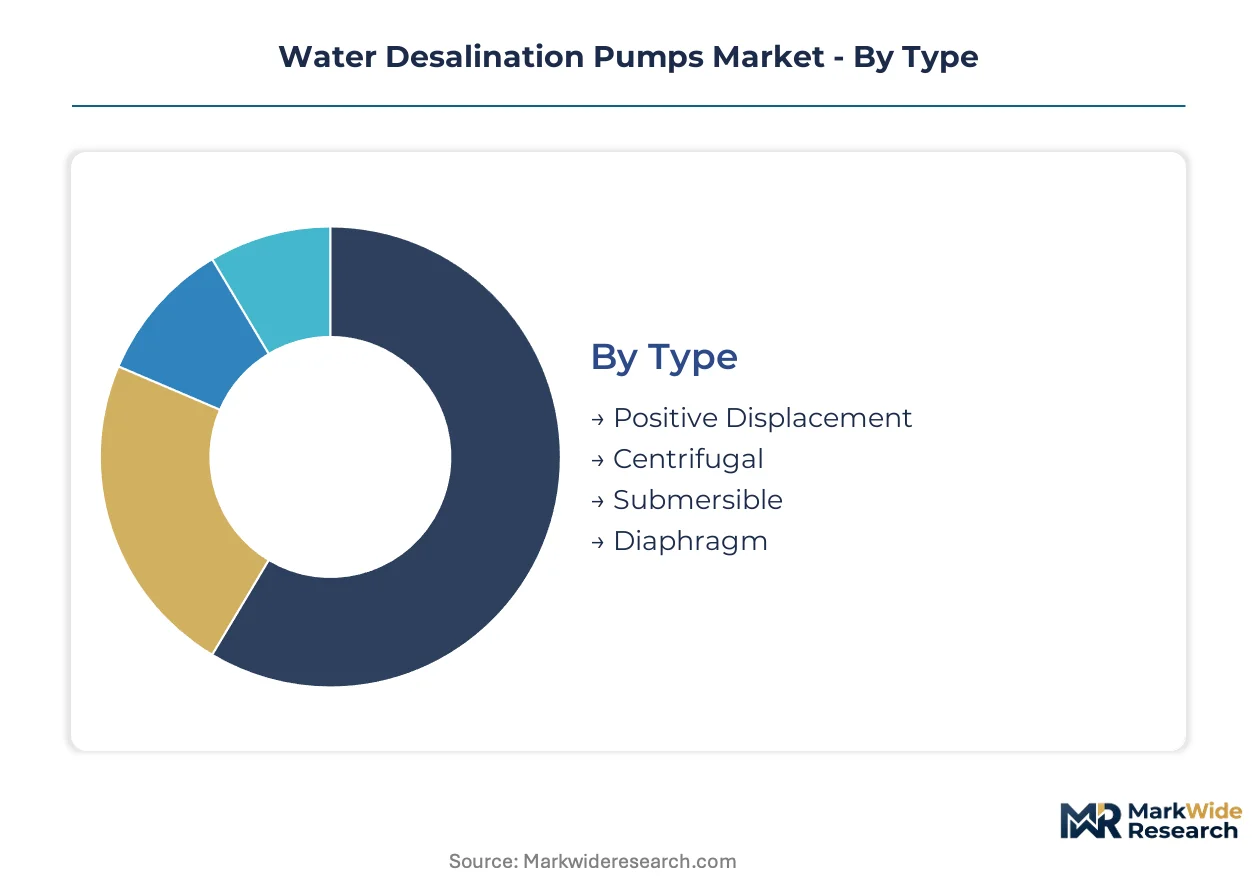
Pump specification varies sharply by salinity source, pressure regime, and duty cycle. Segmentation reveals where metallurgy investments concentrate and which hydraulic architectures dominate procurement tenders across desalination corridors.
Type:
Domestic fabrication concentrates on centrifugal and submersible designs for coastal utilities, while positive displacement and diaphragm pumps flow through specialized export channels serving offshore platforms and remote mining sites.
- Positive Displacement:Reciprocating or rotary mechanisms deliver precise flow control at extreme pressures exceeding 70 bar. Demand clusters in Middle Eastern oilfield waterflooding operations where variable-salinity brine requires pressure flexibility. Saudi Aramco's produced-water treatment specifications favor these configurations for high-recovery reverse osmosis trains.
- Centrifugal:Radial or mixed-flow impellers generate high-volume throughput at moderate pressure rises, constructed from super-duplex stainless steel for chloride resistance. Municipal utilities across California, Texas, and Florida specify these for seawater reverse osmosis plants above five million gallons per day capacity. Energy recovery device integration is compressing specific energy consumption below two kilowatt-hours per cubic meter.
- Submersible:Motor-pump units operate submerged in intake wells or offshore caissons, eliminating suction lift limitations. Deployment is expanding in deep-well brackish sources beneath the Ogallala Aquifer and Red Sea offshore structures.
- Diaphragm:Sealless positive displacement designs isolate process fluid from mechanical components through elastomeric membranes. Chemical dosing and pretreatment skids at Australian and Spanish plants specify these for precise antiscalant injection.
Centrifugal designs command the established base. The steepest expansion runs through submersible architectures.
Application:
Cost tiering separates premium-specification industrial installations from standardized municipal procurement, with agricultural and power generation applications occupying intermediate positions on capital intensity and lifecycle service bundling.
- Municipal:Large-scale potable water production for urban distribution networks, typically exceeding ten million gallons per day. Procurement in Saudi Arabia, UAE, and Chile favors twenty-year service contracts bundled with initial capital awards. EPA discharge mandates under the Clean Water Act are redirecting U.S. coastal utility capital toward intake structure upgrades and efficient high-pressure trains.
- Industrial:Process water for chemical manufacturing, refining, and mineral processing where purity specifications exceed municipal standards. Mediterranean chemical processors under EU carbon-border adjustment mechanisms are replacing freshwater abstraction with treated seawater, expanding demand for corrosion-resistant pump specifications.
- Agricultural:Irrigation supply from brackish groundwater or coastal desalination for high-value crop production. Israel's national water carrier and California's Central Valley operators specify mid-pressure centrifugal trains for greenhouse and orchard applications.
- Power Generation:Boiler feedwater and cooling system makeup for thermal and nuclear plants. Gulf Cooperation Council countries integrate desalination with power production in cogeneration facilities, specifying pumps rated for continuous duty at 55-65 bar discharge pressure.
Municipal installations anchor procurement volume. Industrial applications are climbing the fastest on chemical sector water stress.
End User:
Customer type determines specification authority—utility providers centralize engineering standards while oil and gas operators demand field-proven configurations for remote deployment.
- Utility Providers:Municipal and regional water authorities with centralized procurement departments and standardized technical specifications. Saudi Arabia's Saline Water Conversion Corporation and Spain's Aqualia enforce energy recovery integration and permanent magnet motor efficiency tiers through tender requirements.
- Oil & Gas:Upstream and downstream operators requiring produced water treatment and injection systems. Specifications prioritize mean time between failures in high-sand, high-H2S environments across Permian Basin and North Sea installations.
- Mining:Mineral extraction operations in water-stressed jurisdictions requiring process water and dust suppression supply. Chilean copper concentrators and Australian iron ore operators specify submersible intake pumps for pit dewatering and desalination feed.
- Agriculture:Large-scale irrigation districts and agribusiness operations with decentralized decision-making. Procurement concentrates in Israel, Spain, and Australia's Murray-Darling Basin on mid-size reverse osmosis trains with simplified maintenance protocols.
Utility providers dominate specification authority. Mining end users are expanding most quickly on lithium extraction water demand.
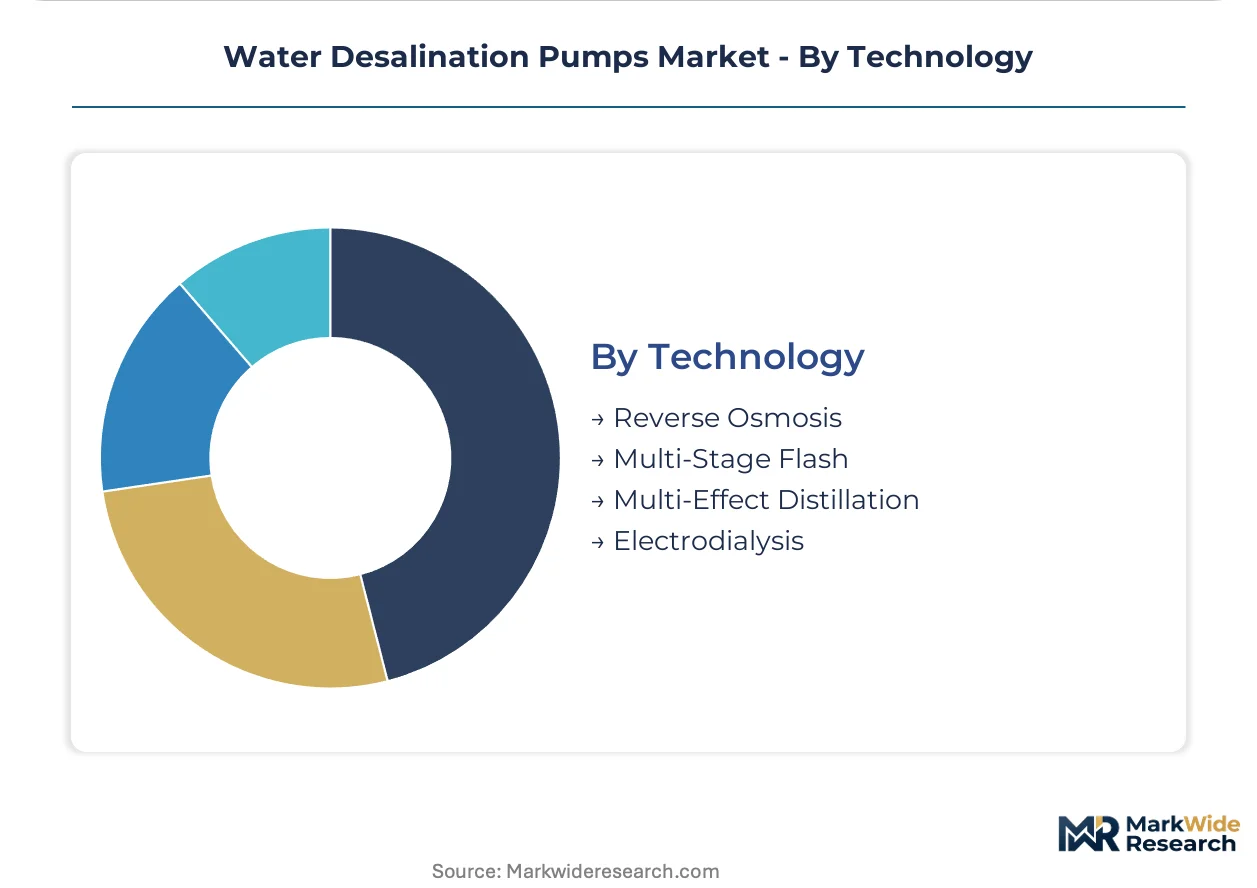
Technology:
Maturity gradients separate established thermal distillation from membrane-based expansion, with electrodialysis capturing specialized niches in brackish water and industrial process streams.
- Reverse Osmosis:Semi-permeable membrane separation driven by high-pressure pumps at 55-70 bar, now the dominant technology for new capacity. Isobaric energy recovery devices are displacing Pelton wheel turbines in SWCC and California utility specifications above ten million gallons per day, reducing specific energy consumption below two kilowatt-hours per cubic meter.
- Multi-Stage Flash:Thermal distillation through successive pressure-reduction chambers, legacy capacity concentrated in Kuwait, Qatar, and UAE. Existing installations sustain pump maintenance demand but retrofit cycles lag reverse osmosis adoption despite inferior energy efficiency.
- Multi-Effect Distillation:Lower-temperature thermal evaporation with multiple reuse of vapor heat, common in cogeneration facilities. Specifications require specialized vacuum pumps and brine circulation pumps rated for high-temperature chloride service.
- Electrodialysis:Ion-exchange membrane separation driven by direct current, effective for brackish water with moderate salinity. Niche applications in Japan's industrial water recycling and China's zero-liquid-discharge installations favor this technology for its selective ion removal capability.
Reverse osmosis commands the established base. Electrodialysis is gaining share fastest on industrial zero-liquid-discharge expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pump procurement in Saudi Arabia commands pricing premiums that Gulf fabricators cannot match, while Spanish and Italian suppliers compete on efficiency compliance within EU regulatory corridors.
United States
California's coastal utilities and Texas drought-response programs drive municipal capacity expansion. EPA discharge mandates under the Clean Water Act compel intake structure upgrades and high-pressure train efficiency improvements. The Colorado River Basin and Central Valley clusters specify corrosion-resistant specifications for brackish groundwater projects.
Saudi Arabia
Saline Water Conversion Corporation procurement schedules sustain demand for large-capacity high-pressure trains. The kingdom's national water regulator enforces energy recovery integration and permanent magnet motor efficiency tiers through tender requirements. Jubail and Yanbu industrial clusters anchor fabrication demand for super-duplex metallurgy installations.
Spain
Mediterranean chemical processors under EU carbon-border adjustment mechanisms replace freshwater abstraction with treated seawater. The Ecodesign Directive and REACH chemical compliance frameworks shape material selection and motor efficiency standards. Catalonia and Valencia desalination corridors accelerate permanent magnet synchronous motor adoption.
Australia
Murray-Darling Basin irrigation districts and lithium extraction operations expand brackish water processing demand. The National Water Commission enforces procurement standards favoring energy recovery integration. Western Australian mining clusters and South Australian agricultural zones specify submersible intake architectures for pit dewatering applications.
United Arab Emirates
Abu Dhabi and Dubai utility authorities bundle long-term service contracts into initial capital awards for reverse osmosis capacity. MOHAP procurement guidelines emphasize lifecycle cost optimization over upfront capital minimization. The Al Taweelah and Jebel Ali industrial zones concentrate demand for continuous-duty high-pressure specifications.
Water Desalination Pumps Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with engineering-intensive specialists commanding premium positioning while scale-driven fabricators compete on throughput efficiency. The vendor base concentrates around three strategic tiers: integrated smart-system providers, metallurgy-focused specialists, and service-network anchors. Dominant competitive moves include backward integration into energy recovery device architectures and geographic expansion through engineering-procurement-construction partnership structures.
Among vertically integrated pump manufacturers, Xylem Inc. and Ebara Corporation exemplify divergent specialization paths. Xylem anchors premium positioning through captive control over monitoring and control systems. Ebara occupies a fabrication-focused tier optimized for high-salinity corrosion resistance. Flowserve Corporation represents the service-network archetype, sustaining presence through coastal industrial zone coverage rather than manufacturing scale advantages.
| Leading Market Players |
|---|
| Xylem Inc. |
| Ebara Corporation |
| Flowserve Corporation |
| GEA Group |
| Weir Group |
| Grundfos |
| KSB |
| Alfa Laval AB |
| Sulzer |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at European super-duplex foundries shapes both supply concentration and price floors for high-pressure pump fabricators. Scale advantages in chloride-resistant alloy casting concentrate procurement leverage among Middle Eastern utilities, compressing margins for component assemblers while integrated manufacturers capture premium positioning through captive metallurgy control.
Pricing Analysis
Configured-to-order pricing for super-duplex high-pressure trains commands spreads exceeding standard catalog centrifugal units by substantial margins. Project-based contracting dominates municipal procurement in Saudi Arabia and California, with price differentiation driven by certification grade and after-sales service bundling. Cost compression in mid-tier centrifugal configurations is intensifying because Chinese fabricators are expanding export capacity for standardized designs. Utility providers exhibit lowest price sensitivity due to twenty-year lifecycle cost mandates, while agricultural operators in Australia's Murray-Darling Basin prioritize upfront capital minimization.
Supply Chain Analysis
Sweden and Germany anchor super-duplex stainless steel production for chloride-resistant pump housings, while Japan specializes in precision casting for high-pressure impellers. Fabrication draws from nickel and molybdenum feedstocks concentrated in Indonesian and Chilean extraction operations. Single-source vulnerability runs through European specialty mills exposed to energy cost volatility. Distribution runs through engineering-procurement-construction consortiums that bundle pump supply with installation and long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Saudi Arabia's Saline Water Conversion Corporation and California's coastal utility alliances, fragmenting specification authority away from municipal procurement departments toward centralized engineering standards.
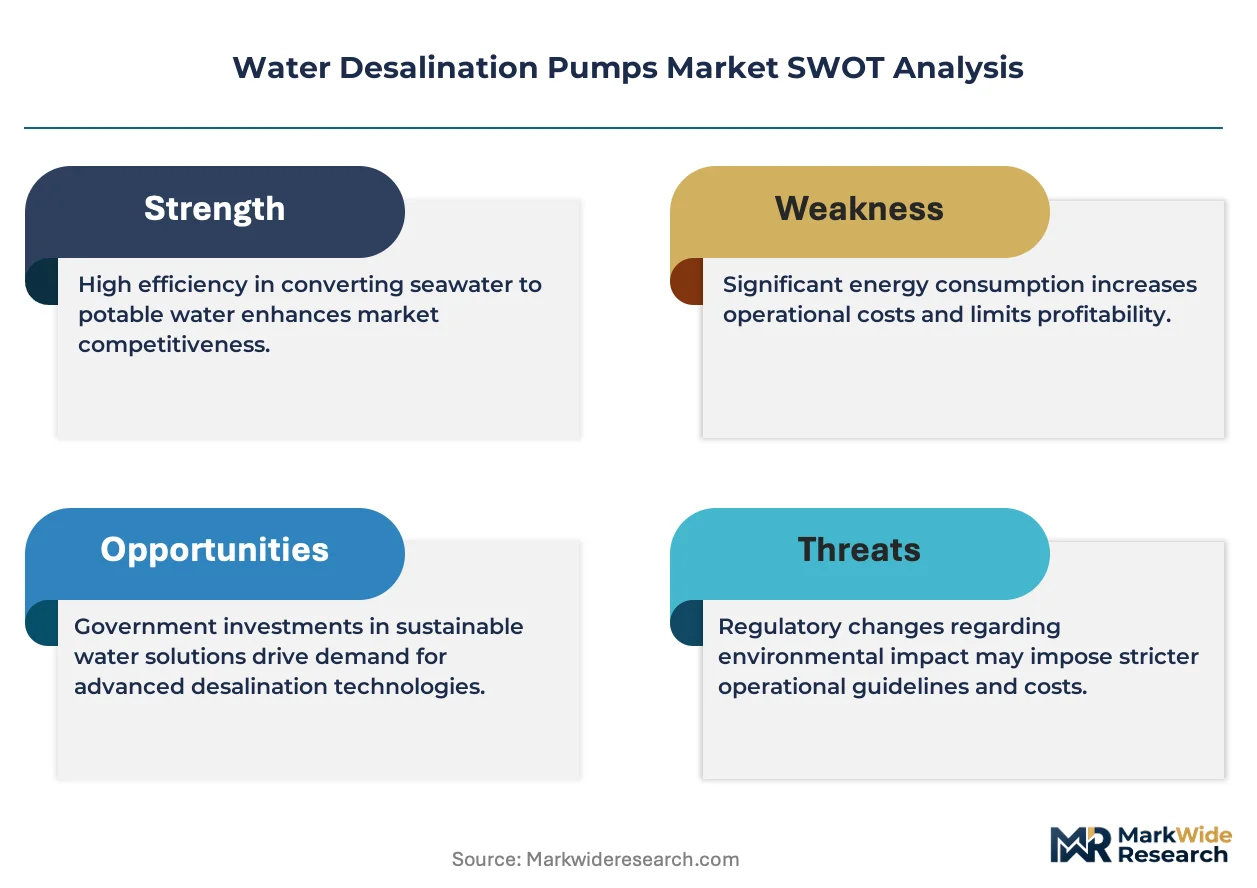
For Market Incumbents: Fortify metallurgy capabilities through backward integration into super-duplex casting operations or exclusive offtake agreements with European specialty mills. Deepen service network density across Gulf Cooperation Council industrial zones to capture lifecycle maintenance contracts that Saudi Aramco and ADNOC subsidiaries now bundle into initial capital awards. Energy recovery device vendors with proprietary control interfaces pose substitution threats to standalone pump manufacturers. For New Entrants and Emerging Players: Aftermarket digital twin integration represents a service-layer gap where incumbents under-serve smaller Australian mining operators and Spanish agricultural cooperatives. Target submersible pump architectures for offshore floating desalination projects, where deployment models are decoupling from coastal land constraints. Pursue partnership structures with Mediterranean engineering-procurement-construction firms to bypass entrenched supplier relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with captive energy recovery device architectures over pure-play pump fabricators. Long-term viability hinges on isobaric chamber integration capabilities and permanent magnet motor efficiency compliance across EU regulatory corridors. Monitor SWCC tender specifications for mandatory digital twin inclusion as an inflection indicator for aftermarket service valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Super-Duplex Casting | Captive metallurgy supply secures margin control against nickel price volatility from Indonesian extraction operations. |
| Isobaric Energy Recovery Device Development | Proprietary chamber designs reduce specific energy consumption below SWCC efficiency thresholds for Jubail megaprojects. |
| Digital Twin Platform Deployment | Real-time hydraulic modeling creates recurring revenue streams from California utilities mandating predictive maintenance. |
| Permanent Magnet Motor Certification | Ecodesign Directive compliance unlocks Spanish and Italian municipal procurement corridors for high-efficiency specifications. |
| Offshore Submersible Architecture Expansion | Deep-water intake designs access floating desalination projects beyond coastal land constraints in Red Sea developments. |
Study Parameters
The analysis maps centrifugal, positive displacement, submersible, and diaphragm pump architectures, each validated through engineering-procurement-construction contractors, municipal utility procurement directors, and aftermarket service managers. Primary interviews with plant engineers at Saudi Aramco water subsidiaries and California coastal utilities combined with secondary validation against EPA discharge filings, SWCC tender documentation, and EU Ecodesign Directive implementation reports. Bottom-up unit economics and top-down capacity installation data triangulate market sizing across technology segments.
Consistency checks validated volume and value outputs against desalination capacity databases and regional utility capital expenditure disclosures. The analytical framework models pump type, application tier, end-user category, and technology architecture across the projection horizon. CAGRs derive from installed base replacement cycles and newbuild procurement schedules. Forecast inputs incorporate SWCC megaproject pipelines, EPA Clean Water Act enforcement timelines, and EU carbon-border adjustment mechanism implementation.
Underlying assumptions cover energy recovery device adoption rates and super-duplex alloy price stability, with deviation risk concentrated in nickel supply disruptions and membrane fouling warranty liability disputes. Recalibration cycles align with material shifts in SWCC procurement specifications and EPA discharge standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Intelligent Pump Market