
 Europe Sealants Market | 2026-2036
Europe Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sealants Market Foresight
CE marking under the Construction Products Regulation is reorganizing competitive access across the Europe Sealants Market, forcing reformulation investments that favor incumbents with established testing infrastructure. Sika AG leverages its Swiss lab network and construction chemical integration to sustain premium positioning in structural glazing applications. Henkel AG & Co. KGaA anchors its position through automotive OEM certification depth, while Wacker Chemie AG specializes in silicone feedstock control that extends from raw silane to finished building sealants.
Sealants are polymeric compounds engineered to fill joints and gaps with specified elongation at break, tensile strength, and adhesion to substrates including concrete, metal, glass, and polymer composites; they cure through moisture reaction, UV initiation, or solvent evaporation to form flexible, weather-resistant barriers against air, water, and chemical ingress. Silicone formulations dominate facade and glazing installations where movement accommodation exceeds 25% joint width, while polyurethane competes aggressively in construction bonding where paintability and substrate versatility command specification priority. Acrylic retains cost-driven share in interior caulking and DIY renovation, though margin pools concentrate in contractor-grade hybrid polymers that merge silicone durability with polyurethane handling characteristics.
EMA's chemical safety assessments, REACH substance restrictions, and the EU Green Deal's embodied carbon tracking are collectively elevating compliance costs and accelerating bio-based feedstock development among formulators. The F-Gas Regulation's phase-down of fluorinated blowing agents further redirects polyurethane system R&D toward pentane and hydrofluoroolefin alternatives. Stakeholders must monitor how the EU AI Act's pending conformity assessment protocols may digitize supply chain traceability requirements and reshape procurement qualification workflows.
Market Dynamics
The EU Green Deal's building renovation targets are compressing specification cycles and forcing formulators to requalify entire product lines for low-VOC, high-durability performance. CE marking under the Construction Products Regulation now gates market access, concentrating procurement among suppliers with established testing infrastructure.
Growth Catalysts
- Energy retrofit mandates:The EU Green Deal's building renovation targets are accelerating silicone and polyurethane procurement across Germany, France, and the Netherlands as commercial stock upgrades for thermal efficiency.
- REACH compliance protocols:Chemical substance restrictions are filtering out non-compliant suppliers and concentrating demand among formulators with advanced reformulation capabilities.
- Solar integration programs:Italy and Spain are expanding specialty sealant consumption through residential solar mounting system specifications requiring weather-resistant jointing solutions.
Market Restraints
- Silane feedstock volatility:Raw material costs for silicone precursors fluctuate with energy prices, compressing margins for non-integrated formulators.
- F-Gas Regulation phase-down:Fluorinated blowing agent restrictions are forcing polyurethane system R&D pivots toward pentane and hydrofluoroolefin alternatives, extending development timelines.
- Hybrid polymer substitution:Acrylic formulations retain cost-driven share in interior applications, limiting premium pricing power for advanced chemistries in DIY renovation channels.
Strategic Opportunities
- Bio-based feedstock development:EMA chemical safety assessments and embodied carbon tracking are creating first-mover advantages for formulators investing in renewable polymer precursors.
- Hybrid polymer convergence:Silicone-polyurethane blends that merge durability with paintability are opening specification opportunities in contractor-grade construction bonding.
- Digital traceability infrastructure:The pending EU AI Act conformity assessment protocols are creating competitive differentiation for suppliers with digitized supply chain verification systems.
Industry Challenges
- CE marking certification timelines:Construction Products Regulation testing protocols extend product launch cycles, requiring sustained capital commitment to qualification infrastructure.
- Reformulation skill scarcity:Low-VOC, high-performance chemistry expertise concentrates among senior formulators, constraining R&D throughput for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sealants Market |
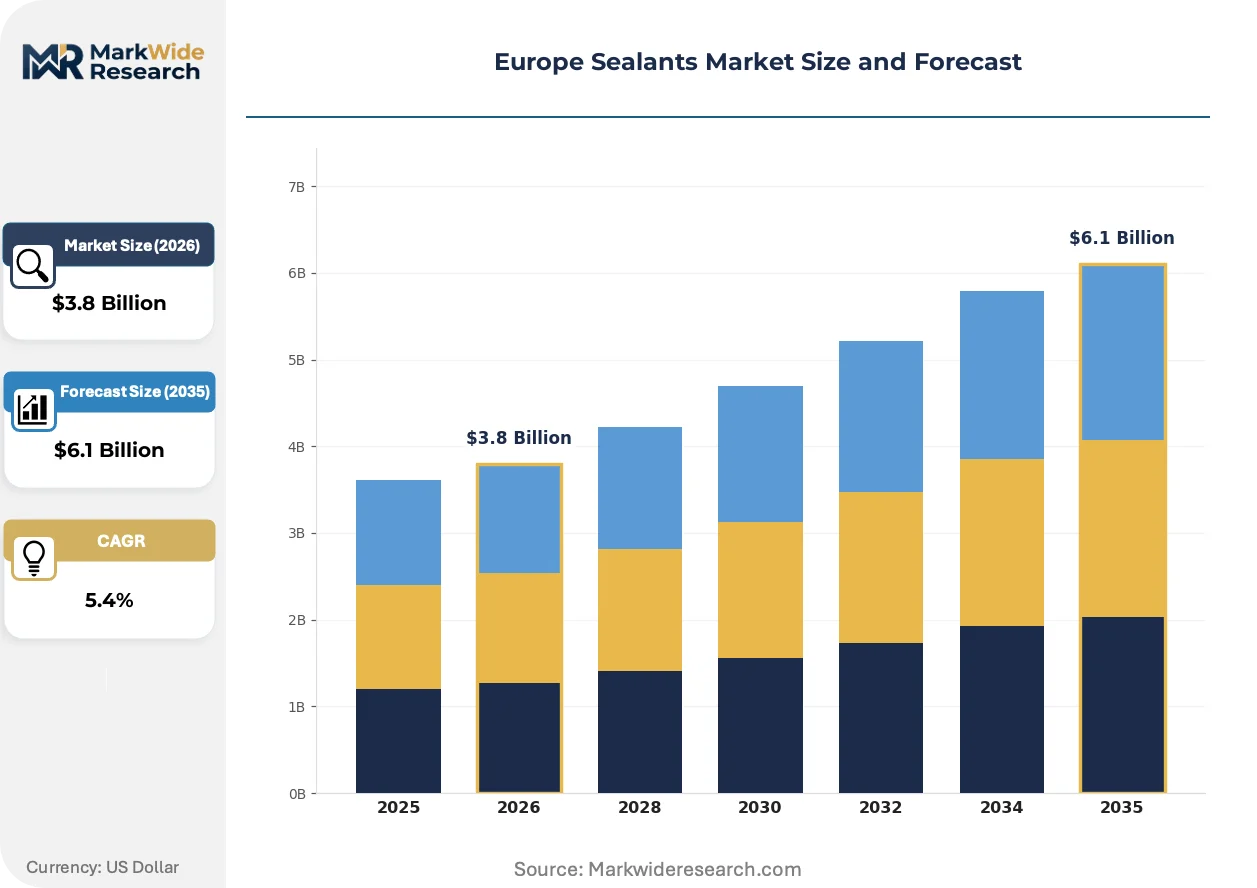
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Butyl Application: Construction, Automotive, Consumer Goods, Electronics End User: Manufacturers, Contractors, DIY Enthusiasts, Distributors Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, 3M, Arkema, Dow, H.B. Fuller Company, BASF, RPM International, Wacker Chemie AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sealants Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-based and hybrid architectures as regulatory pressure intensifies. Digital traceability and automated specification tools are compressing traditional procurement workflows across European construction supply chains.
Hybrid polymer sealants are fragmenting traditional silicone-polyurethane category boundaries by combining movement accommodation exceeding 25% joint width with paintable, substrate-versatile handling. German and Dutch facade contractors are specifying these formulations at accelerating rates for commercial glazing retrofits. The technology is fragmenting incumbent supplier positions by enabling mid-tier formulators to compete on performance without captive silane production.
REACH substance restrictions and the F-Gas Regulation are forcing systematic reformulation investments across polyurethane and silicone product lines. Industrial consequence includes extended R&D cycles and elevated compliance costs that favor suppliers with integrated testing infrastructure. Construction-grade formulations face the most acute pressure, with formulators redirecting development resources toward pentane-based blowing agents and bio-derived polymer backbones.
Buyer concentration among large European construction groups is compressing traditional distribution tiers and forcing direct specification relationships with formulators. National distributors in France and Spain are losing volume to manufacturer-direct technical sales teams that embed in project design phases. Germany exhibits the most pronounced channel consolidation, where major retrofit programs centralize procurement through engineering-procurement-construction consortiums.
Europe Sealants Market Segmentation
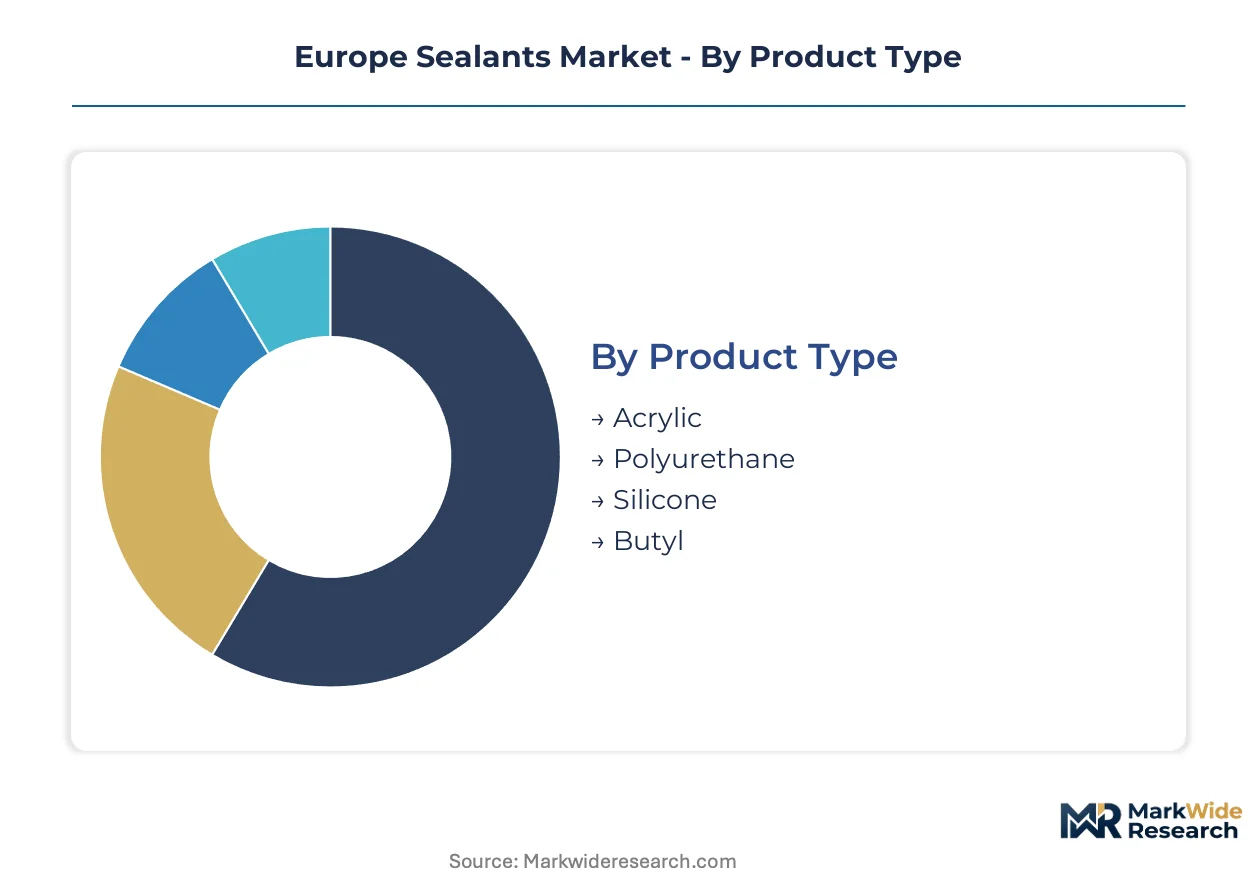
Segmentation in the Europe Sealants Market reveals how regulatory pressure and specification complexity are redistributing volume across chemistry types and procurement channels. CE marking requirements and REACH compliance are filtering supplier access, concentrating procurement among segments with established certification infrastructure.
Product Type:
Domestic production of silicone and polyurethane dominates supply to Germany, France, and the Netherlands, while acrylic and butyl volumes increasingly serve export markets through distributor networks in Italy and Spain.
- Silicone:Moisture-curing polysiloxane formulations deliver movement accommodation exceeding 25% joint width with UV-stable weather resistance. Demand concentrates in German and Dutch commercial glazing retrofits where the EU Green Deal's energy efficiency mandates specify high-durability facade jointing. REACH substance restrictions are forcing systematic reformulation of plasticizer packages.
- Polyurethane:Isocyanate-terminated prepolymers cure through atmospheric moisture to form paintable, substrate-versatile bonds with high tensile strength. French and Italian construction bonding applications specify these formulations where thermal insulation attachment requires structural adhesion. The F-Gas Regulation's fluorinated blowing agent phase-down is redirecting R&D toward pentane-based systems.
- Acrylic:Water-based emulsions cure through solvent evaporation to form cost-effective interior seals with limited movement accommodation. Primarily serves DIY renovation channels in Spain and residential caulking specifications.
- Butyl:Synthetic rubber formulations provide permanent tack and vapor barrier performance in pre-compressed tape configurations. Specialized demand runs through automotive glazing and industrial membrane applications.
Silicone commands the established base. The steepest expansion runs through polyurethane as pentane-based formulations achieve qualification.
Application:
Construction procurement absorbs the majority of contractor-grade volume, while automotive and electronics specifications concentrate technical sales resources on OEM certification programs.
- Construction:Structural glazing, facade jointing, and thermal insulation bonding specifications dominate procurement across German and French commercial retrofit programs. CE marking under the Construction Products Regulation gates market access, forcing sustained capital commitment to testing infrastructure.
- Automotive:Direct glazing, seam sealing, and NVH management applications require OEM certification depth and just-in-time supply capability. Henkel AG & Co. KGaA anchors position through tier-1 supplier relationships.
- Consumer Goods:Appliance assembly and furniture manufacturing specify fast-curing formulations with cosmetic finish requirements. Italian manufacturers drive specification through design-integrated procurement.
- Electronics:Potting and encapsulation applications demand ultra-low outgassing and thermal conductivity control. Swiss and German precision manufacturing clusters concentrate demand.
Construction absorbs the volume base. Electronics is gaining share fastest through miniaturization-driven specification density.
End User:
Contractor procurement is consolidating through engineering-procurement-construction consortiums, while DIY channels fragment across national distributor networks.
- Manufacturers:Industrial OEMs specify sealants through integrated design-for-manufacturing workflows. German automotive and appliance producers centralize procurement through technical partnership frameworks.
- Contractors:Commercial construction and facade installation specialists dominate premium formulation procurement. French and Spanish national distributors are losing volume to manufacturer-direct technical sales teams.
- DIY Enthusiasts:Retail consumers prioritize cost and convenience over performance specifications. Acrylic formulations retain dominant share in this channel.
- Distributors:Inventory-holding intermediaries face margin compression as large construction groups centralize direct procurement relationships.
Contractors command the established base. Manufacturers are expanding procurement fastest through design-phase integration.
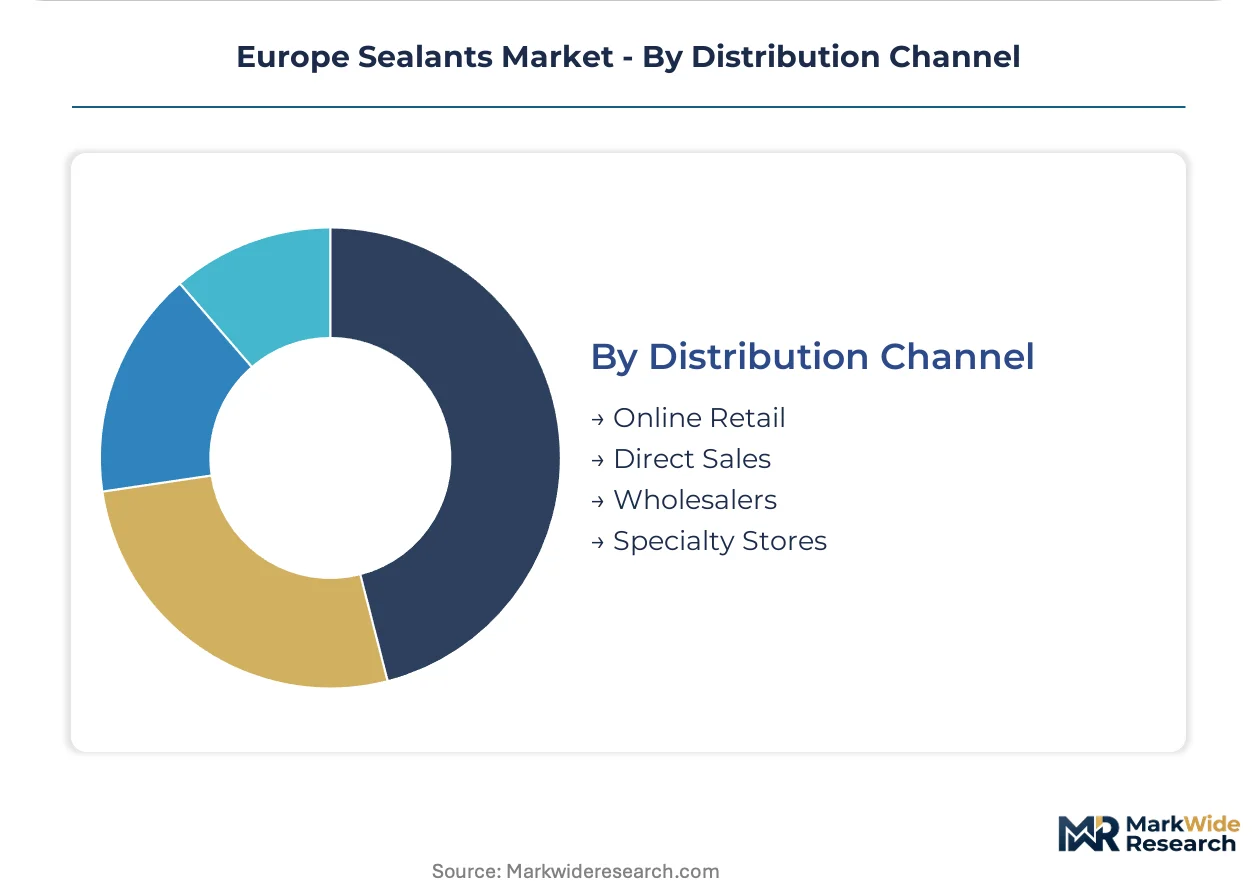
Distribution Channel:
Direct sales capture premium specification volume, while online retail penetrates cost-sensitive segments with compressed technical service content.
- Online Retail:E-commerce platforms serve DIY and small contractor procurement with standardized product configurations. Delivery logistics and technical support limitations constrain penetration in complex specification segments.
- Direct Sales:Manufacturer technical teams embed in project design phases to influence specification and secure volume commitments. Germany exhibits the most pronounced channel consolidation through EPC consortium relationships.
- Wholesalers:National and regional distributors maintain inventory positions for contractor spot purchasing. Margin pressure intensifies as procurement centralizes.
- Specialty Stores:Localized technical service and immediate availability serve renovation contractors and maintenance operations.
Direct sales commands the established base. Online retail is climbing the fastest through platform consolidation and delivery optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's building renovation targets and REACH chemical compliance protocols are redirecting procurement flows across European construction markets. National retrofit programs and solar integration mandates are concentrating sealant demand in specific industrial corridors.
Germany
Commercial glazing retrofits and thermal insulation upgrades dominate silicone and polyurethane procurement. The F-Gas Regulation's fluorinated blowing agent phase-down is redirecting polyurethane R&D toward pentane-based systems. The Rhine-Ruhr industrial corridor hosts formulator testing facilities serving Central European specification requirements.
France
Facade renovation programs and automotive OEM supply chains anchor sealant consumption. CE marking under the Construction Products Regulation gates market access for construction-grade formulations. The Paris-Saclay cluster concentrates technical sales teams embedding in engineering-procurement-construction consortium relationships.
Netherlands
Commercial stock energy retrofits and marine construction specifications drive high-durability silicone demand. ECHA substance restrictions are filtering non-compliant suppliers from procurement shortlists. The Rotterdam-The Hague port-industrial complex handles feedstock imports for polyurethane system production.
Italy
Residential solar mounting system integration and infrastructure renewal programs accelerate specialty sealant consumption. The EU Green Deal's embodied carbon tracking elevates bio-based formulation specifications. The Milan-Turin-Genoa industrial triangle concentrates appliance manufacturing procurement with design-integrated sealant specifications.
Spain
DIY renovation channels and residential caulking specifications sustain acrylic formulation volumes. REACH compliance timelines extend product requalification cycles for construction-grade suppliers. The Madrid-Barcelona corridor distributes inventory through national distributor networks facing margin compression from procurement centralization.
Europe Sealants Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive silane production and specialized construction chemical formulators. Market structure concentrates premium specification share among suppliers with established CE marking testing infrastructure. Two strategic archetypes dominate: Swiss-German integrated chemical groups controlling feedstock-to-formulation value chains, and mid-tier hybrid polymer specialists competing on reformulation agility. Competitive moves center on backward integration into silane precursors and direct technical sales embedding in EPC consortium procurement workflows.
Among Swiss-German integrated suppliers, Sika AG and Wacker Chemie AG occupy positions exemplifying feedstock control and construction chemical integration archetypes. Sika AG represents the construction-centric formulator with testing network depth, while Wacker Chemie AG anchors the silicone feedstock specialization tier extending from raw silane to finished building sealants. Henkel AG & Co. KGaA sits within the diversified industrial adhesive segment, representing automotive OEM certification depth as a competitive anchor point.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| 3M |
| Arkema |
| Dow |
| H.B. Fuller Company |
| BASF |
| RPM International |
| Wacker Chemie AG |
| Others |
Supply & Pricing Matrix
Pentane-based polyurethane blowing agent substitution for phased-down fluorinated alternatives is redrawing raw material sourcing maps while compressing formulation margins across Central European production hubs. This chemistry pivot simultaneously elevates inbound logistics costs from Middle Eastern feedstock suppliers and intensifies price competition among non-integrated formulators lacking captive silane production.
Pricing Analysis
Certification level under CE marking and REACH compliance creates the primary spread between premium contractor-grade formulations and economy DIY products. Three-tier pricing structure across certified structural, standard construction, and retail acrylic levels reflects testing infrastructure investment recovery timelines. Cost compression in mid-tier polyurethane runs through F-Gas Regulation reformulation expenses and silane precursor energy-cost pass-through. DIY enthusiasts exhibit highest price sensitivity, while engineering-procurement-construction consortiums prioritize performance guarantees over unit economics.
Supply Chain Analysis
Rotterdam port congestion and container availability fluctuations on Asia-Europe trade lanes are elevating inbound logistics costs for silane monomers and isocyanate prepolymers. Manufacturing concentrates in Germany, Belgium, and the Netherlands, with feedstock dependencies on Chinese silane intermediates, Saudi methanol derivatives, and Norwegian silicon metal. Single-source vulnerability concentrates in specialized hybrid polymer catalysts sourced from Swiss and Japanese chemical specialists. Distribution runs through manufacturer-direct technical sales for premium specifications and national wholesaler networks for spot contractor purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Sealants Market represents a high-growth disruption as EU Green Deal retrofit mandates and REACH chemical restrictions simultaneously expand addressable volume and elevate compliance barriers to entry.
For Market Incumbents: Fortify position through backward integration into silane precursor production and expansion of CE marking testing infrastructure across German and Dutch industrial corridors. Hybrid polymer specialists threaten premium positioning through reformulation agility; counter by embedding technical sales teams in engineering-procurement-construction consortium procurement workflows to secure specification lock-in. For New Entrants and Emerging Players: CE marking fast-track partnerships with established testing laboratories offer the most viable market entry pathway. White-space concentrates in Italian and Spanish solar mounting system specifications and bio-based formulation segments where embodied carbon tracking creates first-mover advantages. Pursue direct specification relationships with mid-sized facade contractors underserved by incumbent technical service coverage. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid polymer specialists with demonstrated pentane-based polyurethane qualification and established distributor relationships in high-velocity sub-markets. Long-term viability hinges on reformulation capability depth rather than scale economics. Monitor ECHA substance restriction announcements as the critical inflection signal for portfolio reallocation toward bio-based feedstock developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Captive supply of silicone feedstock insulates margin pressure from energy-linked raw material volatility. |
| CE Marking Testing Infrastructure Expansion | Accelerated product qualification timelines compress competitor access under Construction Products Regulation gates. |
| Bio-Based Feedstock Development Program | Renewable polymer backbone investment captures premium positioning under EU Green Deal embodied carbon tracking. |
| Direct Technical Sales Embedding | Manufacturer teams influencing project design phases displace national distributors in specification-intensive procurement. |
| Hybrid Polymer Formulation Launch | Silicone-polyurethane blend qualification fragments traditional category boundaries in commercial glazing retrofits. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with construction procurement managers, facade contractor technical directors, chemical formulator R&D leads, and distributor category buyers. Secondary validation drew from ECHA substance restriction databases, EU Green Deal policy implementation trackers, Cefic chemical industry statistics, and national customs trade flow records. Bottom-up volume estimates by chemistry type and application were triangulated against top-down market sizing derived from construction sector expenditure patterns.
Across the analysis window, forecasts reflect segmented modeling across silicone, polyurethane, acrylic, and butyl chemistries; construction, automotive, consumer goods, and electronics applications; and contractor, manufacturer, and DIY end-user channels. CAGRs were derived from elasticity-adjusted demand projections incorporating EU Green Deal retrofit target compliance rates and REACH substance restriction implementation timelines. Pentane-based polyurethane qualification pace and hybrid polymer specification conversion rates served as key industry-specific forecast inputs.
Underlying assumptions cover sustained EU Green Deal policy enforcement, stable silane feedstock supply from Asian producers, and gradual F-Gas Regulation phase-down adherence, with deviation risk concentrated in ECHA substance restriction acceleration and energy price volatility impacting raw material costs. Recalibration cycles align with material shifts in regulatory announcement schedules and construction sector procurement centralization trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market