
 Aqueous Acrylic Binders Market | 2026-2036
Aqueous Acrylic Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Aqueous Acrylic Binders Market Outlook
ISO 14001 environmental management certification is bifurcating the supplier base into qualified multinationals and regional formulators lacking audit bandwidth. BASF SE leverages integrated acrylic acid back-integration to sustain margin control across emulsion grades. Wacker Chemie AG anchors its position through silicone-acrylic hybrid technology leadership in high-durability coatings. Dow Inc. competes on geographic scale with manufacturing footprints spanning Texas, Germany, and China.
Aqueous acrylic binders are water-dispersed polymers with glass transition temperatures typically engineered between minus twenty and plus sixty degrees Celsius, serving as film-forming agents that impart adhesion, flexibility, and weather resistance to coatings and adhesives. Emulsions dominate volume flows in architectural paints where cost-performance ratios favor bulk supply, while low-VOC formulations capture expanding share in regulatory-stringent European and North American construction markets. Specialty grades command premium positioning in automotive clearcoats and textile laminates where performance thresholds exceed commodity specifications.
REACH registration requirements in Europe, EPA VOC emission limits under Clean Air Act provisions in the United States, and China's GB standards for architectural coatings collectively redirect formulation investment from solvent-borne toward waterborne acrylic systems. ECHA substance evaluation protocols and state-level air quality regulations in California and New York further tighten permissible solvent content, accelerating specification changes by coatings architects and industrial buyers. Stakeholders must monitor regulatory harmonization pressures between Brussels and Beijing while calibrating R&D allocation across performance tiers.
Market Dynamics
REACH registration deadlines and EPA VOC emission limits under Clean Air Act provisions are systematically eliminating solvent-borne alternatives, forcing coatings architects to specify waterborne acrylic systems across construction and automotive refinishing applications.
Growth Catalysts
- REACH compliance deadlines:European coatings manufacturers face substance evaluation protocols that restrict solvent content, redirecting formulation investment toward aqueous acrylic emulsions for architectural and industrial applications.
- Construction sector demand:Residential and commercial building activity in Germany, China, and the United States sustains bulk consumption of water-dispersed polymers for interior and exterior paints.
- Automotive refinishing specifications:Collision repair shops and OEM clearcoat operations adopt low-VOC waterborne systems to meet state-level air quality regulations in California and New York.
Market Restraints
- Acrylic acid feedstock volatility:Propylene derivative pricing fluctuations compress margins for emulsion producers lacking backward integration into monomer supply.
- Freezing sensitivity in logistics:Water-based dispersions require temperature-controlled transport and storage infrastructure unavailable in certain distribution corridors.
- Performance gaps in extreme environments:Solvent-borne urethanes and epoxies retain specification dominance in marine and heavy industrial coatings where humidity resistance thresholds exceed current aqueous acrylic capabilities.
Strategic Opportunities
- Silicone-acrylic hybrid expansion:High-durability coatings for facade protection and roofing membranes command premium positioning as building owners extend maintenance cycles.
- China GB standard alignment:Architectural coatings compliance with national VOC limits creates specification pull for certified waterborne binders across tier-one and tier-two cities.
- Textile laminates segment:Performance-grade emulsions for technical fabrics and automotive interiors offer margin expansion beyond commodity architectural paint volumes.
Industry Challenges
- ISO 14001 certification bandwidth:Regional formulators lack audit resources to qualify for multinational procurement panels, bifurcating the supplier base into certified and non-certified tiers.
- Emulsion stability expertise:Formulation chemists capable of engineering glass transition temperatures across minus twenty to plus sixty degrees Celsius remain concentrated among incumbent multinationals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aqueous Acrylic Binders Market |
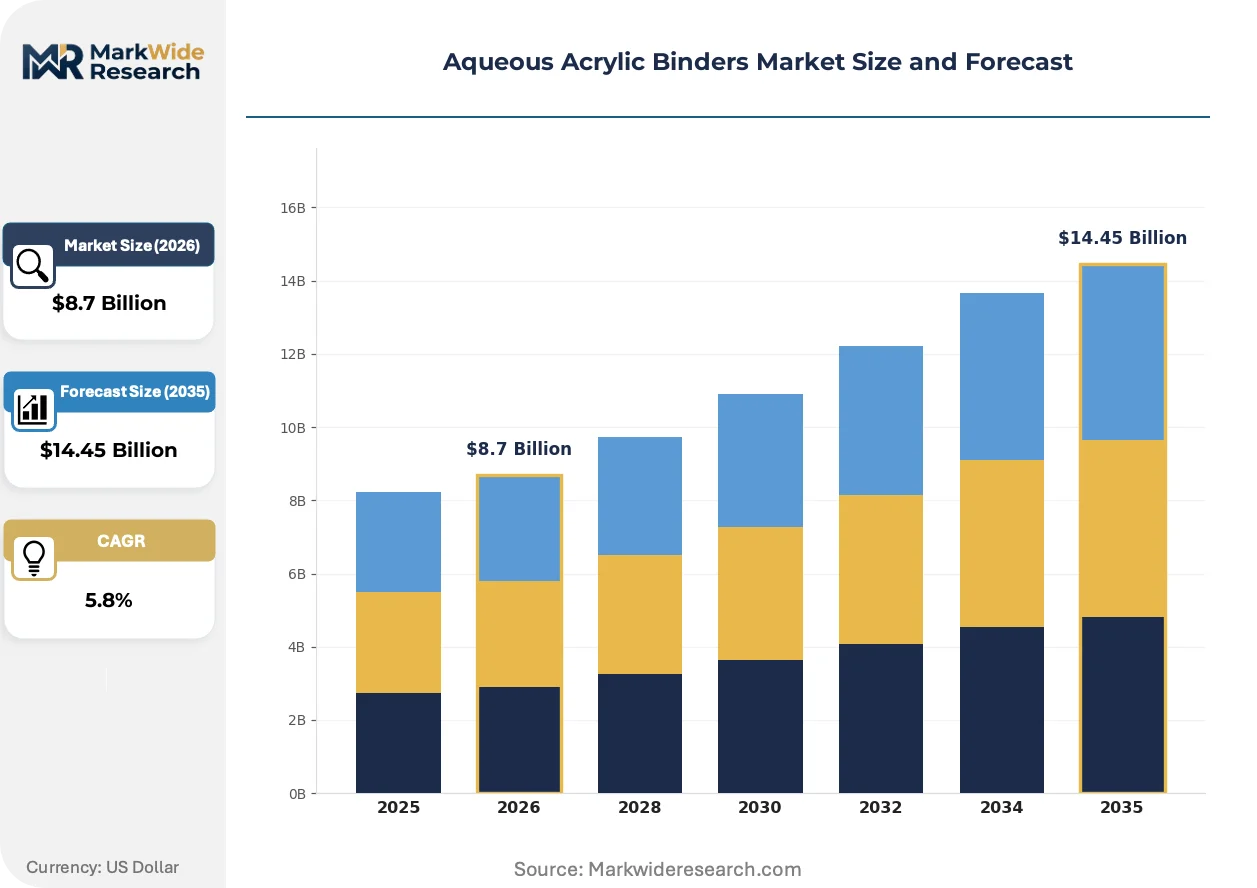
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Dispersions, Solutions, Powders End Use Industry: Coatings, Adhesives, Construction, Textiles Application: Paints, Sealants, Varnishes, Print Inks Formulation: Waterborne, Low VOC, High Performance, Specialty |
| Companies Covered | Celanese Corporation, Lubrizol Corporation, BASF SE, DIC Corporation, Wacker Chemie AG, Dow Inc., Synthomer plc, Trinseo S.A., Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aqueous Acrylic Binders Market Strategic Shifts
Formulation chemistry and regulatory enforcement are converging to compress the solvent-borne coatings installed base while elevating performance requirements for waterborne alternatives in premium applications.
Self-crosslinking aqueous acrylic emulsions are supplanting conventional two-component systems in wood furniture and flooring coatings. European mid-market manufacturers accelerate adoption to eliminate isocyanate handling hazards and reduce curing energy. The technology is compressing the addressable market for solvent-borne alkyd and polyurethane segments while enabling single-component formulations that simplify application training.
EPA VOC emission limits under Clean Air Act provisions tighten permissible solvent content in architectural and industrial maintenance coatings. Coatings architects in the United States face state-level preemption battles as California Air Resources Board standards exceed federal baselines. Low-VOC aqueous acrylic specifications capture expanding share in commercial construction and public infrastructure projects where bid requirements mandate compliance documentation.
Certification-driven procurement is fragmentizing buyer concentration as ISO 14001 and EMAS registration become mandatory gatekeepers for public sector and multinational contracts. Tier-one coatings manufacturers in Germany and France now require supplier sustainability disclosures that exclude uncertified regional formulators. The shift is most visible in European public housing renovation programs and automotive OEM supply chains where environmental management system documentation determines vendor eligibility.
Aqueous Acrylic Binders Market Segmentation
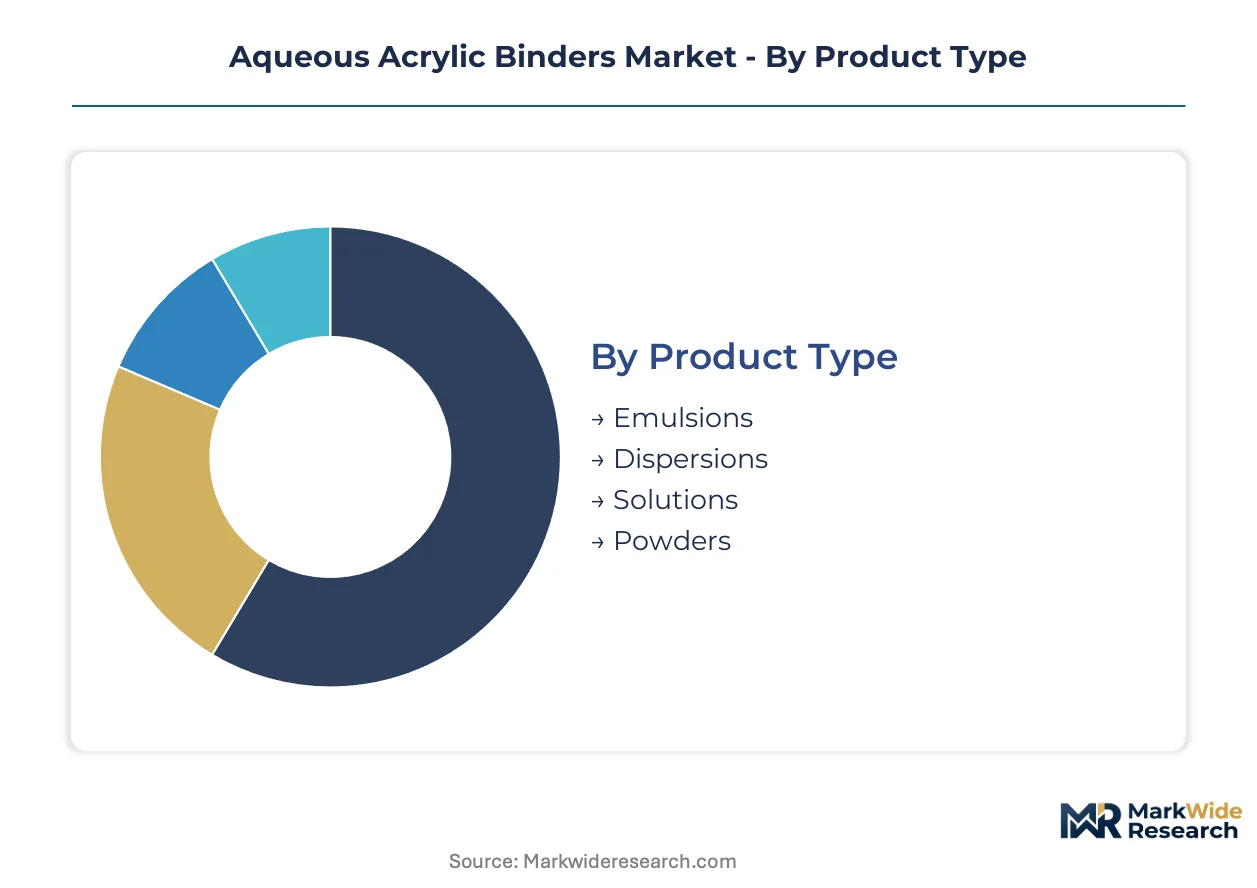
Segmentation in aqueous acrylic binders reveals distinct margin architectures across product chemistry, end-use specifications, and regulatory compliance tiers. Manufacturers optimize formulation investment by mapping glass transition temperature engineering to application performance thresholds and geographic regulatory intensity.
Product Type:
Margin pools concentrate in emulsion technologies where scale economies intersect with formulation complexity barriers.
- Emulsions:Water-dispersed polymers with particle sizes engineered between 100-500 nanometers serve as the dominant film-forming architecture for architectural coatings. Demand concentrates in Germany and China where construction activity sustains bulk consumption and REACH compliance tightens solvent-borne alternatives.
- Dispersions:These stabilized polymer systems offer broader solid content ranges and superior mechanical stability in adhesive applications. Automotive refinishing specifications in California and New York rotate procurement toward low-VOC dispersion grades for collision repair operations.
- Solutions:Fully dissolved polymer chains provide clarity and gloss retention in specialty wood coatings.
- Powders:Redispersible polymer powders enable dry-mix mortar applications in construction chemicals.
Emulsions hold installed capacity. Dispersions are rotating up the share rankings.
End Use Industry:
Application pull varies sharply by sector, with coatings commanding volume leadership while textiles offer premium positioning.
- Coatings:Architectural and industrial paint formulations consume the majority of aqueous acrylic volumes, driven by EPA VOC limits under Clean Air Act provisions and ECHA substance evaluation protocols. Specification changes in commercial construction and public infrastructure projects mandate compliance documentation.
- Adhesives:Pressure-sensitive and structural bonding applications leverage acrylic tack and aging resistance. Packaging and electronics assembly in China and the United States sustain demand for high-shear formulations.
- Construction:Cement modification and waterproofing membranes utilize redispersible powders and emulsions.
- Textiles:Technical fabric laminates and automotive interior coatings command premium positioning where performance thresholds exceed commodity specifications.
Coatings anchor volume flows. Textiles are climbing the fastest in margin contribution.
Application:
Performance requirements stratify sharply across surface protection, sealing, and imaging applications.
- Paints:Interior and exterior architectural coatings dominate consumption, with low-VOC formulations capturing expanding share in European and North American markets. Self-crosslinking emulsions are supplanting conventional two-component systems in wood furniture applications.
- Sealants:Joint filling and weatherproofing applications require elastic recovery and UV resistance. Building envelope specifications in Germany and France emphasize durability testing under ECHA framework conditions.
- Varnishes:Clear protective coatings for wood and metal substrates emphasize gloss retention and scratch resistance.
- Print Inks:Flexographic and gravure printing applications demand fast-drying, adhesion-promoting binder systems.
Paints maintain capacity dominance. Sealants are gaining share fastest in specification-driven procurement.
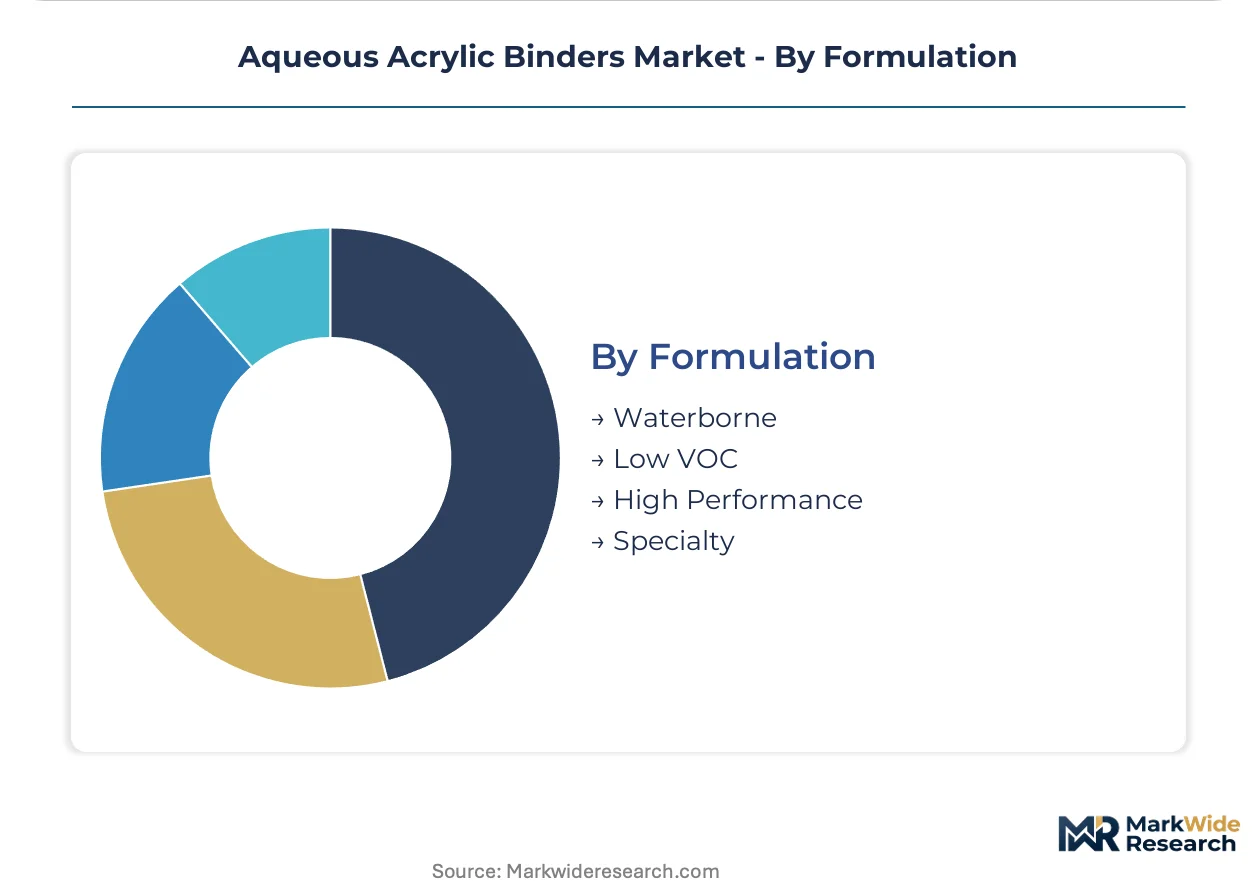
Formulation:
Regulatory tiering creates distinct price-performance bands that separate commodity supply from certified premium grades.
- Waterborne:Standard aqueous systems serve cost-sensitive architectural markets where bulk supply and application simplicity outweigh performance extremes. Construction activity in tier-one and tier-two Chinese cities sustains volume demand under GB standard compliance requirements.
- Low VOC:Reduced-emission formulations capture specification share in California Air Resources Board jurisdictions and European public housing renovation programs. ISO 14001 certification becomes mandatory for multinational procurement panels.
- High Performance:Silicone-acrylic hybrids and self-crosslinking architectures serve facade protection and roofing membranes.
- Specialty:Automotive clearcoats and textile laminates require customized glass transition temperature engineering.
Waterborne retains capacity leadership. Low VOC is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coatings formulators in Germany, China, and the United States concentrate procurement of aqueous acrylic binders, with regulatory enforcement and construction cycles determining regional demand intensity.
Germany
Automotive refinishing and facade coatings drive binder consumption in Bavaria and North Rhine-Westphalia. ECHA substance evaluation protocols under REACH restrict solvent content in architectural formulations. The Rhine-Ruhr industrial corridor hosts specialty emulsion production serving OEM clearcoat specifications.
China
Tier-one and tier-two construction markets in Shanghai and Beijing sustain bulk emulsion demand for interior and exterior paints. GB standards for architectural coatings mandate VOC compliance, redirecting formulation investment from solvent-borne systems. The Yangtze River Delta concentrates manufacturing capacity for water-dispersed polymers.
United States
Commercial construction activity in Texas and California anchors architectural coatings consumption. EPA emission limits under Clean Air Act provisions tighten permissible solvent content, accelerating specification changes. The Gulf Coast petrochemical corridor supplies acrylic acid feedstock to emulsion producers.
Japan
Automotive interior laminates and electronics adhesives command premium-grade acrylic dispersions in Kansai and Chubu regions. METI industrial standards emphasize low-emission formulations for building materials. Osaka-based formulators specialize in high-durability coatings for transportation applications.
France
Public housing renovation programs in Île-de-France drive low-VOC coatings procurement. EMAS registration and ISO 14001 certification determine supplier eligibility for state contracts. Lyon and Marseille industrial zones concentrate textile laminate production utilizing aqueous acrylic binders.
Aqueous Acrylic Binders Market Competitive Environment
Player mix skews toward integrated chemical multinationals with captive monomer supply and regional formulators dependent on merchant acrylic acid. The supplier base bifurcates along certification tiers, with ISO 14001-qualified multinationals capturing specification-driven procurement. Strategic archetypes include backward-integrated producers controlling acrylic acid economics, silicone-acrylic hybrid specialists commanding premium positioning, and geographic-scale operators balancing cost with regulatory proximity. Dominant competitive moves center on capacity alignment with regional regulatory deadlines and portfolio diversification into high-performance hybrid chemistries.
Within the integrated multinational tier, BASF SE, Dow Inc., and Wacker Chemie AG exemplify contrasting strategic positions. BASF SE represents backward-integrated economics through captive acrylic acid production. Dow Inc. anchors geographic-scale operations across manufacturing footprints in Texas, Germany, and China. Wacker Chemie AG occupies a specialist position through silicone-acrylic hybrid technology leadership in high-durability coatings applications.
| Leading Market Players |
|---|
| Celanese Corporation |
| Lubrizol Corporation |
| BASF SE |
| DIC Corporation |
| Wacker Chemie AG |
| Dow Inc. |
| Synthomer plc |
| Trinseo S.A. |
| Arkema Group |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for waterborne acrylic emulsions concentrate margin pressure on regional formulators lacking captive monomer supply, while backward-integrated multinationals leverage acrylic acid cost control to sustain pricing power across REACH-compliant and GB-standard grades.
Pricing Analysis
Cost-plus contracts indexed to propylene derivative benchmarks dominate procurement between emulsion producers and coatings manufacturers. Price differentiation separates ISO 14001-certified supply from uncertified regional tiers, with premium positioning commanded by silicone-acrylic hybrid grades. Cost compression in commodity architectural emulsions is intensifying because merchant acrylic acid exposure leaves regional formulators vulnerable to feedstock volatility. Small-to-mid coatings houses exhibit highest price sensitivity, while automotive OEM clearcoat operations prioritize performance consistency over unit cost.
Supply Chain Analysis
Germany, China, and the United States anchor acrylic acid production and downstream emulsion manufacturing. Propylene oxide and acrylate ester inputs draw from Gulf Coast petrochemical corridors and Yangtze River Delta refining complexes. Single-source vulnerability concentrates in specialty silicone-acrylic hybrid intermediates where Wacker Chemie AG maintains technology leadership. Distribution runs through bulk tanker networks serving coatings clusters in Bavaria, Shanghai, and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aqueous acrylic binders represent a substitution defense market where solvent-borne urethanes and epoxies threaten to reclaim specification share if humidity resistance gaps in marine applications persist unaddressed.
For Market Incumbents: Secure captive acrylic acid supply through backward integration or long-term offtake agreements with Gulf Coast propylene derivative producers. Expand ISO 14001 certification bandwidth to exclude uncertified regional competitors from European public housing and automotive OEM procurement panels. Prioritize R&D investment in self-crosslinking emulsion architectures that compress the addressable market for two-component solvent systems.
For New Entrants and Emerging Players: Differentiate on silicone-acrylic hybrid formulations for facade protection and roofing membranes where incumbent concentration remains lowest. Target textile laminates for technical fabrics and automotive interiors as the most penetrable premium segment. Pursue white-label supply partnerships with mid-tier European coatings houses seeking REACH-compliant alternatives to multinational sourcing.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwinds play because REACH deadlines, EPA VOC limits, and China GB standards collectively eliminate solvent-borne alternatives across construction and automotive refinishing. Acquisition targets include regional emulsion specialists with established distribution in tier-two Chinese cities and certified production assets in Germany or France. Monitor ECHA substance evaluation protocol expansions as the signal for accelerated specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive monomer supply insulates margin compression from propylene derivative volatility. |
| Silicone-Acrylic Hybrid Capacity Expansion | Premium positioning in high-durability coatings extends maintenance cycles for building owners. |
| ISO 14001 Certification Investment | Environmental management documentation qualifies suppliers for multinational procurement panels. |
| Long-term Supply Agreement with Coatings OEMs | Contracted offtake secures volume visibility through REACH compliance deadline cycles. |
| Joint Venture in Yangtze River Delta | Local production proximity serves GB-standard compliance demand in tier-one Chinese construction. |
Study Parameters
Cross-validation between primary interviews with coatings formulators, procurement leads at architectural paint manufacturers, and technical R&D directors anchors the qualitative findings. Secondary validation draws from ECHA substance evaluation databases, EPA Clean Air Act regulatory filings, China GB standard compliance registries, and SEC 10-K disclosures from integrated chemical multinationals. Bottom-up emulsion consumption estimates triangulate against top-down coatings production data across Germany, China, and the United States.
Sensitivity analysis around propylene derivative pricing and REACH registration deadline phasing shapes the analytical framework. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, formulation regulatory grade, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand projections incorporating construction cycle intensity and automotive refinishing specification shifts. Feedstock cost trajectories and certification penetration rates serve as industry-specific forecast inputs across the projection horizon.
Material uncertainties — acrylic acid supply disruptions, ECHA protocol acceleration, China construction stimulus withdrawal — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and coatings architect specification inertia. Recalibration cycles align with material shifts in ECHA evaluation protocols and state-level EPA preemption battles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Acrylic Adhesives Market