
 Wood Glue Market | 2026-2036
Wood Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Glue Market Analytics
North American polyurethane producers is pivoting toward waterborne adhesive platforms to serve California's CARB ATCM-compliant panel mills. Henkel AG & Co. KGaA leverages its European R&D base to sustain leadership in reactive hot-melt systems for engineered flooring. H.B. Fuller Company anchors its position through captive supply of tackifier resins across Southeast Asian joint-venture plants. Sika AG competes in construction-grade phenolic adhesives with formulations rated for exterior structural lamination.
Wood glue comprises polymeric bonding agents formulated from polyvinyl acetate emulsions, urea-formaldehyde resins, or epoxy-amine systems, typically achieving shear strengths of 1,500–4,000 psi depending on substrate and cure conditions. These adhesives create load-bearing bonds between timber, veneer, particleboard, and engineered wood products for furniture assembly, structural lamination, and interior finish applications. Polyvinyl acetate dominates volume flows in furniture and crafts segments due to its ambient-temperature cure and clean machining characteristics. Epoxy and phenolic grades command premium positioning in construction and flooring where moisture resistance and structural code compliance create defensible margin pools. Urea formaldehyde retains cost-driven share in commodity panel production despite regulatory pressure on formaldehyde emissions.
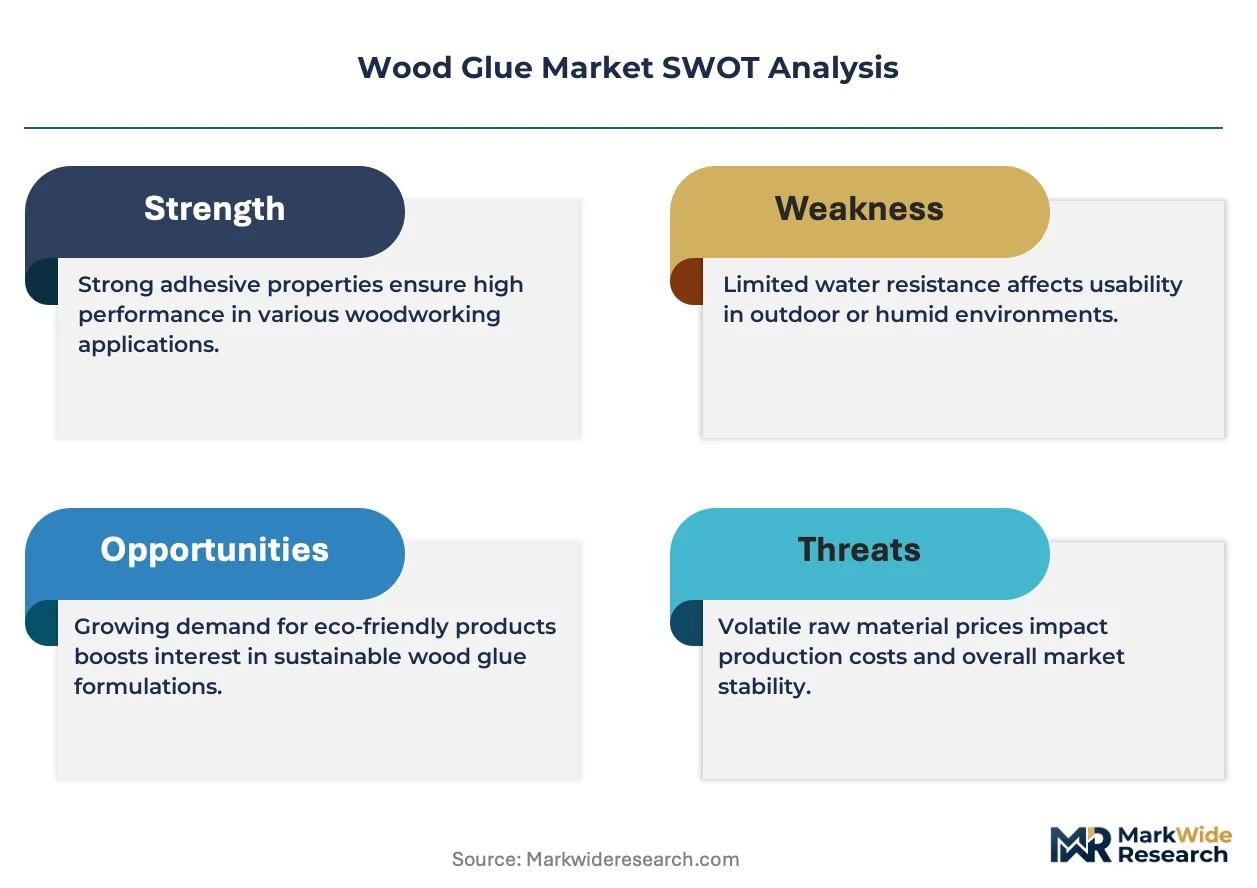
EPA TSCA Title VI and the EU ECHA REACH framework restrict formaldehyde content in wood adhesives, compelling reformulation toward low-emitting resorcinol and soy-based alternatives. ISO 12404 and ASTM D5573 testing protocols govern bond durability classification, creating certification barriers for non-compliant imports. Stakeholders must monitor evolving biobased feedstock availability and regional enforcement variance to align capacity investments with compliant formulation demand.
Market Dynamics
EPA TSCA Title VI and EU ECHA REACH frameworks are forcing adhesive formulators to eliminate formaldehyde from wood panel bonding systems, triggering a wholesale resin chemistry transition across furniture and construction supply chains.
Growth Catalysts
- Formaldehyde-Free Mandates:EPA TSCA Title VI emission standards in the United States and EU ECHA REACH restrictions in Europe are compelling manufacturers to adopt soy-based and resorcinol adhesive alternatives, expanding compliant formulation demand.
- Engineered Flooring Expansion:Reactive hot-melt polyurethane systems are gaining traction in multi-layer flooring production due to superior moisture resistance and rapid cure cycles that accelerate manufacturing throughput.
- Vietnam Wood Processing Cluster:Export-oriented furniture manufacturing zones near Ho Chi Minh City and Binh Duong province are concentrating demand for high-volume polyvinyl acetate emulsions serving North American and European retail supply chains.
Market Restraints
- Petrochemical Feedstock Volatility:Polyvinyl acetate and polyurethane adhesive producers face margin compression from fluctuating ethylene and propylene derivative costs, limiting pricing flexibility in commodity furniture segments.
- Resin Supply Concentration:Specialty tackifier resins for hot-melt formulations remain concentrated among Southeast Asian joint-venture producers, creating vulnerability to regional logistics disruptions and trade policy shifts.
- Technical Performance Gaps:Soy-based and biobased alternatives currently exhibit inferior shear strength and moisture resistance compared to urea-formaldehyde resins, restricting adoption in structural exterior applications.
Strategic Opportunities
- India Furniture Manufacturing:BIS certification requirements and PLI scheme incentives for domestic wood product manufacturing are opening demand for compliant adhesive systems in previously underpenetrated South Asian markets.
- Cross-Laminated Timber Construction:Phenolic and melamine-urea adhesive formulations rated for exterior structural lamination are capturing new volume in mass timber building projects requiring code-compliant bond durability.
- Digital Formulation Platforms:AI-driven adhesive property prediction is converging with automated batch control systems to accelerate R&D cycles and reduce reformulation costs for regulatory compliance.
Industry Challenges
- ISO 12404 Certification Timelines:Bond durability classification testing protocols require extended aging cycles that delay product launches and tie up quality assurance resources for six to twelve months.
- Legacy Equipment Retrofit Costs:Hot-melt and moisture-cure polyurethane systems demand heated storage, precision metering, and modified press configurations that strain capital budgets at mid-scale panel mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Glue Market |
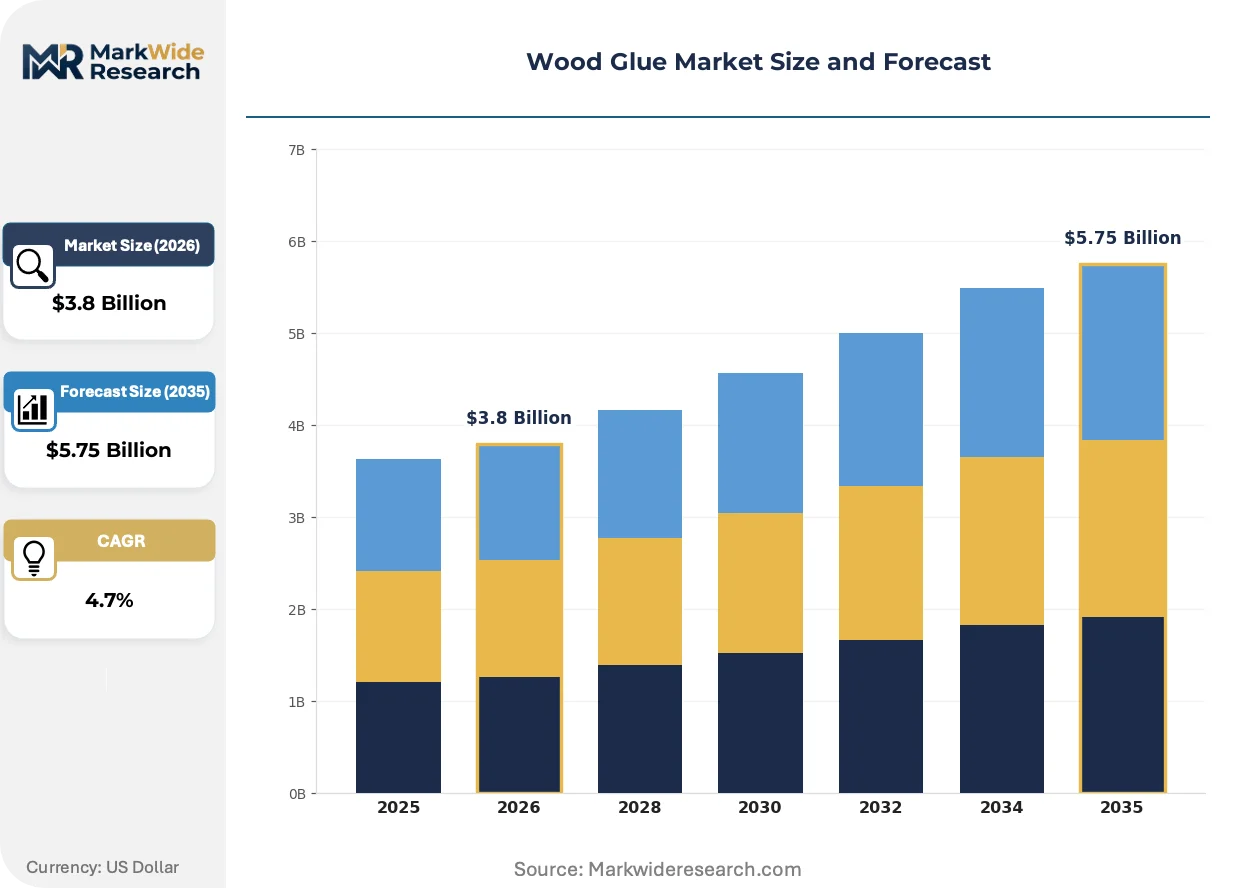
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Acetate, Urea Formaldehyde, Epoxy, Phenolic Application: Furniture, Crafts, Construction, Flooring End User: Manufacturers, DIY Enthusiasts, Contractors, Retailers Grade: Industrial, Commercial, Architectural, Specialty |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Sika AG, Bostik S.A., Pidilite Industries Ltd., Ashland Inc., Akzo Nobel N.V., Jowat SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Glue Market Evolving Landscape
Adhesive automation, regulatory chemistry mandates, and buyer consolidation are restructuring how wood bonding systems are formulated, certified, and procured across furniture and construction verticals.
Robotic dispensing and vision-guided adhesive application is automating bond-line control in high-volume furniture assembly operations. European and North American cabinet manufacturers are deploying these systems to reduce labor dependency and eliminate variability in glue spread rates. This automation is compressing defect rates and enabling real-time viscosity adjustment that maintains bond integrity across temperature and humidity fluctuations.
EU ECHA REACH framework restrictions on formaldehyde content are accelerating resorcinol-phenolic and soy-protein adhesive development for interior panel applications. Industrial consequence includes stranded capital in conventional urea-formaldehyde reactor assets and urgent reformulation partnerships between resin suppliers and composite wood producers. Engineered flooring manufacturers in Germany and Austria are most affected, responding with certified low-emitting product lines that command specification preference from institutional buyers.
Consolidated home improvement retail chains are compressing supplier bases and demanding consolidated adhesive procurement across multiple wood product categories. This concentration is displacing fragmented regional distributors with direct manufacturer relationships and volume-tiered pricing structures. The shift is most visible in North American big-box retail supply chains, where private-label furniture and cabinetry programs now specify single-source adhesive compliance across entire product portfolios.
Wood Glue Market Segmentation
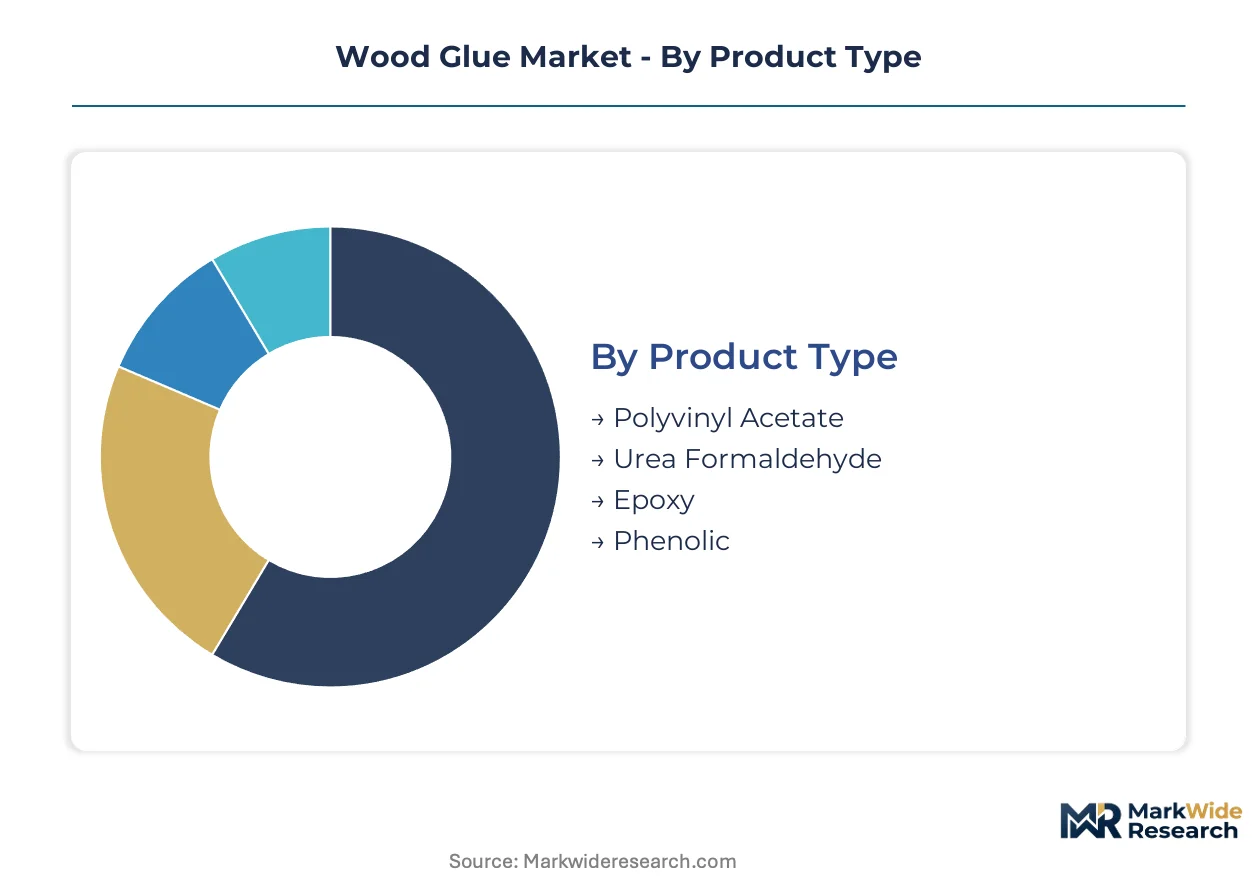
Wood glue segmentation reveals how formulation chemistry, application requirements, and procurement patterns create distinct margin pools. Regulatory pressure and automation trends are reshaping which segments capture volume and value across furniture and construction supply chains.
Product Type:
Equipment replacement cycles in panel mills and furniture plants are accelerating shifts between adhesive chemistries as legacy urea-formaldehyde systems face obsolescence.
- Polyvinyl Acetate:Waterborne emulsion systems cure at ambient temperature and machine cleanly without residue, making them dominant in furniture assembly and craft applications. Demand concentrates in Vietnam's export processing zones near Ho Chi Minh City, where high-volume manufacturers serving North American retail chains specify PVA for interior casegoods and cabinetry.
- Urea Formaldehyde:Thermosetting amino resin systems offer low-cost bonding for commodity particleboard and medium-density fiberboard production. EPA TSCA Title VI emission standards are forcing reformulation investments, with stranded reactor assets accumulating across Midwestern US panel mills that delayed compliance upgrades.
- Epoxy:Two-part amine-cured systems deliver superior moisture resistance and structural shear strength for exterior applications and engineered wood lamination.
- Phenolic:Resorcinol-formaldehyde and phenol-resorcinol formulations rated for exterior structural use command premium positioning in mass timber construction and marine plywood.
Polyvinyl Acetate sits at the top of the volume ranking, with Phenolic climbing the fastest as cross-laminated timber construction expands.
Application:
Cost tier differentiation separates commodity adhesive procurement from specification-grade systems where performance certification justifies price premiums.
- Furniture:Cabinet, casegood, and upholstery frame assembly drives bulk PVA consumption through automated edge-banding and dowel-insertion lines. European manufacturers in Germany and Poland are deploying robotic dispensing systems that require viscosity-stable formulations.
- Crafts:Hobbyist woodworking and small-batch artisan production sustain demand for consumer-packaged adhesive formats with extended open times and easy cleanup.
- Construction:Structural laminated beams, I-joists, and mass timber panels require phenolic and melamine-urea systems meeting ICC-ESR code evaluation reports. EU ECHA REACH formaldehyde restrictions are accelerating resorcinol-phenolic adoption for interior structural applications in German and Austrian engineered wood plants.
- Flooring:Multi-layer engineered hardwood and laminate production depends on reactive hot-melt polyurethane systems with rapid cure cycles that accelerate press throughput.
Furniture commands the largest volume position, with Flooring expanding most quickly as European producers automate multi-layer production lines.
End User:
Procurement patterns diverge sharply between consolidated manufacturing accounts and fragmented retail channels.
- Manufacturers:Large-scale furniture and panel producers negotiate direct supply agreements with volume-tiered pricing and technical service support. North American big-box retail private-label programs now specify single-source adhesive compliance across entire product portfolios.
- DIY Enthusiasts:Consumer retail channels demand convenient packaging, extended shelf life, and clear application instructions for home woodworking projects.
- Contractors:Professional installation crews prioritize rapid cure times and reliable bond strength under variable jobsite conditions for finish carpentry and millwork.
- Retailers:Home improvement chains and distributors consolidate supplier bases, displacing fragmented regional distributors with direct manufacturer relationships.
Manufacturers hold the dominant volume share, with Retailers gaining influence fastest through procurement consolidation.
Grade:
Margin pools stratify across certification tiers where regulatory compliance creates defensible pricing power.
- Industrial:High-volume production formulations optimized for automated application equipment and rapid line speeds in panel mills and furniture plants.
- Commercial:Mid-tier systems balancing performance and cost for regional manufacturers and institutional furniture suppliers.
- Architectural:Specification-grade adhesives carrying ISO 12404 and ASTM D5573 durability certifications for visible structural applications and code-compliant mass timber.
- Specialty:Custom formulations for extreme environments, fire-rated assemblies, or heritage restoration projects requiring reversible bonds and substrate compatibility testing.
Industrial grade leads absolute volume, with Architectural grade showing the steepest expansion trajectory as mass timber codes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter formaldehyde limits than the United States, while Vietnam processes more export furniture volume per capita than any other Asian manufacturing hub. These regulatory and production asymmetries are redirecting adhesive procurement flows across three continents.
United States
California's CARB ATCM regulations predate federal EPA TSCA Title VI standards, creating a dual-compliance burden for panel mills serving West Coast construction markets. Midwestern furniture manufacturers in North Carolina and Indiana are retrofitting hot-melt application lines to handle moisture-cure polyurethane systems. The Southeast timber belt around Atlanta concentrates new mass timber projects demanding code-certified phenolic adhesives.
Germany
Engineered flooring plants in Bavaria and Baden-Württemberg source reactive hot-melt systems for automated multi-layer production lines. EU ECHA REACH restrictions on formaldehyde emissions exceed US EPA thresholds, accelerating resorcinol-phenolic development at resin suppliers along the Rhine chemical corridor. Frankfurt-area distributors consolidate procurement for Central European furniture exporters.
Vietnam
Export-oriented wood processing zones near Ho Chi Minh City and Binh Duong province consume high-volume polyvinyl acetate emulsions for North American retail supply chains. Japanese and South Korean furniture OEMs operate captive adhesive blending facilities to ensure specification consistency. The Dong Nai river industrial corridor anchors Southeast Asia's largest concentration of automated edge-banding operations.
India
BIS certification requirements and PLI scheme incentives for domestic wood product manufacturing are opening demand for compliant adhesive systems in previously underpenetrated South Asian markets. Gujarat and Maharashtra furniture clusters are upgrading from solvent-based to waterborne PVA formulations. Pune-based panel mills are piloting soy-based alternatives for interior applications.
Canada
British Columbia mass timber construction codes recognize phenolic and melamine-urea adhesives rated for exterior structural lamination. Quebec furniture manufacturers serving US big-box retailers align adhesive procurement with EPA TSCA Title VI compliance protocols. Ontario particleboard mills face stranded asset risk from delayed urea-formaldehyde reactor upgrades.
Wood Glue Market Competitive Landscape
German and Swiss producers anchor the premium formulation tier; US and Japanese specialists hold positions in construction-grade and automated application segments. The vendor base clusters around three strategic archetypes: diversified chemical conglomerates with captive resin supply, mid-scale adhesive pure-plays with regional formulation expertise, and construction-chemical specialists with structural certification capabilities. Competitive moves concentrate on backward integration into tackifier resins and partnerships with automated equipment OEMs.
Within the diversified chemical tier, Henkel AG & Co. KGaA and H.B. Fuller Company represent archetypes of European and North American scale-driven positioning. Sika AG exemplifies the construction-specialist vector with structural adhesive certification depth. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic emphasis—German KGaA and AG forms against US Inc. and Company suffixes—without prescribing specific product-market actions.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Sika AG |
| Bostik S.A. |
| Pidilite Industries Ltd. |
| Ashland Inc. |
| Akzo Nobel N.V. |
| Jowat SE |
| Others |
Value Network & Pricing Analysis
Adhesive chemist labor pools in Germany's Rhine chemical corridor command wage premiums that widen pricing spreads between European specification-grade phenolic systems and Vietnamese commodity PVA volumes. This workforce differential compresses margins for mid-tier producers unable to access either premium certification premiums or low-cost manufacturing arbitrage.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for commodity polyvinyl acetate emulsions serving North American retail supply chains. Three-tier pricing structure across architectural, commercial, and industrial certification levels separates specification-grade phenolic adhesives from bulk furniture formulations. Cost compression in standard-grade PVA is intensifying because ethylene derivative volatility strains resin producers. DIY enthusiasts exhibit highest price sensitivity, while mass timber contractors prioritize code-compliant bond durability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from consolidated North American big-box retailers mandate multi-supplier qualification across phenolic tackifier producers. Supply concentrates in Germany, Vietnam, and the United States for specialty resorcinol formulations and high-volume emulsion production. Formulation chemistry draws from petrochemical ethylene derivatives, soy protein isolates, and resorcinol feedstocks. Single-source vulnerability persists in Southeast Asian joint-venture tackifier plants. Distribution runs through direct manufacturer relationships with large furniture OEMs and regional distributor networks serving fragmented contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA TSCA Title VI compliance costs in North America and Vietnam's export-processing labor advantages. The spread between regulatory burden and manufacturing cost creates repositioning incentives across three continents.
For Market Incumbents: Hedge stranded asset risk in Midwestern urea-formaldehyde reactor capacity by accelerating resorcinol-phenolic partnerships with German resin suppliers. Secure captive supply of Southeast Asian tackifier resins through joint-venture equity stakes before logistics disruptions trigger allocation shortages. Certification investment in ISO 12404 exterior durability ratings protects margin pools from soy-based substitute encroachment.
For New Entrants and Emerging Players: AI-driven formulation property prediction offers a technology-first wedge against incumbent R&D cycle times. White-space targets include India's BIS-certified adhesive demand under PLI scheme incentives and cross-laminated timber construction-grade phenolic supply in British Columbia. A technical service partnership with automated edge-banding equipment OEMs accelerates specification adoption in Vietnam's Dong Nai corridor.
For Investors and Strategic Acquirers: Construction-chemical conglomerates are the most active acquirer in this space, consolidating regional formulation expertise to complement structural certification capabilities. Long-term viability hinges on regulatory chemistry transition completion and biobased feedstock cost parity. Acquisition target archetype: mid-scale adhesive pure-plays with captive Southeast Asian resin supply and ISO 12404 test protocol familiarity. The signal to watch is EPA enforcement variance across state-level implementation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifier Resins | Captive supply of Southeast Asian joint-venture plants insulates Henkel and H.B. Fuller from logistics disruption. |
| Reactive Hot-Melt Capacity Expansion | Automated multi-layer flooring lines in Bavaria demand moisture-cure polyurethane systems with rapid cure cycles. |
| Soy-Based Formulation Partnership | Pune panel mills piloting biobased alternatives need technical collaboration to close shear-strength gaps with urea-formaldehyde. |
| Digital Formulation Platform Deployment | AI-driven property prediction accelerates EPA TSCA Title VI compliance reformulation for stranded Midwestern assets. |
| Mass Timber Certification Investment | Architectural-grade phenolic systems rated for ICC-ESR compliance capture specification preference in Atlanta structural projects. |
Research Methodology
Direct dialogue with adhesive plant managers, furniture OEM procurement leads, resin supplier technical directors, and distribution channel partners grounded qualitative findings. Secondary validation drew from EPA TSCA Title VI filings, EU ECHA REACH substance restrictions, customs trade data for vinyl acetate monomer flows, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Bottom-up modeling aggregated product-type, application, and grade-tier volumes through the projection horizon. Top-down cross-checks incorporated construction spending patterns, furniture export trade flows, and regulatory enforcement variance across state and national jurisdictions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic anchors. Industry-specific forecast inputs included mass timber building code adoption timelines and robotic dispensing equipment deployment rates in European cabinet manufacturing.
The model holds under stable petrochemical feedstock availability and gradual biobased alternative performance improvement; deviation in EPA enforcement stringency or Southeast Asian logistics disruptions would shift volume projections materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Germany Adhesives Market