
 Indonesia Adhesives Market | 2026-2036
Indonesia Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Adhesives Market Foresight
Technical service contracts for adhesive application equipment and bonded joint validation are rebalancing how suppliers capture value beyond raw material tonnage. Henkel AG & Co. KGaA leverages its global formulation archive to anchor premium industrial accounts in Surabaya and Batam. Sika AG competes through specialized construction-grade systems for Indonesia's elevated infrastructure spending. PT ALTECO Chemical Indonesia dominates regional distribution with localized production and channel control across the archipelago.
Adhesives are non-metallic substances applied to substrates to develop structural or semi-structural bonds through surface attachment, with formulations typically comprising synthetic polymers, tackifiers, curing agents, and functional additives processed via bulk polymerization or emulsion techniques. Their primary commercial purpose spans permanent assembly, temporary fixation, protective coating, and environmental sealing across discrete manufacturing and continuous construction operations. Water-based technology leads volume in Indonesia due to regulatory pressure and wood-processing demand, while reactive systems command margin pools in automotive and electronics bonding where cure speed and thermal resistance justify premium positioning. Hot melt technology extends fastest in packaging lines seeking elimination of solvent drying stages and energy reduction.
BIS technical standards, Indonesia's Ministry of Environment and Forestry emission protocols, and ASEAN harmonized chemical classification frameworks collectively shape product registration pathways and reformulation timelines for both domestic blenders and import-dependent distributors. The country's national pharmaceutical regulator and industrial chemical oversight bodies are tightening import inspection regimes for adhesive raw materials containing restricted isocyanates and formaldehyde-releasing compounds. Stakeholders must monitor regulatory divergence between Jakarta's administrative standards and provincial enforcement practices to anticipate compliance cost shifts.
Market Dynamics
Water-based adhesive technology is displacing solvent-based formulations across Indonesia's manufacturing base as BIS technical standards and Ministry of Environment protocols tighten VOC emission thresholds. This regulatory compression is forcing simultaneous reformulation investments while packaging converters in Java and Sumatra expand bonded carton capacity.
Growth Catalysts
- ASEAN Harmonized Chemical Classification:Regional framework alignment reduces registration friction for cross-border adhesive trade between Indonesia and neighboring manufacturing hubs.
- Packaging Automation:Flexible laminate lines in Greater Jakarta's manufacturing corridor demand hot melt systems that eliminate solvent drying stages and reduce energy consumption.
- Automotive Tier-One Clustering:Electronics assemblers and vehicle component suppliers around Surabaya and Batam pull reactive adhesive systems with superior thermal resistance and cure speed.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer resins and tackifiers face price instability tied to naphtha and propylene supply fluctuations from Singapore refining hubs.
- Import Dependency Concentration:Specialty curing agents and isocyanate-containing raw materials flow through limited port infrastructure, creating bottleneck risk at Tanjung Priok.
- Cure Speed Limitations:Water-based systems fail to match reactive polyurethane performance in high-temperature automotive underhood applications, restricting segment penetration.
Strategic Opportunities
- Eastern Indonesia Archipelago:Sulawesi and Papua manufacturing zones remain underpenetrated by technical adhesive distributors serving construction and marine sectors.
- Green Building Certification:Indonesia's national green building council protocols create specification pull for low-emission construction adhesives in commercial high-rise development.
- UV-Curable Convergence:Ultraviolet curing technology hybridized with digital printing lines offers electronics assemblers instant bonding without thermal damage to sensitive components.
Industry Challenges
- Formulation Chemistry Expertise Gap:Local technical talent scarcity in polymer rheology and curing kinetics delays product development cycles for domestic blenders.
- Provincial Enforcement Divergence:Compliance cost uncertainty persists as Jakarta's administrative standards face inconsistent implementation across regional environment offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Adhesives Market |
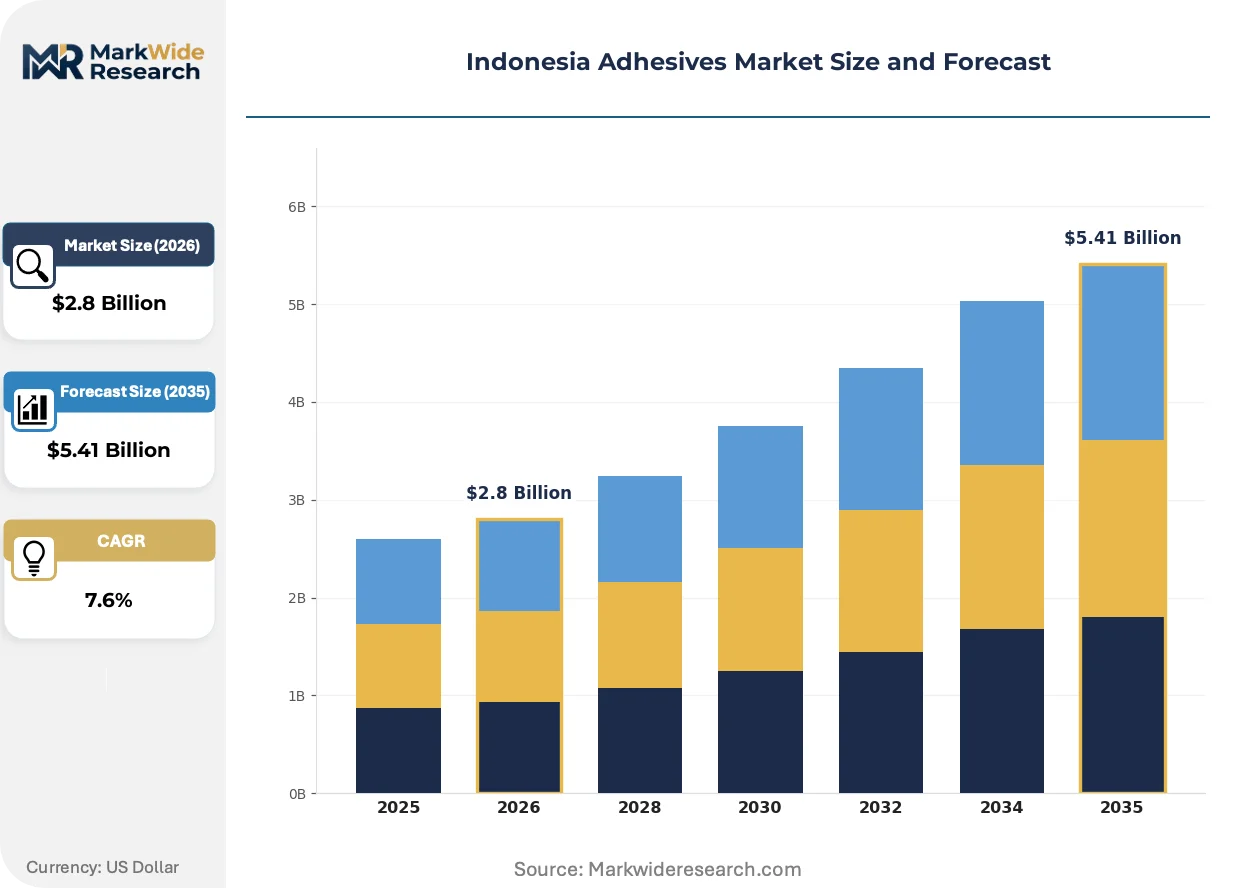
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End User: Construction, Automotive, Electronics, Packaging Technology: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Bonding, Coating, Sealing, Assembly |
| Companies Covered | Sika AG, PT ALTECO Chemical Indonesia, Henkel AG & Co. KGaA, DEXTONE INDONESIA, Pamolite Adhesive Industry, 3M, Pidilite Industries Ltd, PT Ekadharma International Tbk, H.B. Fuller Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Adhesives Market Shifts & Advancements
Reactive hot melt technology is overtaking conventional solvent-based systems as the dominant bonding approach for high-speed packaging lines. This shift compresses equipment footprints while eliminating volatile organic compound handling entirely.
Waterborne polyurethane dispersions are overtaking acrylic emulsions in woodworking and furniture assembly applications. Indonesian panel manufacturers adopt these systems for superior heat resistance and bond durability in tropical humidity conditions. The technology is overtaking commodity alternatives by enabling direct substitution without capital equipment replacement.
Indonesia's Ministry of Environment and Forestry emission protocols now mandate third-party verification for solvent-based adhesive imports. Industrial chemical oversight bodies tightened inspection regimes for formaldehyde-releasing compounds in 2023. Wood-processing facilities in Java face accelerated reformulation timelines to maintain operating licenses under provincial clean air commitments.
Technical service unbundling is reshaping how adhesive suppliers capture value. Packaging converters in Greater Jakarta now contract separately for application equipment validation and bonded joint testing rather than accepting bundled supply agreements. Electronics assemblers in Batam drive this fragmentation by demanding outcome-based performance guarantees independent of material tonnage.
Indonesia Adhesives Market Segmentation
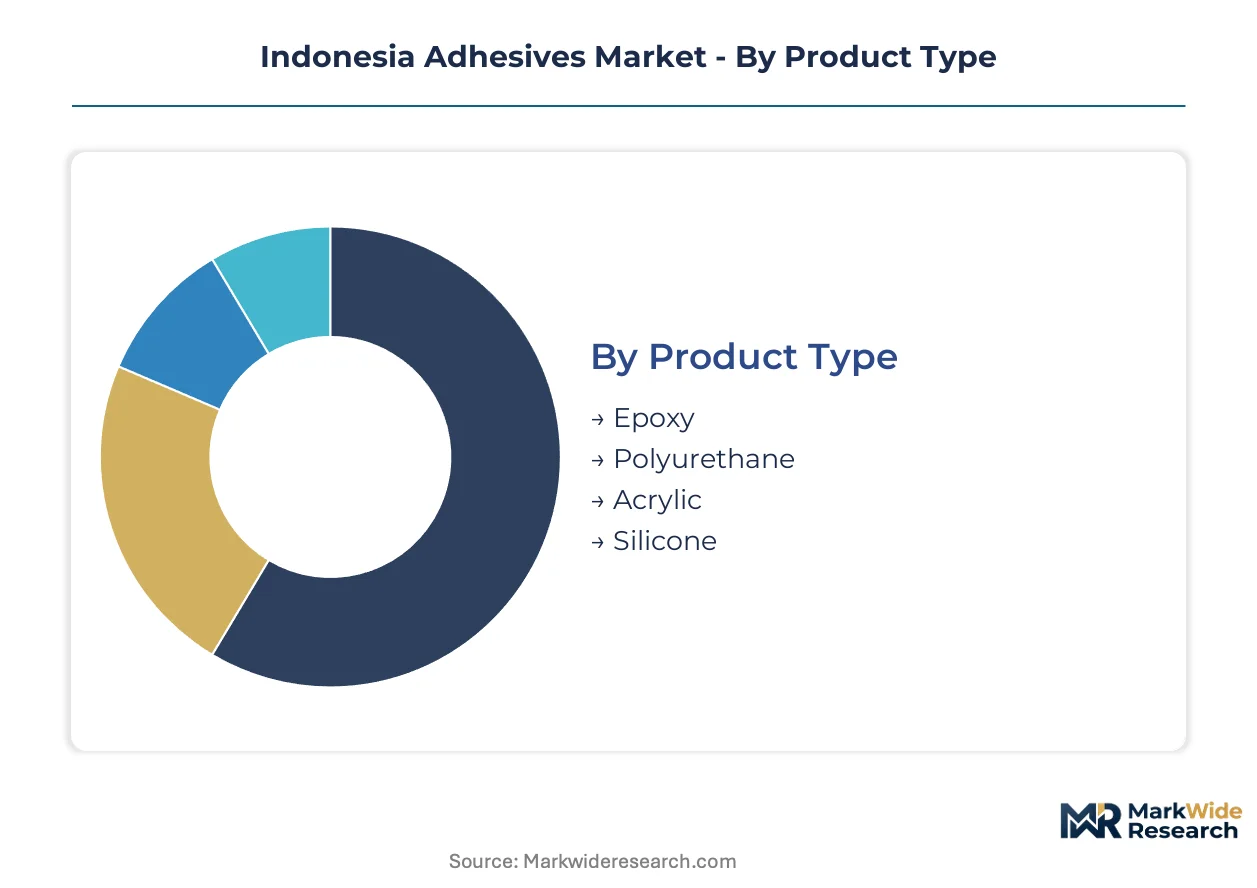
Adhesive formulation chemistry and cure mechanism determine regulatory pathway complexity and capital equipment requirements for Indonesian manufacturers. Segmentation reveals how technology choices lock customers into specific supplier relationships and service contracts across Java and Sumatra's industrial corridors.
Product Type:
Epoxy and polyurethane formulations require BIS technical standard certification plus Ministry of Environment and Forestry emission protocol compliance, while acrylic and silicone systems face lighter registration burdens under ASEAN harmonized chemical classification.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and amine hardeners deliver superior structural strength and chemical resistance. Demand concentrates in Batam's electronics assembly sector where printed circuit board potting and component underfill specifications demand thermal cycling durability. BIS certification timelines extend 8-12 months for new epoxy formulations.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture or catalyst reaction to form flexible bonds with excellent impact absorption. Automotive tier-one suppliers around Surabaya specify polyurethane for interior trim bonding and windshield direct glazing where vibration damping matters. Import inspection regimes for isocyanate raw materials create supply security concerns at Tanjung Priok.
- Acrylic:Emulsion and solvent-borne variants offer rapid tack development and UV stability for outdoor exposure. Construction contractors across Greater Jakarta specify acrylic pressure-sensitive adhesives for flooring and tile applications.
- Silicone:Crosslinked polydimethylsiloxane systems provide temperature resistance from minus fifty to plus two hundred degrees Celsius. Electronics assemblers adopt silicone for thermal interface materials and environmental sealing of sensitive components.
Leading the category by volume: Polyurethane. Growing fastest: Epoxy.
End User:
Customer procurement sophistication varies sharply — packaging converters negotiate outcome-based performance guarantees while construction contractors prioritize distributor availability and technical service response times.
- Construction:Commercial high-rise development and infrastructure projects pull cementitious, tile, and structural bonding systems. Green building certification protocols from Indonesia's national green building council create specification filters favoring low-VOC formulations. Sika AG and PT ALTECO Chemical Indonesia dominate project specification through direct contractor relationships.
- Automotive:Tier-one seating, interior, and powertrain component suppliers demand reactive systems with validated cure kinetics and bonded joint durability testing. Henkel AG anchors premium accounts through global formulation archive access and localized technical service contracts.
- Electronics:Surface mount assembly, display bonding, and device sealing applications require ultra-pure formulations with ionic contamination controls. Batam's free trade zone status attracts precision electronics manufacturing pulling specialized adhesive imports.
- Packaging:Flexible laminate and corrugated carton converters across Java drive water-based and hot melt volume. Automation investments in Greater Jakarta's manufacturing corridor favor systems eliminating solvent drying stages.
Construction commands the largest volume share. Electronics expands most quickly on precision assembly demand.
Technology:
Capital equipment intensity and energy consumption separate technology tiers — water-based systems demand drying ovens while reactive systems require meter-mix-dispense infrastructure.
- Water-Based:Acrylic and polyurethane dispersions in aqueous carrier dominate woodworking and packaging applications. Regulatory pressure from Ministry of Environment protocols accelerates displacement of solvent alternatives. Indonesian panel manufacturers favor these systems for tropical humidity performance.
- Solvent-Based:Hydrocarbon and ester solvent carriers deliver fast tack and high initial bond strength. VOC emission thresholds under BIS technical standards force reformulation investments or import restriction risks.
- Hot Melt:Thermoplastic EVA and polyolefin formulations applied molten and set on cooling. Packaging automation lines in Greater Jakarta adopt reactive hot melt variants for instant handling strength without solvent exposure.
- Reactive:Two-component polyurethane, epoxy, and UV-curable systems cure through chemical reaction or radiation exposure. Automotive underhood and electronics applications specify these for thermal resistance and cure speed despite higher applied costs.
Water-based technology leads volume. Reactive systems capture the steepest expansion trajectory on automotive and electronics specification pull.
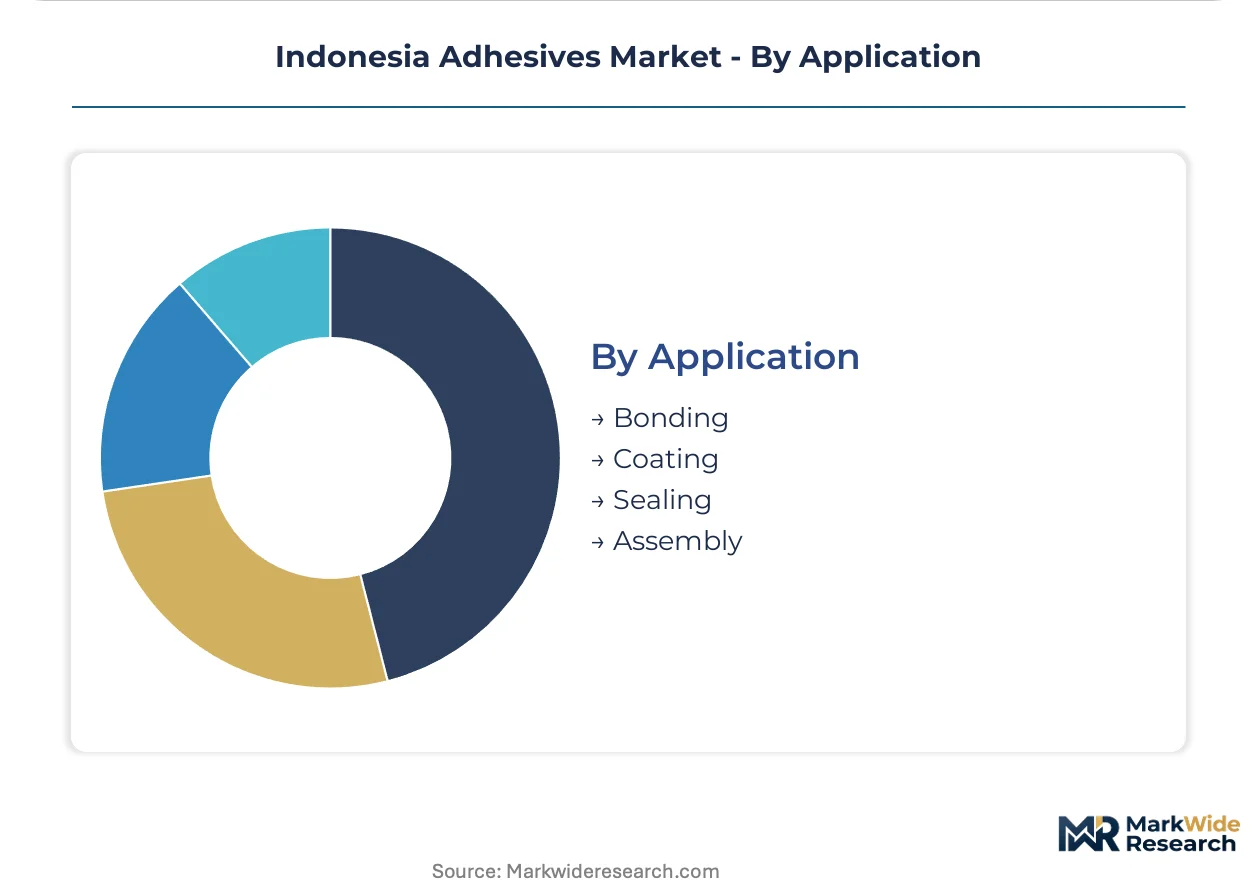
Application:
Functional purpose determines performance validation protocols — structural bonding demands lap shear testing while sealing applications require elongation and compression set measurement.
- Bonding:Permanent substrate attachment for load-bearing and non-structural assemblies. Woodworking facilities across Java specify waterborne polyurethane dispersions for panel lamination and furniture assembly.
- Coating:Protective and decorative surface films providing environmental barrier properties. Construction applications specify coating adhesives for flooring wear layers and waterproof membranes.
- Sealing:Gap-filling and environmental isolation for joints and penetrations. Electronics assemblers in Batam demand silicone and modified silicone systems for device ingress protection.
- Assembly:Multi-component fixation and temporary positioning prior to permanent cure. Automotive interior suppliers specify hot melt and pressure-sensitive systems for trim attachment and wire harness securing.
Bonding captures the largest application share. Sealing gains share fastest on electronics environmental protection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta's manufacturing corridor concentrates Indonesia's adhesive demand through automotive tier-one suppliers and electronics assemblers clustered across Bekasi, Tangerang, and Bogor industrial zones.
Java
Woodworking facilities in Central Java and packaging converters across East Java drive water-based adhesive volume. BIS technical standards enforcement tightens VOC emission thresholds. Surabaya's automotive component cluster specifies polyurethane systems for interior trim bonding and vibration damping applications.
Sumatra
Palm oil processing equipment maintenance and rubber glove manufacturing pull industrial-grade bonding systems. Ministry of Environment and Forestry protocols accelerate solvent-based formulation phase-out. Medan's logistics hub serves as distribution gateway for Sumatran manufacturing zones seeking technical adhesive supply security.
Kalimantan
Coal mining equipment repair and construction activity around Balikpapan and Samaranda create demand for heavy-duty structural adhesives. Provincial clean air commitments impose reformulation timelines on imported solvent-based products. Samarinda's industrial park hosts emerging wood panel processing investments adopting waterborne polyurethane dispersions.
Sulawesi
Nickel processing plant construction and stainless steel facility expansion generate construction adhesive specification opportunities. National green building council protocols filter project approvals toward low-VOC formulation categories. Morowali Industrial Park's battery material investments attract technical distributor presence for chemical-resistant bonding systems.
Batam
Free trade zone status attracts precision electronics manufacturing requiring ultra-pure adhesive formulations with ionic contamination controls. ASEAN harmonized chemical classification reduces registration friction for cross-border raw material movements. Batam's semiconductor packaging houses specify epoxy underfill and thermal interface materials for thermal cycling durability.
Indonesia Adhesives Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across Indonesia's adhesive supply chain. Domestic blenders with captive manufacturing assets battle import-dependent traders for share in Greater Jakarta's manufacturing corridor. Three archetypes dominate: multinational formulators leveraging global technical archives, regional distributors controlling archipelago logistics, and local blenders serving price-sensitive construction segments. Strategic moves concentrate on technical service unbundling and provincial distribution network expansion.
Among multinational formulators, Henkel AG & Co. KGaA and Sika AG exemplify premium-tier positioning through technical service anchoring. PT ALTECO Chemical Indonesia occupies a distinct archetype as a domestic producer with archipelago-wide channel control. These three represent the structural separation between global formulation expertise and localized distribution density.
| Leading Market Players |
|---|
| Sika AG |
| PT ALTECO Chemical Indonesia |
| Henkel AG & Co. KGaA |
| DEXTONE INDONESIA |
| Pamolite Adhesive Industry |
| 3M |
| Pidilite Industries Ltd |
| PT Ekadharma International Tbk |
| H.B. Fuller Company |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between BIS-compliant industrial formulations and unverified commodity imports splits Indonesia's adhesive market into parallel pricing ecosystems, with premium tiers commanding service-intensive supply relationships while economy segments flow through trader-mediated port arbitrage. This bifurcation concentrates margin capture among multinationals with localized technical archives while domestic blenders compete on feedstock cost minimization through Singapore naphtha-linked procurement.
Pricing Analysis
Margin tightening in water-based formulations reflects Ministry of Environment protocol compliance investments and third-party verification costs for VOC emission thresholds. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels separates Henkel and Sika specification accounts from price-driven construction distributors. Price differentiation hinges on BIS certification status and technical service bundling. Packaging converters in Greater Jakarta demonstrate highest price sensitivity through unbundled equipment validation contracts, while automotive tier-one suppliers accept premium positioning for validated cure kinetics.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one automotive and electronics demand around Surabaya and Batam, while distributor networks serve construction contractors across the archipelago. Feedstock supply concentrates in Singapore, South Korea, and Japan for synthetic polymer resins, isocyanate prepolymers, and specialty tackifiers. Raw material flows depend on naphtha cracking economics, propylene derivative availability, and formaldehyde-releasing compound inspection regimes. Single-source vulnerability at Tanjung Priok for isocyanate-containing imports creates bottleneck exposure. Distribution runs through PT ALTECO's archipelago logistics infrastructure and multinational direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compression on solvent-based formulations is forcing consolidation as compliance investments exceed returns for import-dependent traders without technical service capabilities.
For Market Incumbents: Lock in specification authority through BIS certification acceleration and localized formulation archives that match Henkel's Surabaya technical service model. Deepen channel control in Eastern Indonesia archipelago zones before distributor competitors establish presence. Defend against water-based displacement by embedding application equipment validation into supply contracts. For New Entrants and Emerging Players: Enter via Sulawesi and Papua construction zones where technical adhesive distribution remains sparse and national green building council protocols create specification entry points. Target nickel processing facility maintenance contracts in Morowali Industrial Park with chemical-resistant polyurethane systems. Lead with UV-curable convergence offerings for Batam electronics assemblers seeking thermal-damage elimination. For Investors and Strategic Acquirers: Exit pathways concentrate in technical service-capable regional distributors with BIS registration portfolios and archipelago logistics infrastructure. Long-term viability favors assets with backward integration into waterborne polyurethane dispersion production and provincial environment office relationships. Watch for Ministry of Environment protocol enforcement divergence between Jakarta and regional offices as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Polyurethane Production | Captures margin pools in woodworking panel lamination while insulating from Singapore naphtha volatility. |
| BIS Certification Fast-Track Investment | Accelerates product registration timelines against competitors facing 8-12 month epoxy approval delays. |
| Eastern Indonesia Distribution Network Buildout | Establishes first-mover presence in Sulawesi construction and marine bonding before incumbent expansion. |
| Technical Service Unbundling and Equipment Validation | Aligns with Greater Jakarta packaging converter procurement fragmentation toward outcome-based contracts. |
| UV-Curable Formulation Development Partnership | Addresses Batam electronics assembler demand for instant bonding without thermal damage to sensitive components. |
Research Methodology
Multi-period observation of BIS certification timelines, Ministry of Environment enforcement patterns, and port import inspection frequencies anchored the trend analysis, supplemented by interviews with adhesive plant managers, procurement leads at automotive tier-one suppliers, distribution channel partners, and technical R&D directors across Java and Sumatra. Secondary validation drew from Indonesian customs trade data, ASEAN harmonized chemical classification frameworks, SEC filings of multinational formulators, and provincial clean air commitment disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation reconciled volume estimates.
Segment-weighting across formulation chemistry, cure mechanism technology, end-use industry, and regional manufacturing corridor concentration shaped the analytical framework over the projection horizon. CAGRs were derived from installed capacity expansion announcements, automation investment trajectories, and regulatory phase-out schedules for solvent-based systems. Forecast inputs incorporated petrochemical feedstock price elasticity and electronics assembly reshoring patterns into Batam's free trade zone.
Revisions become necessary when Ministry of Environment protocol enforcement diverges from Jakarta administrative standards, when Tanjung Priok logistics disruptions exceed historical baseline, or when ASEAN chemical classification harmonization stalls. Forecasts reflect documented assumptions on BIS certification throughput rates and water-based technology substitution curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Removable Adhesive Market