
 Space Traffic Management Market | 2026-2036
Space Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
Space Traffic Management Market Outlook
Defense organization spending is rebalancing toward orbital tracking and collision avoidance as satellite constellation density rises. Lockheed Martin Corporation leverages its long-standing government relationships to anchor classified space situational awareness programs. LeoLabs, Inc. specializes in radar-based tracking of small satellites and debris fragments, occupying a distinct technical tier below prime contractors. Northrop Grumman Corporation extends its sensor portfolio into space domain awareness, competing on integrated ground-to-orbit architectures.
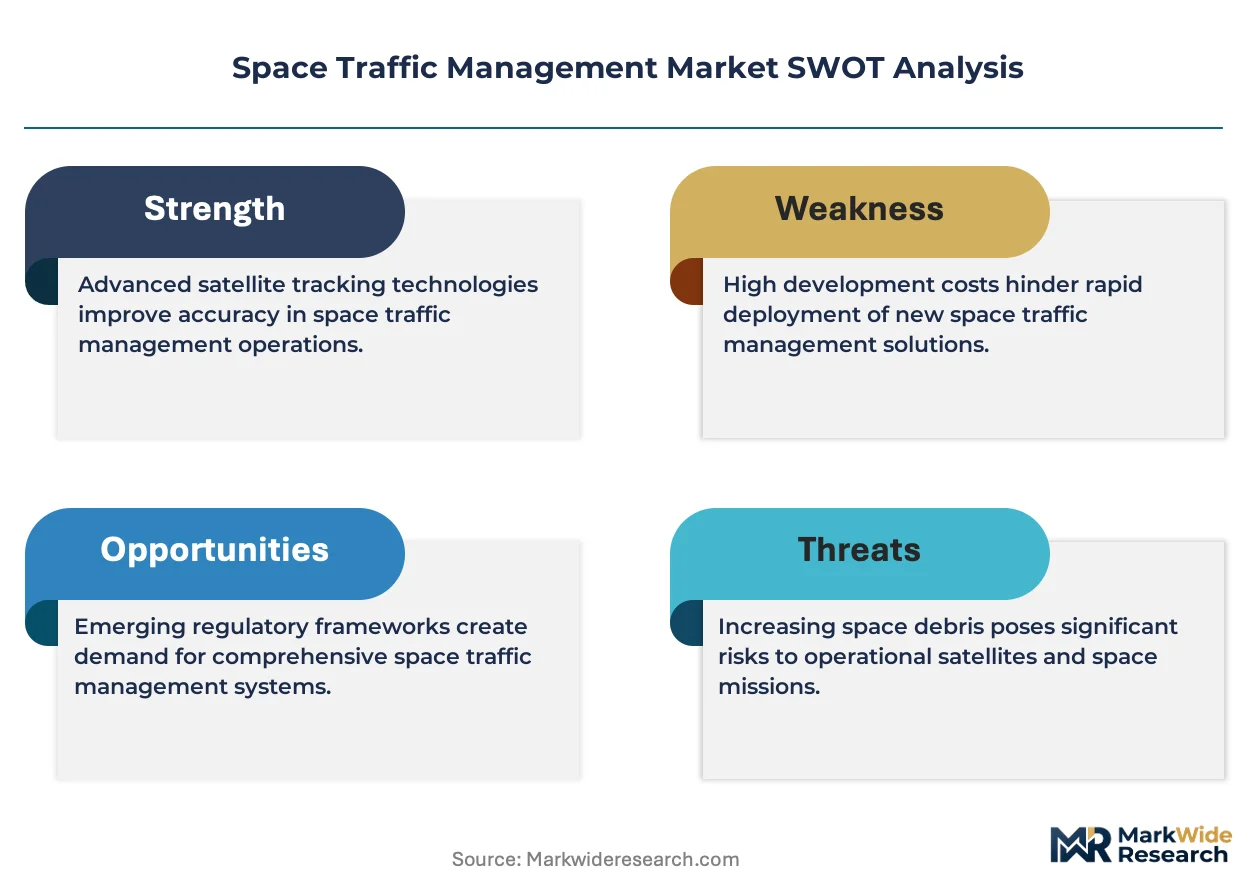
Space Traffic Management encompasses the monitoring, prediction, and coordination of spacecraft and debris trajectories using radar, optical, and laser tracking systems with sub-meter positional accuracy to prevent orbital collisions and protect critical infrastructure. Ground-Based Systems currently dominate operational budgets due to legacy radar networks and optical telescope installations, though Hybrid Systems integrating space-based sensors with terrestrial processing are capturing the fastest-growing share of new contracts. Software Solutions for conjunction assessment and maneuver planning concentrate margin pools, while Collision Avoidance services generate recurring revenue from commercial constellation operators requiring continuous screening.
The FCC enforces orbital debris mitigation rules that shape operator licensing and end-of-life disposal requirements for U.S.-registered spacecraft. NASA and the U.S. Space Force coordinate space situational awareness data sharing protocols that influence procurement standards and interoperability mandates for vendors. Stakeholders must monitor evolving international coordination frameworks and decide whether to align product roadmaps with government data formats or pursue independent sensor architectures.
Market Dynamics
The collision risk from proliferating satellite mega-constellations is forcing operators and governments into real-time coordination architectures. Orbital density above 1,200 kilometers now exceeds historical tracking capacity, compressing maneuver windows and elevating demand for predictive analytics.
Growth Catalysts
- Debris Mitigation Mandates:The FCC enforces stricter end-of-life disposal rules for U.S.-licensed spacecraft, compelling operators to procure active tracking services. Compliance deadlines accelerate procurement cycles.
- Military Space Domain Awareness:The U.S. Space Force expands classified surveillance networks, creating anchor demand for high-precision orbital catalogs. Defense budgets prioritize collision avoidance for national security payloads.
- Small Satellite Proliferation:CubeSat and microsatellite deployments exceed 3,000 active units, overwhelming legacy radar networks. Commercial operators seek dedicated tracking for non-cooperative objects below one meter.
Market Restraints
- Sensor Infrastructure Capital Intensity:Phased-array radar installations require $50-150 million per site, concentrating supply among defense primes. Smaller vendors face barrier-to-entry thresholds.
- Data Sovereignty Fragmentation:Military classification protocols restrict sharing of high-fidelity orbital data across national boundaries. Commercial operators receive degraded ephemeris, limiting prediction accuracy.
- Optical Tracking Limitations:Ground-based telescopes suffer weather dependency and daylight gaps. Persistent coverage requires redundant geographic distribution that multiplies operational cost.
Strategic Opportunities
- Space-Based Sensor Architectures:Orbital platforms eliminate atmospheric interference and enable continuous debris monitoring. Early movers capture premium positioning for government data fusion contracts.
- India's Emerging Launch Market:ISRO's commercial rideshare program accelerates Indian-registered satellite populations. Indigenous tracking infrastructure remains underdeveloped, creating vendor entry potential.
- Machine Learning Convergence:Neural networks processing radar returns improve fragment classification accuracy. Operators reduce false conjunction alerts, cutting maneuver fuel expenditure.
Industry Challenges
- Astrodynamics Talent Scarcity:Specialized orbital mechanics expertise concentrates in aerospace engineering programs with limited annual graduates. Vendors compete for PhD-level analysts across defense and commercial sectors.
- Legacy System Interoperability:NATO and allied space surveillance networks operate on incompatible data formats. Integration projects demand custom middleware development, extending deployment timelines.
- International Standardization Delays:ISO working groups on space traffic coordination lack binding enforcement mechanisms. Voluntary guidelines create inconsistent operator behavior across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Traffic Management Market |
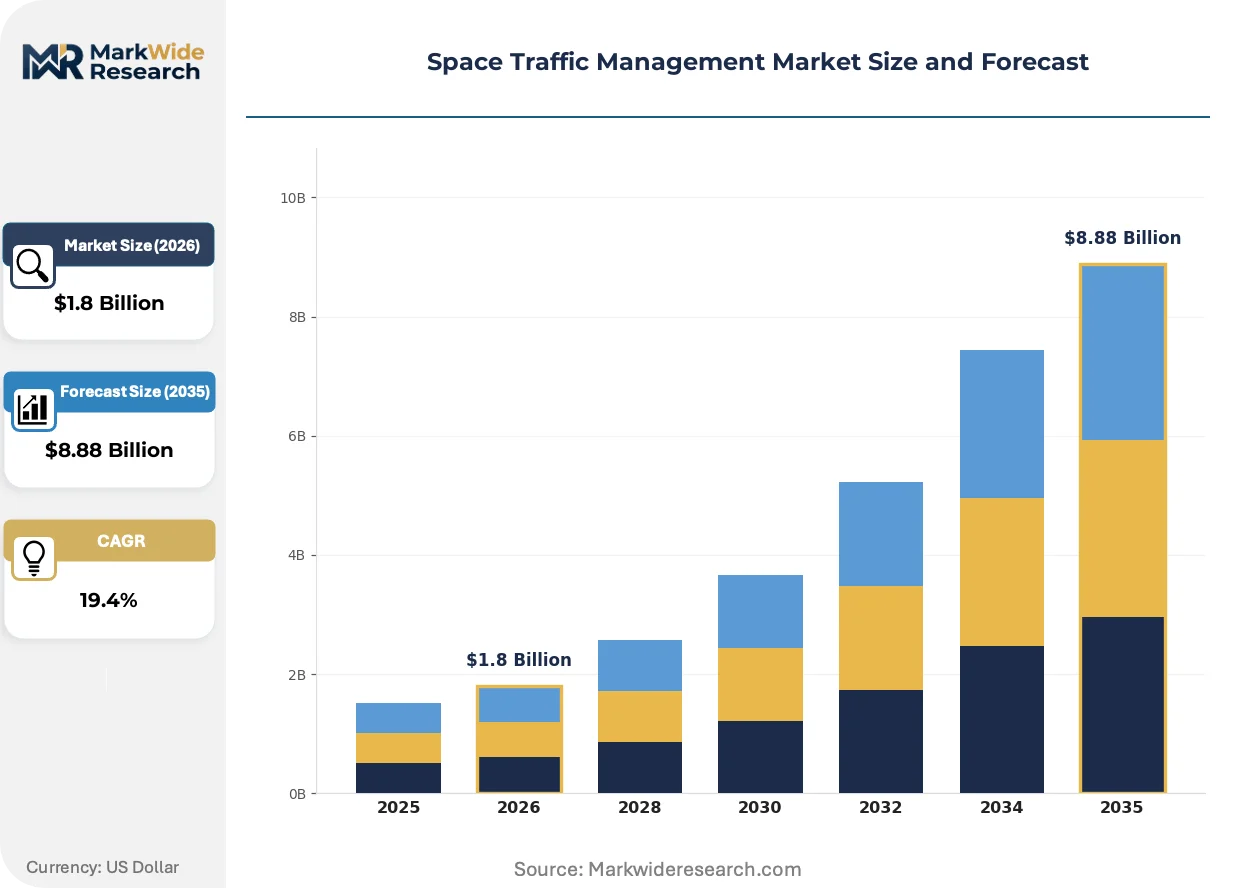
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Space-Based Systems, Ground-Based Systems, Hybrid Systems, Software Solutions Service Type: Collision Avoidance, Monitoring Services, Data Analytics, Regulatory Compliance Customer Type: Government Agencies, Commercial Operators, Research Institutions, Defense Organizations Deployment: On-Premises, Cloud-Based, Hybrid Deployment, Mobile Solutions |
| Companies Covered | L3Harris Technologies, Inc., LeoLabs, Inc., Lockheed Martin Corporation, BAE Systems plc, Astroscale Holdings Inc., Northrop Grumman Corporation, Thales Group, Raytheon Technologies Corporation, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Traffic Management Market Strategic Shifts
Artificial intelligence is compressing conjunction assessment timelines from hours to minutes, reshaping operational workflows for constellation operators. Three developments dominate competitive positioning.
Neural network-based orbit determination is automating the correlation of sparse radar tracks with cataloged objects. Commercial satellite operators now demand sub-thirty-minute screening turnaround, displacing batch-processed legacy systems. The technology compresses staffing requirements while expanding screening volume capacity.
The FCC's updated spectrum and orbital debris rules tighten operator compliance obligations for U.S.-registered spacecraft. Licensing now requires verifiable maneuver capability and post-mission disposal probability thresholds. Small satellite ventures face elevated insurance and bonding costs, favoring established operators with proven track records.
Service-based contracting is displacing capital-intensive sensor ownership among commercial constellation managers. Operators prefer subscription access to multi-source tracking data over building proprietary ground stations. This shift concentrates vendor relationships with specialized providers like LeoLabs while reducing fixed asset burdens.
Space Traffic Management Market Segmentation
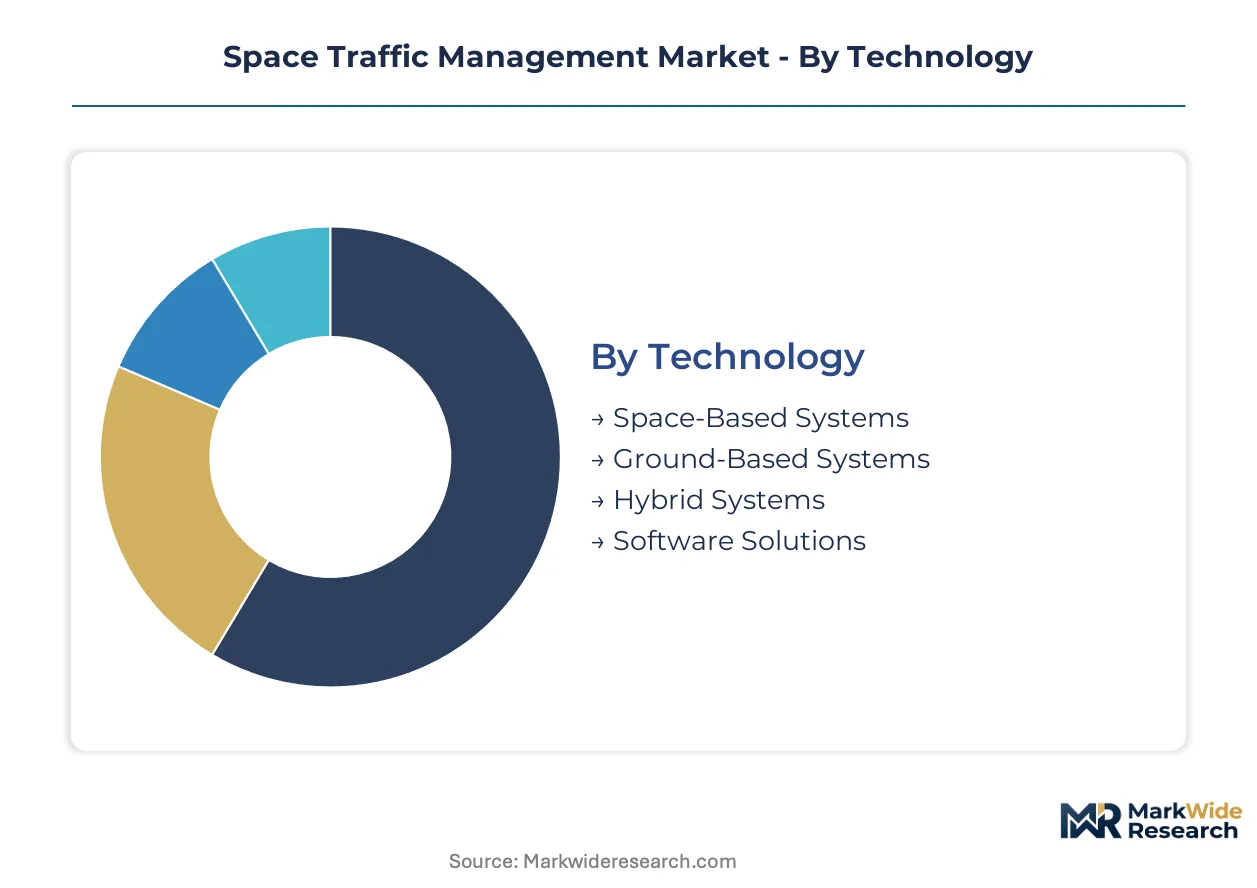
Space traffic management vendors configure product portfolios around four intersecting dimensions. Technology choices determine capital intensity and data fidelity. Service packaging shapes recurring revenue stability and customer retention mechanics.
Technology:
Ground-based radar networks absorb the majority of current procurement budgets, while space-based architectures command premium positioning for next-generation contracts.
- Ground-Based Systems:Phased-array radar installations and optical telescope networks deliver sub-meter positional accuracy for cataloged objects. NASA and the U.S. Space Force anchor demand through legacy infrastructure upgrades and interoperability mandates for national security payloads.
- Hybrid Systems:Integrated architectures fuse terrestrial sensor feeds with space-based data streams, eliminating atmospheric interference gaps while preserving processing economies. Commercial constellation operators in the United States prioritize these configurations for continuous coverage of high-value orbital regimes.
- Space-Based Systems:Orbital sensor platforms enable persistent debris monitoring without weather or daylight constraints.
- Software Solutions:Conjunction assessment algorithms and maneuver planning tools concentrate margin pools through recurring licensing.
Today's leader: Ground-Based Systems. Tomorrow's challenger: Hybrid Systems.
Service Type:
Service packaging separates mission-critical collision avoidance from compliance-driven regulatory offerings, with data analytics emerging as the margin expansion layer.
- Collision Avoidance:Real-time trajectory screening and maneuver recommendation services protect high-value satellites from conjunction events. Commercial operators with dense constellations above 1,200 kilometers purchase subscription screening to compress response windows and reduce fuel expenditure from false alerts.
- Data Analytics:Predictive models processing orbital catalogs identify long-term debris evolution patterns and asset risk exposure. Insurance underwriters and satellite fleet managers in the United States leverage these capabilities for bonding verification and premium calibration.
- Monitoring Services:Continuous tracking of non-cooperative objects below one meter in size.
- Regulatory Compliance:FCC-mandated end-of-life disposal verification and maneuver capability documentation.
Collision Avoidance locks in baseline revenue. Data Analytics climbs the fastest as operators seek predictive rather than reactive capabilities.
Customer Type:
Defense and government segments concentrate procurement volume, while commercial operators represent the expansion frontier as constellation density escalates.
- Government Agencies:NASA and civil space programs procure foundational space situational awareness infrastructure and data sharing protocols. These contracts establish technical standards that cascade into vendor qualification requirements for downstream commercial opportunities.
- Defense Organizations:Classified surveillance networks and national security payload protection drive premium pricing for high-fidelity orbital catalogs. The U.S. Space Force expands dedicated tracking capacity for sensitive orbital regimes, creating anchor demand insulated from commercial pricing pressure.
- Commercial Operators:Satellite constellation managers purchasing subscription tracking services.
- Research Institutions:Academic and scientific users accessing archival orbital data for debris modeling.
Defense Organizations dominate contract value. Commercial Operators gain share fastest as mega-constellation deployments multiply screening volumes.
Deployment:
Cloud architectures displace on-premises installations as operators prioritize scalability over capital ownership, with hybrid configurations bridging security-classified and commercial workloads.
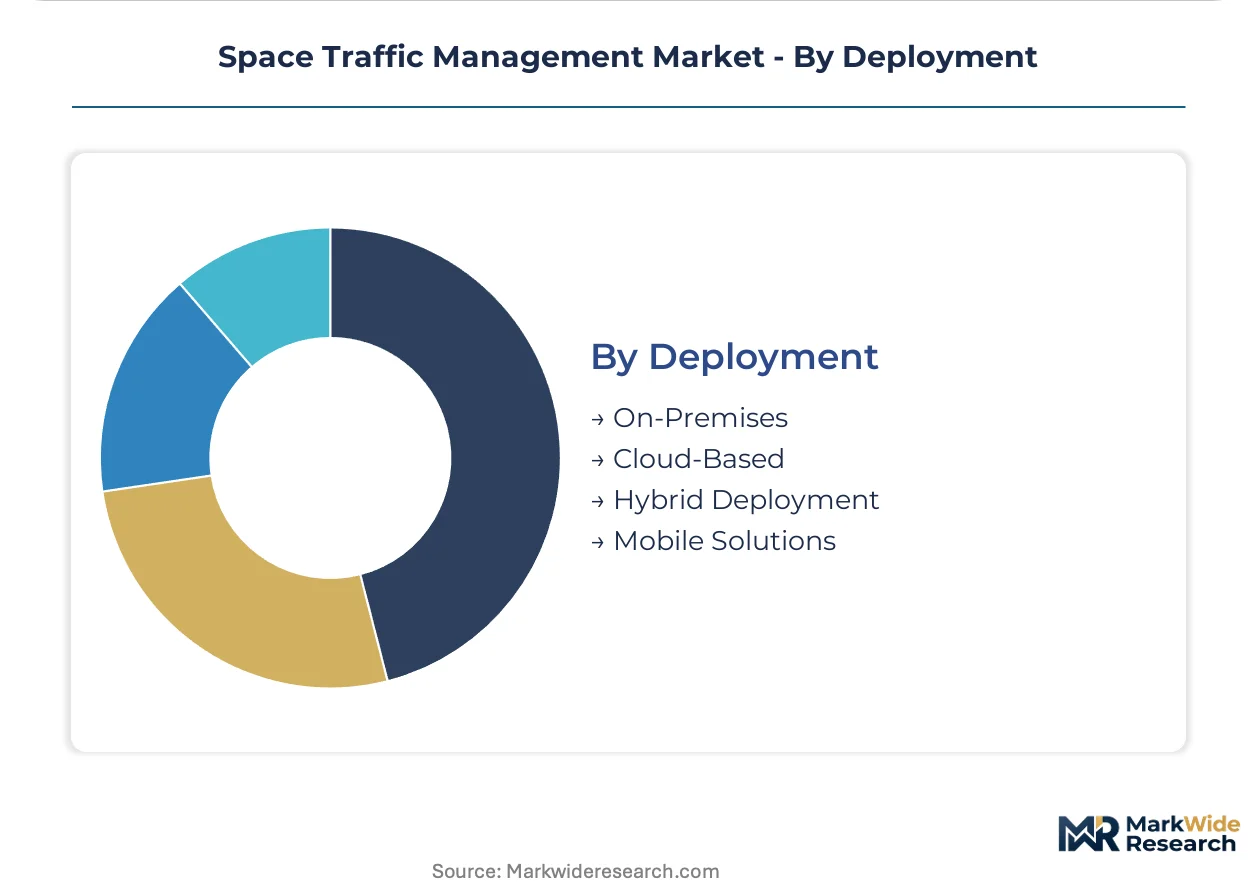
- Cloud-Based:Scalable processing environments accommodate variable conjunction screening loads without fixed infrastructure commitment. Commercial constellation operators prefer subscription access to multi-source tracking databases over proprietary ground station construction.
- Hybrid Deployment:Segregated architectures process classified government data on-premises while routing commercial workloads through cloud pipelines. This configuration satisfies U.S. Space Force security protocols while capturing cloud economics for non-sensitive operations.
- On-Premises:Dedicated installations for operators with stringent data sovereignty requirements.
- Mobile Solutions:Portable tracking terminals for expeditionary or contingency operations.
Cloud-Based deployment captures the fastest expansion trajectory. Hybrid Deployment satisfies the security-economy tension for dual-use vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colorado Front Range anchors North American space traffic management activity, hosting dense clusters of ground-based radar installations and defense contractor operations that shape procurement standards across allied nations.
United States
NASA and the U.S. Space Force drive procurement of orbital tracking infrastructure through classified surveillance network expansions. The FCC enforces orbital debris mitigation rules that compel commercial operators to document end-of-life disposal capabilities. The Colorado Springs-Denver corridor concentrates prime contractor facilities and Space Force command operations.
United Kingdom
The UK Space Agency accelerates investment in national space domain awareness capabilities following satellite constellation licensing growth. Ministry of Defence procurement prioritizes interoperability with NATO space surveillance networks. Harwell Science and Innovation Campus hosts emerging sensor technology development clusters.
Germany
Deutsche Raumfahrtagentur coordinates civil-military data sharing protocols for conjunction assessment services. The national aerospace regulator aligns licensing requirements with emerging EU space traffic coordination frameworks. Munich-Stuttgart industrial corridors concentrate optical telescope manufacturing and ground station engineering expertise.
France
CNES expands orbital monitoring partnerships with commercial radar operators to address small satellite tracking gaps. National defense procurement prioritizes autonomous space situational awareness capabilities for sovereign payload protection. Toulouse aerospace clusters integrate sensor development with satellite manufacturing supply chains.
Japan
JAXA collaborates with U.S. Space Force on data sharing agreements for Indo-Pacific orbital coverage. METI funding accelerates domestic radar network modernization to address mega-constellation monitoring demands. Tsukuba science city clusters space situational awareness research with commercial debris removal ventures.
Space Traffic Management Market Competitive Environment
Strategic partnerships dominate the current landscape as sensor infrastructure costs concentrate operational scale among defense primes and specialized tracking ventures. The vendor base separates into three distinct tiers: legacy aerospace conglomerates with classified program access, commercial radar specialists serving constellation operators, and emerging debris removal ventures integrating tracking with active remediation. Prime contractors anchor government procurement through integrated ground-to-orbit architectures. Mid-tier specialists capture commercial subscription demand with dedicated small-object tracking capabilities. Competitive intensity centers on data fusion contracts and multi-source catalog integration mandates.
Within the defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify integrated system providers with established Space Force relationships. LeoLabs, Inc. occupies a distinct position among commercial specialists, representing the radar-native tracking archetype that serves constellation operators outside classified procurement channels. These three anchors illustrate the market's bifurcation between sovereign security infrastructure and commercial subscription services.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| LeoLabs, Inc. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Astroscale Holdings Inc. |
| Northrop Grumman Corporation |
| Thales Group |
| Raytheon Technologies Corporation |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
FCC orbital debris mitigation mandates gate qualified supply for U.S.-registered spacecraft operators, restricting premium-tier pricing access to vendors with verifiable maneuver capability and end-of-life disposal documentation. Compliance deadlines compress procurement cycles while elevating bonding and insurance costs for non-compliant entrants.
Pricing Analysis
Direct-to-government contract discounts anchor the pricing architecture, with subscription SaaS-tiered models dominating commercial constellation operator procurement. Price differentiation hinges on sensor fidelity tiers and FCC certification status, with hybrid system integrators commanding premiums over pure software vendors. Pricing pressure stems from capital intensity of phased-array radar installations, squeezing mid-tier vendors unable to amortize infrastructure costs. Commercial operators with dense satellite populations exhibit highest price sensitivity, while defense organizations prioritize capability over unit economics.
Supply Chain Analysis
Specialized astrodynamics talent scarcity in the Colorado Springs-Denver corridor and Munich-Stuttgart industrial regions constrains manufacturing scale for precision tracking components. Supply concentrates in the United States, Germany, and Japan for phased-array radar subsystems and optical telescope assemblies. Raw material dependencies include gallium nitride semiconductors, precision optical glass, and high-grade aluminum alloys. Single-source vulnerability runs through domestic radar component foundries. Distribution runs through prime contractor integration channels for defense contracts and direct subscription platforms for commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Space traffic management functions as a margin-expansion story where service-based contracting displaces capital ownership, compressing fixed asset burdens while elevating recurring revenue stability for qualified vendors.
For Market Incumbents: Deploy machine learning convergence as the primary capability lever to automate fragment classification and reduce false conjunction alerts. Incumbent radar operators should deepen sensor network density above 1,200 kilometers to defend against emerging space-based sensor architectures. Lockheed Martin and Northrop Grumman must accelerate hybrid system integration to counter LeoLabs' commercial subscription momentum.
For New Entrants and Emerging Players: Commercial constellation operators with sub-one-meter satellite tracking needs represent the most penetrable buyer archetype currently underserved by legacy radar networks. India's ISRO commercial rideshare program offers geographic white space with underdeveloped indigenous tracking infrastructure. New entrants should pursue cloud-native conjunction assessment platforms to bypass capital-intensive ground station construction.
For Investors and Strategic Acquirers: Roll-up economics work for specialized radar tracking ventures because sensor infrastructure costs concentrate operational scale and create natural consolidation pressure. The 5-10 year viability window favors vendors with Space Force data fusion contracts and FCC compliance verification capabilities. Acquisition targets should demonstrate neural network-based orbit determination and multi-source catalog integration. Watch for inflection in international standardization binding enforcement as the signal triggering accelerated regulatory compliance procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Space-Based Sensor Deployment | Orbital platforms eliminate atmospheric interference for persistent debris monitoring above 1,200 kilometers. |
| Machine Learning Integration | Neural networks compress conjunction assessment timelines from hours to minutes for constellation operators. |
| Hybrid System Architecture | Integrated terrestrial-space sensor feeds satisfy U.S. Space Force security protocols while capturing cloud economics. |
| Regulatory Compliance Service | FCC-mandated end-of-life disposal verification creates recurring revenue from bonding and documentation requirements. |
| Strategic Partnership Formation | Data sharing agreements with NASA and Space Force establish vendor qualification for downstream commercial opportunities. |
Study Parameters
Direct dialogue with Space Force program officers, commercial constellation operations directors, FCC regulatory affairs leads, and radar system engineering heads grounded the qualitative foundation. Secondary validation drew from FCC orbital debris rulemakings, NASA space situational awareness data sharing protocols, U.S. Space Force budget justifications, and SEC 10-K filings from defense primes. Bottom-up sensor deployment tallies and top-down defense procurement budget analysis were triangulated to anchor market sizing.
Segment-level revenue projections across ground-based, hybrid, and space-based technology tiers were produced through the analytical framework. Deployment model segmentation by cloud, hybrid, and on-premises configurations was modeled alongside customer type splits between defense organizations and commercial operators. CAGRs were derived from procurement cycle acceleration tied to FCC compliance deadlines and constellation density trajectories. Forecast inputs incorporated phased-array radar installation timelines and neural network adoption curves for orbit determination automation.
Underlying measurement precision varies by segment; defense organization contract values carry tighter precision than emerging commercial operator subscription estimates due to classification protocols. Forecasts reflect assumptions around international coordination framework evolution and machine learning convergence timelines. Material deviation in FCC enforcement intensity or Space Force surveillance network expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space-Based Solar Power Market
Space
Rocket Launchpad Market
Space
Space Rover Market
Space
Spacecraft Market
Space
Private Space Travel Market
Space
Space Management Solutions Market
Space
Space Mining Market
Space
India Space Electronics Market
Space
France Space Electronics Market
Space
Italy Space Electronics Market
Space
Space Burial Service Market
Space
Europe Space Logistics Market
Space
Carrier Rocket Market
Space
Asteroid Mining Market
Space
Suborbital Space Tourism Market
Space
LAMEA Space As a Service Market