
 Global Post-Consumer Recycled Plastics Market | 2026-2036
Global Post-Consumer Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Post-Consumer Recycled Plastics Market Foresight
Multi-source feedstock aggregation is rebalancing toward vertically integrated collection-sorting-reprocessing chains. Veolia anchors European municipal collection infrastructure and extends into mechanical recycling capacity. LyondellBasell Industries N.V. competes through proprietary molecular recycling technology that sustains polymer quality across cycles. SABIC differentiates via certified circular polymers derived from mixed plastic waste streams.
Post-consumer recycled plastics comprise reprocessed polymers recovered from end-use products, typically requiring flake washing, extrusion, and pelletization to achieve melt flow indices between 0.7 and 1.0 g/10min for bottle-grade applications. These materials displace virgin resin in packaging, construction, and automotive applications where technical specifications permit partial or full substitution. Polyethylene terephthalate dominates packaging applications due to established food-contact approval pathways, while polypropylene captures expanding share in automotive components demanding higher heat resistance. Mechanical recycling retains margin leadership for clear monostream feedstocks, though chemical recycling commands premium positioning for contaminated or degraded polymer recovery.
The EU Green Deal and REACH framework mandate recycled content thresholds and restrict hazardous additive carryover, compelling processors to certify chain-of-custody documentation. FDA equivalency assessments for food-contact recycled plastics in the United States create parallel compliance obligations for exporters. Stakeholders must monitor chemical recycling scale-up economics against mechanical reprocessing yields to optimize capital allocation across technology pathways.
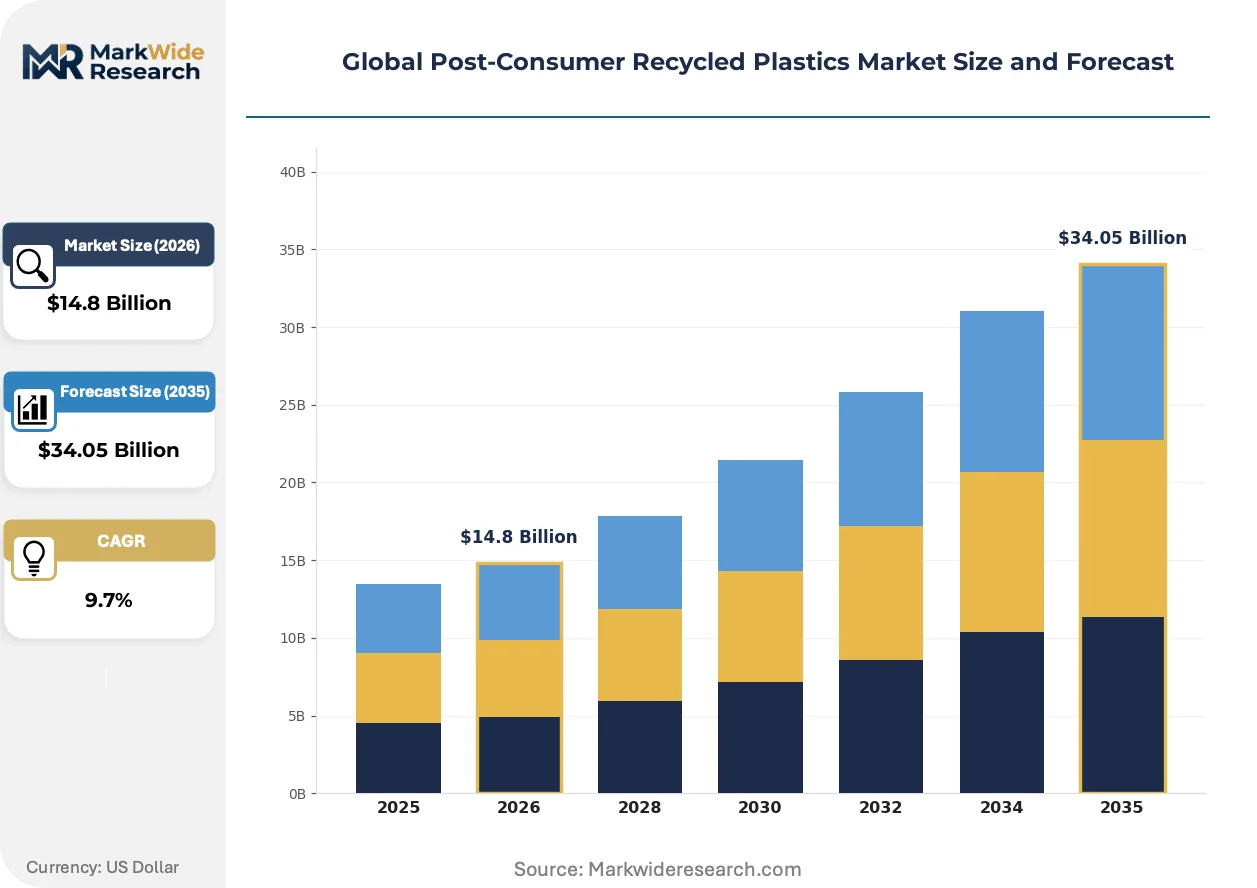
Market Dynamics
The EU Green Deal's recycled content mandates are compressing virgin resin demand while forcing packaging converters to requalify supply chains around certified circular feedstocks. Mechanical recyclers face margin pressure from chemical recycling scale-up in Germany and the Netherlands.
Growth Catalysts
- EU Green Deal mandates:Binding recycled content thresholds for packaging are pulling food-grade rPET into European beverage bottles. Bavarian converters are expanding pelletization capacity to meet 2025 compliance deadlines.
- Automotive lightweighting:Polypropylene recycled content is displacing metal in HVAC housings and interior trim. Baden-Württemberg molding clusters specify heat-stabilized grades for under-hood applications.
- Chemical recycling scale-up:Pyrolysis and depolymerization units in Rotterdam and Antwerp are recovering degraded polymers from mixed waste streams. These outputs achieve virgin-equivalent melt flow indices for sensitive applications.
Market Restraints
- Feedstock cost volatility:Baled PET flake prices swing with crude oil parity and seasonal collection volumes. Municipal collection shortfalls in Southern Europe tighten monostream availability.
- Technical degradation limits:Mechanical recycling shear history reduces polymer chain length. Each reprocessing cycle degrades intrinsic viscosity below bottle-grade thresholds.
- Regulatory fragmentation:FDA food-contact approvals for recycled plastics lag EU EFSA equivalency pathways. US export processors face dual certification burdens.
Strategic Opportunities
- Underpenetrated automotive interiors:Japanese OEMs are qualifying rPP for door panels and seat backs. METI circular economy incentives subsidize closed-loop collection from dismantling yards.
- Construction applications:Recycled polyethylene is displacing virgin resin in drainage pipes and geomembranes. German infrastructure stimulus packages specify minimum recycled content for public tenders.
- Chemical-mechanical hybrid processing:Partial depolymerization of contaminated feedstocks extends mechanical recycling yield. Dutch processors are piloting this convergence for multilayer film waste.
Industry Challenges
- Sortation technology bottlenecks:Near-infrared and robotics-based separation of multiresin streams requires specialized maintenance technicians. Training pipelines lag installation schedules.
- Certification timeline compression:EFSA and FDA food-contact approvals demand 18-24 month migration testing cycles. Brand owners accelerate sourcing decisions before dossier completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Post-Consumer Recycled Plastics Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polyvinyl Chloride, Polypropylene, Polystyrene Application: Packaging, Construction Materials, Automotive Components, Textiles, Consumer Goods End User: Manufacturers, Fabricators, Molders, Assemblers, Distributors Processing Technology: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Solvent-Based Recycling, Energy Recovery |
| Companies Covered | BASF SE, Veolia, SABIC, Suez SA, Evonik Industries AG, Republic Services, WM Intellectual Property Holdings, L.L.C., Remondis SE & Co. KG, LyondellBasell Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Post-Consumer Recycled Plastics Market Shifts & Advancements
Digital traceability infrastructure and molecular recycling advances are redefining quality assurance boundaries for post-consumer resins. These shifts are compressing the premium between mechanical and chemical outputs.
Enzymatic depolymerization is absorbing contaminated PET waste streams that mechanical processes reject. French packaging converters are trialing these biocatalytic routes for colored and opaque bottle flakes. The technology is absorbing volume from pyrolysis units where energy costs erode margins.
REACH framework amendments are tightening hazardous additive carryover limits for recycled polymers. ECHA screening protocols now flag legacy flame retardants and plasticizers in construction-grade regrinds. Compounders in Belgium and Italy are investing in super-cleaning extrusion lines to maintain market access.
Brand-led procurement coalitions are consolidating demand for certified circular resins. European beverage bottlers now specify ISCC PLUS chain-of-custody documentation for food-contact applications. This behavioral pivot concentrates volume with processors who have integrated collection-sorting-reprocessing assets under single ownership.
Global Post-Consumer Recycled Plastics Market Segmentation
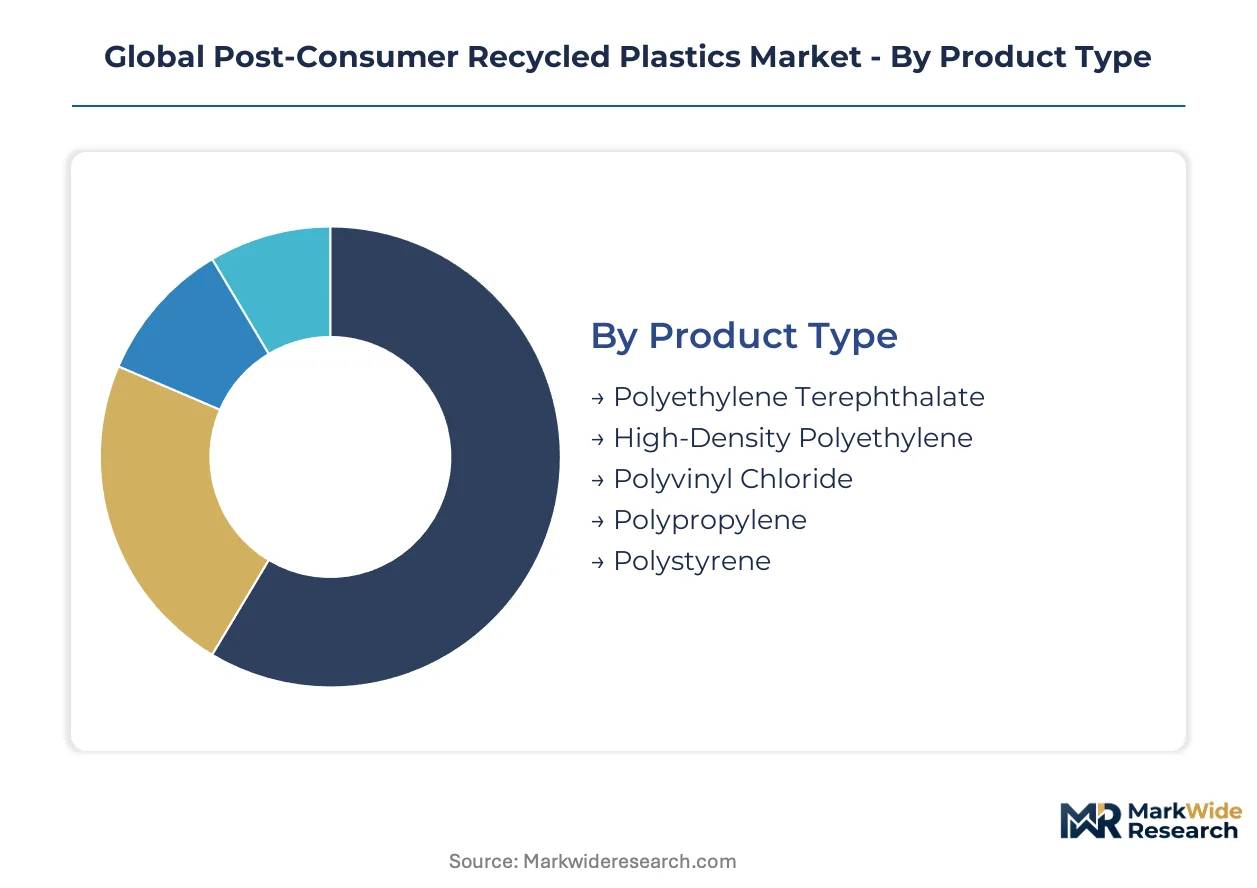
Segmentation in post-consumer recycled plastics reveals where capital requirements and technical barriers concentrate competitive advantage. Each dimension—resin chemistry, downstream application, customer type, and reprocessing method—carries distinct margin profiles and regulatory exposure that shape procurement decisions.
Product Type:
Capital intensity varies sharply across polymer recovery chains, with food-contact purification and high-heat stabilization demanding specialized extrusion and super-cleaning investments.
- Polyethylene Terephthalate:Flake washing and solid-state polymerization restore intrinsic viscosity to 0.72-0.82 dL/g for bottle-grade compliance. European beverage converters in Germany and France are expanding pelletization capacity to meet EU Green Deal recycled content thresholds.
- Polypropylene:Heat-stabilized grades require additive packages to maintain dimensional stability above 120°C. Automotive molding clusters in Baden-Württemberg specify these grades for HVAC housings and under-hood components.
- High-Density Polyethylene:Drainage pipe and geomembrane applications tolerate broader melt flow variance. German infrastructure tenders specify minimum recycled content for public procurement.
- Polyvinyl Chloride:Legacy plasticizer screening under REACH amendments complicates construction-grade regrind certification. Belgian compounders invest in super-cleaning lines to maintain market access.
- Polystyrene:Contaminated foam and food-service waste streams face limited mechanical recycling economics. Pyrolysis units in Rotterdam recover styrene monomer for re-polymerization.
Most installed capacity flows through Polyethylene Terephthalate. Expansion is steepest in Polypropylene.
Application:
Application mix determines certification burden intensity, with food-contact and automotive safety applications imposing the steepest compliance costs.
- Packaging:EFSA and FDA food-contact approvals demand 18-24 month migration testing cycles. Brand owners accelerate sourcing decisions before dossier completion, concentrating volume with ISCC PLUS-certified processors.
- Automotive Components:OEM qualification protocols for interior and under-hood applications require heat-aging and emissions testing. Japanese OEMs are qualifying recycled polypropylene for door panels and seat backs.
- Construction Materials:REACH hazardous additive carryover limits tighten for recycled polymers in building applications. German stimulus packages specify minimum recycled content for drainage pipes and geomembranes.
- Textiles:Fiber-grade recycled PET requires controlled IV reduction for spun yarn tenacity. French converters trial enzymatic depolymerization for colored and opaque bottle flakes.
- Consumer Goods:Non-food contact applications face lower regulatory barriers but price-sensitive demand. Durable goods molders prioritize cost over certified circular documentation.
Packaging commands the largest revenue pool. Automotive Components are climbing the fastest as lightweighting mandates accelerate resin substitution.
End User:
End user category shapes technical service requirements and contract structure, with integrated manufacturers capturing margin through captive recycling operations.
- Manufacturers:Brand-owning producers with internal sustainability targets drive certified circular resin demand. Beverage bottlers specify chain-of-custody documentation for ESG reporting compliance.
- Fabricators:Sheet and profile extruders serving construction and industrial applications prioritize volume scale over certification tier. Price sensitivity concentrates procurement with mechanical recyclers.
- Molders:Injection and blow molders face requalification costs when switching from virgin to recycled feedstocks. Bavarian converters expand pelletization capacity to secure supply continuity.
- Assemblers:Tier suppliers to automotive and electronics OEMs manage multi-resin specifications. REACH screening protocols flag legacy additives in incoming regrinds.
- Distributors:Merchant resin traders arbitrage price volatility between virgin and recycled parity. Baled PET flake prices swing with crude oil correlation and seasonal collection volumes.
Manufacturers absorb the highest volume share. Molders are gaining share fastest as converters internalize reprocessing capabilities.
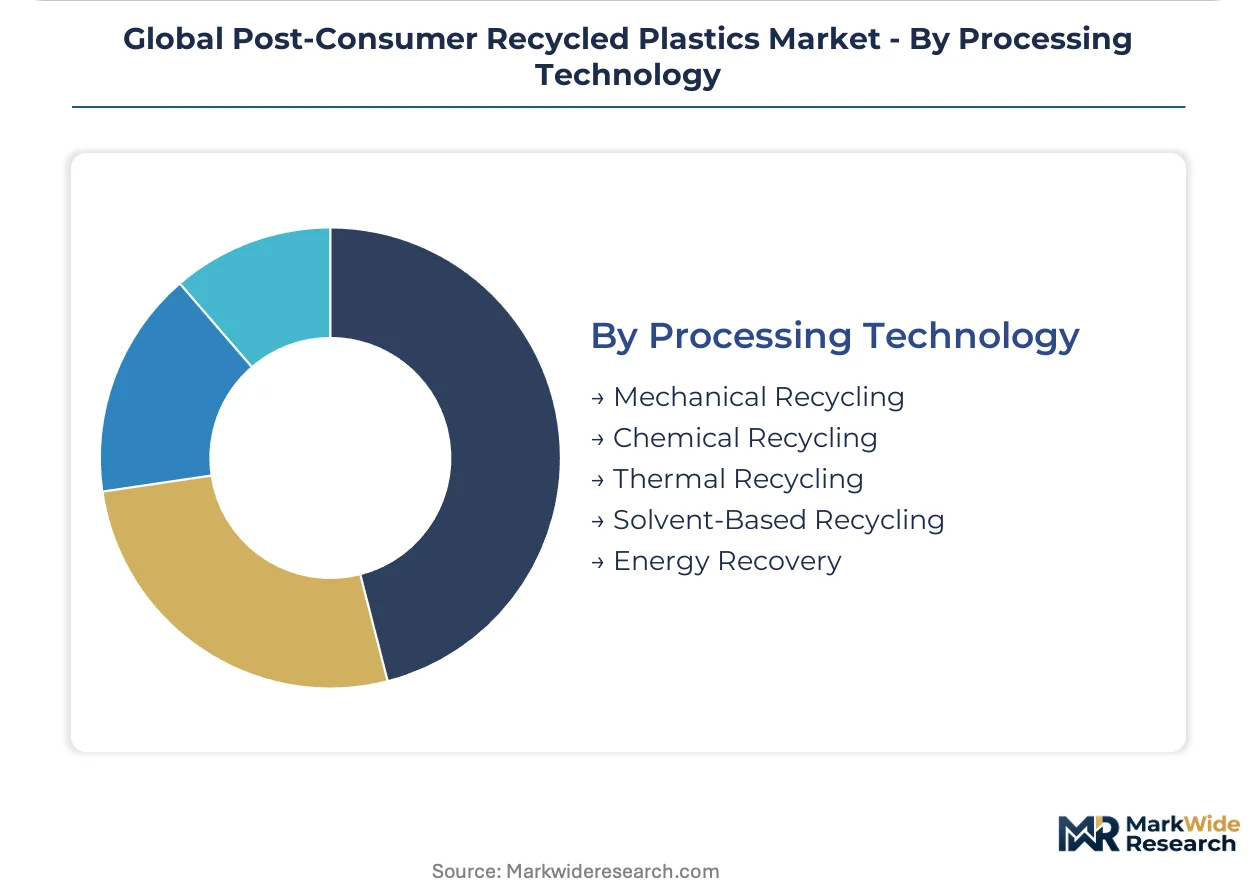
Processing Technology:
Technology selection determines yield, quality ceiling, and energy intensity, with hybrid approaches emerging to optimize economics across feedstock quality tiers.
- Mechanical Recycling:Extrusion and pelletization of monostream feedstocks retains margin leadership for clear PET and natural HDPE. Each reprocessing cycle degrades intrinsic viscosity below bottle-grade thresholds.
- Chemical Recycling:Pyrolysis and depolymerization achieve virgin-equivalent melt flow indices from mixed or degraded waste. Units in Rotterdam and Antwerp recover polymers that mechanical processes reject.
- Thermal Recycling:Combustion with energy recovery serves as backstop for non-recyclable fractions. Incineration gate fees compete with landfill economics in regions with weak extended producer responsibility enforcement.
- Solvent-Based Recycling:Selective dissolution separates target polymers from multilayer and contaminated streams. Dutch processors pilot this convergence for multilayer film waste.
- Energy Recovery:Waste-to-fuel applications face regulatory pressure under EU circular economy hierarchy. Cement kilns substitute solid recovered fuel for coal in clinker production.
Mechanical Recycling holds the dominant capacity base. Chemical Recycling is expanding most quickly as pyrolysis economics improve with scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavarian molding clusters anchor European mechanical recycling capacity. German converters are expanding pelletization infrastructure to meet EU Green Deal compliance deadlines. Chemical recycling investments concentrate in Rotterdam and Antwerp.
Germany
Automotive lightweighting specifications from Baden-Württemberg OEMs pull heat-stabilized recycled polypropylene into HVAC housings. REACH amendments tighten hazardous additive screening for construction-grade regrinds. Bavarian converters internalize flake washing and solid-state polymerization to secure food-grade rPET supply chains.
Netherlands
Rotterdam-Antwerp chemical recycling corridors recover degraded polymers from mixed waste streams through pyrolysis and depolymerization. ECHA screening protocols flag legacy plasticizers in incoming regrinds. Dutch processors pilot solvent-based separation for multilayer film waste that mechanical routes reject.
United States
FDA food-contact approval timelines for recycled plastics lag EU EFSA equivalency pathways by 12-18 months. Republic Services and WM Intellectual Property Holdings control municipal collection infrastructure across Sun Belt population centers. Export processors face dual certification burdens when supplying European beverage bottlers.
Japan
METI circular economy incentives subsidize closed-loop collection from automotive dismantling yards. Japanese OEMs are qualifying recycled polypropylene for door panels and seat backs. Kansai molding clusters specify heat-stabilized grades for interior trim applications.
France
Enzymatic depolymerization trials for colored and opaque PET bottle flakes are absorbing volume from energy-intensive pyrolysis routes. EFSA migration testing cycles compress procurement timelines for food-contact applications. French packaging converters prioritize ISCC PLUS chain-of-custody documentation for ESG reporting compliance.
Global Post-Consumer Recycled Plastics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chemical recycling scale-up and digital traceability integration. The vendor base stratifies across integrated waste management conglomerates, petrochemical incumbents with molecular recycling capabilities, and specialized mechanical recyclers. Three archetypes dominate: municipal collection operators extending into reprocessing, petrochemical majors licensing depolymerization technology, and regional compounders with super-cleaning extrusion assets. Competitive moves concentrate on backward integration into collection-sorting infrastructure and ISCC PLUS certification acquisition.
Among European waste management operators, Veolia and Suez SA exemplify the integrated archetype spanning municipal collection through mechanical recycling. LyondellBasell Industries N.V. occupies a position within the petrochemical tier with proprietary molecular recycling technology. SABIC represents the certified circular polymer segment through mixed plastic waste stream recovery. BASF SE and Evonik Industries AG sit within the specialty chemicals tier supplying additive packages for heat stabilization and super-cleaning processes.
| Leading Market Players |
|---|
| BASF SE |
| Veolia |
| SABIC |
| Suez SA |
| Evonik Industries AG |
| Republic Services |
| WM Intellectual Property Holdings, L.L.C. |
| Remondis SE & Co. KG |
| LyondellBasell Industries N.V. |
| Others |
Supply & Pricing Matrix
EU Green Deal recycled content mandates gate qualified supply and premium-tier pricing access for food-contact rPET, forcing converters to absorb certification costs or exit beverage packaging tiers entirely. Mechanical recyclers in Bavaria and Baden-Württemberg command price premiums through integrated flake-to-pellet operations that chemical recycling challengers struggle to undercut at current pyrolysis scale.
Pricing Analysis
Input-cost pass-through from baled PET flake volatility shapes contract structures, with crude oil parity and seasonal collection swings transmitted directly to converters. Three-tier pricing structure across ISCC PLUS-certified premium, standard food-grade, and non-certified economy levels separates beverage bottlers from construction molders and industrial fabricators. Pricing pressure stems from chemical recycling scale-up in Rotterdam and Antwerp as pyrolysis units achieve virgin-equivalent quality. Brand-owning manufacturers exhibit lowest price sensitivity due to ESG reporting requirements, while merchant distributors arbitrage spot-market swings most aggressively.
Supply Chain Analysis
Workforce availability constraints in German and Dutch chemical recycling corridors limit pyrolysis unit commissioning schedules despite capital deployment. Supply concentrates in Germany, the Netherlands, and Belgium, with feedstock drawing from municipal collection networks across Southern and Western Europe. Raw material dependencies center on post-consumer PET bottle bales, mixed plastic waste streams, and pyrolysis oil intermediates. Single-source vulnerability runs through Rotterdam-Antwerp chemical recycling infrastructure for virgin-equivalent outputs. Distribution runs through integrated waste management conglomerates extending from collection into reprocessing, with merchant resin traders filling spot-market gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where food-contact certification and automotive heat-stabilization specifications concentrate margin with integrated processors. Demand is shifting toward premium ISCC PLUS-certified tiers as brand owners internalize chain-of-custody documentation for ESG compliance.
For Market Incumbents: Hedge chemical recycling exposure by maintaining mechanical recycling yield leadership for clear monostream feedstocks while piloting hybrid depolymerization for contaminated streams. Expand pelletization capacity in Bavaria to capture EU Green Deal compliance-driven volume before pyrolysis economics improve. Defend margin position through backward integration into municipal collection infrastructure rather than technology licensing. For New Entrants and Emerging Players: Begin with automotive under-hood polypropylene applications in Baden-Württemberg clusters where heat-stabilization specifications create technical barriers to incumbent replication. Target Japanese OEM qualification programs subsidized by METI circular economy incentives as the most penetrable geography. Pursue toll-processing arrangements with established compounders to bypass 18-24 month EFSA migration testing cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional mechanical recyclers with super-cleaning extrusion assets because certification timeline compression concentrates volume with processors who own integrated collection-sorting-reprocessing chains. Five-to-ten year viability hinges on chemical recycling scale-up economics remaining above mechanical reprocessing yields for clear feedstocks. Watch enzymatic depolymerization pilot results in France as signal for pyrolysis displacement risk in colored and opaque PET segments.| Strategic Initiative | Industry Significance |
|---|---|
| ISCC PLUS Certification Acquisition | European beverage bottlers now mandate chain-of-custody documentation for ESG reporting compliance. |
| Backward Integration into Collection | Veolia and Suez SA anchor municipal infrastructure that secures monostream feedstock access. |
| Chemical Recycling Scale-Up | Pyrolysis units in Rotterdam achieve virgin-equivalent melt flow indices for sensitive automotive applications. |
| Hybrid Processing Pilot Programs | Dutch processors trial solvent-based separation for multilayer film waste that mechanical routes reject. |
| Automotive Lightweighting Partnerships | Baden-Württemberg OEMs specify heat-stabilized rPP for HVAC housings and under-hood components. |
Research Methodology
Coverage spans Western Europe, North America, and East Asia, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged plant managers at mechanical recycling facilities, procurement leads at beverage converters, technical R&D directors at chemical recycling ventures, and distribution channel partners in resin trading. Secondary sources included EFSA migration testing protocols, FDA food-contact guidance documents, EU Green Deal implementation texts, customs and trade data from Eurostat and UN Comtrade, and SEC 10-K filings from petrochemical majors. Bottom-up capacity modeling triangulated against top-down demand projections across resin chemistry and application segments.
Granularity-level modeling distinguished food-contact from non-food-contact grades, automotive safety-critical from interior trim applications, and mechanical versus chemical reprocessing pathways. Segmentation dimensions included polymer chemistry, downstream application, end-user category, and processing technology tier. CAGRs derived from installed capacity expansion schedules, regulatory compliance deadline clustering, and substitution elasticity estimates for virgin resin displacement. Industry-specific inputs incorporated pyrolysis unit commissioning timelines, enzymatic depolymerization pilot scale-up trajectories, and OEM qualification protocol durations.
Several conditions sit outside the modeled scope, including abrupt feedstock cost shocks from crude oil volatility, unanticipated REACH amendment stringency, and breakthrough enzymatic depolymerization scale-up that displaces pyrolysis economics. Forecasts reflect assumptions about regulatory timeline adherence, technology cost curves, and brand owner procurement coalition stability. Material deviation in chemical recycling yield improvements, EFSA/FDA approval acceleration, or municipal collection infrastructure privatization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Graphite Recycling Market