
 US Commercial Restoration Waterproofing Membranes Market | 2026-2036
US Commercial Restoration Waterproofing Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Restoration Waterproofing Membranes Market Intelligence
ASTM D6134 qualification for self-adhering sheet systems is collapsing the vendor pool to firms with certified in-house polymer compounding. Sika AG leverages its captive styrene-butadiene-styrene supply chain to sustain batch consistency across regional distribution hubs. Carlisle Companies anchors its position through backward integration into EPDM and TPO sheet manufacturing. Johns Manville competes on mineral wool-adjacent channel relationships that extend into commercial roofing specification.
US commercial restoration waterproofing membranes are synthetic or bituminous barriers, typically 40–120 mils thick, engineered to block liquid water transmission while accommodating substrate movement through elastomeric recovery. These systems restore failed envelopes on existing structures where full demolition proves economically unfeasible. Liquid-applied membranes now lead value contribution because applicators price complex detailing at premium labor rates, while sheet membrane volumes dominate square-footage throughput in warehouse and big-box retrofit programs. Mechanically fastened installation retains share in hurricane-prone zones where uplift resistance codes exceed adhered-system capacity.
OSHA fall-protection standards for roofing work, EPA stormwater discharge permits under the NPDES framework, and ASCE 7 wind-load provisions collectively shape product selection, contractor licensing, and project scheduling across US jurisdictions. Local building departments in Florida and Texas now require Miami-Dade County or Texas Department of Insurance product approval for membrane overlays on public facilities. Stakeholders must monitor how state-level adoption of International Energy Conservation Code stretch provisions will redefine thermal-barrier integration requirements for restoration assemblies.
Market Dynamics
ASTM D6134 certification requirements are compressing the qualified supplier base, forcing commercial restoration contractors to consolidate procurement around polymer-compounding specialists with captive SBS supply chains.
Growth Catalysts
- LEED v4.1 Material Transparency:Building owners pursuing green certification must document chemical inventories, pulling specification toward manufacturers with Environmental Product Declarations already on file.
- Sun Belt Thermal Cycling:Accelerated membrane degradation across Florida, Texas, and Arizona is collapsing replacement cycles from twenty-year intervals to twelve-year intervals.
- EPA NPDES Stormwater Enforcement:Municipal discharge permit violations are triggering mandatory envelope remediation on commercial properties exceeding impervious surface thresholds.
Market Restraints
- Petrochemical Feedstock Volatility:Styrene-butadiene-styrene block copolymer prices track benzene and butadiene futures, compressing blended margin on self-adhering sheet systems.
- Single-Source Polymer Dependency:Three domestic compounders control certified SBS supply for ASTM D6134-qualified membranes, creating concentration risk in the Gulf Coast petrochemical corridor.
- Adhered-System Wind Uplift Limits:Miami-Dade County product approval standards exclude fully adhered membranes from high-velocity hurricane zone overlays above 120 feet.
Strategic Opportunities
- Below-Grade Restoration in Coastal Cities:Saltwater intrusion damage in Miami, New Orleans, and Charleston is opening specification for crystalline admixture-compatible membrane systems.
- OSHA Fall-Protection Compliance Services:Contractors bundling membrane installation with certified anchor-point engineering capture premium pricing on high-slope restoration projects.
- Integrated Air-Barrier Assemblies:IECC stretch code adoption in Massachusetts and Washington is merging vapor control with waterproofing specification on deep energy retrofits.
Industry Challenges
- Certified Applicator Shortage:Manufacturer-trained crews for hot-fluid-applied rubberized asphalt are concentrated in six metropolitan markets, extending project lead times in secondary cities.
- Legacy Substrate Compatibility:Coal-tar pitch and asbestos-containing built-up roofing beneath existing membranes require hazardous abatement sequencing that disrupts restoration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Restoration Waterproofing Membranes Market |
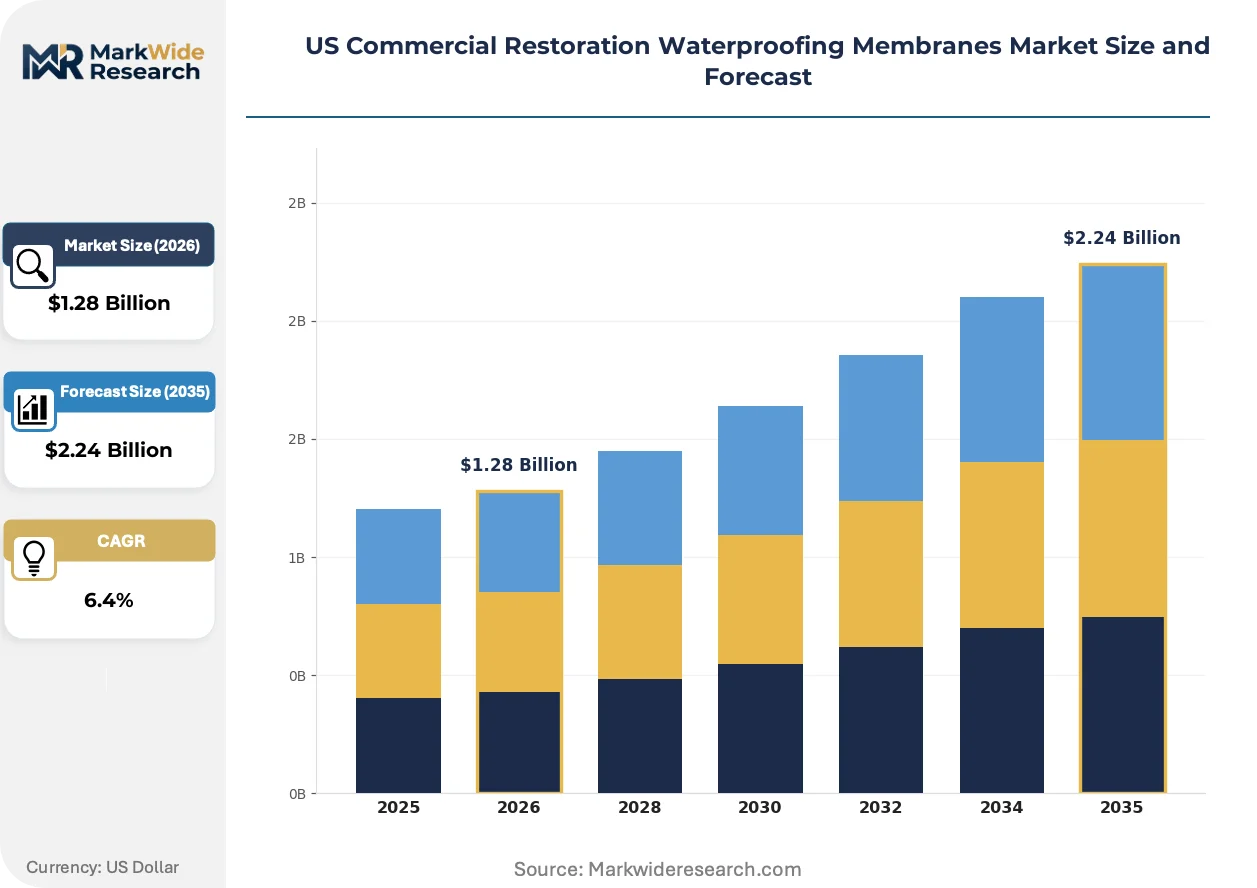
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Membranes, Liquid Membranes, Spray-Applied Membranes, Self-Adhering Membranes Installation Method: Adhered, Mechanically Fastened, Liquid Applied, Hybrid Systems End User: Commercial Buildings, Industrial Facilities, Warehouses, Shopping Malls Performance Feature: Durability, UV Resistance, Flexibility, Water Resistance |
| Companies Covered | Sika AG, BASF SE, Kemper System America, Inc., GAF Materials Corporation, Johns Manville, Tremco Incorporated, Carlisle Companies, Soprema, DuPont de Nemours, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Restoration Waterproofing Membranes Market Strategic Shifts & Innovations
Product differentiation is migrating from chemistry to installation-system integration, with manufacturers competing on applicator training depth and digital substrate assessment tools rather than membrane formulation alone.
Self-healing polymer technology is fragmenting the repair-service revenue model. Microcapsule-embedded TPO membranes release elastomeric sealant when punctured, reducing callback frequency for facility managers. Big-box retailers and distribution centers are specifying these systems on high-traffic roof sections. The technology is fragmenting aftermarket maintenance contracts into performance-guarantee structures that shift risk to membrane producers.
OSHA's updated fall-protection standards for low-slope roofing are tightening contractor licensing requirements. Jurisdictions now mandate Competent Person certification for projects above six feet, filtering out casual installers. Commercial property insurers in Texas and Florida are requiring documented compliance before binding coverage on membrane restoration work.
Building engineers are consolidating specification authority through owner-direct procurement. Facility managers at hospital and university portfolios are bypassing general contractors to negotiate directly with Sika AG and Carlisle Companies for multi-site maintenance agreements. This pattern concentrates most visibly in the Northeast corridor where institutional asset density supports dedicated capital planning staff.
US Commercial Restoration Waterproofing Membranes Market Segmentation
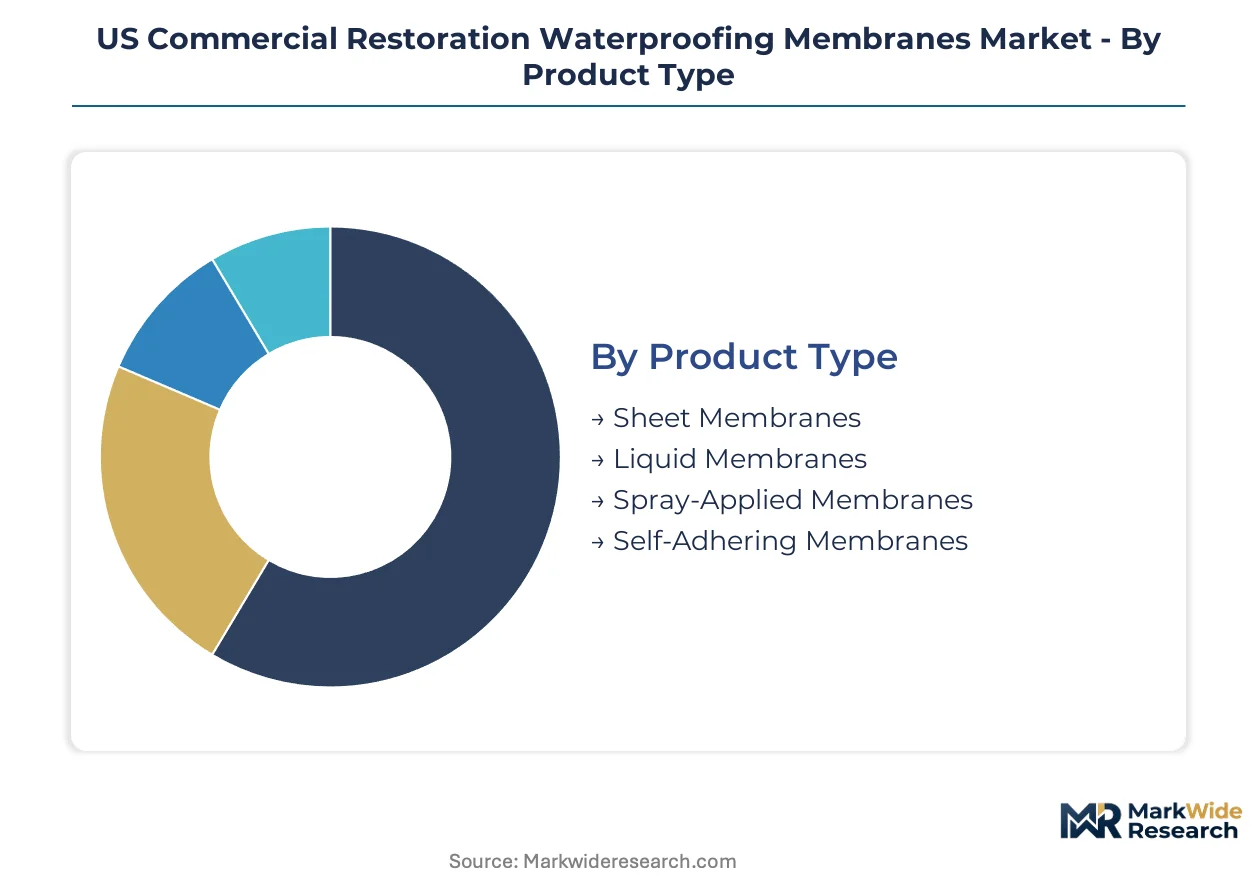
Channel strategy in US commercial restoration waterproofing membranes hinges on matching product form to contractor capability and project urgency. Specification engineers route high-complexity detailing through liquid-applied specialists, while volume-driven warehouse retrofits flow through sheet membrane distribution networks. Understanding these segment-to-channel dynamics enables manufacturers to optimize margin capture across project types.
Product Type:
Sheet membranes dominate distribution center and big-box retail channels where standardized SKUs support rapid fulfillment. Liquid-applied systems concentrate in specification-driven markets where applicators command premium labor pricing for complex geometries.
- Liquid Membranes:Cold-applied elastomeric formulations cure to seamless monolithic barriers accommodating irregular substrates. Demand clusters in hospital and university restoration projects across the Northeast corridor where detailing complexity around HVAC penetrations and expansion joints exceeds sheet membrane capability. LEED v4.1 material transparency documentation pulls specification toward manufacturers with verified Environmental Product Declarations.
- Sheet Membranes:Factory-controlled thickness TPO and EPDM rolls deliver consistent performance in high-throughput warehouse retrofit programs. Sun Belt thermal cycling accelerates replacement schedules in Florida, Texas, and Arizona distribution centers where 12-year intervals now replace traditional 20-year cycles. ASTM D6134 qualification requirements compress qualified supply to polymer-compounding specialists with captive SBS supply chains.
- Spray-Applied Membranes:Rapid-build polyurethane and polyurea systems serve industrial facilities requiring minimal downtime during envelope restoration.
- Self-Adhering Membranes:Pre-applied adhesive layers reduce field labor and eliminate torch hazards in occupied building retrofits.
By volume, Sheet Membranes leads. By growth pace, Liquid Membranes is ahead.
Installation Method:
Cost tier stratification separates premium adhered systems from economy mechanically fastened alternatives, with hybrid approaches capturing mid-market specification.
- Mechanically Fastened:Barbed plates and seam welding secure membranes through wind uplift resistance exceeding adhered-system capacity. Miami-Dade County product approval standards mandate this method for hurricane zone overlays above 120 feet on Florida public facilities.
- Adhered:Full-surface bonding eliminates fastener penetrations and delivers smooth aesthetic finishes valued in high-visibility commercial architecture. Premium positioning reflects specialized crew training and extended installation timelines.
- Liquid Applied:Roller or spray deployment suits complex detailing where sheet seams create failure risk.
- Hybrid Systems:Strategic combination of mechanical fastening in field areas with adhered perimeters and penetrations balances cost and performance.
Mechanically Fastened commands the largest installed base. Adhered systems are expanding most quickly in institutional specification.
End User:
Application urgency varies sharply across end-use segments, with industrial facilities demanding rapid turnaround and commercial buildings accepting phased restoration schedules.
- Warehouses:Big-box retail and distribution center portfolios drive square-footage throughput with standardized membrane specifications and repetitive detailing. OSHA fall-protection compliance bundling creates premium pricing opportunities on high-slope restoration projects.
- Commercial Buildings:Office and mixed-use properties in urban centers accelerate replacement schedules as aging infrastructure exceeds design life. EPA NPDES stormwater enforcement triggers mandatory envelope remediation where impervious surface thresholds are exceeded.
- Industrial Facilities:Manufacturing plants prioritize chemical resistance and rapid cure times to minimize production disruption.
- Shopping Malls:Retail property managers balance tenant continuity requirements with envelope performance during restoration planning.
Warehouses dominates membrane volume. Commercial Buildings shows the steepest expansion trajectory as urban infrastructure ages.
Performance Feature:
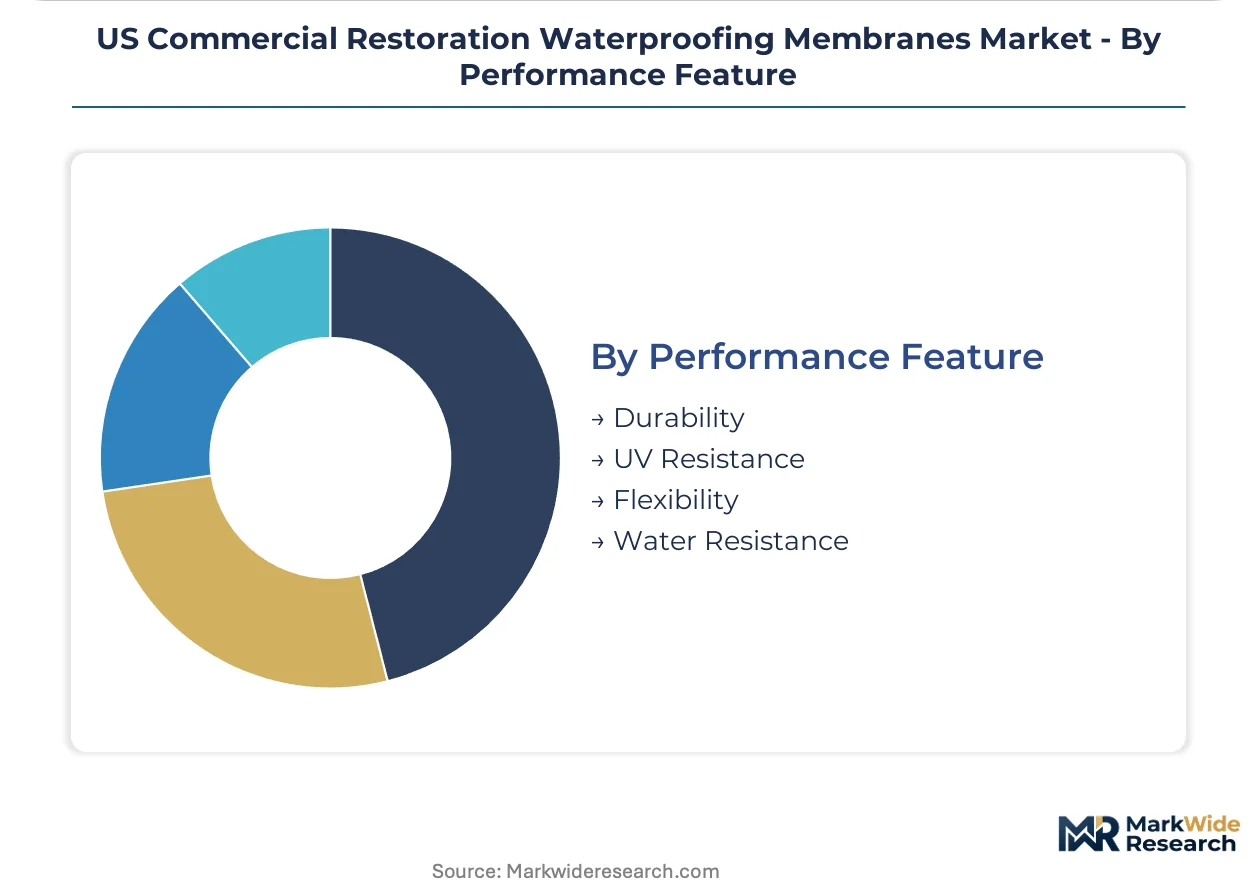
Customer type differentiation separates specification engineers prioritizing durability from facility managers emphasizing installation speed and callback reduction.
- Durability:Elongation recovery and puncture resistance metrics determine membrane selection for high-traffic roof sections. Self-healing polymer technology with microcapsule-embedded TPO reduces maintenance contract frequency for big-box retailers.
- UV Resistance:Stabilized formulations prevent embrittlement in exposed roofing applications across Sun Belt states where thermal cycling stress concentrates.
- Flexibility:Low-temperature bend properties accommodate structural movement in freeze-thaw climates.
- Water Resistance:Hydrostatic head ratings and permeance values define below-grade restoration suitability in coastal cities facing saltwater intrusion.
Durability leads specification priority. UV Resistance is gaining share fastest as Sun Belt replacement cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital and university facility managers in the Northeast corridor negotiate directly with membrane manufacturers for multi-site maintenance agreements, bypassing general contractors to consolidate specification authority. Sun Belt distribution center portfolios drive volume throughput with compressed replacement cycles, while coastal cities face saltwater intrusion remediation mandates.
Northeast Corridor
Institutional asset density supports dedicated capital planning staff at hospital and university portfolios. Massachusetts stretch code adoption under IECC merges vapor control with waterproofing specification on deep energy retrofits. Greater Boston and New York Metro concentrate owner-direct procurement negotiations with polymer-compounding specialists.
Southeast
Florida thermal cycling stress degrades roofing systems fastest, collapsing replacement intervals from twenty years to twelve years. Miami-Dade County product approval standards mandate mechanically fastened installation for hurricane zone overlays above 120 feet. Charleston faces saltwater intrusion damage opening specification for crystalline admixture-compatible membrane systems.
Southwest
Texas distribution centers and big-box retail drive square-footage throughput with standardized membrane specifications. Texas Department of Insurance product approval requirements filter qualified membranes for public facility overlays. Dallas-Fort Worth and Houston metro areas concentrate OSHA fall-protection compliance bundling on high-slope restoration projects.
West Coast
California commercial building owners accelerate envelope remediation as aging infrastructure exceeds design life. EPA NPDES stormwater discharge permits trigger mandatory restoration where impervious surface thresholds are exceeded. Los Angeles and San Francisco Bay Area facility managers prioritize LEED v4.1 material transparency documentation.
Mountain West
Arizona thermal cycling parallels Florida in accelerating membrane degradation across exposed roofing applications. Phoenix and Tucson distribution centers specify UV-stabilized formulations to prevent embrittlement in extreme solar exposure. Certified applicator shortages extend project lead times in these secondary markets.
US Commercial Restoration Waterproofing Membranes Market Key Industry Players
Player mix skews toward polymer-compounding specialists with captive SBS supply chains and sheet membrane fabricators with backward integration into EPDM and TPO manufacturing. Market structure concentrates around three domestic compounders controlling certified supply for ASTM D6134-qualified membranes. Dominant competitive moves include strategic consolidation around qualified supply chains and vertical integration into raw material production to defend margin positions against petrochemical feedstock volatility.
Among Swiss and German-based chemical conglomerates, Sika AG and BASF SE exemplify the polymer-compounding specialist archetype with captive styrene-butadiene-styrene supply chains sustaining batch consistency. Carlisle Companies and Johns Manville occupy positions within the integrated sheet membrane fabricator tier, leveraging in-house EPDM and TPO production alongside mineral wool-adjacent channel relationships. Tremco Incorporated and GAF Materials Corporation represent the commercial roofing specification anchor archetype, competing on applicator training depth and regional distribution hub coverage.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Kemper System America, Inc. |
| GAF Materials Corporation |
| Johns Manville |
| Tremco Incorporated |
| Carlisle Companies |
| Soprema |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between membrane fabricators and Gulf Coast SBS compounders lock in both polymer supply security and price visibility against benzene futures volatility. These contracts insulate qualified ASTM D6134 suppliers from spot market swings while forcing non-integrated contractors to absorb margin compression.
Pricing Analysis
Cost-plus contracts with benzene indexation dominate procurement between membrane manufacturers and SBS suppliers. Three-tier pricing structure across premium, standard, and economy levels separates certified polymer-compounding specialists from regional sheet distributors and commodity bitumen resellers. Cost compression in standard-grade TPO runs through single-source polymer dependency as three domestic compounders control qualified supply. Warehouse portfolio managers show highest price sensitivity, while hospital facility directors prioritize certified installation bundling over unit cost.
Supply Chain Analysis
Gulf Coast petrochemical corridor concentration underwrites domestic SBS block copolymer availability for self-adhering membrane production. Manufacturing draws from Texas and Louisiana ethylene crackers, Kentucky butadiene extraction, and Illinois styrene production. Single-source vulnerability concentrates in certified polymer compounders with ASTM D6134 qualification. Distribution runs through manufacturer-direct regional hubs serving commercial roofing contractors, bypassing traditional distribution for institutional owner-direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EPA NPDES enforcement fragments demand across municipal discharge compliance timelines, creating project-based niches for specialized applicators. Building envelope remediation urgency varies by violation schedule, enabling targeted service positioning.
For Market Incumbents: Consolidate certified applicator networks through exclusive training partnerships to lock out non-qualified competitors. Backward integration into EPDM sheet manufacturing defends margin positions against petrochemical feedstock volatility threatening blended product lines. For New Entrants and Emerging Players: OSHA fall-protection compliance bundling gaps in secondary Sun Belt markets offer service-layer entry points. Target Arizona and Mountain West distribution centers where certified crew shortages extend project lead times, enabling premium positioning on rapid-turnaround restoration. For Investors and Strategic Acquirers: Regional polymer-compounding specialists with captive SBS supply chains present acquisition targets with durable competitive moats. Watch ASTM D6134 certification expansion timelines as inflection indicators for supply base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive SBS supply secures ASTM D6134 qualification against Gulf Coast concentration risk. |
| Certified Applicator Training Expansion | OSHA Competent Person credentialing filters casual installers and binds contractor loyalty. |
| Environmental Product Declaration Filing | LEED v4.1 material transparency documentation pulls specification from competing manufacturers. |
| Regional Distribution Hub Establishment | Proximity to Sun Belt thermal cycling hotspots compresses replacement cycle capture. |
| Self-Healing Polymer Technology Licensing | Microcapsule-embedded TPO shifts aftermarket maintenance risk to membrane producers. |
Research Approach
A spread of perspectives from membrane manufacturing executives, commercial roofing contractors, hospital facility managers, and EPA regional enforcement officers converged on the working assumptions driving demand quantification. Primary fieldwork combined structured interviews with specification engineers and restoration project managers, validated against secondary sources including ASTM technical committee proceedings, Miami-Dade County product approval databases, and SEC 10-K disclosures from publicly traded building materials firms. Bottom-up project pipeline tracking across metropolitan statistical areas triangulated with top-down construction spending forecasts.
Segmentation dimensions modeled include product form, installation method complexity, end-use asset type, and regional regulatory stringency tier across the projection horizon. CAGRs derive from replacement cycle compression rates in thermal stress zones and enforcement-driven remediation mandates. Industry-specific inputs encompass benzene futures correlation coefficients, certified applicator density by metropolitan market, and LEED v4.1 adoption velocity in institutional portfolios.
Underlying assumptions cover stable EPA NPDES enforcement intensity and continued Sun Belt population migration, with deviation risk concentrated in petrochemical feedstock price spikes and state-level building code adoption delays. Practitioners should keep alternative scenarios live as IECC stretch code expansion timelines and OSHA fall-protection jurisdictional harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Nafion Market
Membrane Materials
Reverse Osmosis Films Market