
 Polypropylene and High-Impact Polystyrene Market | 2026-2036
Polypropylene and High-Impact Polystyrene Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene and High-Impact Polystyrene Market Analytics
Modular packaging configurations is shifting procurement patterns across the consumer goods and electronics sectors. LG Chem Ltd. leverages its integrated petrochemical complexes to sustain cost-competitive resin supply. Braskem anchors its position through bio-based polypropylene development. INEOS Styrolution Group GmbH specializes in high-purity styrenics for medical and food-contact applications.
Polypropylene and high-impact polystyrene constitute thermoplastic resins synthesized through Ziegler-Natta or metallocene catalysis and free-radical polymerization respectively, with melt flow indices spanning 0.3 to 100 g/10 min and Izod impact strengths of 10 to 25 kJ/m² for toughened grades. These materials serve as structural and barrier layers across automotive interior panels, appliance housings, and flexible food packaging. Injection molding applications dominate volume throughput due to cycle-time efficiency in mass production of complex geometries. Copolymer grades capture expanding share in blow-molded automotive ducts and living-hinge packaging where ethylene incorporation enhances flexibility.
The EPA oversees volatile organic compound emissions from resin production facilities under the Clean Air Act while REACH restricts phthalate-based plasticizers and persistent organic pollutants in European compound formulations. China's MEE enforces dual carbon intensity caps on naphtha crackers and polyolefin units. FDA food-contact notifications and EU 10/2011 migration limits dictate additive package selections for direct-contact packaging applications. Stakeholders must monitor evolving extended producer responsibility schemes and mechanical recycling certification standards to secure offtake agreements with brand-owner sustainability commitments.
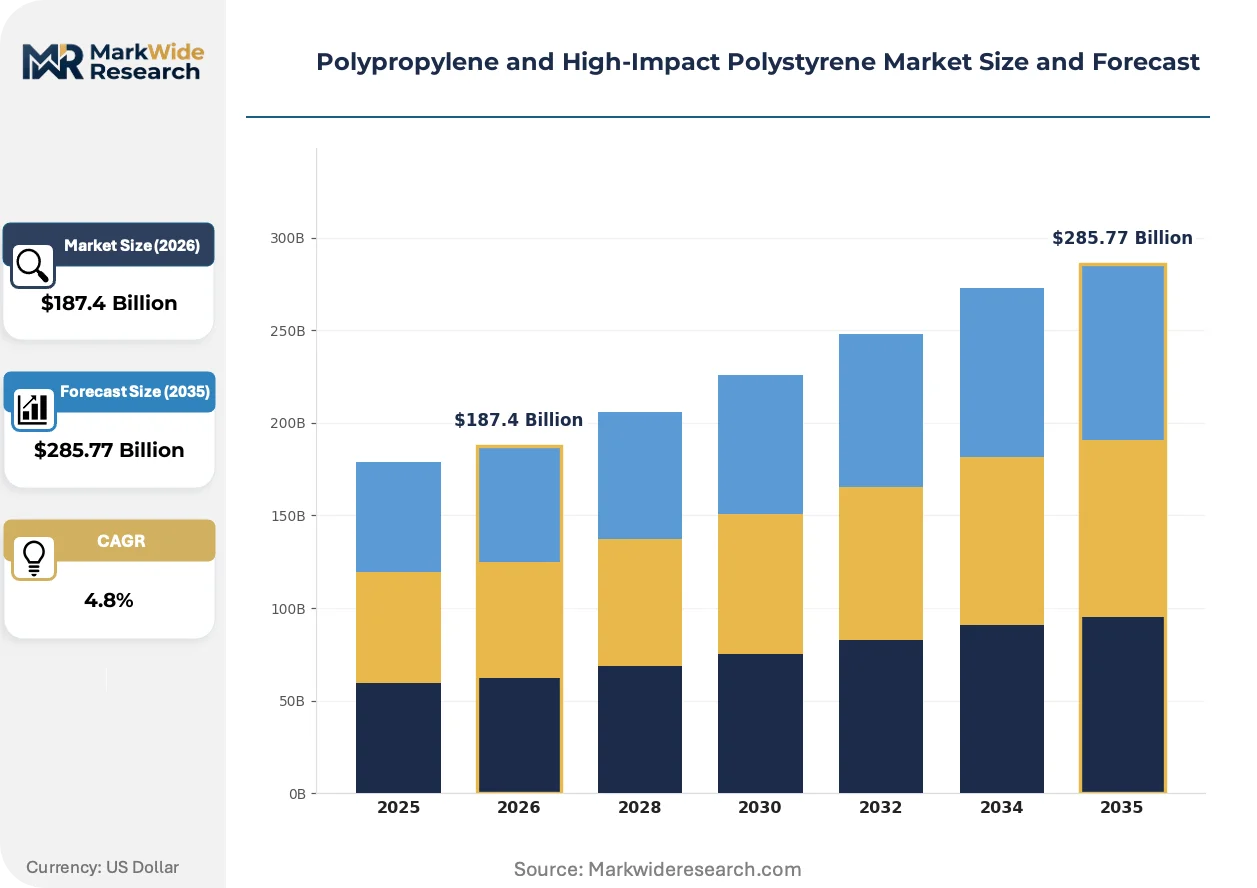
Market Dynamics
Automotive lightweighting mandates and circular economy regulations are forcing resin producers to reconfigure feedstock strategies and melt-flow specifications simultaneously across multiple continents.
Growth Catalysts
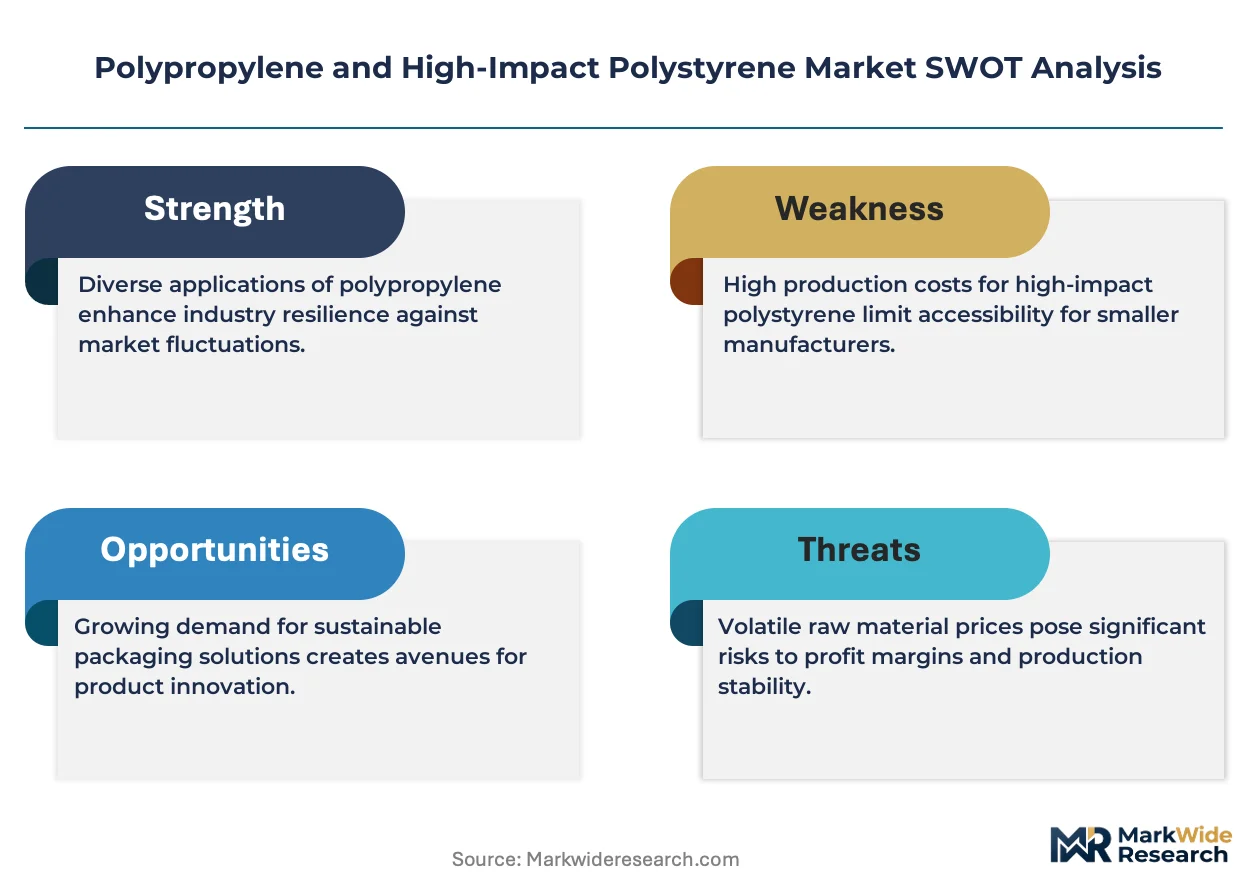
- REACH chemical restrictions:European formulation bans on phthalate-based plasticizers accelerate investment in bio-based polypropylene grades with equivalent flexibility profiles.
- China's dual carbon goals:Naphtha cracker intensity caps under MEE enforcement drive demand for mechanically recycled-content resins in domestic appliance manufacturing.
- Injection molding cycle efficiency:Metallocene-catalyzed copolymers with narrow polydispersity enable thinner-wall automotive ducts without sacrificing impact resistance.
Market Restraints
- Propylene feedstock volatility:Steam cracker co-product yields tie resin pricing to naphtha-arbitrage swings between Middle Eastern and North American supply basins.
- High-purity styrenics concentration:Medical-grade HIPS production clusters in Germany and the United States, creating single-source risk for European device manufacturers.
- Mechanical recycling degradation:Repeated thermal processing of polypropylene chains reduces Izod impact strength below automotive interior panel specifications.
Strategic Opportunities
- India's packaging modernization:FSSAI migration limit harmonization with EU 10/2011 creates opening for food-contact-certified HIPS in dairy and confectionery segments.
- Closed-loop automotive takeback:Extended producer responsibility schemes in Germany and California mandate post-industrial scrap reintegration into OEM supply contracts.
- Metallocene-LLDPE convergence:Hybrid catalyst systems enable single-reactor production of polypropylene-ethylene block copolymers with living-hinge fatigue resistance.
Industry Challenges
- Polymer characterization expertise:Melt flow index interpretation for recycled-content grades requires rheologists capable of correlating shear history with end-use performance.
- Additive migration testing backlog:FDA food-contact notification queues for novel nucleating agents delay commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene and High-Impact Polystyrene Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, High-Impact Polystyrene, Polypropylene Block Copolymer End User: Automotive, Consumer Goods, Packaging, Electronics Application: Injection Molding, Extrusion, Thermoforming, Blow Molding Form: Granules, Sheets, Films, Pellets |
| Companies Covered | LG Chem Ltd., Braskem, INEOS Styrolution Group GmbH, Formosa Chemicals & Fibre Corporation, Versalis S.p.A., Trinseo PLC, SABIC, Chevron Phillips Chemical Company, Chi Mei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene and High-Impact Polystyrene Market Evolving Landscape
Resin producers are racing to decouple volume growth from virgin fossil feedstock dependence through chemical recycling scale-up and mass-balance certification schemes.
Advanced recycling pyrolysis oils are expanding into virgin-equivalent polypropylene production for automotive interior applications. Tier-1 suppliers in Germany and the United States now specify ISCC PLUS-certified resins with 30% pyrolysis content for instrument panel substrates. This technology is expanding into blow-molded HVAC ducting where odor and color specifications previously blocked mechanical recycling acceptance.
China's MEE dual carbon enforcement is tightening emission intensity benchmarks for naphtha crackers in Shandong and Zhejiang provinces. Provincial authorities now link production permits to verified carbon accounting through third-party audit protocols. Polyolefin units in the Yangtze River Delta are responding by integrating carbon capture retrofits and bio-naphtha co-feed trials.
Brand-owner sustainability procurement mandates are compressing supplier qualification cycles for recycled-content certifications. Consumer goods multinationals now require mass-balance documentation from resin converters prior to contract renewal. This pattern is most visible in European flexible food packaging where retailer plastic reduction pledges cascade through tier-2 compounder selection criteria.
Polypropylene and High-Impact Polystyrene Market Segmentation
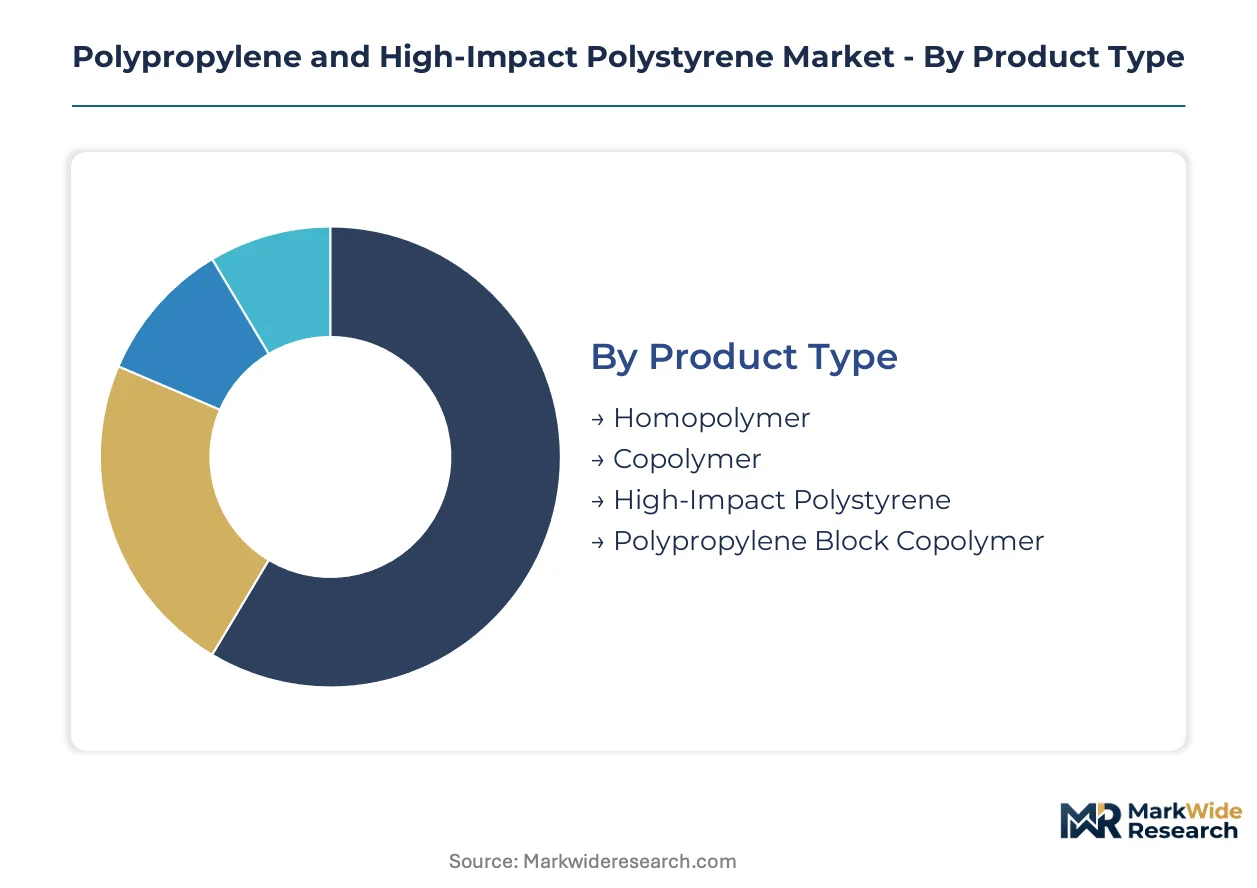
Resin specifications diverge sharply across end-use requirements, with melt flow indices and impact strength tolerances dictating formulation choices. Procurement teams segment supply contracts by conversion technology compatibility rather than material chemistry alone.
Product Type:
Upgrade cycles in automotive interior specifications and packaging sustainability mandates are accelerating grade substitution across homopolymer and copolymer categories.
- Homopolymer:High crystallinity grades deliver stiffness-to-weight ratios exceeding 1.5 GPa density-adjusted modulus, serving structural automotive under-the-hood components in Germany and the United States where OEMs enforce 15-year thermal aging standards. REACH restrictions on phthalate plasticizers are compressing demand in flexible applications, redirecting volumes toward rigid appliance housings.
- Copolymer:Ethylene incorporation at 3-7% weight fraction extends low-temperature ductility to -40°C, capturing blow-molded HVAC duct contracts from Chinese and US automotive tier-1 suppliers. Metallocene catalysis narrows polydispersity indices below 2.5, enabling thinner-wall designs without sacrifice in drop-test performance.
- High-Impact Polystyrene:Rubber particle sizes of 1-5 micrometers deliver Izod impact strengths of 10-25 kJ/m² for refrigerator liner thermoforming and medical device housings subject to FDA 21 CFR compliance.
- Polypropylene Block Copolymer:Sequential polymerization architecture separates crystalline and amorphous domains, serving living-hinge packaging applications where 100,000-cycle fatigue resistance is mandatory.
Homopolymer sits at the top of the volume ranking, with copolymer climbing the fastest.
End User:
Customer procurement scale determines contract structure, with automotive OEMs negotiating multi-year resin supply agreements against consumer goods spot-market purchasing.
- Automotive:Lightweighting mandates in Germany, China, and the United States specify density targets below 1.0 g/cm³ for interior panels, with BMW and Toyota qualifying recycled-content grades at 30% pyrolysis oil inclusion. MEE carbon intensity caps in Shandong province are forcing domestic suppliers toward mass-balance certification.
- Consumer Goods:Appliance manufacturers in India and Brazil specify HIPS for refrigerator liners where thermal insulation properties must withstand 80°C compressor proximity. BIS certification requirements for electrical housings add 8-12 week qualification timelines.
- Packaging:Flexible food-contact applications in the European Union face EU 10/2011 migration limit enforcement, with brand-owners demanding ISCC PLUS documentation for recycled-content claims.
- Electronics:High-purity HIPS grades serve medical device housings and laboratory equipment where USP Class VI biocompatibility is required.
Automotive commands the largest contract values, with packaging expanding most quickly.
Application:
Conversion technology selection locks in resin specification ranges, with injection molding cycle economics dominating high-volume procurement decisions.
- Injection Molding:Cycle times below 30 seconds for thin-wall automotive ducts require melt flow indices of 20-50 g/10 min, with metallocene grades commanding 8-12% price premiums for narrow molecular weight distribution. German tier-1 suppliers specify these grades for instrument panel substrates.
- Extrusion:Sheet extrusion for thermoformed packaging demands melt strength stability across 200-250°C processing windows, with copolymer grades capturing dairy container contracts in India following FSSAI-EU harmonization.
- Thermoforming:Deep-draw ratios exceeding 3:1 for refrigerator liners favor HIPS with 6-8% rubber content for uniform thickness distribution.
- Blow Molding:Parison swell control in automotive HVAC ducts requires high melt strength copolymers with strain-hardening indices above 1.2.
Injection molding holds the highest throughput volumes, with blow molding gaining share fastest in under-the-hood applications.
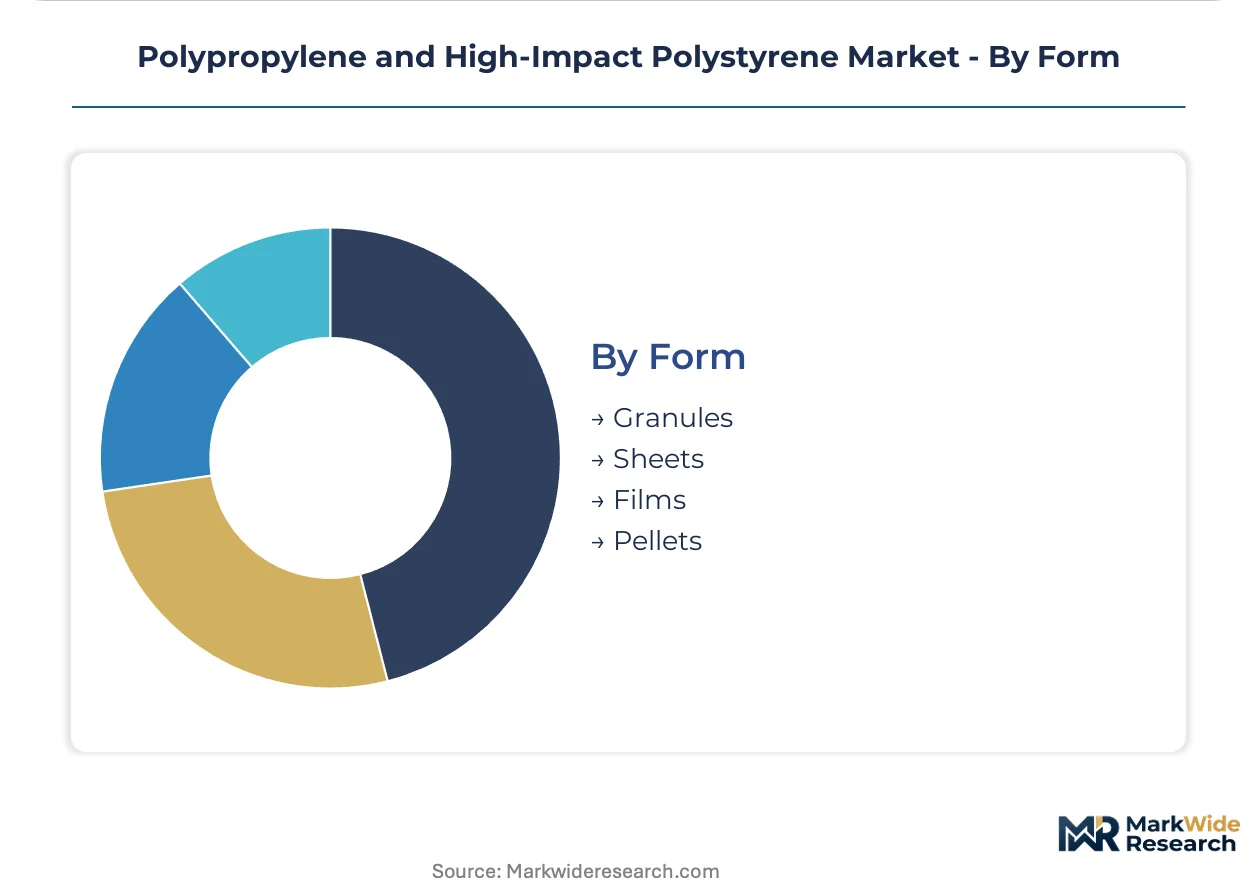
Form:
Physical form determines logistics economics and downstream processing capital requirements, with bulk pellet supply dominating automotive contract structures.
- Granules:Standard 3-5 mm pellet dimensions serve compounder blending operations where color masterbatch and additive packages are integrated prior to OEM delivery.
- Sheets:Extruded HIPS sheet at 1.5-3.0 mm gauges feeds inline thermoforming lines for food packaging and appliance liners, with thickness tolerances of ±3% specified by European converters.
- Films:Biaxially oriented polypropylene films at 20-40 micron thickness serve snack packaging barrier layers, with metallization compatibility driving specification in India and Southeast Asia.
- Pellets:Virgin-equivalent pyrolysis-derived pellets with ISCC PLUS certification are penetrating automotive specifications in Germany and California where extended producer responsibility mandates apply.
Pellets dominate shipment volumes, with films showing the steepest expansion trajectory in flexible food packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The polypropylene and high-impact polystyrene industry traces its modern scale to German chemical engineering advances in Ziegler-Natta catalysis during the 1950s, with subsequent capacity buildouts in the US Gulf Coast and Northeast Asia establishing today's tripartite supply geography.
United States
Automotive OEMs in Michigan and Ohio specify recycled-content grades for instrument panel substrates under extended producer responsibility commitments. EPA Clean Air Act enforcement targets volatile organic compound emissions from Gulf Coast steam crackers. Houston Ship Channel petrochemical complexes are integrating ISCC PLUS certification for pyrolysis-derived resin output.
Germany
BMW and Volkswagen qualify mass-balance-certified polypropylene for interior lightweighting programs reaching 30% recycled content. REACH restrictions on phthalate plasticizers redirect formulation investments toward bio-based feedstocks. Ludwigshafen and Marl chemical parks anchor European high-purity styrenics production for medical device applications.
China
MEE dual carbon intensity caps force naphtha cracker operators in Shandong and Zhejiang toward carbon capture retrofits. Domestic appliance manufacturers specify mechanically recycled-content resins to meet provincial emission benchmarks. Yangtze River Delta polyolefin units are trialing bio-naphtha co-feed at commercial scale.
India
FSSAI harmonization with EU 10/2011 migration limits opens food-contact HIPS demand in dairy and confectionery packaging. BIS certification requirements for electrical housings extend supplier qualification timelines. Gujarat and Maharashtra industrial corridors attract compounding investments serving appliance and automotive tier-1 supply chains.
Saudi Arabia
SABIC's integrated petrochemical complexes leverage advantaged ethane feedstock costs for export-grade homopolymer production. Domestic downstream diversification targets automotive and packaging conversion within Vision 2030 industrialization mandates. Jubail and Yanbu industrial cities concentrate capacity additions for Asian and European offtake markets.
Polypropylene and High-Impact Polystyrene Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with backward control over naphtha and ethane feedstocks. Three archetypes dominate: Gulf-based ethane-advantaged producers, Northeast Asian integrated refiners, and European specialty styrenics specialists. Capacity expansion and mass-balance certification partnerships constitute the primary competitive moves as sustainability procurement mandates harden.
Among Korean and Brazilian producers, LG Chem Ltd. and Braskem exemplify the integrated refinery-to-resin archetype with captive feedstock security. INEOS Styrolution Group GmbH anchors the European high-purity styrenics specialization tier. These three occupy positions across the cost-curve spectrum from commodity scale to medical-grade premium positioning.
| Leading Market Players |
|---|
| LG Chem Ltd. |
| Braskem |
| INEOS Styrolution Group GmbH |
| Formosa Chemicals & Fibre Corporation |
| Versalis S.p.A. |
| Trinseo PLC |
| SABIC |
| Chevron Phillips Chemical Company |
| Chi Mei Corporation |
| Others |
Value Network & Pricing Analysis
OEM sustainability procurement mandates for ISCC PLUS-certified recycled-content grades are forcing resin producers to absorb certification premiums and pyrolysis oil feedstock costs, compressing margins on standard homopolymer contracts while creating price stratification around mass-balance documentation tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS-certified automotive grades from uncertified commodity homopolymer and spot-market distressed volumes. Price differentiation centers on certification tier and volume scale, with German OEM contracts commanding premiums for 30% recycled-content specifications. Cost compression in standard-grade homopolymer is intensifying because Middle Eastern ethane-advantaged supply is displacing naphtha-based European production. Appliance manufacturers in India exhibit highest price sensitivity due to BIS certification delays, while medical-device OEMs in Germany show least sensitivity given single-source qualification requirements.
Supply Chain Analysis
ISCC PLUS and FDA food-contact qualification gating restricts supplier pools to integrated petrochemical complexes with verified mass-balance accounting capabilities. Geographic supply concentrates in Saudi Arabia, China, and the United States, with SABIC's Jubail complexes, Yangtze River Delta polyolefin units, and Gulf Coast steam crackers anchoring global capacity. Raw material dependencies rest on naphtha cracker co-product yields, bio-naphtha co-feed trials, and pyrolysis oil scale-up. Single-source vulnerability concentrates in medical-grade HIPS production clustered in Germany and the United States. Distribution runs through compounder blending operations where additive packages and color masterbatch integration precede OEM delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between ethane-advantaged Middle Eastern production and naphtha-based European supply, with carbon intensity regulations in China and REACH restrictions widening cost differentials that favor integrated refinery-to-resin operators.
For Market Incumbents: Lock in backward integration into pyrolysis oil supply through offtake agreements with chemical recycling operators, and anchor capacity additions in Saudi Arabia or US Gulf Coast locations where feedstock costs insulate against European regulatory compression. Defend position by accelerating ISCC PLUS certification across all product grades before brand-owner procurement mandates harden qualification windows. For New Entrants and Emerging Players: Direct-to-compounder digital platforms offer a route to bypass established distributor relationships and capture spot-market volumes from distressed European naphtha-based producers. Target India's packaging modernization segment where FSSAI-EU harmonization creates first-mover advantage for food-contact-certified HIPS, and pursue private-label supply contracts with appliance OEMs in Gujarat and Maharashtra industrial corridors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty styrenics producers holding FDA medical-device qualifications and narrow-molecular-weight metallocene copolymer capabilities. Long-term viability favors acquisition targets with verified mass-balance certification infrastructure and pyrolysis oil integration pathways rather than pure commodity scale. Watch for inflection when California or German extended producer responsibility schemes mandate minimum recycled-content thresholds in automotive supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Oil Supply | Secures ISCC PLUS feedstock for BMW and Volkswagen recycled-content specifications. |
| Mass-Balance Certification Investment | Unlocks German and California automotive OEM contract eligibility under EPR mandates. |
| Capacity Expansion in Ethane-Advantaged Geography | Captures cost spread versus European naphtha-based competitors facing REACH restrictions. |
| Joint Venture for Bio-Naphtha Co-Feed Trials | Positions Yangtze River Delta units ahead of MEE dual carbon intensity enforcement. |
| Long-Term Supply Agreement with Medical Device OEM | Locks in premium pricing for USP Class VI biocompatible HIPS grades. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Saudi Arabia, with primary inputs from each region combining interviews with plant managers at integrated petrochemical complexes, procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors specializing in metallocene catalysis. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from listed resin producers, and FDA food-contact notification databases. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Granularity-level framing applied country-specific melt flow index specifications, copolymer ethylene incorporation tiers, and end-use industry conversion technology compatibility as core segmentation dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand modeling for automotive lightweighting, packaging sustainability mandates, and appliance manufacturing cycles. Industry-specific inputs included naphtha-ethane feedstock spread dynamics, MEE carbon intensity enforcement timelines, and REACH restriction implementation phases.
The model assumes a particular technology adoption path for chemical recycling pyrolysis scale-up; alternative pathways for mechanical recycling quality retention would alter the outlook for automotive interior panel specifications. Forecasts reflect assumptions around brand-owner sustainability procurement mandate adoption rates and provincial carbon accounting verification protocols. A model refresh is warranted upon material change in EU extended producer responsibility scheme implementation or MEE dual carbon enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Thermoplastics Market