
 Mexico Oral Anti-Diabetic Drug Market | 2026-2036
Mexico Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Oral Anti-Diabetic Drug Market Insights
Fixed-dose combination manufacturing is fragmenting traditional single-molecule production lines across Mexican pharmaceutical operations. Novo Nordisk leverages its insulin-to-oral portfolio bridge to anchor hospital formulary relationships. Eli Lilly and Company sustains competitive pressure through GLP-1 receptor agonist adjacencies that reshape prescriber switching patterns. AstraZeneca differentiates via SGLT2 inhibitor cardiovascular outcome positioning in cardiology-endocrinology crossover protocols.
Mexico oral anti-diabetic drugs comprise chemically synthesized hypoglycemic agents administered perorally to reduce blood glucose in type 2 diabetes mellitus, formulated as immediate-release tablets, extended-release matrices, or oral solutions with defined dissolution profiles and bioequivalence thresholds against reference listed drugs. Their primary purpose is to achieve glycemic control as monotherapy or in combination regimens, delaying insulin initiation and reducing microvascular complication risk. Metformin immediate-release and extended-release formulations occupy the volume base due to decades of first-line guideline placement and low manufacturing cost structure. SGLT2 inhibitors represent the fastest-expanding margin pool as nephrology and cardiology co-prescription broadens beyond endocrinology silos. DPP-4 inhibitors compete in the middle tier where payer cost-containment policies favor generic erosion of originator compounds.
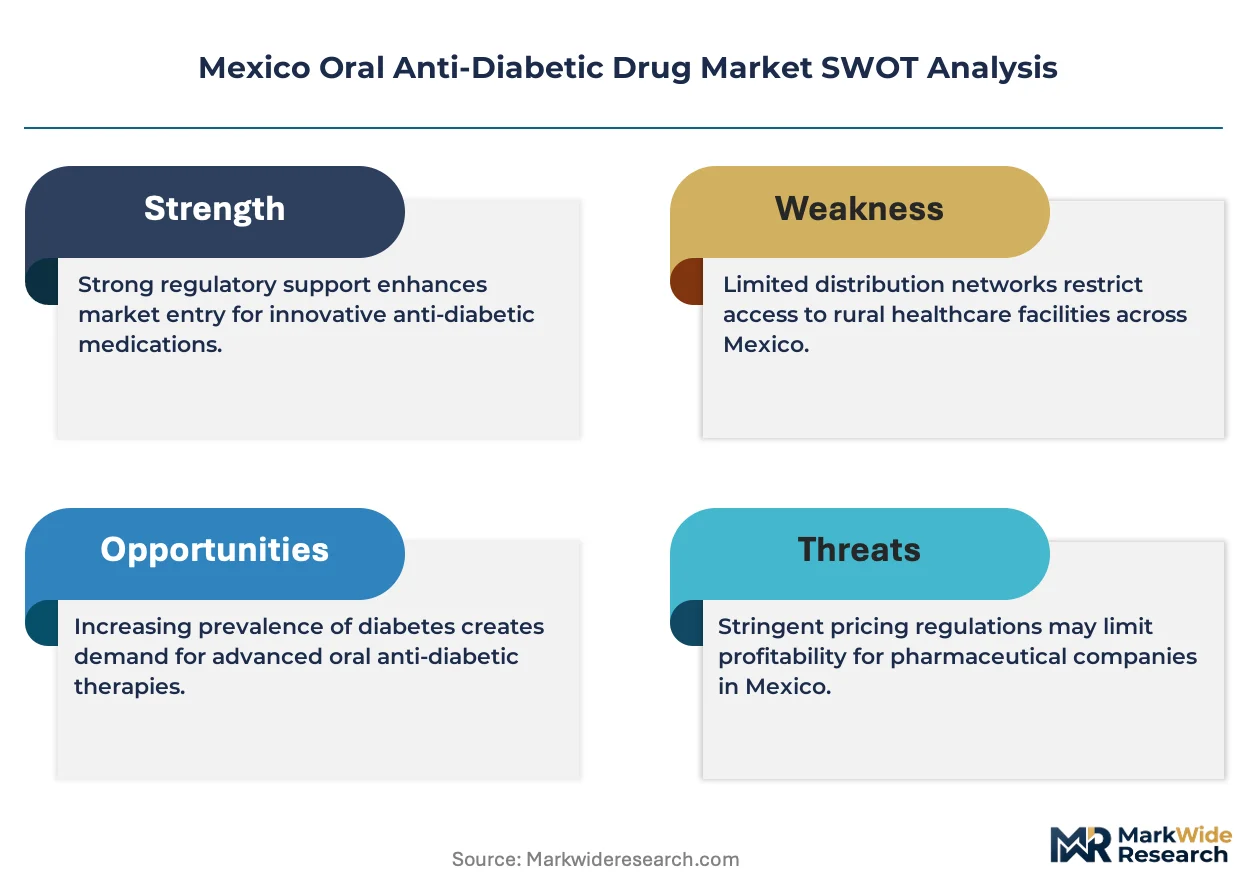
COFEPRIS maintains bioequivalence study requirements for generic oral anti-diabetic approvals, while the national health system's UNEME-CRC diabetes clinic network shapes demand through standardized treatment algorithms and formulary restrictions. The country's national pharmaceutical regulator enforces good manufacturing practice inspections that filter substandard imports from Asian suppliers. Stakeholders must monitor whether Mexico's forthcoming pharmaceutical traceability mandate alters wholesaler consolidation patterns and direct-to-pharmacy distribution economics.
Market Dynamics
Fixed-dose combination manufacturing is fragmenting traditional single-molecule production lines across Mexican pharmaceutical operations, forcing facility reconfiguration and API sourcing diversification.
Growth Catalysts
- COFEPRIS fast-track pathways:The regulator's accelerated review for chronic disease medicines compresses registration timelines from 18 months to under 12 months. This pulls forward revenue recognition for sponsors.
- UNEME-CRC clinic network expansion:The national diabetes clinic infrastructure standardizes treatment algorithms that favor formulary inclusion of second-line oral therapies. Volume flows through public procurement channels.
- Cardiology-endocrinology protocol convergence:SGLT2 inhibitors with cardiovascular outcome data are displacing sulfonylureas in hospital formularies. Prescriber behavior shifts toward renal and cardiac protection metrics.
Market Restraints
- API import concentration:Active pharmaceutical ingredient supply concentrates among Chinese manufacturers subject to COFEPRIS good manufacturing practice inspection backlogs. Supply interruption risk elevates safety stock requirements.
- Generic erosion of DPP-4 inhibitors:Payer cost-containment policies at IMSS and ISSSTE accelerate price compression on originator compounds. Margin pools contract faster than volume expansion.
- Bioequivalence study cost structure:COFEPRIS requirements for pharmacokinetic trials against reference listed drugs impose six-figure peso burdens on domestic generic entrants. Market participation narrows to capitalized firms.
Strategic Opportunities
- Jalisco and Nuevo León manufacturing clusters:Underpenetrated states with rising diabetes prevalence lack specialist density. Regional distribution partnerships with state health systems capture volume ahead of saturation.
- Pharmaceutical traceability mandate:Mexico's forthcoming serialization requirement creates first-mover advantage for wholesalers investing in direct-to-pharmacy distribution infrastructure. Channel consolidation favors integrated players.
- Extended-release matrix technology:Convergence of polymer science with continuous manufacturing enables once-daily formulations that improve adherence. Patient retention economics favor reformulation investments.
Industry Challenges
- Formulary negotiation complexity:IMSS, ISSSTE, and INSABI operate distinct procurement calendars and technical committees. Parallel submission requirements strain regulatory affairs capacity.
- Legacy insulin-to-oral switching protocols:Hospital endocrinology departments maintain embedded relationships with injectable portfolio sponsors. Oral therapy displacement requires prescriber education investment.
- Wholesaler consolidation friction:Traceability-driven distribution restructuring disrupts existing credit terms and inventory ownership models. Working capital requirements shift toward manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Oral Anti-Diabetic Drug Market |
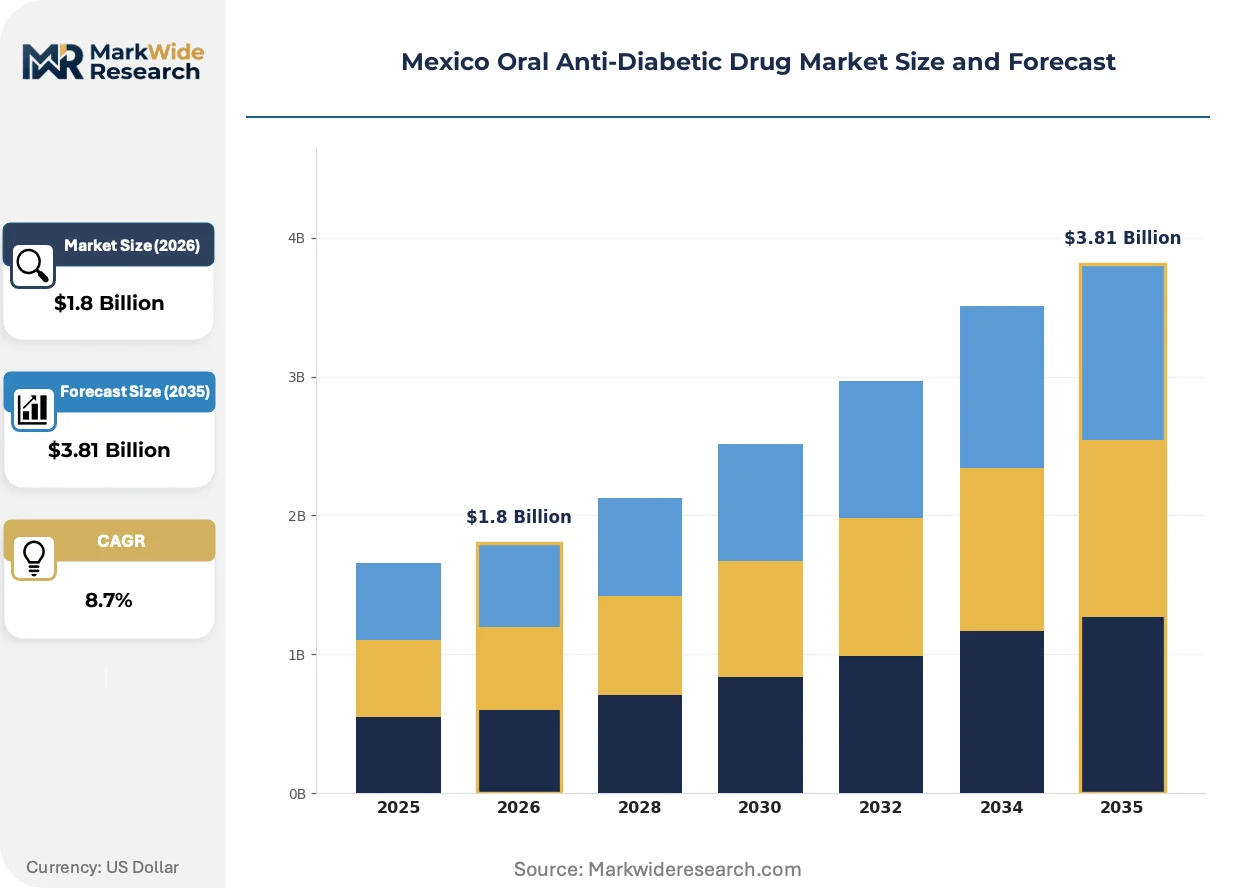
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers End User: Clinics, Hospitals, Homecare, Pharmacies Formulation: Tablet, Oral Solution, Extended-Release Tablet, Granules |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, AstraZeneca, Sanofi, Boehringer Ingelheim, Takeda Pharmaceutical, Pfizer, Merck & Co., Novartis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Oral Anti-Diabetic Drug Market Trends and Innovations
Digital integration across manufacturing and distribution layers is compressing batch release cycles and enabling real-time quality verification in Mexican pharmaceutical operations.
Continuous direct compression technology is digitizing tablet production workflows by replacing batch-oriented wet granulation with real-time powder feeding and in-line near-infrared spectroscopy. Contract manufacturers in Querétaro and Puebla are adopting these systems to meet COFEPRIS good manufacturing practice inspection standards. The technology is digitizing documentation and release protocols, collapsing batch record review from weeks to hours.
COFEPRIS bioequivalence guidance revisions now mandate narrower confidence intervals for critical-dose drugs including metformin extended-release formulations. The policy tightens pharmacokinetic comparability thresholds and elevates study design costs. Generic sponsors are responding by consolidating bioanalytical contract research organization relationships to secure capacity.
Public hospital procurement is consolidating volume through centralized UNEME-CRC formulary committees that bypass traditional wholesaler relationships. State health secretariats in Mexico and Jalisco are piloting direct manufacturer agreements for second-line oral therapies. This pattern concentrates most visibly in Mexico City, where IMSS specialty hospitals negotiate annual tenders with sole-source provisions.
Mexico Oral Anti-Diabetic Drug Market Segmentation
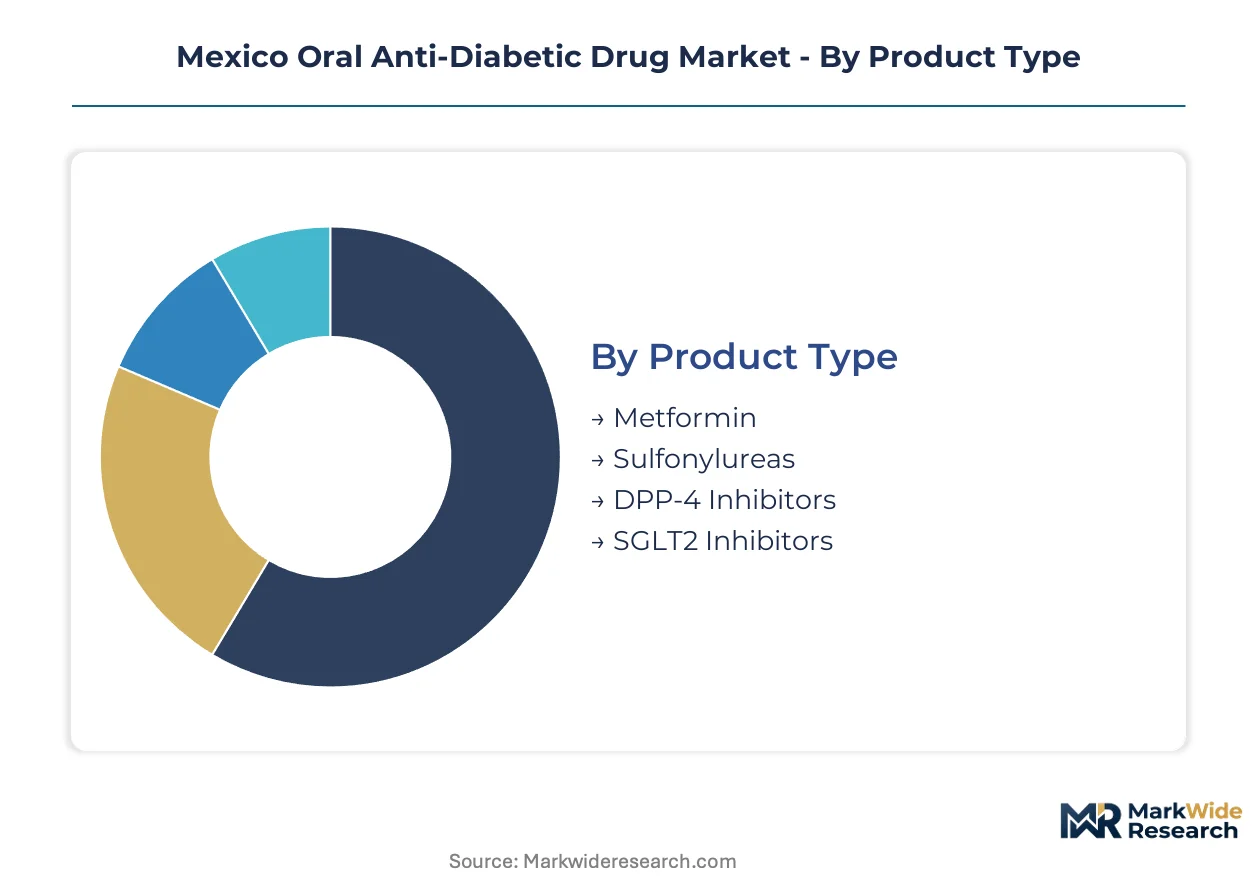
Segmentation reveals how COFEPRIS regulatory pathways, UNEME-CRC formulary committees, and regional diabetes prevalence reshape procurement patterns across Mexico's oral anti-diabetic landscape. Each dimension exposes distinct margin structures and access barriers.
Product Type:
Use-case spectrum spans first-line metabolic control through organ-protective second-line interventions, with reimbursement tiering separating volume leaders from premium-margin compounds.
- Metformin:Immediate-release and extended-release formulations dominate prescription volume through decades of first-line guideline placement. IMSS and ISSSTE procurement channels concentrate demand in Mexico City and State of Mexico, where UNEME-CRC clinics standardize metformin-first protocols. Established volume favors metformin; emerging adoption favors SGLT2 inhibitors.
- Sulfonylureas:Glimepiride and glipizide compounds retain formulary presence through low acquisition cost, though cardiology-endocrinology protocol convergence is displacing their hospital use. Demand concentrates in state health secretariat tenders outside specialist-dense urban centers.
- DPP-4 Inhibitors:Sitagliptin and linagliptin formulations compete in the middle reimbursement tier where generic erosion accelerates price compression.
- SGLT2 Inhibitors:Empagliflozin and dapagliflozin are climbing the fastest as nephrology and cardiology co-prescription broadens beyond endocrinology silos.
Cost tier separation distinguishes mature molecules facing generic pressure from organ-protective compounds commanding premium positioning.
Distribution Channel:
Channel configuration determines inventory ownership, credit terms, and traceability compliance burden as Mexico's serialization mandate approaches.
- Retail Pharmacies:Independent and chain pharmacies handle cash-pay segments and private insurance reimbursement across urban corridors. COFEPRIS good manufacturing practice enforcement filters substandard imports before they reach this channel.
- Hospital Pharmacies:IMSS specialty hospitals and UNEME-CRC clinic dispensaries operate centralized procurement with sole-source annual tenders. Demand concentrates in Mexico City, where formulary committees bypass traditional wholesaler relationships.
- Online Pharmacies:Digital platforms are expanding most quickly in metropolitan zones with established cold-chain logistics, though chronic medication adherence programs lag institutional channels.
- Wholesalers:Regional distributors in Jalisco and Nuevo León face consolidation pressure as traceability requirements elevate working capital needs.
Direct manufacturer agreements are displacing traditional wholesaler intermediation in public procurement; private retail retains fragmented distribution economics.
End User:
Patient acuity and prescriber specialization shape therapy selection, with institutional protocols diverging from ambulatory practice patterns.
- Clinics:UNEME-CRC diabetes clinics standardize treatment algorithms that favor formulary inclusion of second-line oral therapies. Volume flows through public procurement channels with defined bioequivalence thresholds.
- Hospitals:IMSS specialty hospitals and ISSSTE facilities maintain embedded relationships with injectable portfolio sponsors. Oral therapy displacement requires prescriber education investment.
- Homecare:Extended-release formulations improve adherence in patient-managed settings across underpenetrated states.
- Pharmacies:Community dispensing sites bridge prescription fulfillment with patient counseling on hypoglycemia risk.
Institutional volume concentrates in Mexico City and State of Mexico; homecare and pharmacy channels extend reach into specialist-scarce regions.
Formulation:
Manufacturing technology and dissolution profile determine bioequivalence study burden and prescriber preference for dosing convenience.
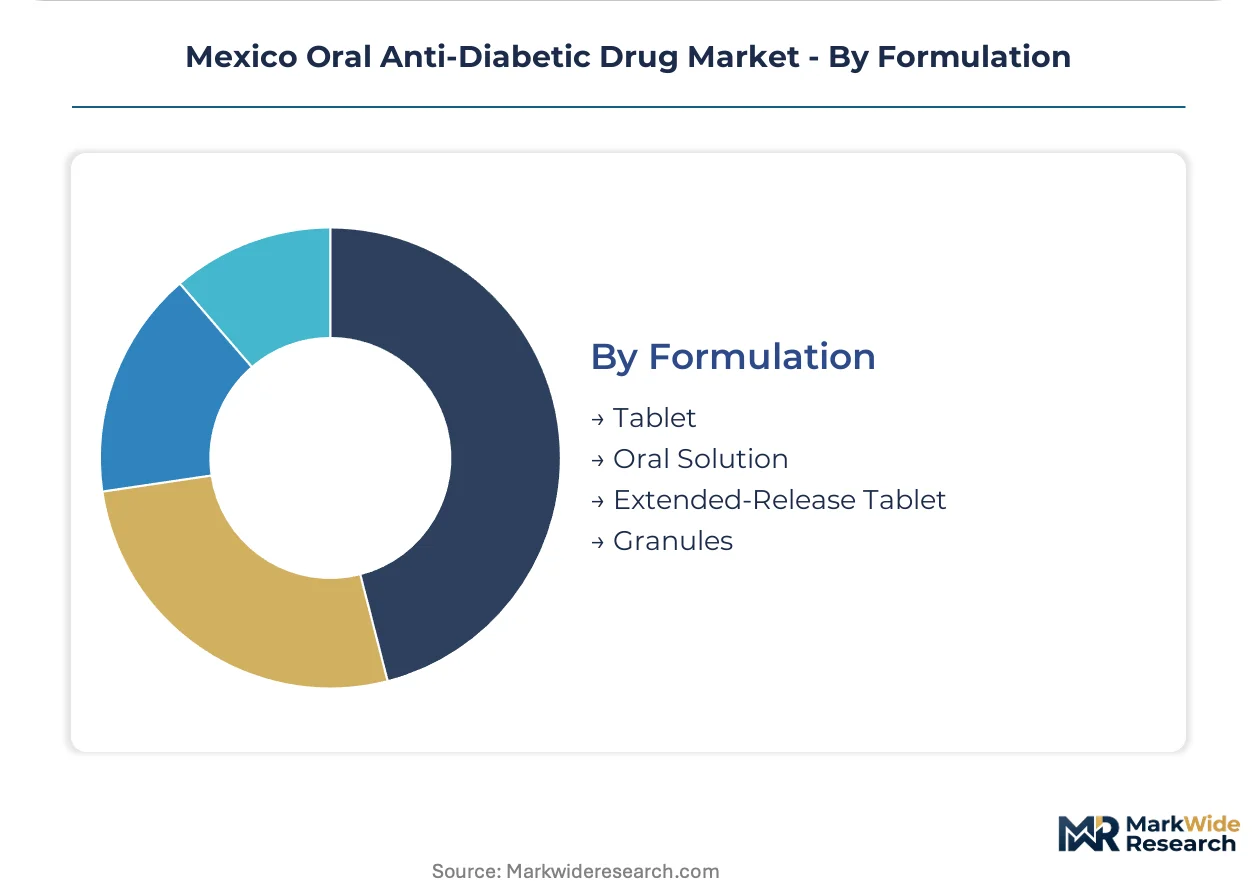
- Tablet:Immediate-release tablets occupy the volume base through low manufacturing cost structure and established compression workflows. COFEPRIS bioequivalence guidance revisions now mandate narrower confidence intervals for critical-dose drugs.
- Extended-Release Tablet:Polymer matrix technology enables once-daily dosing that improves patient retention. Continuous direct compression systems in Querétaro and Puebla contract manufacturers collapse batch release cycles.
- Oral Solution:Liquid formulations serve geriatric and dysphagia populations with defined dissolution profiles.
- Granules:Sachet presentations offer dose flexibility for titration protocols in pediatric or renal-impaired patients.
Matrix technology investments favor extended-release platforms; immediate-release tablets retain cost-driven procurement dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's oral anti-diabetic drug trade balance tilts toward import dependency, with active pharmaceutical ingredients sourced predominantly from Asian manufacturers while finished formulations circulate through domestic distribution networks anchored in central Mexico.
Mexico City Metro
Diabetes prevalence and specialist density converge in the capital region, driving concentrated demand through IMSS specialty hospitals and UNEME-CRC clinic networks. COFEPRIS regulatory oversight filters substandard imports before they reach institutional procurement channels. The metropolitan manufacturing corridor hosts contract research organizations conducting bioequivalence studies for generic sponsors.
Nuevo León
Rising diabetes prevalence in this northern industrial state outpaces specialist availability, creating ambulatory care gaps that retail pharmacies fill. State health secretariat tenders favor low-cost sulfonylureas over cardiology-endocrinology protocol therapies. Monterrey-based distribution partnerships are capturing volume ahead of formulary standardization.
Jalisco
Guadalajara's pharmaceutical manufacturing cluster reconfigures production lines toward fixed-dose combinations as prescriber preferences shift. The state's underpenetrated diabetes clinic infrastructure leaves room for regional distribution partnerships with direct-to-pharmacy networks. Extended-release matrix technology investments concentrate in Querétaro-adjacent contract manufacturing facilities.
Bajío Region
Aguascalientes and Guanajuato pharmaceutical operations adopt continuous direct compression systems to meet COFEPRIS good manufacturing practice standards. The region's logistics connectivity positions it for traceability-mandate distribution restructuring. State health systems here pilot direct manufacturer agreements bypassing traditional wholesaler intermediation.
Northern Border States
Cross-border patient flows and private insurance penetration create dual-market dynamics distinct from central Mexico's public procurement dominance. Tijuana and Ciudad Juárez retail pharmacies serve cash-pay segments with immediate-release metformin formulations. COFEPRIS inspection backlogs on Chinese API imports elevate safety stock requirements for regional distributors.
Mexico Oral Anti-Diabetic Drug Market Competitive Landscape
On the supply side, the industry is structured around multinational originators with embedded hospital formulary relationships and domestic generic manufacturers navigating bioequivalence study burdens. Three archetypes dominate: insulin-to-oral portfolio bridgers, cardiovascular outcome differentiators, and cost-driven generic sponsors. Competitive moves center on prescriber education investments and direct-to-pharmacy distribution infrastructure buildout ahead of serialization mandates.
Within the originator tier, Novo Nordisk and Eli Lilly and Company exemplify portfolio bridgers leveraging injectable relationships to anchor oral therapy displacement. AstraZeneca occupies a position as cardiovascular outcome differentiator, with SGLT2 inhibitor positioning in nephrology-cardiology crossover protocols. These three anchors represent distinct strategic vectors: metabolic continuity, organ-protective premium positioning, and formulary negotiation capacity through hospital embeddedness.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| AstraZeneca |
| Sanofi |
| Boehringer Ingelheim |
| Takeda Pharmaceutical |
| Pfizer |
| Merck & Co. |
| Novartis |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in extended-release matrix manufacturing across Querétaro and Puebla contract facilities is elevating batch premiums for once-daily formulations while compressing margins on immediate-release commoditized tablets. COFEPRIS bioequivalence study backlogs tether pricing power to capitalized sponsors capable of securing contract research organization capacity ahead of generic entrants.
Pricing Analysis
Public procurement buyers anchor three-tier pricing stratification across premium SGLT2 inhibitors, standard DPP-4 compounds, and economy sulfonylurea tiers. Price differentiation hinges on cardiovascular outcome certification status and IMSS formulary placement tier. Cost compression in the DPP-4 segment intensifies as ISSSTE generic substitution policies accelerate originator erosion. State health secretariats exhibit highest price sensitivity; IMSS specialty hospitals prioritize clinical outcome metrics over acquisition cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Querétaro and Puebla facilities adopting continuous direct compression systems. Active pharmaceutical ingredient supply draws from China and India, with metformin hydrochloride and empagliflozin intermediates dominating import volumes. Single-source vulnerability concentrates in COFEPRIS inspection backlogs for Chinese API facilities. Distribution runs through regional wholesalers facing consolidation pressure from forthcoming serialization mandates, with direct-to-pharmacy infrastructure investments favoring integrated logistics players in Mexico City and Jalisco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient adherence program attach rates are expanding faster than molecule volume across Mexico's oral anti-diabetic landscape, creating recurring revenue layers that offset generic price erosion on mature compounds.
For Market Incumbents: Harden hospital formulary embeddedness through cardiology-endocrinology protocol convergence investments that displace legacy insulin relationships. Secure backward integration into API sourcing from Indian alternative suppliers to mitigate Chinese inspection backlog exposure. Expand UNEME-CRC clinic direct agreements ahead of traceability-driven wholesaler restructuring. For New Entrants and Emerging Players: Jalisco and Nuevo León underpenetration offers lowest competitive density for regional distribution partnerships with state health secretariats. Target extended-release formulation gaps where polymer matrix technology investments lag patient preference shifts. Pursue bioequivalence study consortium arrangements with established contract research organizations to compress regulatory entry timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fixed-dose combination manufacturing lines requiring facility reconfiguration. Five-to-ten year viability favors sponsors with integrated distribution infrastructure and COFEPRIS regulatory affairs depth. Monitor COFEPRIS fast-track pathway utilization rates as inflection signal for revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Fast-Track Registration | Accelerated review compresses 18-month timelines to under 12 months for chronic disease sponsors. |
| Extended-Release Matrix Manufacturing | Polymer science convergence enables once-daily adherence improvements commanding formulation premiums. |
| Direct-to-Pharmacy Distribution Buildout | Traceability mandate investments favor integrated wholesalers with serialization-ready infrastructure. |
| Cardiology-Endocrinology Protocol Convergence | SGLT2 inhibitor cardiovascular outcome positioning displaces sulfonylureas in hospital formularies. |
| Regional State Health Secretariat Partnerships | Jalisco and Nuevo León tenders capture volume ahead of UNEME-CRC clinic network saturation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of COFEPRIS registration filings, UNEME-CRC procurement databases, and IMSS formulary committee minutes. Primary interviews engaged regulatory affairs directors at multinational sponsors, procurement managers at state health secretariats, and bioequivalence study coordinators at Querétaro contract research organizations. Secondary validation drew from COFEPRIS good manufacturing practice inspection records, customs API import data, and hospital pharmacy tender announcements. Bottom-up prescription volume modeling triangulated against top-down public health expenditure tracking.
Forecast inputs incorporate treatment line progression rates, dosage form substitution elasticities, and regional diabetes prevalence trajectories across the projection horizon. Segmentation dimensions span molecule class, formulation technology, distribution channel configuration, and end-user institution type. CAGRs derive from epidemiological trend extrapolation, formulary inclusion probability weighting, and pricing tier compression curves. Industry-specific inputs include COFEPRIS review cycle duration assumptions and UNEME-CRC clinic network expansion cadence.
Practitioners should monitor COFEPRIS inspection backlog resolution and API import license volatility for early signals of supply constraint or pricing inflection. Forecasts reflect assumptions regarding formulary standardization velocity and traceability mandate implementation timelines. Quarterly review of state health secretariat tender award patterns and cardiovascular outcome study publication flow is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
France Diabetes Devices Market