
 Saudi Arabia Self-Monitoring Blood Glucose Devices Market | 2026-2036
Saudi Arabia Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Self-Monitoring Blood Glucose Devices Market Insights
Remote patient monitoring subscription services is consolidating recurring revenue models around glucose data platforms. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor cloud-connected analytics in Saudi hospital networks. Roche competes through integrated diabetes management software that sustains clinician engagement across chronic care pathways.
Self-monitoring blood glucose devices comprise portable electrochemical or optical biosensors that quantify capillary glucose concentration via enzymatic reaction with glucose oxidase, typically yielding results within five seconds for clinical or home-based glycemic control. Their primary commercial purpose centers on enabling real-time therapeutic adjustments by type 1 and type 2 diabetes patients outside institutional settings. Continuous glucose monitors now capture the fastest-expanding margin pool as sensor miniaturization reduces calibration burden, while traditional meters retain volume dominance through pharmacy reimbursement tiers. Smart meters with Bluetooth connectivity represent an emerging structural segment where data interoperability commands premium positioning.
SFDA medical device registration mandates ISO 15197 accuracy standards for all commercially distributed glucose meters, while NPHIES integration requirements push manufacturers toward interoperable data formats. The Saudi Food and Drug Authority also enforces post-market surveillance protocols that elevate compliance costs for non-compliant importers. Stakeholders must monitor evolving reimbursement criteria under the Health Sector Transformation Program as coverage decisions will reshape channel economics between retail pharmacies and hospital procurement.
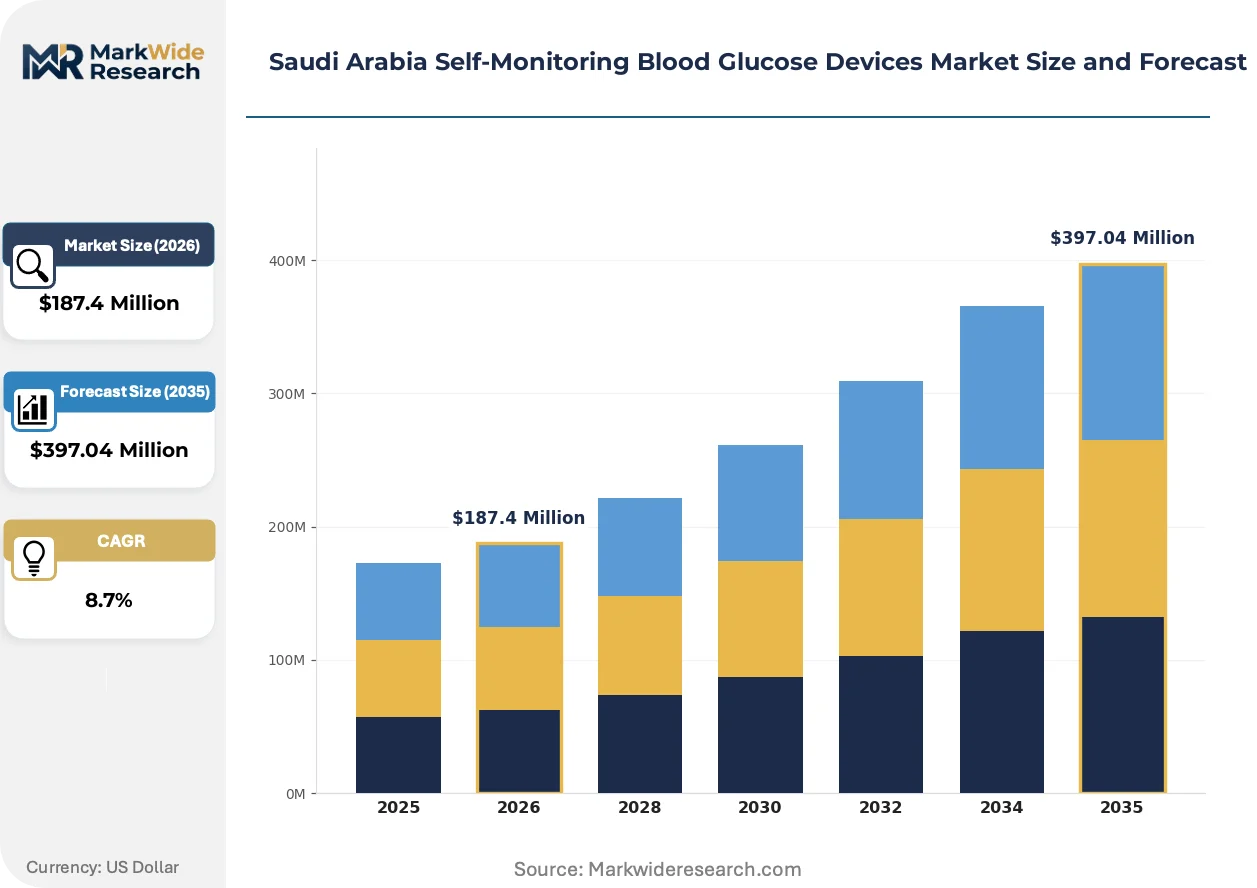
Market Dynamics
SFDA device registration mandates and NPHIES digital health integration requirements are compressing market entry timelines while elevating compliance costs for glucose meter manufacturers seeking hospital procurement contracts.
Growth Catalysts
- Home-based elderly diabetes management:Saudi Arabia's aging demographic is expanding the addressable patient base for portable glucose monitoring outside clinical settings, with family caregivers driving pharmacy channel demand.
- NPHIES interoperability mandate:The National Health Information Exchange System requires connected glucose data formats, accelerating hospital procurement of Bluetooth-enabled meters that feed electronic health records.
- Riyadh-Jeddah hospital network concentration:Specialist diabetes clinics and tertiary care centers in these metropolitan clusters create dense demand pockets for high-accuracy devices with cloud analytics integration.
Market Restraints
- ISO 15197 compliance cost escalation:SFDA enforcement of international accuracy standards for enzymatic biosensors imposes substantial validation expenses on smaller importers, reducing price competition at the economy tier.
- Test strip supply concentration:Dependence on glucose oxidase reagent manufacturing concentrated in East Asian chemical suppliers exposes distributors to input cost volatility and customs clearance delays.
- Continuous glucose monitor substitution:Sensor miniaturization advances in factory-calibrated CGM systems threaten traditional meter volume retention among insulin-intensive type 1 patients seeking reduced fingerstick burden.
Strategic Opportunities
- Eastern Province pharmacy penetration:Dammam and Khobar retail networks remain underdeveloped relative to Riyadh and Jeddah, offering first-mover positioning for brands with Arabic-language mobile app support.
- Remote patient monitoring subscriptions:Recurring revenue models around glucose data platforms enable manufacturers to capture lifetime value beyond initial device sales through clinician dashboard licensing.
- Health Sector Transformation Program reimbursement expansion:Evolving coverage criteria under Saudi Vision 2030 health reforms may extend glucose meter subsidies to prediabetic populations, enlarging the reimbursed patient pool.
Industry Challenges
- Biomedical engineering talent scarcity:SFDA's post-market surveillance protocols require in-country technical staff capable of adverse event reporting and device troubleshooting, stretching specialist recruitment in the Kingdom.
- Legacy hospital IT integration complexity:NPHIES-compliant data formats must interface with heterogeneous electronic medical record systems across Ministry of Health facilities, private hospital chains, and university medical centers, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Self-Monitoring Blood Glucose Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Meters, Continuous Glucose Monitors, Smart Meters, Test Strips End User: Patients, Healthcare Providers, Family Caregivers, Diagnostic Laboratories Technology: Electrochemical, Optical, Enzymatic, Non-Invasive Distribution Channel: Pharmacies, Online Retailers, Hospitals, Medical Supply Stores |
| Companies Covered | Ascensia Diabetes Care Holdings, Rossmax International Ltd, F. Hoffmann-La Roche, Nipro, Nova Biomedical, Abbott Laboratories, Sinocare, Arkray Inc, LifeScan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Connected glucose monitoring ecosystems are displacing standalone meter sales as Saudi healthcare providers prioritize longitudinal patient data visibility over point-in-time measurements.
Factory-calibrated continuous glucose monitoring is rewriting competitive positioning in the Saudi market by eliminating patient calibration burden while delivering 14-day wear periods. Endocrinology departments at King Faisal Specialist Hospital and Saudi German Hospital are adopting these systems for insulin titration protocols. The technology is compressing traditional meter margins among type 1 diabetes patients while creating premium pricing power for integrated sensor-reader-app ecosystems.
SFDA's alignment with ISO 15197:2013 accuracy standards is tightening glucose meter performance thresholds for commercial distribution authorization. The regulation is forcing manufacturers to redesign enzymatic strip chemistry and hematocrit correction algorithms. Hospital procurement committees in Riyadh are now requiring documented compliance certificates as mandatory bid qualifications, disadvantaging uncertified gray-market imports.
Pharmacy reimbursement tier differentiation is fragmenting device selection criteria across Saudi patient segments. Cash-paying patients in Jeddah retail channels prioritize unit cost minimization, while insured populations through Council of Health Insurance schemes access subsidized connected meters with data platform subscriptions. This bifurcation is visible in Dammam's Al Khobar district, where parallel pharmacy and hospital discharge channels serve distinct socioeconomic patient profiles with divergent feature requirements.
Saudi Arabia Self-Monitoring Blood Glucose Devices Market Segmentation
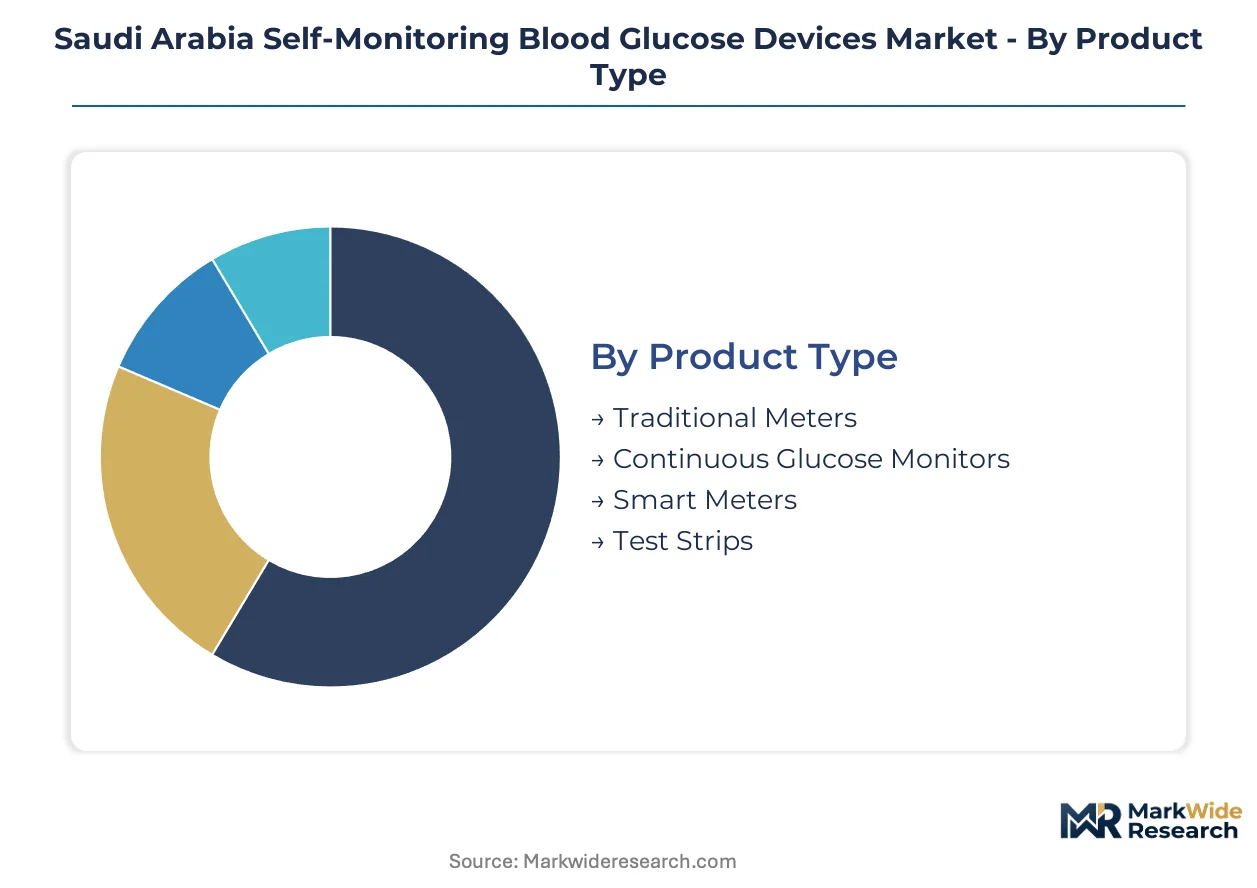
Segmentation reveals how SFDA certification requirements and NPHIES interoperability mandates reshape procurement economics across patient populations and care settings. Device selection criteria diverge sharply between insured hospital discharge channels and cash-paying retail pharmacy customers.
Product Type:
Traditional meters require ISO 15197 accuracy certification for SFDA registration, while continuous glucose monitors face additional electromagnetic compatibility testing for hospital IT integration.
- Traditional Meters:Portable electrochemical biosensors using glucose oxidase enzymatic reactions deliver capillary glucose readings within five seconds. Riyadh retail pharmacies move the highest volumes of these devices to price-sensitive elderly patients managing type 2 diabetes through diet and oral medication adjustments.
- Continuous Glucose Monitors:Factory-calibrated sensors eliminate patient calibration burden through interstitial glucose measurement algorithms. King Faisal Specialist Hospital and Saudi German Hospital in Riyadh-Jeddah clusters are deploying these systems for intensive insulin titration protocols among type 1 pediatric and adult populations.
- Smart Meters:Bluetooth-enabled devices with cloud data transmission capability meeting NPHIES format specifications.
- Test Strips:Disposable glucose oxidase reagent strips subject to hematocrit correction algorithm validation under SFDA post-market surveillance.
Traditional meters sit at the top of the volume ranking, with continuous glucose monitors climbing the fastest.
End User:
Cost tier differentiation separates insured hospital discharge populations from cash-paying retail customers, with family caregivers emerging as a distinct decision-making unit in Eastern Province expansion zones.
- Patients:Individual diabetes self-managers selecting devices based on insurance coverage tier and fingerstick frequency tolerance. Jeddah's insured population through Council of Health Insurance schemes accesses subsidized connected meters, while Dammam cash-paying segments prioritize unit cost minimization.
- Healthcare Providers:Endocrinology departments and primary care clinics prescribing devices as part of chronic care pathway protocols. SFDA registration certificates are mandatory bid qualifications for Ministry of Health procurement committees.
- Family Caregivers:Adult children managing elderly parental diabetes in multigenerational Saudi households, driving pharmacy channel demand for Arabic-language interface devices.
- Diagnostic Laboratories:Reference labs utilizing high-throughput glucose analyzers for HbA1c correlation studies and meter accuracy validation services.
Patients command the dominant volume position, with family caregivers gaining share fastest as elderly home-based management expands.
Technology:
Application requirements determine technology selection, with electrochemical systems dominating point-of-care testing while optical methods serve specific hematocrit correction needs.
- Electrochemical:Amperometric glucose oxidase biosensors generating current proportional to glucose concentration. These systems anchor hospital procurement contracts across Saudi German Hospital and Dr. Sulaiman Al Habib Medical Group networks due to established accuracy validation protocols.
- Optical:Reflectance photometry systems measuring color change intensity in glucose-sensitive reagent chemistry. Niche deployment in high-altitude regions where hematocrit variation affects electrochemical accuracy.
- Enzymatic:Glucose oxidase or hexokinase reaction-based detection methods requiring temperature-stable storage conditions.
- Non-Invasive:Spectroscopic and transdermal glucose measurement technologies still seeking SFDA clinical validation approval for commercial distribution.
Electrochemical technology holds the volume leadership position, with non-invasive methods showing the steepest expansion trajectory pending regulatory clearance.
Distribution Channel:
Customer type bifurcation between insured and cash-paying populations concentrates demand in hospital procurement for the former and retail pharmacies for the latter.
- Pharmacies:Community and hospital-affiliated retail outlets serving walk-in patients and discharge prescriptions. Al Khobar district pharmacies in Dammam serve distinct socioeconomic profiles with divergent feature requirements compared to Riyadh flagship locations.
- Online Retailers:E-commerce platforms expanding device access to remote Eastern Province and Northern Borders regions beyond specialist clinic catchment areas.
- Hospitals:Tertiary care centers and diabetes specialist clinics integrating NPHIES-compliant meters into electronic health record workflows.
- Medical Supply Stores:Independent durable medical equipment distributors serving home healthcare agencies and long-term care facilities.
Pharmacies retain the highest volume throughput, with online retailers expanding most quickly into underserved geographic territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA compliance costs and NPHIES integration requirements create a regulatory-arbitrage gap that favors manufacturers with established Gulf distribution infrastructure over new entrants seeking hospital procurement contracts.
Riyadh
King Faisal Specialist Hospital and Saudi German Hospital anchor demand for NPHIES-compliant connected meters with cloud analytics integration. The Health Sector Transformation Program channels reimbursement through Council of Health Insurance schemes, concentrating insured patient volumes in tertiary care networks. Ministry of Health procurement committees in the capital enforce ISO 15197 certificate requirements as mandatory bid qualifications.
Eastern Province
Dammam and Al Khobar retail pharmacy networks serve underpenetrated cash-paying segments where family caregivers drive Arabic-language device selection. The region's petrochemical workforce demographic shows elevated type 2 diabetes prevalence, expanding home-based monitoring needs. King Fahd University Hospital operates as the primary referral center for CGM adoption among insulin-intensive pediatric populations.
Western Region
Jeddah's commercial hub concentrates private insurance-covered demand through specialist diabetes clinics aligned with Dr. Sulaiman Al Habib Medical Group networks. The port city's import logistics advantage reduces test strip supply lead times for distributors serving the Hejaz corridor. King Abdulaziz University Hospital maintains reference laboratory validation services for meter accuracy correlation studies.
NEOM Northwest
The giga-project's healthcare infrastructure planning incorporates remote patient monitoring architectures that prioritize Bluetooth-enabled glucose data platforms. NEOM's digital-first health system design bypasses legacy EMR integration challenges facing established hospital networks. The zone's regulatory sandbox framework may accelerate SFDA registration pathways for novel non-invasive monitoring technologies.
Saudi Arabia Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement favoring established multinationals holding SFDA registration certificates while retail pharmacy channels accommodate lower-cost imports. The market exhibits tiered concentration: three to four multinational holding companies control premium connected device segments through integrated software ecosystems, while fragmented regional distributors populate economy meter tiers. Strategic archetypes include full-stack diabetes management platforms, component-focused strip suppliers, and telehealth-integrated remote monitoring services. Competitive moves center on NPHIES interoperability certification racing and Eastern Province pharmacy network exclusivity agreements.
Among Swiss-based pharmaceutical conglomerates with diabetes care divisions, F. Hoffmann-La Roche occupies a position exemplifying integrated software-hardware bundling for clinician engagement. Abbott Laboratories represents the ecosystem-architecture archetype through its cloud-connected analytics platform anchoring hospital network procurement. Chinese diagnostic equipment specialists including Sinocare sit within the volume-tier supplier category, serving price-sensitive retail pharmacy segments across Dammam and Jeddah cash-paying markets.
| Leading Market Players |
|---|
| Ascensia Diabetes Care Holdings |
| Rossmax International Ltd |
| F. Hoffmann-La Roche |
| Nipro |
| Nova Biomedical |
| Abbott Laboratories |
| Sinocare |
| Arkray Inc |
| LifeScan |
| Others |
Pricing and Supply Chain Analysis
Factory-calibrated continuous glucose monitoring sensor production is consolidating manufacturing scale among East Asian contract manufacturers while simultaneously compressing unit economics for traditional electrochemical meter producers. This dual shift forces Saudi distributors to rebalance procurement portfolios between premium CGM ecosystems and volume-tier legacy devices.
Pricing Analysis
Distributor margin layers in Saudi Arabia stratify sharply across certification tiers, with SFDA-registered devices commanding 15-25 point premiums over gray-market imports lacking ISO 15197 documentation. Price differentiation rests on NPHIES interoperability certification and Arabic-language mobile app bundling. Cost compression in traditional meter segments is intensifying because Sinocare and other Chinese manufacturers are flooding Dammam retail channels with uncertified units. Cash-paying elderly patients in Eastern Province pharmacies exhibit highest price sensitivity, while insured populations through Council of Health Insurance schemes accept premium connected meter subscriptions.
Supply Chain Analysis
Dual-sourcing requirements from King Faisal Specialist Hospital and Saudi German Hospital procurement committees mandate qualified suppliers for glucose oxidase reagent strips across at least two manufacturing jurisdictions. Supply concentration centers on China, South Korea, and Taiwan for enzymatic biosensor components and Bluetooth module integration. Raw material dependencies include glucose oxidase enzyme formulations, PET substrate films, and electrochemical electrode materials. Single-source vulnerability persists in factory-calibrated CGM sensor manufacturing where proprietary interstitial glucose algorithms lock buyers into sole-supplier relationships. Distribution runs through Ministry of Health central procurement for hospital networks, with retail pharmacies and medical supply stores serving cash-paying segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's Self-Monitoring Blood Glucose Devices Market functions as a regulatory-arbitrage play where SFDA registration costs and NPHIES compliance timelines create defendable moats for established Gulf distributors against direct Chinese import competition.
For Market Incumbents: Extend cloud analytics platform licensing to capture recurring revenue beyond initial device sales, while deepening backward integration into test strip manufacturing to offset glucose oxidase reagent cost volatility. Continuous glucose monitor substitution threatens traditional meter volume retention among insulin-intensive type 1 patients, making NPHIES interoperability certification investment the critical defensive lever. For New Entrants and Emerging Players: Capture underdeveloped Eastern Province pharmacy networks in Dammam and Al Khobar where Arabic-language mobile app support remains scarce and family caregiver decision-making creates brand loyalty opportunities. The most penetrable segment sits among cash-paying elderly type 2 diabetes patients managing home-based care through diet and oral medication adjustments. A direct-to-pharmacy distribution partnership with established Saudi medical supply wholesalers accelerates shelf placement without hospital procurement committee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors holding SFDA registration certificates but lacking integrated software ecosystems, presenting roll-up opportunities for private equity seeking platform consolidation. Long-term viability across the analysis window hinges on NPHIES-compliant data platform ownership rather than hardware margins alone. The signal to watch is Health Sector Transformation Program reimbursement expansion for prediabetic populations, which would enlarge the addressable patient pool materially.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Fast-Track Investment | Abbott Laboratories and Roche leverage existing Gulf distribution infrastructure to compress approval timelines versus new entrants. |
| NPHIES Interoperability Certification | Bluetooth-enabled meter manufacturers secure hospital procurement contracts through electronic health record integration mandates. |
| Eastern Province Pharmacy Network Expansion | Sinocare and economy-tier brands establish first-mover positioning in Dammam cash-paying segments before premium competitors arrive. |
| Remote Patient Monitoring Subscription Launch | Device manufacturers capture lifetime value through clinician dashboard licensing beyond initial hardware sales. |
| Test Strip Manufacturing Backward Integration | Multinationals reduce glucose oxidase reagent supply concentration risk through captive production or exclusive supplier agreements. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, SFDA regulatory affairs specialists, and retail pharmacy buyers in Riyadh and Jeddah grounded the qualitative foundation. Secondary validation drew from SFDA medical device registration databases, Council of Health Insurance reimbursement schedules, Ministry of Health procurement records, and hospital GPO contract filings. Bottom-up patient population estimates triangulated against top-down healthcare expenditure projections.
Segment-level demand outputs across the projection horizon reflect modeled interactions between aging demographics, diabetes prevalence trends, and insurance coverage expansion under Saudi Vision 2030 health reforms. The analytical framework incorporated product type, end user archetype, technology platform, and distribution channel dimensions. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory milestone impacts. Forecast inputs included SFDA approval pipeline status and NPHIES technical specification evolution.
Underlying measurement precision varies by segment; continuous glucose monitor adoption rates carry tighter precision than traditional meter volume estimates due to concentrated hospital procurement visibility. Forecasts reflect assumptions around Health Sector Transformation Program reimbursement timing and SFDA enforcement intensity against gray-market imports. Deviation in NPHIES interoperability mandate implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Germany Continuous Glucose Monitoring Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market