
 China Self-Monitoring Blood Glucose Devices Market | 2026-2036
China Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Self-Monitoring Blood Glucose Devices Market Insights
Aftermarket service revenue is fragmenting across China's self-monitoring blood glucose ecosystem as manufacturers diversify beyond hardware sales. Sinocare dominates domestic production scale for electrochemical test strips while competing aggressively on price in tier-two cities. Abbott Laboratories anchors its position through hospital channel control and specialized diabetes care protocols. Roche differentiates via integrated data platforms that link glucose readings directly to physician dashboards.
Self-monitoring blood glucose devices comprise portable electrochemical or optical biosensors that quantitatively measure capillary blood glucose concentration using enzyme-mediated reactions, typically requiring sample volumes below one microliter and delivering results within five seconds for real-time metabolic management. Continuous glucose monitors represent the fastest-expanding product category as Chinese patients shift from discrete fingerstick testing toward trend-based glycemic pattern recognition. Electrochemical technology leads volume production due to mature domestic supply chains for enzyme electrode fabrication, though dual-function platforms combining glucose and ketone measurement are gaining traction among Type 1 diabetes patients in tertiary hospital networks.
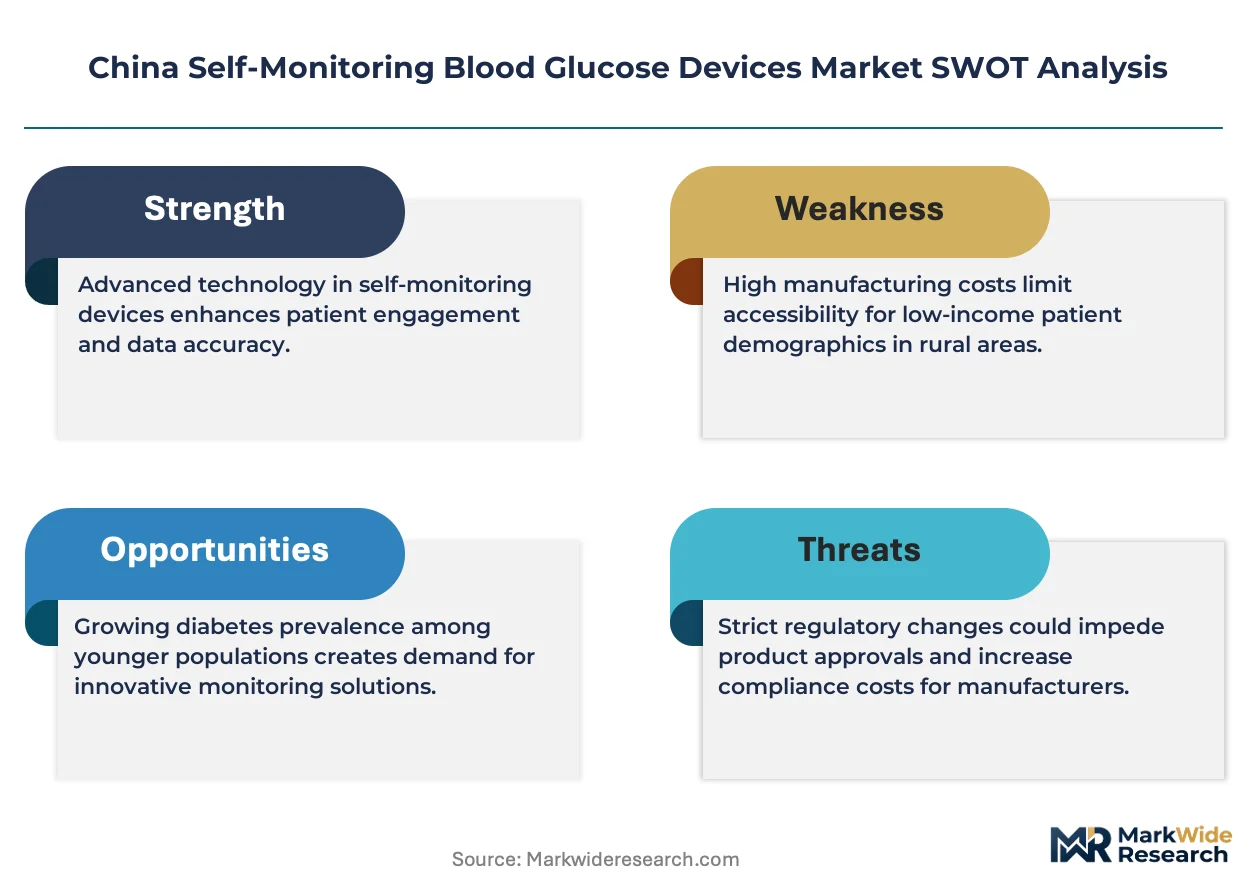
NMPA's updated medical device classification rules and GB standards for in-vitro diagnostic performance establish mandatory accuracy thresholds that filter lower-quality imports from hospital procurement lists. The country's dual carbon goals indirectly shape manufacturing compliance as provincial environmental regulators enforce stricter waste protocols for electrochemical sensor production facilities. Stakeholders must monitor how MIIT's connected health device interoperability standards will reshape data portability requirements between competing glucose monitoring ecosystems.
Market Dynamics
Hospital-at-home program expansion across Shanghai and Beijing is compressing traditional clinical testing volumes while rerouting reimbursement flows toward retail pharmacy channels and direct-to-patient distribution networks.
Growth Catalysts
- Dual carbon goals:Provincial environmental regulators enforce stricter waste protocols for electrochemical sensor production, accelerating facility upgrades that improve manufacturing yields and reduce per-unit costs.
- Type 1 diabetes patient clusters:Tertiary hospital networks in Beijing report rising demand for dual-function glucose-ketone platforms among pediatric and young adult populations.
- MIIT interoperability standards:Connected health device data portability mandates enable seamless glucose reading transmission between patient smartphones and physician dashboards.
Market Restraints
- Enzyme electrode input concentration:Domestic supply chains for glucose oxidase and mediator chemicals remain concentrated in three coastal provinces, exposing manufacturers to regional logistics disruptions.
- Optical biosensor substitution threat:Continuous glucose monitor adoption among urban elderly households reduces fingerstick testing frequency and compresses test strip consumption rates.
- GB standards compliance friction:Updated in-vitro diagnostic performance thresholds require extensive validation studies that delay product registration for imported systems.
Strategic Opportunities
- Tier-two city pharmacy networks:Underpenetrated distribution infrastructure in Chengdu, Xi'an, and Wuhan offers first-mover positioning for localized service and calibration support.
- NMPA streamlined approval pathways:Expedited review timelines for connected monitoring devices reduce time-to-market for Bluetooth-enabled glucose meters with cloud integration.
- AI-driven glycemic pattern recognition:Machine learning algorithms analyzing continuous glucose data streams enable predictive hypoglycemia alerts for insulin-dependent patients.
Industry Challenges
- Biomedical sensor engineering talent:Shortage of specialists in electrochemical enzyme immobilization techniques constrains domestic R&D pipeline velocity.
- Legacy hospital information system integration:Proprietary data formats in tertiary care networks block seamless glucose data import into electronic health records.
- Capital equipment intensity:Cleanroom manufacturing facilities for test strip production require significant upfront investment before achieving regulatory certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Self-Monitoring Blood Glucose Devices Market |
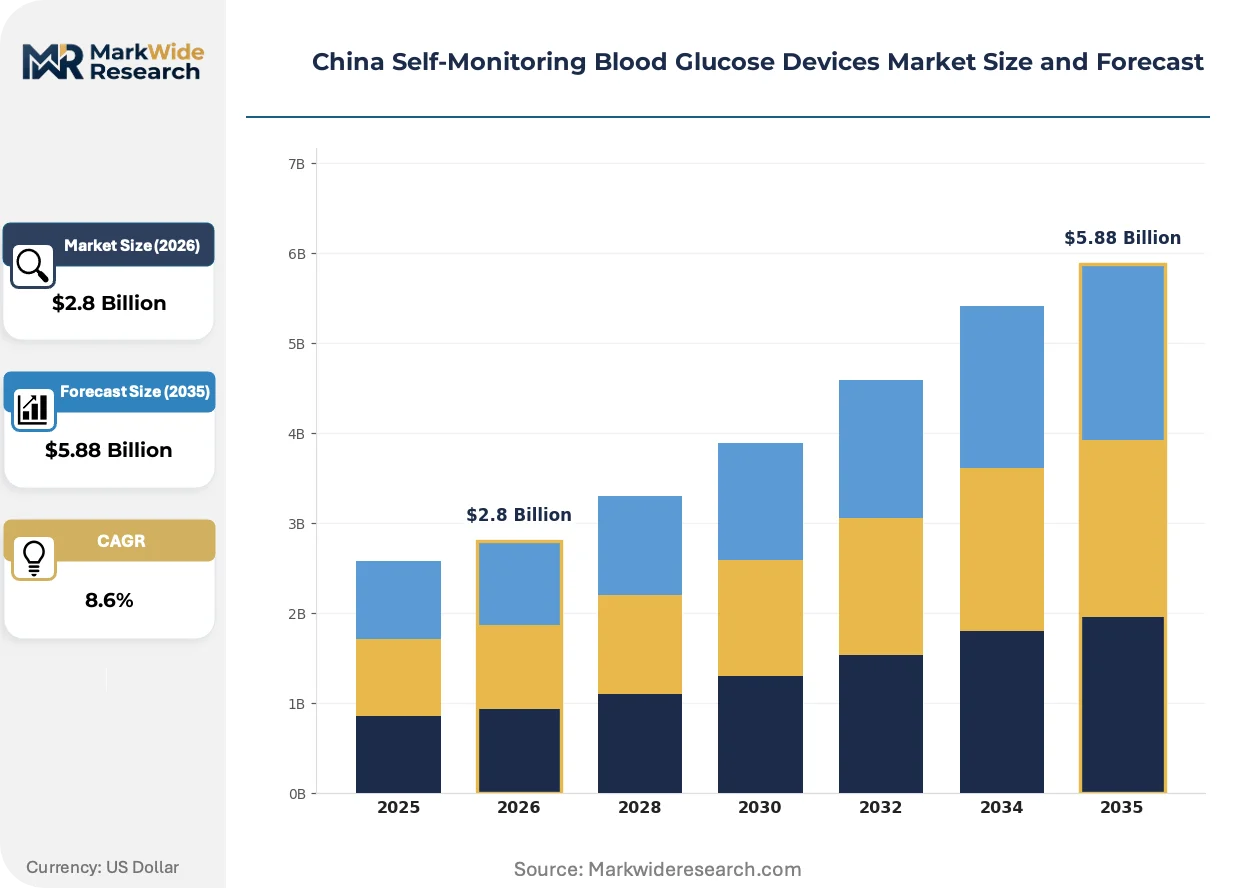
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Lancets, Test Strips Technology: Electrochemical, Optical, Thermal, Dual-Function End User: Diabetes Patients, Healthcare Professionals, Clinics, Pharmacies Distribution Channel: Online Retail, Hospitals, Specialty Stores, Wholesalers |
| Companies Covered | Roche, Abbott Laboratories, Sinocare, Lifescan, Arkray, Ascensia Diabetes Care, PHC Holdings Corp, Bionime, Tianjin Andon Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Digital health convergence and miniaturization engineering are reconfiguring how glucose data flows between patients, caregivers, and clinical decision-makers across China's urban healthcare networks.
Continuous glucose monitoring technology is migrating from discrete fingerstick testing toward real-time trend-based glycemic management. Type 1 diabetes patients in Beijing and Shanghai tertiary hospitals are adopting patch-based sensors at accelerating rates. This shift is compressing traditional electrochemical test strip volumes while expanding subscription revenue models for sensor replacement cycles.
NMPA's updated medical device classification rules and GB standards for in-vitro diagnostic performance establish mandatory accuracy thresholds that filter lower-quality imports from hospital procurement lists. These regulations force manufacturers to invest in enhanced calibration protocols and clinical validation studies. Imported systems face extended registration timelines while domestic producers with established quality management systems capture accelerated approval benefits.
Urban elderly households are consolidating glucose monitoring purchases through pharmacy network membership programs that bundle device subsidies with ongoing test strip subscriptions. Hospital-at-home initiatives in Beijing and Shanghai are displacing traditional clinic-based testing with remote monitoring protocols. This behavioral shift concentrates demand among retail chains with integrated telemedicine capabilities and compresses margins for standalone device vendors lacking service infrastructure.
China Self-Monitoring Blood Glucose Devices Market Segmentation
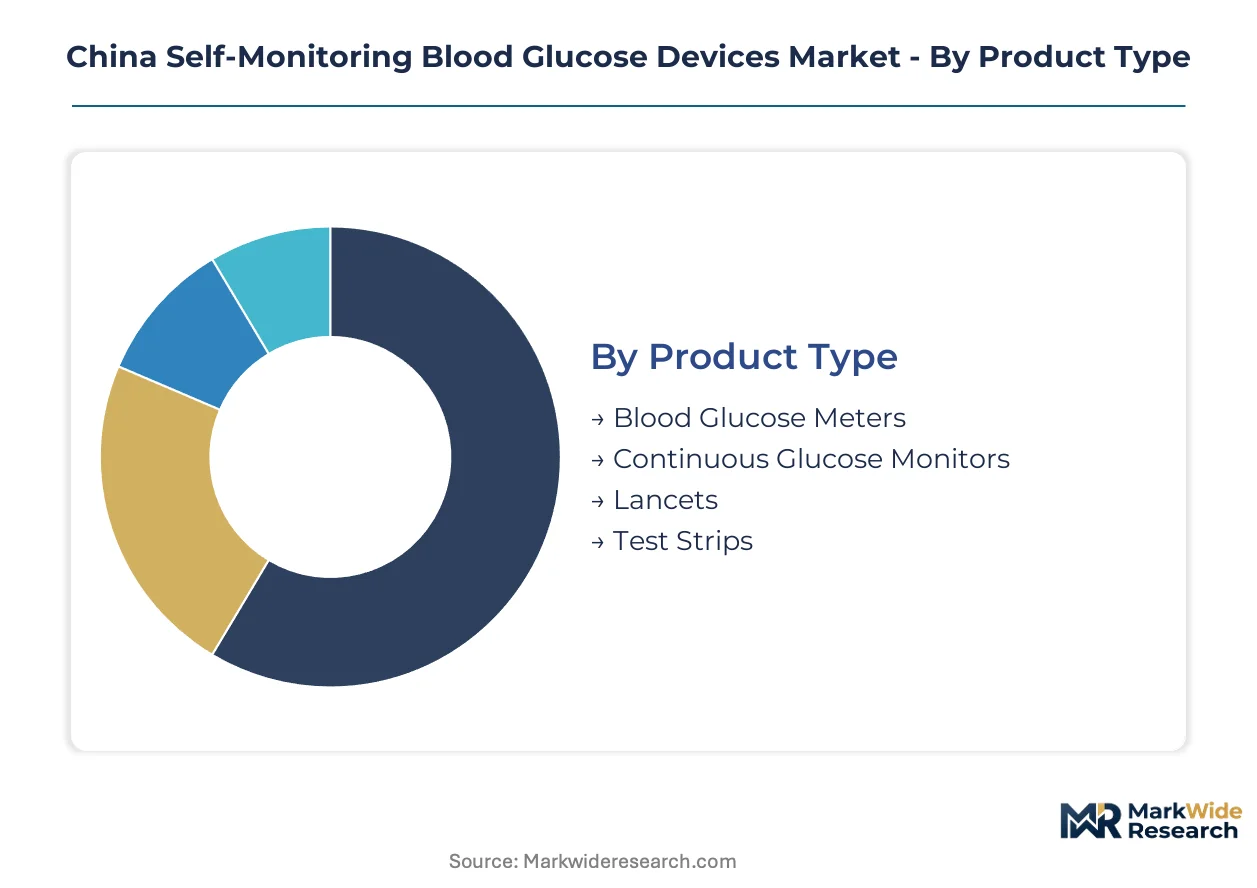
Segmentation reveals distinct consumption rhythms across China's glucose monitoring ecosystem. Test strips and lancets turn over rapidly through recurring purchases, while meters and continuous monitors operate on extended replacement cycles that reshape manufacturer revenue models.
Product Type:
Replacement frequency varies dramatically across product categories, with consumables cycling monthly versus capital equipment lasting years.
- Test Strips:Enzyme-impregnated electrochemical strips requiring sub-microliter blood samples and five-second readout times. Shanghai and Beijing hospital-at-home programs are consolidating procurement through pharmacy network subscriptions that bundle strip resupply with remote monitoring services.
- Continuous Glucose Monitors:Patch-based sensors transmitting real-time glucose trends to smartphone applications via Bluetooth protocols. Pediatric Type 1 diabetes clusters in Beijing tertiary hospitals are adopting these systems fastest as physicians prioritize glycemic pattern recognition over discrete readings.
- Blood Glucose Meters:Portable electrochemical analyzers with digital displays and memory storage for historical readings.
- Lancets:Single-use spring-loaded puncture devices for capillary blood sampling with adjustable depth settings.
Test strips anchor the volume base while continuous glucose monitors gain share at the steepest rate.
Technology:
Cost tiers separate mature domestic production from premium imported platforms, with reimbursement policies favoring standardized electrochemical formats.
- Electrochemical:Glucose oxidase-mediated electron transfer systems with ferricyanide or ferrocene mediators. Domestic supply chains in Jiangsu, Zhejiang, and Guangdong provinces dominate electrode fabrication, though NMPA's updated GB standards are filtering subscale producers from hospital procurement lists.
- Dual-Function:Integrated glucose-ketone measurement platforms using shared electrochemical cells with algorithmic analyte discrimination. Tertiary hospital networks report accelerating demand among insulin-dependent patients requiring simultaneous metabolic monitoring during sick-day protocols.
- Optical:Colorimetric or photometric detection systems measuring glucose concentration through light absorption changes.
- Thermal:Calorimetric biosensors detecting heat generation from enzymatic glucose oxidation reactions.
Electrochemical technology captures the dominant procurement volume while dual-function platforms are climbing the fastest among specialized patient populations.
End User:
Customer type determines purchasing authority, with institutional buyers negotiating centralized contracts versus individual patients selecting retail-accessible options.
- Diabetes Patients:Individual consumers managing Type 1, Type 2, or gestational diabetes through self-directed testing protocols. Urban elderly households in Shanghai are consolidating purchases through pharmacy membership programs that subsidize device costs against ongoing consumable commitments.
- Healthcare Professionals:Physicians, nurses, and diabetes educators incorporating patient-generated glucose data into treatment decisions. Hospital-at-home program expansion is rerouting their procurement influence toward remote monitoring platforms with direct EHR integration.
- Clinics:Community health centers and primary care facilities conducting point-of-care glucose screening.
- Pharmacies:Retail dispensaries serving as distribution nodes for prescription and over-the-counter glucose monitoring supplies.
Individual diabetes patients drive the installed base volume while healthcare professionals are gaining purchasing influence fastest through protocol standardization.
Distribution Channel:
Geographic concentration of demand shapes channel effectiveness, with urban density favoring direct-to-patient models over traditional wholesale networks.
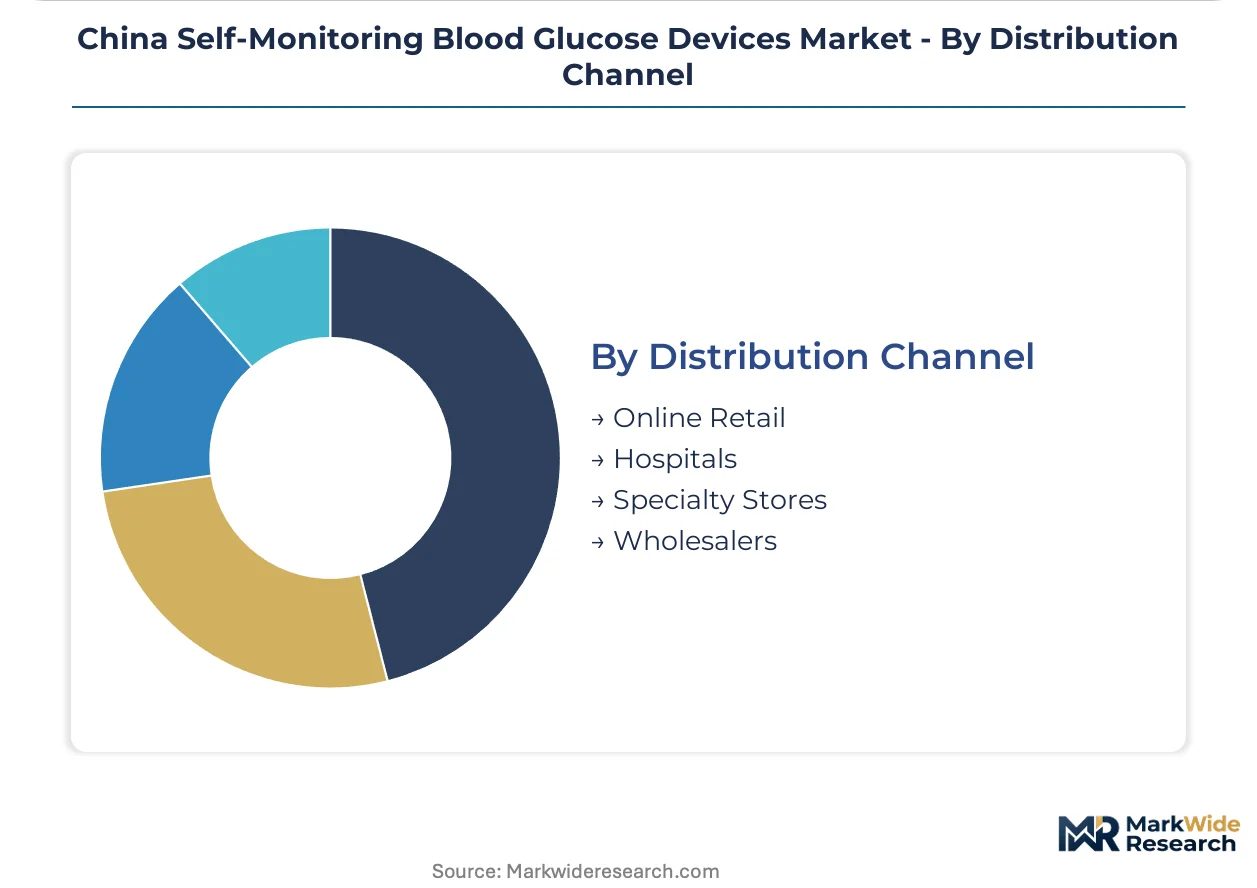
- Online Retail:E-commerce platforms and brand-direct websites offering subscription-based strip resupply and device replacement programs. Tier-two city penetration in Chengdu, Xi'an, and Wuhan is accelerating as logistics networks mature and telemedicine integration improves.
- Hospitals:Tertiary care procurement departments controlling formulary inclusion for inpatient and outpatient glucose monitoring. NMPA's streamlined approval pathways for connected devices are shortening the gap between regulatory clearance and hospital contract execution.
- Specialty Stores:Dedicated medical device retailers providing calibration services and hands-on product training.
- Wholesalers:Regional distributors aggregating inventory for downstream pharmacy and clinic fulfillment.
Hospital procurement anchors the premium segment volume while online retail is expanding most quickly into underpenetrated urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Chinese provinces, with coastal urban centers accepting premium connected devices while inland markets prioritize low-cost electrochemical strips. Hospital-at-home program density determines reimbursement leverage and procurement channel selection.
Shanghai
Pharmacy network consolidation drives device subsidy programs for elderly households managing Type 2 diabetes through remote monitoring protocols. NMPA's streamlined approval pathways accelerate hospital formulary inclusion for Bluetooth-enabled meters. Pudong and Minhang districts concentrate tertiary hospital procurement contracts for continuous glucose monitors.
Beijing
Pediatric Type 1 diabetes clusters in Chaoyang and Haidian districts generate concentrated demand for dual-function glucose-ketone platforms. MIIT interoperability standards mandate seamless data transmission between patient devices and physician dashboards. Hospital-at-home initiatives in municipal health networks displace traditional outpatient testing volumes.
Guangdong Province
Pearl River Delta manufacturing clusters supply enzyme electrode components to domestic test strip producers facing stricter MEE waste protocols under dual carbon goals. Shenzhen and Guangzhou urban households adopt subscription-based continuous monitor models fastest. Provincial environmental regulators enforce cleanroom facility upgrades that improve manufacturing yields.
Sichuan-Chongqing
Underpenetrated pharmacy infrastructure in Chengdu and Chongqing creates first-mover opportunities for localized calibration services and device distribution. Tier-two city reimbursement policies favor standardized electrochemical formats over premium imported systems. Western China logistics networks mature to support direct-to-patient strip resupply programs.
Jiangsu Province
Nanjing and Suzhou industrial parks host concentrated glucose oxidase and mediator chemical suppliers serving domestic electrode fabrication. NMPA's updated GB standards filter subscale producers from hospital procurement lists. Provincial supply chain concentration exposes manufacturers to regional logistics disruption risks from Yangtze River shipping constraints.
China Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Capability concentration sits with multinational specialists controlling hospital channel relationships and integrated data platforms; scale advantage sits with domestic manufacturers leveraging coastal province supply chains for electrochemical test strip production. The market structures around three archetypes: premium-tier connected device specialists, high-volume strip producers, and emerging dual-function platform developers. Competitive moves center on hospital formulary capture and pharmacy network membership program expansion.
Within the multinational tier, Roche and Abbott Laboratories anchor premium positioning through tertiary hospital procurement control and specialized diabetes care protocols. Among domestic scale producers, Sinocare exemplifies the high-volume electrochemical archetype competing aggressively on price in tier-two city markets. These three companies represent the dominant competitive vectors shaping procurement influence and patient access pathways across China's urban healthcare networks.
| Leading Market Players |
|---|
| Roche |
| Abbott Laboratories |
| Sinocare |
| Lifescan |
| Arkray |
| Ascensia Diabetes Care |
| PHC Holdings Corp |
| Bionime |
| Tianjin Andon Health |
| Others |
Pricing and Supply Chain Analysis
Glucose oxidase and mediator chemical suppliers concentrated in Jiangsu, Zhejiang, and Guangdong provinces anchor cost structures for domestic test strip producers, directing margin pools toward manufacturers with captive electrode fabrication or long-term chemical offtake agreements.
Pricing Analysis
Consumable subscription tiers—test strip resupply contracts bundled with device subsidies—drive lifetime value capture across pharmacy network membership programs. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled connected meters from basic electrochemical units and hospital-procured dual-function platforms. Price differentiation hinges on NMPA certification grade and after-sales calibration service inclusion. Cost compression in the economy tier intensifies as Sinocare and domestic producers compete on volume in tier-two cities. Individual diabetes patients in Sichuan-Chongqing exhibit highest price sensitivity; tertiary hospital procurement committees in Beijing and Shanghai demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Electronics manufacturing services for glucose meter assembly concentrate in Shenzhen and Dongguan facilities, with specialized cleanroom operations for test strip production clustered in Suzhou and Wuxi industrial parks. Domestic supply draws from glucose oxidase fermentation facilities in Jiangsu, printed electrode substrates from Zhejiang, and Bluetooth module integration from Guangdong. Single-source vulnerability in enzyme electrode input concentration exposes producers to Yangtze River logistics disruptions and provincial environmental regulator enforcement actions under dual carbon goals. Distribution runs through hospital procurement departments for premium connected devices, pharmacy network subscriptions for consumable resupply, and direct-to-patient online retail for replacement meters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with tier-two city pharmacy infrastructure and AI-enabled glycemic pattern recognition, as hospital-at-home program expansion creates niches between multinational hospital channel control and domestic price competition.
For Market Incumbents: Build data platform moats through MIIT interoperability standard compliance and physician dashboard integration. Defensive moves center on locking hospital formulary positions via NMPA streamlined approval pathway exploitation for Bluetooth-enabled devices, and securing exclusive pharmacy network membership program partnerships in Shanghai and Beijing. Continuous glucose monitor substitution threat demands accelerated R&D in dual-function glucose-ketone platforms for Type 1 diabetes clusters. Vertical integration into enzyme electrode fabrication insulates against Jiangsu-Zhejiang supply concentration risks. For New Entrants and Emerging Players: Mid-market pharmacy networks in Chengdu, Xi'an, and Wuhan represent the most penetrable entry point, given underdeveloped calibration service infrastructure and reimbursement policies favoring standardized electrochemical formats. AI-driven predictive hypoglycemia alert systems for insulin-dependent patients offer white-space differentiation against legacy meter vendors lacking machine learning capabilities. Go-to-market execution should prioritize telemedicine-integrated subscription models that bundle device subsidies with ongoing strip resupply, mirroring successful Shanghai elderly household consolidation patterns. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous glucose monitor sensor manufacturing due to cleanroom facility requirements and NMPA validation study burdens. Long-term viability favors platform plays with recurring revenue models over standalone device vendors exposed to test strip volume compression. Acquisition target archetype: domestic electrochemical strip producers with established GB standards compliance and tier-two city distribution reach. Signal to watch is MIIT connected health device interoperability standard enforcement timing, which will reshape data portability requirements and consolidate winner positions.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Streamlined Approval Pathway Exploitation | Expedited review timelines for Bluetooth-enabled meters reduce regulatory lag against hospital procurement cycles. |
| Pharmacy Network Membership Program Expansion | Device subsidy bundling with consumable subscriptions locks patient lifetime value in tier-two urban markets. |
| AI Glycemic Pattern Recognition Development | Machine learning algorithms enable predictive hypoglycemia alerts that differentiate against basic meter vendors. |
| Dual-Function Glucose-Ketone Platform Launch | Integrated metabolic monitoring captures pediatric Type 1 diabetes demand in Beijing tertiary hospital networks. |
| Enzyme Electrode Fabrication Backward Integration | Captive glucose oxidase supply insulates margin structures from Jiangsu-Zhejiang logistics disruption exposure. |
Research Methodology
Cross-validation between hospital procurement database analysis and NMPA medical device registration filings anchors the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, diabetes clinic physicians, and pharmacy network procurement managers combine with secondary validation from NMPA approval records, MIIT policy circulars, GB standards documentation, and provincial environmental regulator enforcement notices. Bottom-up test strip volume modeling and top-down connected device penetration triangulation ensure segmentation consistency.
Calibration against historical NMPA approval timelines and hospital formulary inclusion patterns refines the analytical framework across the projection horizon. Segmentation dimensions modeled include product type replacement frequency, technology cost tier, end-user purchasing authority, and distribution channel geographic density. CAGRs derive from installed base expansion rates and consumable consumption per patient assumptions. Forecast inputs incorporate dual carbon goal enforcement intensity and MIIT interoperability standard adoption curves.
Macroeconomic conditions sit as an overlay; deviation in urban elderly household disposable income growth or provincial reimbursement policy generosity would shift the trajectory. Forecasts reflect assumptions around NMPA regulatory pacing and hospital-at-home program rollout velocity. Quarterly review of NMPA approval timelines, MIIT standard enforcement notices, and provincial environmental regulator cleanroom facility inspection schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
North America Insulin Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market