
 Continuous Glucose Monitoring Device Market | 2026-2036
Continuous Glucose Monitoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Glucose Monitoring Device Market Intelligence
The pool of trained endocrinology nurses and certified diabetes care specialists is collapsing across major healthcare systems, forcing device makers to engineer simpler patient-operated systems. Abbott Laboratories leverages its vertically integrated sensor manufacturing to maintain cost discipline and supply security. Dexcom, Inc. dominates the direct-to-consumer channel with aggressive pharmacy partnerships that bypass traditional durable medical equipment distributors. Medtronic plc anchors the hospital-integrated segment with closed-loop insulin delivery systems that bundle glucose monitoring with automated therapy.
A continuous glucose monitoring device comprises a subcutaneous sensor, transmitter, and receiver or smartphone application that tracks interstitial glucose levels in real time, typically measuring glucose concentration through electrochemical enzymatic reactions with a measurement lag of approximately five to fifteen minutes relative to blood glucose. Its primary purpose is to enable proactive glycemic management for insulin-dependent patients while reducing hypoglycemic events and HbA1c variability. Sensor-based devices command the largest installed base due to established reimbursement codes and proven clinical outcomes, while non-invasive devices represent the fastest-growing technology frontier despite unresolved accuracy challenges in the hypoglycemic range. Transmitter-integrated systems concentrate margin pools through recurring sensor replacement revenues that lock patients into proprietary ecosystems.
The FDA's breakthrough device program and the EU MDR's post-market surveillance requirements are reshaping clinical evidence standards, forcing manufacturers to generate real-world performance data beyond pivotal trials. Health Canada's parallel review pathway with the FDA accelerates North American market access for qualified submissions. Reimbursement authorities in Germany through the G-BA and in France through the HAS increasingly condition coverage on demonstrated HbA1c reduction and hypoglycemia prevention, not merely device availability. Stakeholders must monitor how regulatory convergence on outcomes-based criteria will filter which sensing technologies achieve sustainable payment.
Market Dynamics
The collapse of trained endocrinology nursing pools across major healthcare systems is forcing manufacturers to engineer simpler patient-operated interfaces, compressing the traditional clinical intermediary layer and accelerating direct-to-consumer channel development.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated approval track for novel glucose sensing technologies compresses time-to-market for electrochemical enzymatic platforms, rewarding innovators with earlier reimbursement eligibility.
- Home Care Migration:Patient preference for clinic-free glycemic management is pulling sensor demand toward residential settings, bypassing traditional durable medical equipment distribution channels.
- German G-BA Outcomes Mandate:Germany's Federal Joint Committee now conditions glucose monitor reimbursement on demonstrated HbA1c reduction, creating payment pull for clinically validated sensor systems.
Market Restraints
- Enzyme Biosensor Instability:Electrochemical glucose oxidase coatings degrade within 7-14 days, forcing recurring sensor replacement and locking patients into proprietary transmitter ecosystems.
- Hypoglycemic Range Accuracy Gap:Non-invasive optical sensing technologies fail to resolve glucose concentrations below 70 mg/dL, limiting their clinical utility for insulin-dependent populations.
- Interstitial Measurement Lag:The 5-15 minute delay between interstitial fluid and blood glucose readings creates therapeutic uncertainty during rapid glycemic excursions.
Strategic Opportunities
- India CDSCO Parallel Track:India's streamlined medical device registration for US FDA-cleared products opens South Asian market access without redundant clinical trials.
- Closed-Loop Insulin Convergence:Integration of real-time glucose sensing with automated insulin delivery algorithms creates bundled therapy ecosystems with higher switching costs.
- Pharmacy Channel Disintermediation:Direct pharmacy partnerships bypass durable medical equipment distributors, capturing margin pools previously fragmented across regional wholesalers.
Industry Challenges
- EU MDR Post-Market Surveillance:The European Medical Device Regulation's real-world performance data requirements extend clinical evidence generation timelines and inflate regulatory compliance costs.
- Certified Diabetes Care Specialist Shortage:The shrinking pool of credentialed educators forces manufacturers to absorb patient training responsibilities, increasing operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Glucose Monitoring Device Market |
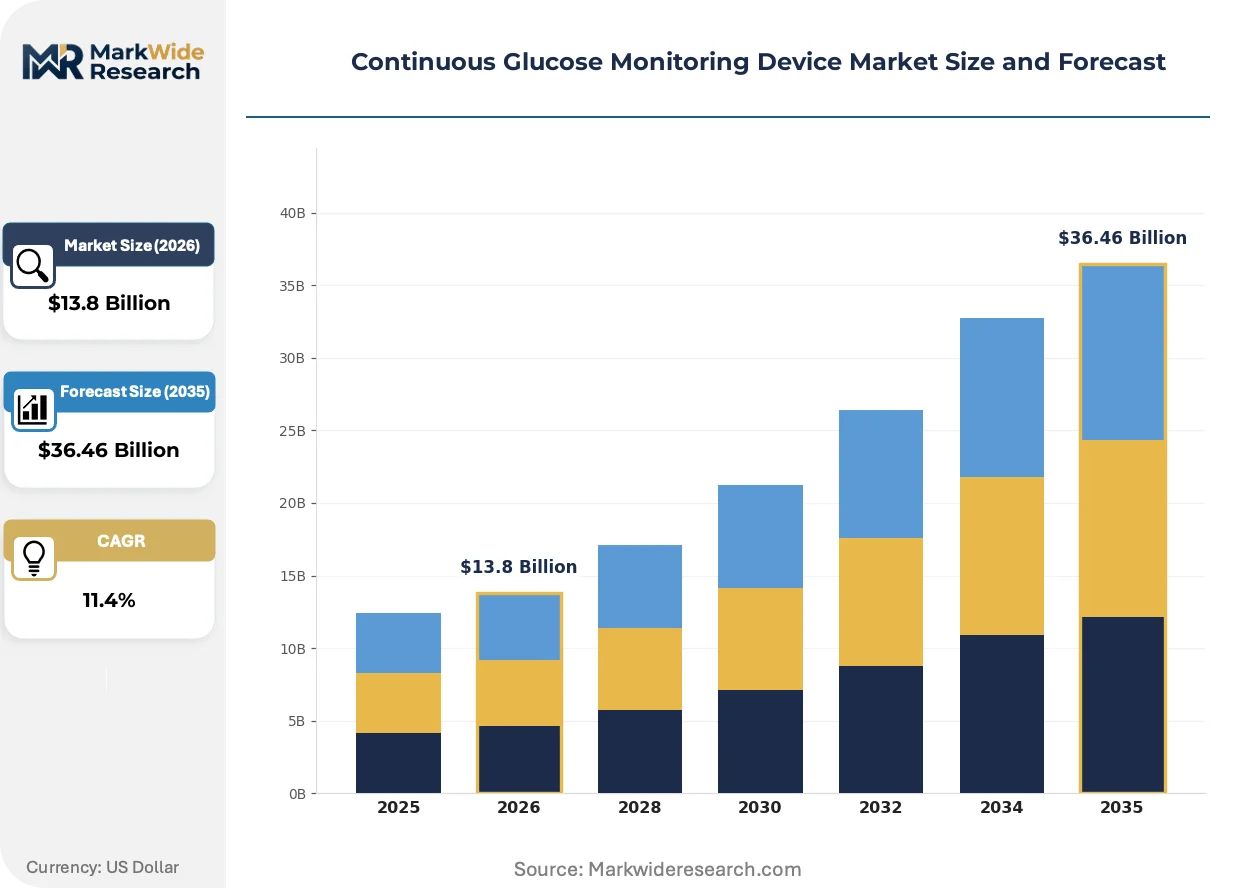
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $36.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-Based Devices, Transmitter-Integrated Systems, Non-Invasive Devices, Smart Insulin Pens End User: Diabetic Patients, Healthcare Providers, Research Institutions, Home Care Technology: Electrochemical Sensing, Optical Sensing, Microdialysis, Continuous Glucose Sensor Distribution Channel: Pharmacies, Online Retailers, Hospitals, Medical Supply Stores |
| Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic plc, F. Hoffmann-La Roche Ltd., Senseonics Holdings, Inc., Ascensia Diabetes Care Holdings, Sinocare, Inc., i-SENS, Inc., Zhejiang POCTech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Glucose Monitoring Device Market Strategic Shifts & Innovations
Sensor miniaturization and algorithmic glucose prediction are compressing the functional boundary between professional-grade and consumer-accessible monitoring, while regulatory frameworks increasingly reward demonstrated clinical outcomes over device availability alone.
Electrochemical enzymatic sensing is bifurcating into two performance tiers: extended-wear factory-calibrated sensors targeting pharmacy-direct consumers, and hospital-calibrated systems with predictive hypoglycemia alerts for intensive insulin users. Type 1 diabetes patients and their caregivers are adopting the former at accelerating rates, while endocrinology practices retain the latter for complex cases. This split is compressing the addressable market for mid-tier systems that lack either convenience or clinical depth.
France's HAS and Germany's G-BA are converging on outcomes-based reimbursement criteria that condition glucose monitor coverage on verified HbA1c reduction and severe hypoglycemia prevention. Industrial consequence: manufacturers must now generate real-world evidence beyond pivotal trials, extending post-market study obligations. Sensor-integrated insulin delivery systems face the steepest evidence burden, as automated therapy algorithms require longitudinal safety validation.
Patients are unbundling glucose data from clinical oversight, transmitting continuous readings directly to smartphone applications and cloud platforms without routine endocrinologist review. This behavior disrupts the traditional durable medical equipment channel, where physician prescription and distributor fulfillment created multi-week access delays. The United States exhibits the most pronounced channel compression, as major pharmacy chains deploy same-day sensor pickup and remote onboarding support.
Continuous Glucose Monitoring Device Market Segmentation
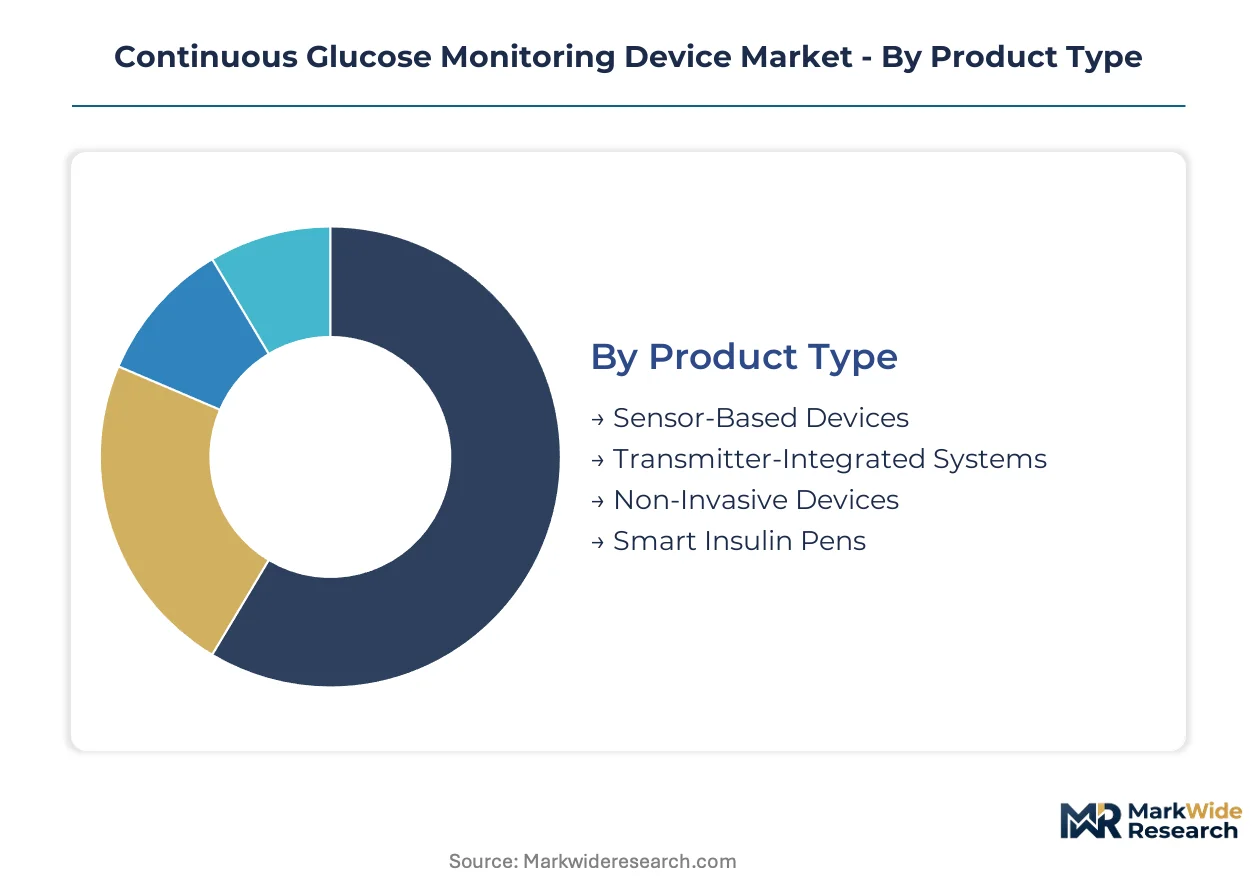
Segmentation in the continuous glucose monitoring device market reveals how reimbursement pathways and patient self-management preferences are fragmenting demand across technical performance tiers. Manufacturers must align product architectures with specific regulatory clearance levels and distribution economics to capture sustainable margin pools.
Product Type:
FDA breakthrough device designation and EU MDR conformity assessment create divergent commercialization timelines across hardware configurations.
- Sensor-Based Devices:Subcutaneous electrochemical sensors with 7-14 day wear periods constitute the dominant installed base. German G-BA reimbursement mandates for HbA1c reduction concentrate demand here among Type 1 diabetes patients seeking pharmacy-direct access.
- Transmitter-Integrated Systems:Proprietary transmitter-receiver pairings lock patients into recurring sensor ecosystems through encrypted wireless protocols. Hospital-integrated closed-loop insulin delivery anchors demand in the United States, where bundled therapy reimbursement rewards automated glycemic control.
- Non-Invasive Devices:Optical sensing platforms target consumer wellness segments but face accuracy limitations below 70 mg/dL glucose concentrations.
- Smart Insulin Pens:Bluetooth-enabled dose logging devices bridge injection therapy with digital glycemic tracking for pen-needle patients.
Sensor-Based Devices handle the majority of throughput; Non-Invasive Devices are expanding most quickly on share despite unresolved hypoglycemic range performance.
End User:
Credential scarcity among diabetes care specialists is compressing the clinical intermediary layer and accelerating patient-directed purchasing authority.
- Diabetic Patients:Insulin-dependent individuals now initiate therapy without endocrinologist intermediation in pharmacy-direct and online channels. United States reimbursement expansion for continuous glucose monitoring enables this self-directed adoption pattern.
- Healthcare Providers:Endocrinology practices and primary care clinics prescribe hospital-calibrated systems with predictive hypoglycemia alerts for complex cases requiring intensive insulin management.
- Research Institutions:Academic medical centers generate real-world evidence for EU MDR post-market surveillance obligations and FDA breakthrough device pathway submissions.
- Home Care:Residential settings bypass traditional durable medical equipment distribution as patients seek clinic-free glycemic management with remote onboarding support.
Diabetic Patients dominate volume absorption; Home Care is climbing the fastest as channel disintermediation accelerates.
Technology:
Measurement modality determines calibration burden, wear duration, and regulatory evidence requirements for market authorization.
- Electrochemical Sensing:Glucose oxidase-coated electrodes measure interstitial fluid through enzymatic reactions with 5-15 minute lag versus blood glucose. Factory-calibrated extended-wear variants target pharmacy-direct consumers in the United States.
- Optical Sensing:Near-infrared spectroscopy and Raman scattering pursue non-invasive glucose measurement through skin transillumination. Accuracy instability in hypoglycemic ranges limits clinical adoption despite consumer wellness interest.
- Microdialysis:Continuous fluid sampling through semipermeable membranes enables reference-quality glucose measurement for intensive care settings.
- Continuous Glucose Sensor:Generic category encompassing all real-time interstitial monitoring technologies regardless of underlying transduction mechanism.
Electrochemical Sensing commands the steepest installed base; Optical Sensing is gaining share fastest on technology frontier interest.
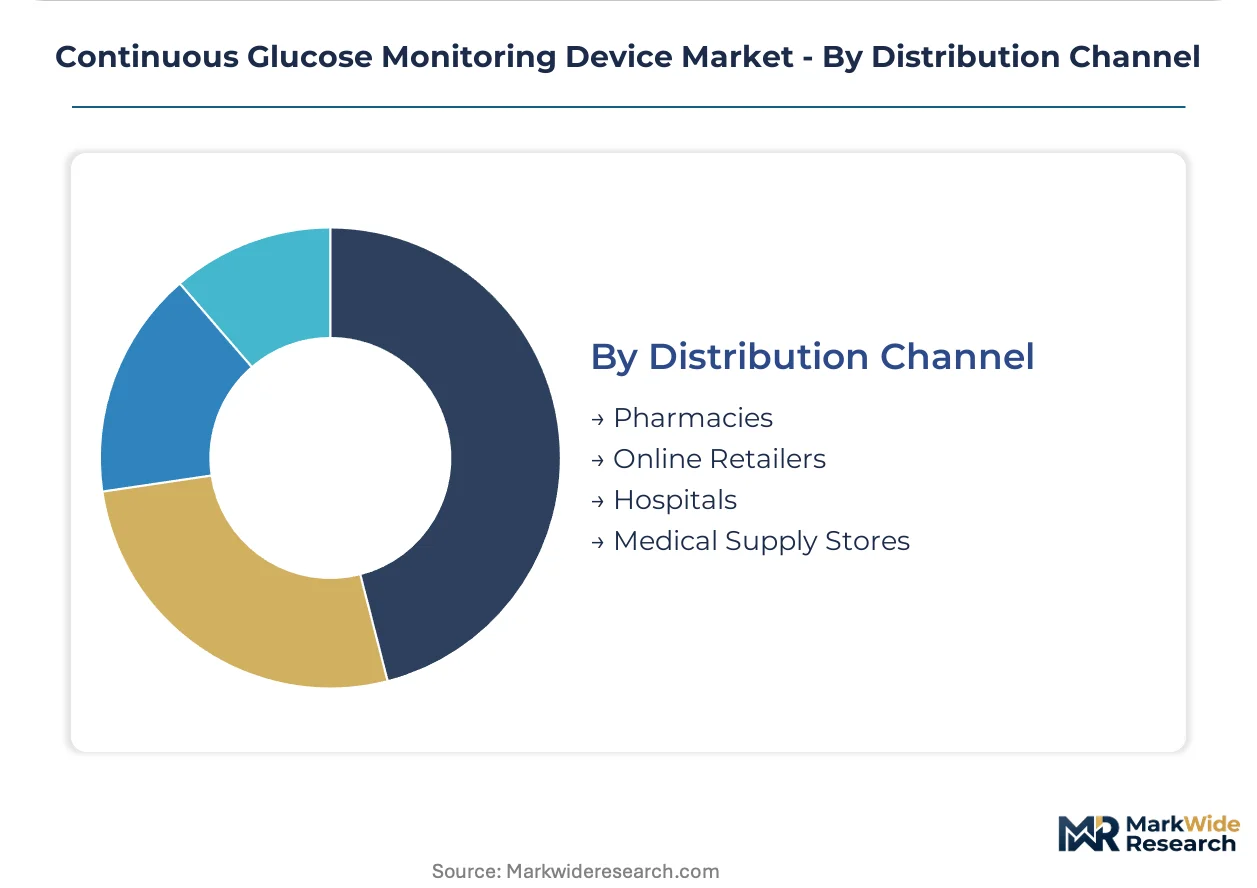
Distribution Channel:
Channel economics determine patient access speed, manufacturer margin retention, and training responsibility allocation.
- Pharmacies:Major United States pharmacy chains deploy same-day sensor pickup with remote onboarding, capturing patients previously routed through durable medical equipment distributors. Direct partnerships with manufacturers compress fulfillment timelines from weeks to hours.
- Online Retailers:E-commerce platforms enable subscription-based sensor replenishment with automated insurance prior authorization processing for recurring revenue capture.
- Hospitals:Integrated delivery networks bundle continuous glucose monitoring with closed-loop insulin systems for inpatient glycemic management and discharge planning continuity.
- Medical Supply Stores:Regional durable medical equipment distributors retain relevance for Medicare fee-for-service beneficiaries requiring face-to-face training compliance documentation.
Pharmacies absorb the dominant share of patient initiations; Online Retailers show the steepest trajectory as digital-native diabetes populations age into therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations and reimbursement expansion have concentrated demand generation in the United States, while European outcomes-based payment mandates and Asian regulatory harmonization initiatives are reshaping competitive access patterns across major markets.
United States
Pharmacy-direct distribution channels and Medicare reimbursement expansion for continuous glucose monitoring are accelerating patient-initiated adoption outside traditional durable medical equipment pathways. The FDA's breakthrough device pathway compresses approval timelines for novel electrochemical sensing platforms. Greater Boston and the San Francisco Bay Area anchor sensor algorithm development clusters where digital health startups converge with established diabetes technology infrastructure.
Germany
The Federal Joint Committee conditions glucose monitor reimbursement on verified HbA1c reduction and severe hypoglycemia prevention, filtering market access toward clinically validated systems. EU MDR post-market surveillance requirements extend evidence generation obligations for manufacturers seeking CE marking renewal. The Rhine-Ruhr metropolitan region concentrates hospital-integrated closed-loop insulin delivery deployments within Europe's densest network of academic medical centers.
India
Rising Type 1 diabetes prevalence and expanding private health insurance coverage are creating addressable demand for factory-calibrated sensor systems at price points below Western benchmarks. CDSCO's parallel review track for US FDA-cleared products eliminates redundant clinical trial requirements for qualified submissions. Maharashtra and Karnataka host emerging medical device manufacturing clusters where contract manufacturers serve both domestic distribution and export markets.
Japan
Aging demographics and government targets for diabetes complication reduction are expanding reimbursement eligibility for real-time glucose monitoring beyond intensive insulin users. PMDA's consultation pathway for combination products accommodates sensor-integrated insulin delivery system submissions. The Tokyo-Osaka corridor concentrates endocrinology specialist practices that anchor hospital-calibrated system prescribing patterns.
United Kingdom
NICE technology appraisals and NHS England commissioning policies are standardizing access criteria for continuous glucose monitoring across integrated care systems. MHRA recognition of FDA and Health Canada approvals accelerates market entry for previously authorized devices. The Oxford-Cambridge-London arc anchors digital health validation studies generating real-world evidence for EU MDR compliance.
Continuous Glucose Monitoring Device Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the former controlling captive sensor manufacturing and the latter concentrating on algorithm development or regional distribution. The market structure rewards backward integration into electrochemical sensor production and penalizes pure-play software entrants lacking hardware anchoring. Three archetypes dominate: vertically integrated multinationals with factory-calibrated sensor platforms; hospital-system specialists bundling glucose monitoring with automated insulin delivery; and regional champions serving price-sensitive markets through simplified device configurations. Competitive moves concentrate on pharmacy channel partnerships that disintermediate durable medical equipment distributors, and on closed-loop convergence strategies that raise patient switching costs through therapy ecosystem integration.
Among the integrated multinational tier, Abbott Laboratories, Dexcom, Inc., and Medtronic plc exemplify divergent strategic positioning. Abbott Laboratories anchors the pharmacy-direct consumer segment through vertically integrated sensor manufacturing. Dexcom, Inc. occupies a position emphasizing algorithmic glucose prediction and aggressive pharmacy partnership expansion. Medtronic plc represents the hospital-integrated therapy bundle archetype, anchoring automated insulin delivery system deployments. These three entities collectively illustrate how control over sensor production, algorithm development, or therapy integration determines margin retention and patient lock-in mechanics.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom, Inc. |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd. |
| Senseonics Holdings, Inc. |
| Ascensia Diabetes Care Holdings |
| Sinocare, Inc. |
| i-SENS, Inc. |
| Zhejiang POCTech Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Fourteen-day sensor inventory cycles at major pharmacy chains concentrate purchasing power among three vertically integrated manufacturers, compressing margin pools for contract manufacturers while rewarding backward integration into glucose oxidase coating production. This inventory-to-pricing linkage intensifies as factory-calibrated sensors displace hospital-calibrated systems in direct-to-consumer channels.
Pricing Analysis
United States pharmacy-direct pricing runs 15-25% below durable medical equipment channel equivalents for identical sensor SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by calibration burden and predictive algorithm sophistication. Pricing pressure stems from Medicare reimbursement compression and pharmacy chain generic substitution policies. Uninsured cash-pay patients exhibit highest price sensitivity; hospital-integrated closed-loop bundles show lowest.
Supply Chain Analysis
Just-in-time sensor replenishment dominates pharmacy-direct channels, while hospital systems maintain 30-45 day strategic stockpiles of transmitter-integrated systems for inpatient glycemic management. Manufacturing concentrates in the United States, Ireland, and Malaysia for electrochemical sensor substrates; transmitter assembly clusters in Mexico and China. Supply chain risk centers on single-source glucose oxidase enzyme suppliers facing regulatory inspection backlogs. Distribution runs through pharmacy chains, online subscription platforms, and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring sits in early-cycle expansion as Type 1 diabetes patients initiate therapy without endocrinologist intermediation, compressing traditional clinical gatekeeper functions and accelerating pharmacy-direct volume absorption.
For Market Incumbents: Fortify sensor manufacturing capacity in Malaysia and Mexico to offset enzyme supplier concentration risk. Deepen backward integration into glucose oxidase coating production to defend margin position against contract manufacturer price erosion. Prioritize pharmacy chain exclusive distribution agreements that lock out emerging optical sensing entrants before hypoglycemic range accuracy gaps resolve.
For New Entrants and Emerging Players: Lead with non-invasive optical platforms targeting Indian and Southeast Asian price-sensitive segments where factory-calibrated electrochemical sensors remain unaffordable. Exploit CDSCO parallel review track for US FDA-cleared products to bypass redundant clinical trials. Pursue wellness-positioned consumer channels rather than clinical reimbursement pathways.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across algorithm development sub-segments as cloud-based glucose prediction platforms reduce hardware-dependent R&D requirements. Five-to-ten year viability favors acquirers of sensor-integrated insulin delivery software stacks rather than pure-play hardware manufacturers. Monitor FDA breakthrough device designation velocity as inflection indicator for competitive access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Disintermediation | Direct partnerships with CVS and Walgreens bypass durable medical equipment distributors, capturing margin pools. |
| Closed-Loop Insulin Convergence | Sensor-integrated automated delivery systems create bundled therapy ecosystems with elevated patient switching costs. |
| FDA Breakthrough Device Pathway | Accelerated approval track compresses time-to-market for electrochemical enzymatic platforms and earlier reimbursement. |
| EU MDR Post-Market Surveillance | Real-world performance data requirements extend evidence generation timelines and inflate regulatory compliance costs. |
| India CDSCO Parallel Track | Streamlined registration for US FDA-cleared products opens South Asian market access without redundant trials. |
Research Approach
The analysis maps sensor-based devices, transmitter-integrated systems, non-invasive optical platforms, and smart insulin pens, each validated through endocrinology practice administrators, pharmacy chain procurement directors, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up sensor shipment estimates triangulated against top-down diabetes prevalence and therapy penetration models.
Consistency checks validated volume and value outputs against pharmacy channel sell-through data and durable medical equipment distributor inventory reports across the projection horizon. Segmentation dimensions modeled include product hardware configuration, end-user clinical setting, measurement technology modality, and distribution channel structure. CAGRs derived from longitudinal reimbursement expansion trajectories and patient-initiated adoption curve analysis, incorporating HbA1c reduction outcome data from German G-BA and French HAS assessments.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough designation velocity assumptions or EU MDR implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding diabetes prevalence trajectories, reimbursement policy continuity, and enzyme biosensor wear duration improvements. Revision becomes warranted when hypoglycemic range accuracy in non-invasive optical platforms crosses clinical utility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Vietnam Diabetes Care Devices Market