
 Tray Dryers Market | 2026-2036
Tray Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Dryers Market Analysis
India's pharmaceutical manufacturing belt is narrowing the gap between installed drying capacity and export-quality output requirements. GEA Group leverages its European engineering base to supply validated cGMP tray dryer systems for sterile API production. Hosokawa Micron specializes in precision vacuum drying technology for heat-sensitive compounds, while Bühler Group anchors its position in food-grade dehydration with hygienic design certifications.
Tray dryers are enclosed cabinet systems that use heated air or vacuum conditions to remove moisture from solids, slurries, or pastes spread across multiple stacked trays, typically operating between 40°C and 150°C depending on product thermal sensitivity. Their primary industrial purpose is batch-wise moisture reduction for heat-labile materials where uniform drying and minimal product degradation are critical. Vacuum tray dryers command premium positioning in pharmaceutical end use due to stringent moisture-content specifications for active pharmaceutical ingredients. Electric-heated units dominate the installed base across laboratory and small-batch chemical processing, while hybrid conduction-convection systems represent the fastest-growing technology segment as processors seek energy efficiency without sacrificing throughput uniformity.
FDA cGMP guidelines and EMA Annex 15 validation requirements shape equipment qualification protocols, compelling manufacturers to invest in documented cleanability and batch reproducibility. India's CDSCO enforces Schedule M compliance for domestic pharmaceutical manufacturing, directly driving tray dryer replacement cycles in facilities across Ahmedabad, Hyderabad, and Mumbai. REACH chemical safety standards in Europe restrict solvent recovery system designs, altering material selection for dryer construction. Stakeholders must monitor evolving energy efficiency mandates and regional sterilization standards to align capital deployment with regulatory trajectory.
Market Dynamics
Vacuum tray technology is displacing conventional convection systems as pharmaceutical manufacturers face tightening moisture-content specifications for active pharmaceutical ingredients, forcing capital redeployment toward validated cGMP equipment with documented batch reproducibility.
Growth Catalysts
- EMA Annex 15 validation requirements:European pharmaceutical manufacturers are expanding batch-processing capacity to meet sterilization standards, directly driving equipment replacement cycles in Germany and Switzerland.
- API manufacturing corridor concentration:India's CDSCO Schedule M mandates are compelling facility upgrades across Gujarat and Maharashtra, narrowing the gap between installed drying capacity and export-quality output requirements.
- Hybrid conduction-convection systems:Processors seeking energy efficiency without sacrificing throughput uniformity are accelerating adoption of this fastest-growing technology segment in chemical and food-grade applications.
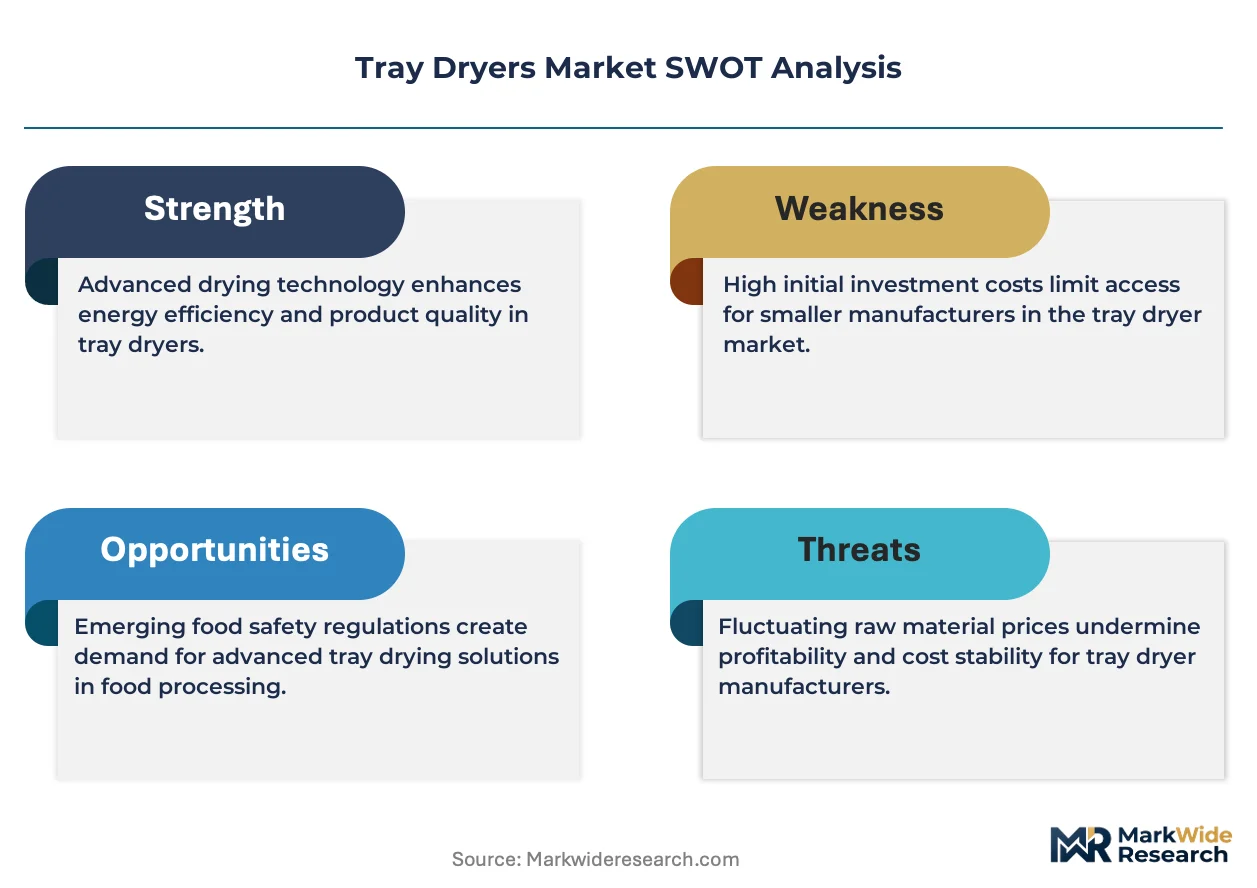
Market Restraints
- Stainless steel input volatility:Material selection for dryer construction faces cost pressure from alloy price swings, particularly affecting vacuum-rated vessel fabrication.
- REACH chemical safety standards:European solvent recovery system designs face restricted material options, adding engineering complexity and qualification timeline risk.
- Freeze-drying substitution:Biologics manufacturers increasingly specify lyophilization for ultra-heat-sensitive compounds, ceding some high-value pharmaceutical applications to alternative drying technologies.
Strategic Opportunities
- CDSCO-driven equipment upgrades:India's domestic pharmaceutical manufacturing compliance deadlines create immediate replacement demand in underpenetrated secondary cities beyond Ahmedabad, Hyderabad, and Mumbai.
- EU Green Deal energy efficiency mandates:European processors face capital incentives to retrofit existing convection systems with heat-recovery hybrid configurations.
- IoT-enabled predictive maintenance convergence:Integration of sensor networks with vacuum tray controls opens service revenue streams and remote qualification support for distributed pharmaceutical operations.
Industry Challenges
- cGMP validation documentation:Pharmaceutical buyers demand exhaustive installation qualification and operational qualification protocols, extending sales-to-revenue cycles and requiring specialized field engineering teams.
- Legacy system integration:Brownfield chemical facilities struggle to interface modern vacuum tray controls with existing distributed control systems, complicating retrofit project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Dryers Market |
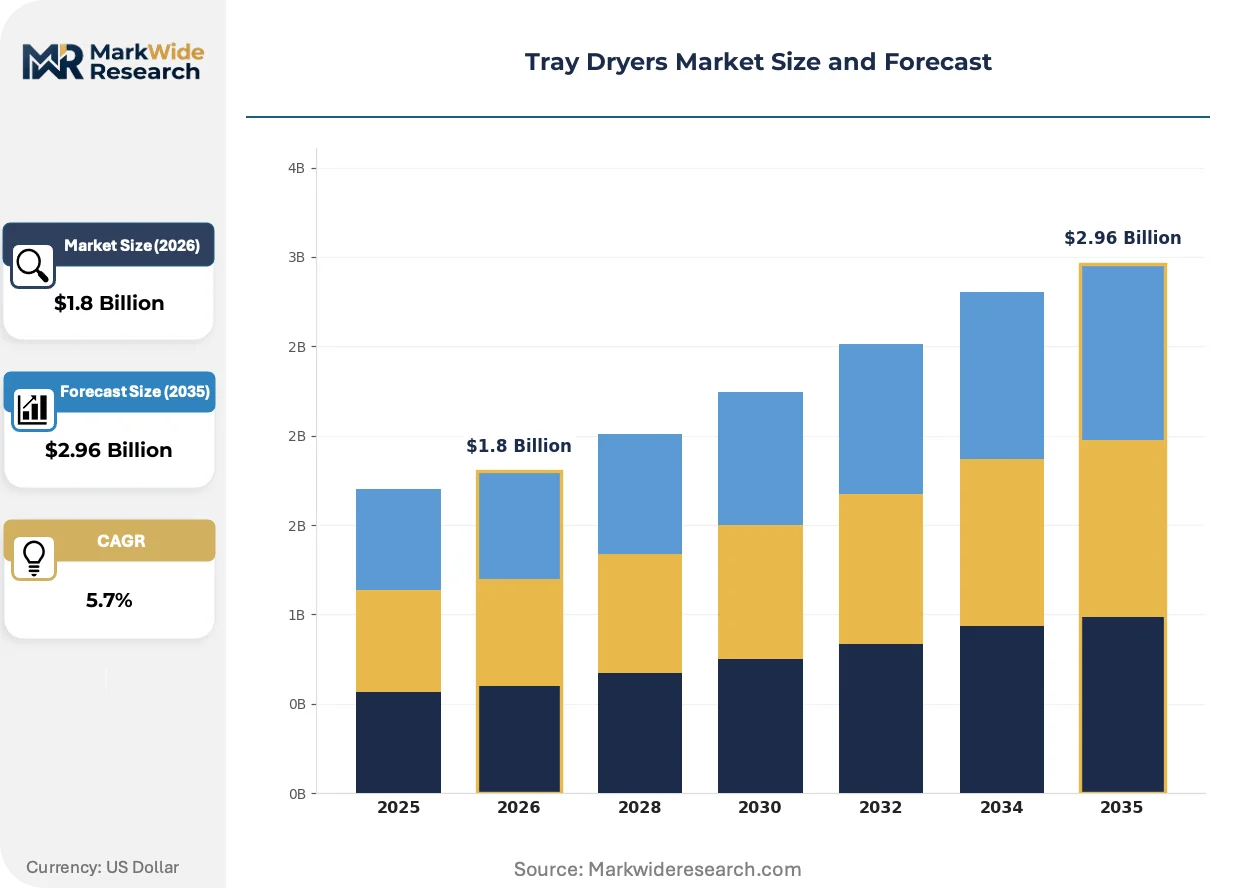
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tray Dryers, Gas Tray Dryers, Vacuum Tray Dryers, Solar Tray Dryers End User: Food Processing, Pharmaceutical, Chemical, Laboratory Capacity: Small, Medium, Large, Extra Large Technology: Conduction, Convection, Radiation, Hybrid |
| Companies Covered | GEA Group, Hosokawa Micron, Bühler Group, SPX FLOW, GMP Engineering, SSP Pvt. Ltd., Rico Scientific, Yamato Scientific, Pope Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Dryers Market Emerging Trajectories
Digital instrumentation and closed-loop control architectures are transforming tray dryer performance from empirical batch art to reproducible science, compressing qualification timelines and enabling remote regulatory audit readiness.
Smart sensor arrays embedded in vacuum tray systems are digitizing moisture-content monitoring in real time, replacing manual sample extraction and laboratory analysis. Pharmaceutical manufacturers in Switzerland and Germany are deploying these configurations to satisfy EMA data integrity requirements. The technology is digitizing batch record generation, eliminating transcription errors and accelerating regulatory submission preparation.
REACH chemical safety standards in Europe are restricting solvent recovery system designs, compelling manufacturers to engineer alternative condensation and absorption architectures. Industrial consequence includes extended material qualification timelines for wetted parts in pharmaceutical applications. Vacuum tray dryers handling organic solvent slurries are most affected, with equipment suppliers responding by pre-certifying construction materials against ECHA substance restrictions.
Certification-driven preference shifts are compressing buyer evaluation cycles as pharmaceutical procurement teams prioritize pre-validated equipment configurations over custom-engineered systems. End-users in India's CDSCO-regulated corridor are migrating toward turnkey qualification packages that bundle installation, commissioning, and documentation. This pattern is most visible in Maharashtra, where Mumbai-based manufacturers face compressed project timelines to meet export contract deadlines.
Tray Dryers Market Segmentation
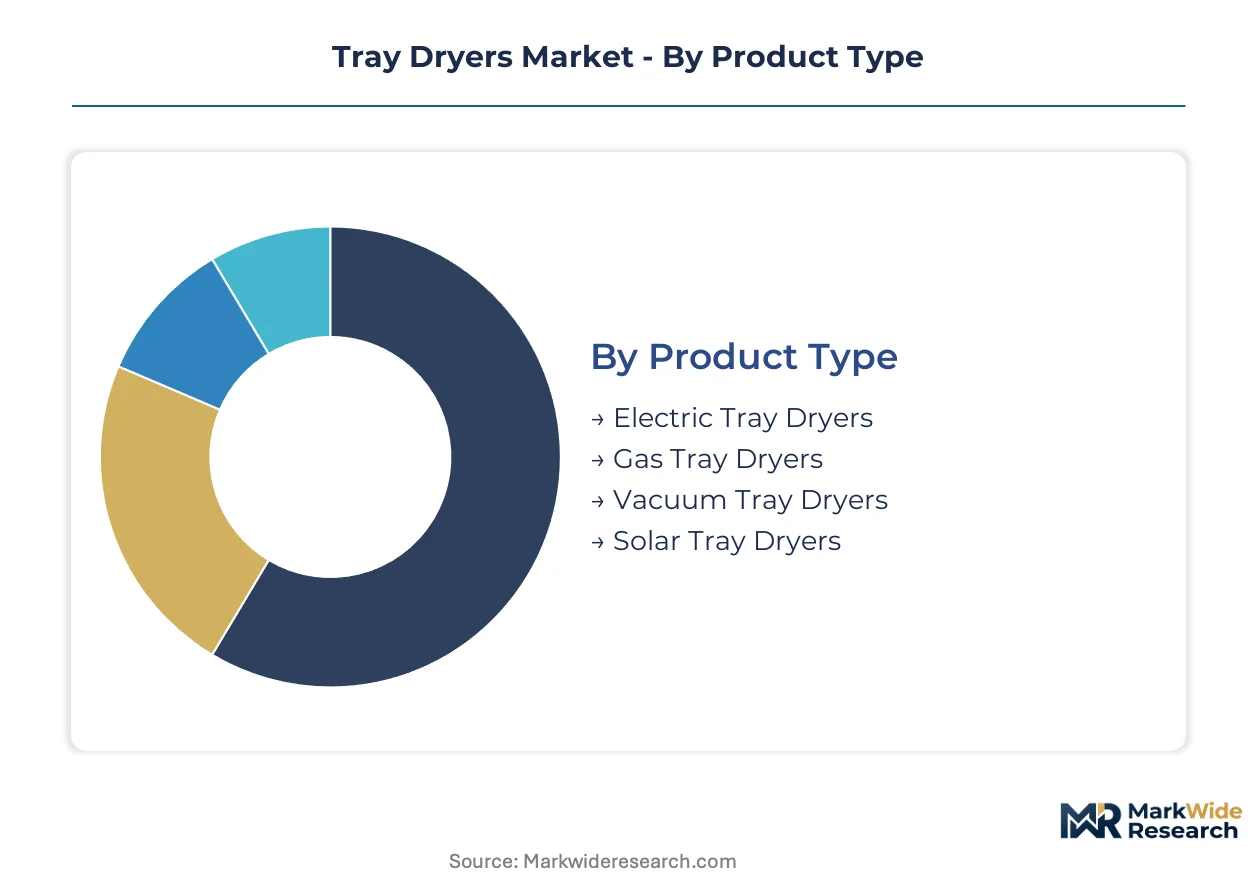
Tray dryer procurement decisions pivot on thermal sensitivity of processed materials, batch scale requirements, and regulatory validation burdens. Equipment specification varies sharply across pharmaceutical sterile API production versus food-grade dehydration, driving divergent technology preferences and price positioning.
Product Type:
Use-case spectrum spans laboratory-scale electric units through industrial vacuum systems handling solvent-laden pharmaceutical slurries.
- Vacuum Tray Dryers:Sealed vessel designs operating under reduced pressure enable moisture removal below 60°C for heat-labile active pharmaceutical ingredients. Swissmedic and EMA validation protocols concentrate demand in Basel and Stuttgart pharmaceutical clusters, where batch documentation requirements command premium equipment pricing.
- Electric Tray Dryers:Resistance-heated cabinets dominate laboratory and small-batch chemical processing with precise temperature control between 40°C and 150°C. India's CDSCO Schedule M compliance deadlines in Gujarat and Maharashtra are accelerating replacement cycles for validated electric systems in domestic API manufacturing.
- Gas Tray Dryers:Direct-fired natural gas configurations serve high-throughput food dehydration where thermal efficiency outweighs precise temperature uniformity.
- Solar Tray Dryers:Passive or active solar-thermal designs address off-grid agricultural processing in rural India and sub-Saharan Africa, constrained by weather dependency and extended drying cycles.
The dominant share belongs to Electric Tray Dryers, while Vacuum Tray Dryers are closing the gap fastest.
End User:
Customer type determines validation depth, material of construction specifications, and service intensity.
- Pharmaceutical:cGMP-compliant systems with documented IQ/OQ protocols handle sterile API and intermediate drying under FDA and EMA oversight. Maharashtra and Gujarat facilities face compressed timelines to meet export contract sterilization standards.
- Food Processing:Hygienic design certifications and sanitary stainless steel construction dominate dehydration of heat-sensitive nutritional ingredients and prepared foods.
- Chemical:Solvent recovery integration and explosion-proofing specifications address organic slurry processing under REACH material restrictions.
- Laboratory:Compact electric units with programmable temperature profiling support R&D scale-up and quality control sample preparation.
Pharmaceutical end users command the highest equipment margins, though Food Processing represents the largest installed base volume.
Capacity:
Scale segmentation reflects batch economics versus continuous processing tradeoffs across facility investment cycles.
- Large:Multi-chamber systems exceeding 500 tray capacity serve commercial pharmaceutical manufacturing and industrial chemical production. Germany's EMA Annex 15 expansion projects favor large validated configurations for economies of scale in batch sterilization.
- Medium:100-500 tray configurations balance throughput flexibility with qualification burden for mid-scale API and specialty chemical production.
- Small:Under 100 tray units dominate pilot-scale pharmaceutical development and contract manufacturing organizations seeking multi-product flexibility.
- Extra Large:Custom-engineered systems exceed standard catalog offerings for integrated continuous manufacturing lines, requiring extended engineering and qualification timelines.
Medium capacity holds the largest revenue share, though Large systems are expanding most quickly in European pharmaceutical capacity additions.
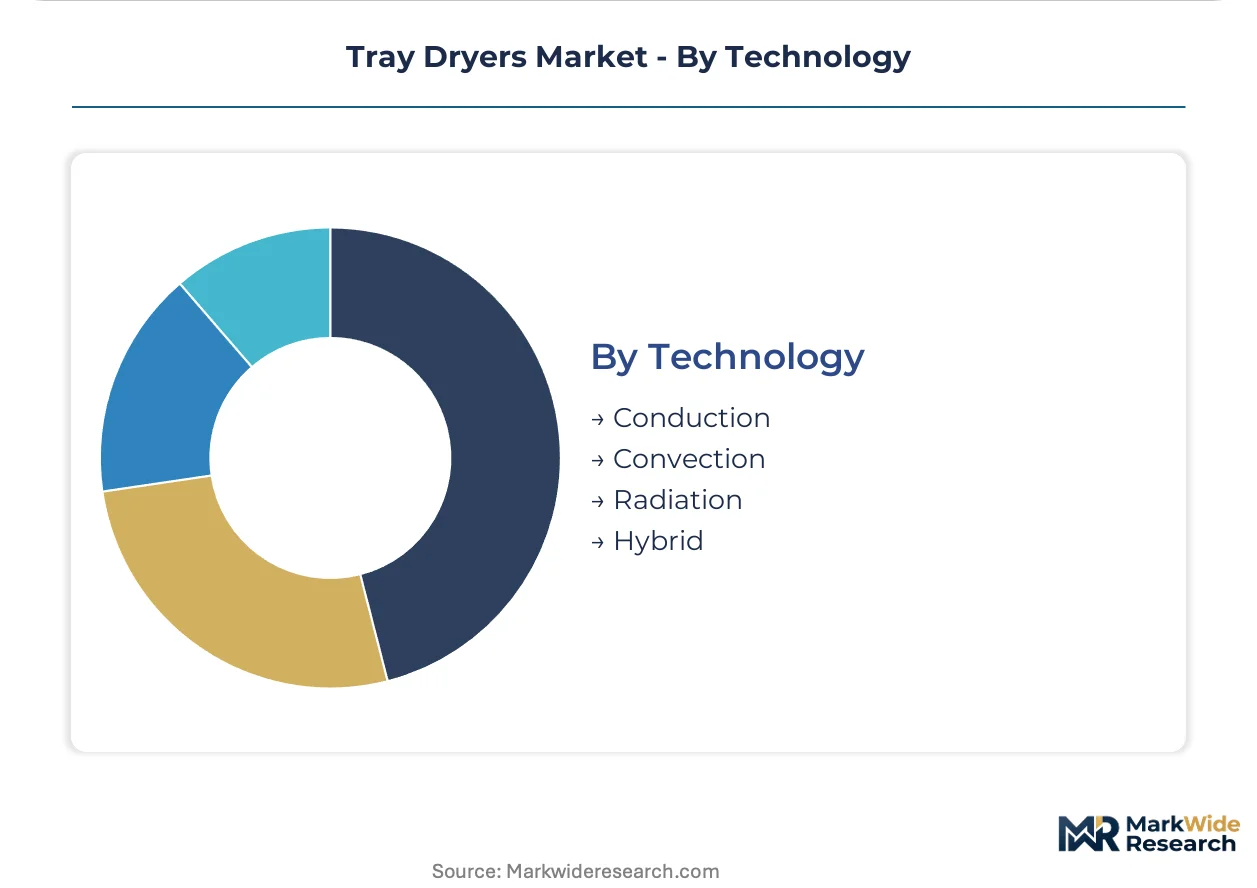
Technology:
Heat transfer mechanism determines energy efficiency, temperature uniformity, and compatibility with vacuum integration.
- Hybrid:Combined conduction-convection architectures with heat recovery represent the steepest expansion trajectory as processors seek energy efficiency without sacrificing throughput uniformity. EU Green Deal retrofit incentives accelerate adoption in German and Swiss chemical facilities.
- Convection:Forced hot air circulation remains the conventional installed base standard, facing displacement pressure from hybrid alternatives in energy-intensive applications.
- Conduction:Heated shelf designs provide precise temperature control for vacuum pharmaceutical applications where air circulation risks product contamination.
- Radiation:Infrared and microwave-assisted configurations address surface-moisture-limited materials in specialty food and ceramic applications, constrained by penetration depth limitations.
Convection technology retains the dominant installed position, while Hybrid systems are gaining share fastest in European retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in Germany, India, and Switzerland supply validated systems to pharmaceutical corridors worldwide. CDSCO deadlines in India and EMA Annex 15 expansions in Europe concentrate procurement activity in these manufacturing hubs.
Germany
EMA Annex 15 validation requirements are accelerating batch-processing capacity additions across Baden-Württemberg and North Rhine-Westphalia. The country's pharmaceutical regulator enforces stringent sterilization documentation for active ingredient production. Stuttgart-based engineering firms supply cGMP-compliant vacuum tray configurations to domestic and export markets.
India
CDSCO Schedule M compliance deadlines are compelling facility upgrades across Gujarat and Maharashtra. The national pharmaceutical regulator mandates equipment replacement cycles for domestic API manufacturing. Ahmedabad and Mumbai manufacturers face compressed timelines to meet export-quality sterilization standards.
Switzerland
Swissmedic validation protocols concentrate demand for precision vacuum drying technology in the Basel pharmaceutical cluster. The country's medical products agency enforces data integrity requirements for batch documentation. Basel-Stadt facilities deploy smart sensor arrays to satisfy regulatory audit readiness standards.
United States
FDA cGMP guidelines shape equipment qualification protocols for sterile API production across New Jersey and Massachusetts. The agency's documented cleanability requirements compel investment in validated tray dryer systems. Greater Boston biopharma corridors specify hybrid conduction-convection configurations for energy-efficient batch processing.
Japan
PMDA oversight of pharmaceutical manufacturing drives adoption of closed-loop control architectures in the Kansai and Kanto regions. The national regulator's data integrity requirements accelerate digital instrumentation deployment. Osaka-based manufacturers integrate IoT-enabled predictive maintenance into vacuum tray operations.
Tray Dryers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying heat transfer assemblies and vacuum vessel fabrication. The vendor base stratifies across three tiers: multinational engineering conglomerates with full validation capabilities, mid-scale regional fabricators serving domestic compliance deadlines, and specialized laboratory equipment makers. Strategic moves center on pre-certified material qualification against REACH restrictions and turnkey IQ/OQ documentation bundling for CDSCO-regulated buyers.
Among German-based engineering conglomerates, GEA Group and Bühler Group exemplify the platform-integrator archetype with European manufacturing footprints. Hosokawa Micron occupies a position within the precision vacuum technology specialist tier, representing Japanese engineering heritage in micron-scale processing equipment. These three entities anchor the competitive structure across pharmaceutical and food-grade dehydration applications.
| Leading Market Players |
|---|
| GEA Group |
| Hosokawa Micron |
| Bühler Group |
| SPX FLOW |
| GMP Engineering |
| SSP Pvt. Ltd. |
| Rico Scientific |
| Yamato Scientific |
| Pope Scientific |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp pharmaceutical logistics corridors transmit stainless steel alloy cost volatility directly into vacuum tray dryer pricing tiers, concentrating margin pressure on European fabricators while enabling premium capture by validated cGMP suppliers serving EMA-regulated buyers.
Pricing Analysis
EMA Annex 15 validation requirements dictate the pricing tier structure across European pharmaceutical procurement. Three-tier pricing structure across premium validated, standard compliant, and economy non-certified levels separates Swissmedic-audited Basel suppliers from mid-tier Indian CDSCO-compliant fabricators and unvalidated secondary market equipment. Cost compression in economy-tier electric units is intensifying because Gujarat-based manufacturers face alloy price swings in 316L stainless steel vessel construction. Contract manufacturing organizations in Maharashtra exhibit highest price sensitivity; sterile API producers in Baden-Württemberg demonstrate lowest sensitivity due to batch failure risk costs.
Supply Chain Analysis
Export control restrictions on precision vacuum pump technology limit flows from German and Swiss engineering clusters into certain pharmaceutical manufacturing jurisdictions. Equipment fabrication concentrates in Germany, India, and Switzerland. Supply chains draw from specialty stainless steel mills in Jamshedpur, vacuum vessel forging facilities in Stuttgart, and digital control system suppliers in Basel. Single-source vulnerability sits with European precision vacuum pump manufacturers facing REACH material qualification delays. Distribution runs through OEM direct sales for large pharmaceutical accounts and regional fabricator networks for mid-scale chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tray dryer demand sits in early-cycle expansion as CDSCO Schedule M compliance deadlines force replacement waves across India's domestic API manufacturing base.
For Market Incumbents: Insulate margin position by deepening backward integration into stainless steel vessel fabrication and pre-certifying material grades against evolving ECHA substance restrictions. Freeze-drying substitution in biologics manufacturing threatens high-value pharmaceutical applications; counter by bundling IoT-enabled predictive maintenance to extend service revenue streams and raise switching costs for validated installations. For New Entrants and Emerging Players: Secondary cities beyond Ahmedabad, Hyderabad, and Mumbai present the most penetrable geography for CDSCO-driven equipment upgrades. Target turnkey qualification packages that compress project timelines for export-contract-pressured manufacturers. Lead with remote IQ/OQ documentation support to differentiate from established European suppliers with slower field engineering deployment. For Investors and Strategic Acquirers: CDSCO compliance deadline clustering reshapes the acquisition landscape toward Indian regional fabricators with validated electric tray dryer portfolios. Long-term viability centers on hybrid conduction-convection technology platforms serving EU Green Deal retrofit incentives. Monitor EMA Annex 15 expansion project announcements in Baden-Württemberg as inflection signal for European capacity addition cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Material Qualification | ECHA REACH compliance accelerates sales cycles for pharmaceutical vacuum tray configurations. |
| Turnkey IQ/OQ Documentation Bundling | CDSCO-regulated buyers in Maharashtra prioritize compressed project timelines for export deadlines. |
| Hybrid Technology Platform Development | EU Green Deal retrofit incentives drive fastest-growing segment in German chemical facilities. |
| IoT Predictive Maintenance Integration | Swissmedic data integrity requirements enable remote service revenue for distributed operations. |
| Secondary City Distribution Expansion | Underpenetrated Indian markets beyond Gujarat create immediate replacement demand capture. |
Methodological Framework
A standing panel of pharmaceutical plant engineers, regulatory affairs specialists at CDSCO and EMA, stainless steel procurement managers, and vacuum system maintenance directors provided ongoing calibration across primary fieldwork and secondary validation. Bottom-up demand estimates triangulated against customs data for pharmaceutical equipment imports, SEC filings of listed engineering conglomerates, CDSCO facility inspection records, and EMA GMP certification databases.
Scenario-bracketing framed projections across the analysis window, modeling technology adoption by heat transfer mechanism, capacity tier, end-use industry, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, compliance deadline clustering, and energy efficiency retrofit incentive trajectories. Forecast inputs incorporated EMA Annex 15 expansion project pipelines and CDSCO Schedule M enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese vacuum equipment manufacturers would shift outcomes. Material shifts in REACH substance restriction scopes or CDSCO enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Piling Machine Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market