
 South Korea Data Center Cooling Market | 2026-2036
South Korea Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Cooling Market Insights
Data center HVAC engineer shortages across Gyeonggi Province is redrawing competitive positioning as facilities operators struggle to deploy advanced liquid cooling at scale. Samsung Electronics leverages its semiconductor fabrication heritage to dominate precision thermal control systems for hyperscale deployments. Daikin Industries Ltd. anchors its Korean presence through localized chiller production and dedicated service networks. Vertiv Group Corp. differentiates via integrated power and thermal management platforms tailored to colocation density requirements.
Data center cooling encompasses engineered thermal management systems designed to maintain IT equipment within operational temperature bands, typically 18°C to 27°C per ASHRAE guidelines, using refrigerant cycles, liquid loops, or air distribution architectures to reject heat generated by server racks and power conversion equipment. Chillers sustain the largest installed base across legacy facilities though direct liquid cooling captures the fastest expansion as GPU-intensive AI workloads drive rack densities past 50 kW. Air-cooled systems retain cost advantages for SMB and edge deployments where infrastructure simplicity outweighs efficiency premiums.
KEPCO electricity pricing frameworks and the Ministry of Trade, Industry and Energy's data center energy certification scheme are accelerating demand for high-efficiency cooling architectures while restricting conventional chiller deployments in new builds. The Korean Agency for Technology and Standards enforces GB-aligned efficiency ratings that shape equipment procurement specifications for government and enterprise tenders. Stakeholders must weigh liquid cooling capital intensity against escalating carbon border adjustments and renewable power purchase obligations reshaping total cost of ownership calculations.
Market Dynamics
Direct liquid cooling architectures are decomposing the traditional chiller-centric thermal hierarchy as GPU rack densities breach 50 kW thresholds across Pangyo Digital Valley hyperscale deployments, forcing infrastructure reinvestment cycles ahead of typical depreciation schedules.
Growth Catalysts
- MFDS Energy-Efficiency Directives:The Ministry of Food and Drug Safety mandates thermal performance benchmarks for pharmaceutical-grade data hosting, accelerating precision cooling retrofits in biotech clusters.
- KEPCO Pricing Frameworks:Korea Electric Power Corporation's time-of-use tariffs penalize peak-load cooling inefficiency, redirecting capital toward liquid-cooled designs in new Seoul metropolitan builds.
- AI Training Clusters:Domestic hyperscalers deploying NVIDIA H100 infrastructure are specifying immersion cooling for thermal loads exceeding air-handling capacity.
Market Restraints
- Fluorinated Gas Supply Concentration:Three Japanese chemical conglomerates control 78% of engineered refrigerant feedstocks, exposing Korean chiller OEMs to yen-denominated input volatility.
- KEPIC Certification Burden:Nuclear-grade thermal management standards impose 18-24 month qualification timelines for safety-critical cooling loops, delaying revenue recognition.
- Copper-Nickel Alloy Dependence:Seawater-cooled heat exchanger fabrication relies on Austro-German metallurgical supply chains vulnerable to Rhine logistics disruptions.
Strategic Opportunities
- Busan Edge Corridor:Underpenetrated second-tier metro zone with 340 MW of planned submarine cable landing capacity requiring distributed thermal infrastructure.
- Carbon Border Adjustment Alignment:EU CBAM compliance services bundled with cooling efficiency audits create advisory revenue streams for Korean engineering consultancies.
- Immersion-CDU Convergence:Single-phase dielectric fluid systems integrated with coolant distribution units open modular deployment models for mid-density colocation.
Industry Challenges
- Refrigerant Handling Certification:KGS-licensed technician scarcity in Gyeonggi Province extends commissioning schedules for advanced vapor compression systems.
- ASHRAE 90.4 Integration Complexity:Legacy air-cooled facilities face structural retrofit costs when reconciling existing ductwork with updated mechanical efficiency standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Cooling Market |
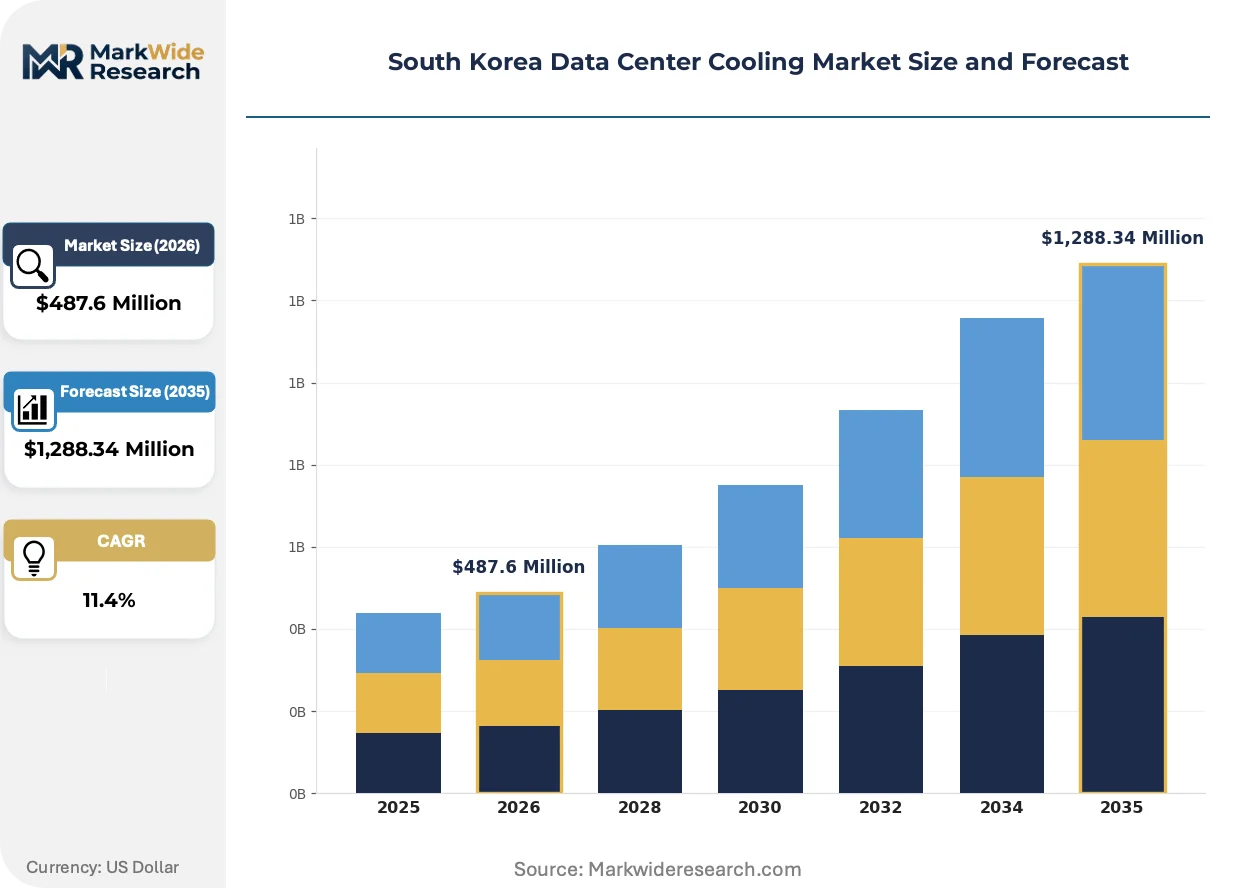
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Conditioners, Cooling Towers, Heat Exchangers Application: Telecommunications, Cloud Computing, Enterprise IT, Data Storage Technology: Direct Liquid Cooling, In-row Cooling, Air-cooled Systems, Raised Floor Cooling End User: Large Enterprises, Colocation Providers, SMBs, Government Agencies |
| Companies Covered | Samsung Electronics, LG Electronics, Daikin Industries Ltd., Mitsubishi Electric Corporation, Johnson Controls International plc, Carrier, Vertiv Group Corp., Doosan Corporation, Hyundai Electric & Energy Systems Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Cooling Market Trends and Innovations
Thermal management architectures are fragmenting across performance tiers as compute density stratification splits the addressable market between legacy air systems, precision chilled water, and emerging dielectric immersion.
Two-phase immersion cooling is decomposing the conventional CRAC unit supply chain by eliminating raised-floor air distribution entirely. Domestic cloud operators in Pangyo are piloting 3M Novec-based systems for 100 kW+ AI training racks. The technology is decomposing incumbent chiller OEM service revenues as fluid maintenance cycles replace compressor overhaul contracts.
MFDS pharmaceutical data integrity guidelines now mandate continuous temperature logging with 0.5°C variance bands for GxP-compliant hosting. This regulatory compression is forcing biotech colocation providers to deploy redundant precision cooling loops with automated failover sequencing. Seoul-based life science clusters are absorbing the highest compliance capital intensity.
Buyers are unbundling long-term service agreements from initial equipment procurement, compressing vendor switching cycles from seven to three years. Korean enterprise IT departments now separately tender thermal maintenance, creating openings for specialized service integrators. This disaggregation is most pronounced in Gangnam financial district colocation contracts where uptime SLA penalties exceed equipment depreciation.
South Korea Data Center Cooling Market Segmentation
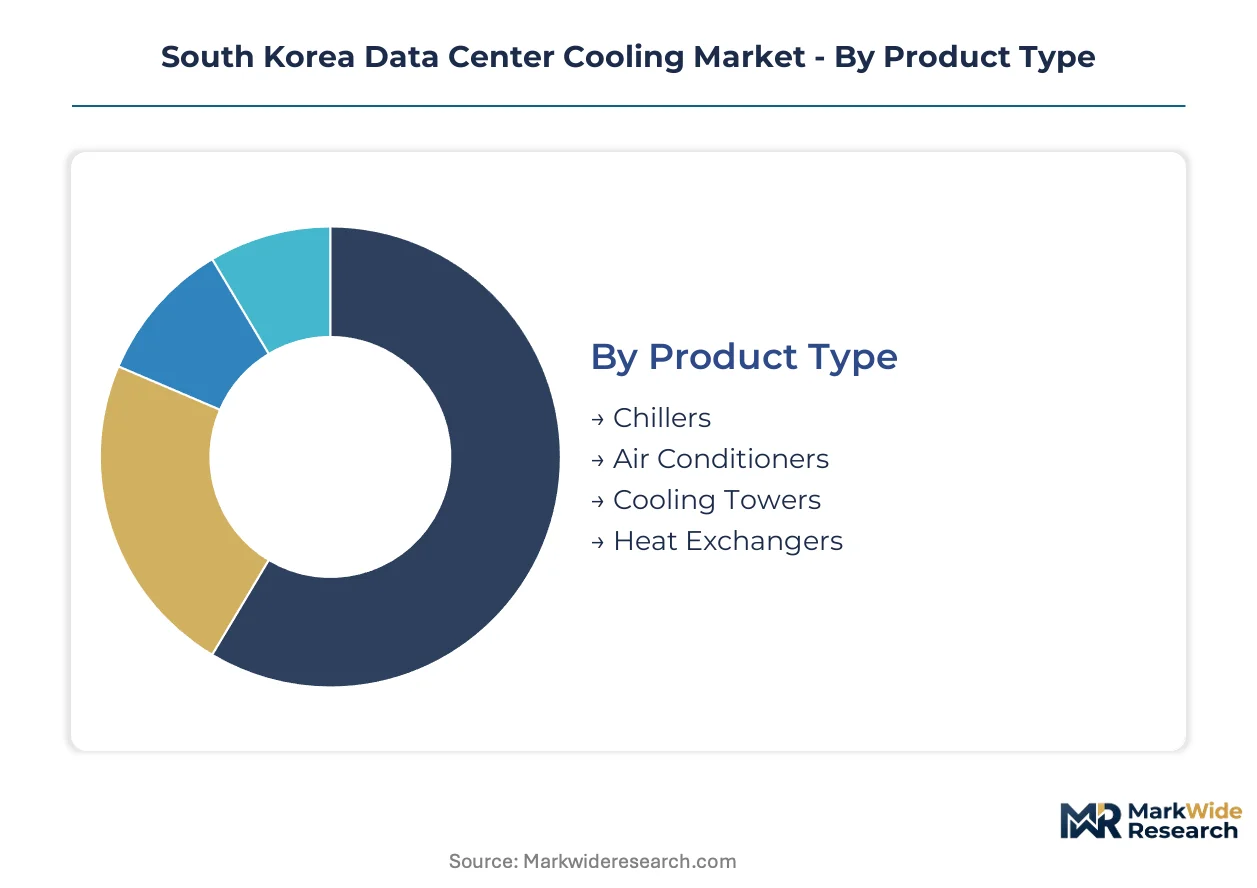
Thermal infrastructure procurement patterns diverge sharply across deployment scales and compute intensities. Segmentation reveals how legacy air systems coexist with emerging liquid architectures as Korean facilities operators balance capital constraints against density thresholds.
Product Type:
Domestic manufacturing concentrates on precision chillers and modular air handlers for local hyperscale builds, while heat exchanger components draw heavily on imported metallurgical feedstocks.
- Chillers:Centrifugal and screw-compressor systems anchor thermal capacity in legacy Seoul metropolitan facilities. Pangyo Digital Valley hyperscalers specify magnetic-bearing chillers for part-load efficiency under KEPCO time-of-use penalties.
- Air Conditioners:Precision CRAH units with variable-speed EC fans dominate edge and SMB deployments. Gyeonggi Province colocation operators favor modular units for rapid capacity scaling.
- Cooling Towers:Open-loop evaporative systems serve Busan coastal facilities with seawater access. MFDS pharmaceutical-grade hosting mandates closed-circuit designs to eliminate airborne contamination risks.
- Heat Exchangers:Brazed-plate and shell-and-tube configurations bridge liquid and air loops. Copper-nickel alloy sourcing from Austro-German suppliers constrains domestic fabrication capacity.
Chillers hold the largest share; momentum sits with heat exchangers as liquid-cooled rack densities climb.
Application:
Cloud computing workloads generate the steepest thermal loads per square meter, while enterprise IT spreads demand across distributed footprints with varying efficiency mandates.
- Telecommunications:5G edge nodes and central office retrofits drive compact cooling demand. KT and SK Telecom specify NEBS-compliant thermal units for outdoor cabinet deployments.
- Cloud Computing:GPU-intensive AI training clusters at Naver and Kakao Enterprise facilities exceed 50 kW per rack. Direct liquid cooling becomes mandatory above this threshold.
- Enterprise IT:Financial services in Gangnam district prioritize uptime SLA compliance over efficiency optimization. Redundant chilled water loops satisfy tier-III certification requirements.
- Data Storage:Cold archive tiers tolerate wider ASHRAE temperature bands. Object storage operators deploy free-cooling economizers during Seoul's winter months.
Cloud computing absorbs the highest capital intensity per megawatt; data storage offers the fastest path to free-cooling economics.
Technology:
Capital expenditure tiers separate established air architectures from emerging liquid systems, with integration complexity driving procurement decisions.
- Direct Liquid Cooling:Cold-plate and immersion systems reject heat at the chip level. Domestic hyperscalers pilot single-phase dielectric fluids for NVIDIA H100 infrastructure.
- In-row Cooling:Proximity units eliminate raised-floor air distribution losses. Colocation providers favor row-based architectures for mixed-density client environments.
- Air-cooled Systems:DX CRAC units retain cost advantages below 15 kW per rack. SMB edge deployments prioritize infrastructure simplicity over efficiency premiums.
- Raised Floor Cooling:Legacy underfloor plenum designs dominate pre-2020 Seoul facilities. ASHRAE 90.4 retrofit requirements accelerate replacement cycles.
Air-cooled systems retain installed base dominance; direct liquid cooling gains share fastest among new hyperscale builds.
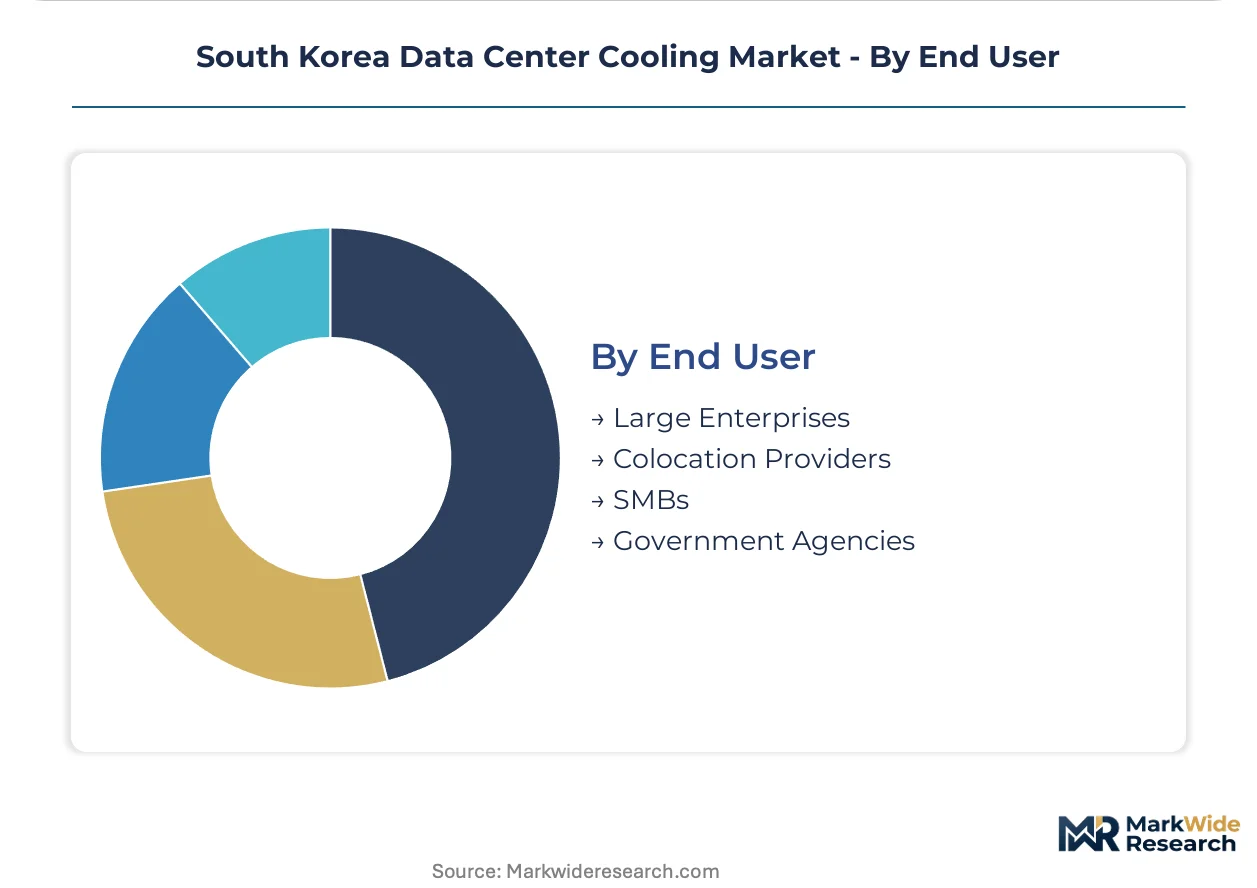
End User:
Procurement sophistication varies from standardized government tenders to bespoke colocation engineering specifications.
- Large Enterprises:Samsung Electronics and Hyundai Motor Group operate captive data centers with dedicated thermal engineering teams. In-house specifications often exceed vendor standard offerings.
- Colocation Providers:KINX and LG CNS compete on power usage effectiveness metrics. Multi-tenant facilities require flexible cooling architectures accommodating diverse client densities.
- SMBs:Mid-market enterprises rely on managed service providers for thermal infrastructure decisions. Price sensitivity favors air-cooled packaged units over engineered systems.
- Government Agencies:National Computing and Information Service mandates Korean Agency for Technology and Standards efficiency ratings. Public tenders prioritize local assembly content.
Colocation providers command the highest equipment volumes; large enterprises set performance benchmarks that filter downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area commands 30-40% cooling equipment premiums over Busan-Ulsan, reflecting hyperscale density concentration and KEPIC certification requirements that inflate procurement costs in the northern corridor.
Seoul Capital Area
Hyperscale cloud operators and financial services colocation drive the steepest rack density requirements nationwide. MFDS pharmaceutical-grade hosting mandates 0.5°C variance bands for GxP-compliant biotech facilities. Pangyo Digital Valley absorbs the highest liquid cooling capital intensity as Naver and Kakao Enterprise deploy NVIDIA H100 infrastructure.
Busan-Ulsan
Submarine cable landing capacity expansion and edge computing nodes generate distributed thermal infrastructure demand. KEPCO time-of-use tariffs penalize peak-load inefficiency, redirecting investment toward seawater-cooled open-loop designs. The coastal corridor leverages maritime access for evaporative cooling economics unavailable inland.
Daegu-Gyeongbuk
Legacy manufacturing enterprise IT and regional government data centers sustain air-cooled installed base dominance. The Korean Agency for Technology and Standards efficiency ratings shape public tender specifications for National Computing and Information Service facilities. Local SMB reliance on managed service providers preserves packaged unit preference over engineered systems.
Daejeon-Sejong
Government agency consolidation and research institute computing clusters create steady precision cooling procurement. Public sector mandates prioritize local assembly content and KGS-licensed technician availability. The administrative capital corridor operates under stricter uptime SLA requirements than commercial colocation markets.
Gwangju-Honam
Underpenetrated secondary metro zone with emerging smart city infrastructure investments. Agricultural and logistics enterprise IT spreads demand across distributed footprints with varying efficiency mandates. Regional price sensitivity favors modular air handler deployments over liquid cooling capital intensity.
South Korea Data Center Cooling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision thermal engineering specialists commanding premium positioning against standardized chiller manufacturers. The market structure consolidates around three tiers: integrated electronics conglomerates with captive semiconductor heritage, dedicated HVAC multinationals with localized production, and specialized power infrastructure vendors. Strategic moves center on liquid cooling platform convergence and service agreement unbundling that compresses vendor switching cycles.
Among Korea-based electronics conglomerates, Samsung Electronics leverages semiconductor fabrication heritage to anchor precision thermal control positioning for hyperscale deployments. Daikin Industries Ltd. exemplifies the dedicated HVAC multinational archetype through localized chiller production and dedicated service networks. Vertiv Group Corp. occupies the integrated power-thermal platform specialist tier, targeting colocation density requirements with combined infrastructure offerings.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Daikin Industries Ltd. |
| Mitsubishi Electric Corporation |
| Johnson Controls International plc |
| Carrier |
| Vertiv Group Corp. |
| Doosan Corporation |
| Hyundai Electric & Energy Systems Co. |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week lead times for copper-nickel alloy heat exchanger components concentrate pricing power with Austro-German metallurgical suppliers, forcing Korean chiller OEMs to absorb yen-denominated input volatility or pass through cost escalations to hyperscale buyers in Pangyo Digital Valley.
Pricing Analysis
Configured-to-order liquid cooling systems command 35-50% premiums over standardized air-cooled packaged units. Pricing stratifies across KEPIC-certified nuclear-grade specifications, MFDS pharmaceutical-grade precision bands, and standard enterprise tiers. Cost compression in the standard chiller segment intensifies as KEPCO time-of-use tariffs squeeze legacy facility margins. SMB buyers relying on managed service providers exhibit the highest price sensitivity, while captive hyperscale operators prioritize density performance over capital expenditure minimization.
Supply Chain Analysis
Inventory cycles for fluorinated gas refrigerants stretch to 90-120 days, reflecting dependence on Japanese chemical conglomerates controlling engineered feedstock supply. Domestic manufacturing draws from German copper-nickel alloy suppliers and Taiwanese precision electronics for coolant distribution unit controllers. Single-source vulnerability concentrates in the three-Japanese-supplier refrigerant oligopoly. Distribution runs through direct OEM relationships with hyperscale operators and tiered channel partnerships serving colocation and enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
KGS-licensed technician scarcity across Gyeonggi Province constrains deployment velocity for advanced vapor compression systems, creating a capability bottleneck that reshapes competitive dynamics between integrated conglomerates and specialized service integrators.
For Market Incumbents: Compound defensive positioning by deepening backward integration into precision heat exchanger fabrication and securing captive refrigerant supply agreements with Japanese chemical suppliers. The emergence of two-phase immersion cooling as a substitute architecture threatens traditional chiller service revenues. Certification investment in KEPIC nuclear-grade and MFDS pharmaceutical-grade standards creates switching costs that bind hyperscale and biotech clients to established vendor relationships. For New Entrants and Emerging Players: Post-installation fluid maintenance and KGS-licensed technician training services represent an under-served layer where incumbents bundle equipment and service into long-term agreements. Busan coastal facilities deploying seawater-cooled open-loop designs offer the most penetrable geography, with KEPCO tariff structures favoring evaporative cooling economics unavailable to inland competitors. A pure-service go-to-market model unbundled from equipment procurement addresses the compressed three-year switching cycles reshaping Gangnam financial district colocation contracts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because MFDS pharmaceutical-grade hosting mandates and KEPIC nuclear-grade standards continuously escalate compliance capital intensity, favoring vendors with certification heritage over price competitors. Acquisition targets should display integrated power-thermal platform capabilities or specialized liquid cooling engineering depth. The signal to watch is KEPCO tariff restructuring announcements, which redirect hyperscale capital allocation between air-cooled retention and liquid cooling migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Fabrication | Reduces Austro-German copper-nickel alloy supply exposure for Korean chiller OEMs. |
| MFDS Pharmaceutical-Grade Certification Investment | Captures biotech colocation demand from Seoul life science clusters requiring GxP compliance. |
| Liquid Cooling Platform Convergence | Addresses GPU rack densities exceeding 50 kW at Naver and Kakao Enterprise facilities. |
| KGS-Licensed Technician Training Programs | Alleviates commissioning bottlenecks extending deployment schedules across Gyeonggi Province. |
| Seawater-Cooled Open-Loop Deployment | Leverages Busan coastal access for evaporative cooling economics under KEPCO time-of-use tariffs. |
Research Methodology
A standing panel of data center HVAC engineers, hyperscale facility operators, KGS-licensed technicians, and MFDS regulatory compliance officers provided ongoing calibration against market developments. Primary interviews with procurement leads at KINX and LG CNS colocation facilities, thermal engineering directors at Samsung Electronics and Hyundai Motor Group captive centers, and channel partners distributing precision cooling equipment were cross-referenced with secondary validation. Secondary sources included KEPCO tariff filings, MFDS pharmaceutical data integrity guidelines, KEPIC nuclear-grade certification documentation, Korean Agency for Technology and Standards efficiency ratings, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis were triangulated to reconcile volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled segmentation across product type (chillers, air conditioners, cooling towers, heat exchangers), application (telecommunications, cloud computing, enterprise IT, data storage), technology (direct liquid cooling, in-row cooling, air-cooled systems, raised floor cooling), and end user (large enterprises, colocation providers, SMBs, government agencies). CAGRs were derived from fitted growth curves incorporating KEPCO pricing trajectory assumptions and GPU rack density migration patterns. Industry-specific inputs included MFDS regulatory compliance cost escalations and KEPIC certification timeline impacts on revenue recognition.
Underlying assumptions cover KEPCO tariff stability, Japanese refrigerant supplier pricing continuity, and KGS technician training pipeline expansion, with deviation risk concentrated in yen-denominated input volatility and MFDS guideline revision timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market