
 Belgium Data Center Cooling Market | 2026-2036
Belgium Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Cooling Market Insights
The capital-intensity divergence between specialist cooling vendors and general HVAC contractors is collapsing as hyperscale operators demand integrated thermal management. Schneider Electric leverages its prefabricated modular data center portfolio to anchor large-scale deployments across Belgian logistics corridors. Vertiv Group Corp. sustains competitive positioning through direct liquid cooling R&D partnerships with Leuven-based research institutions. STULZ competes aggressively on precision air conditioning retrofit cycles in legacy enterprise facilities throughout Flanders.
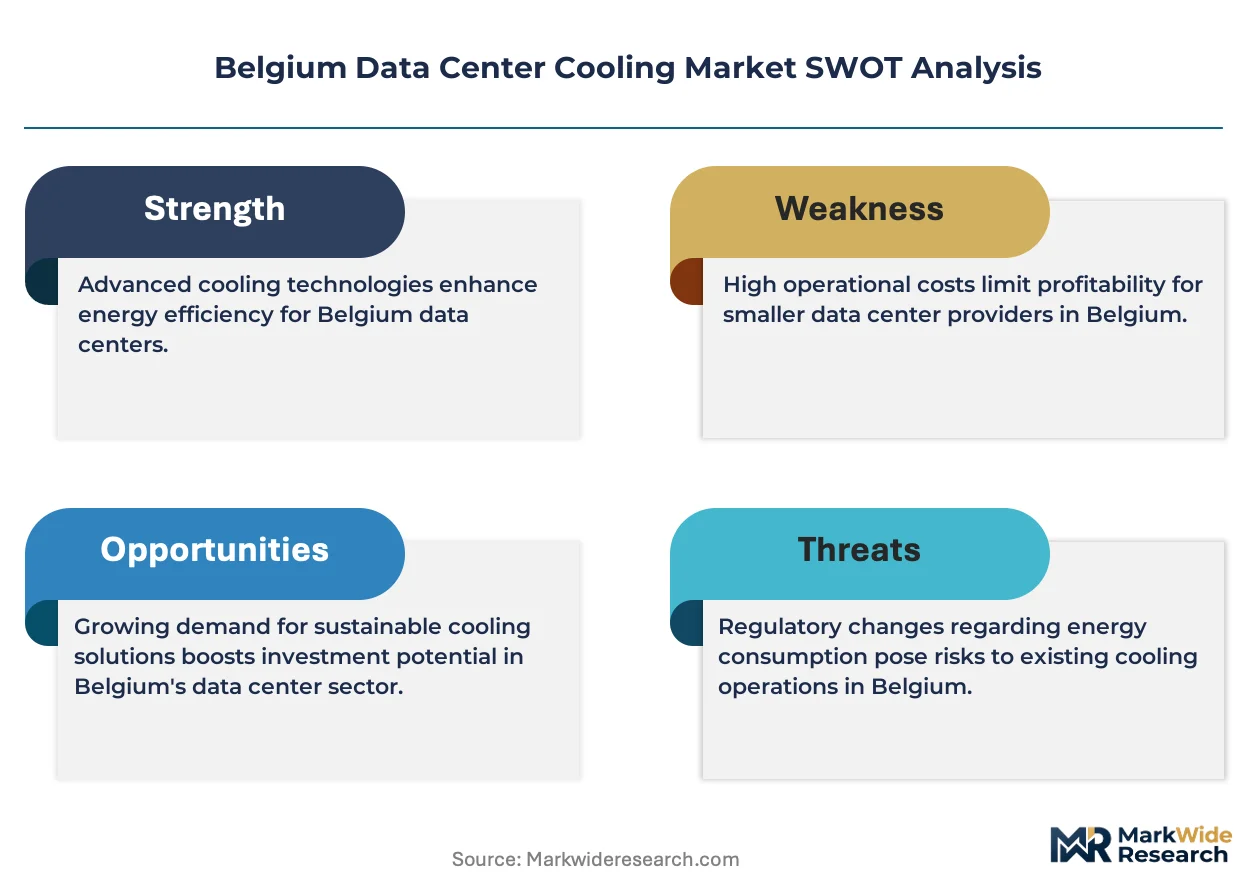
Belgium data center cooling encompasses engineered thermal management systems designed to maintain server inlet temperatures between 18°C and 27°C while dissipating heat loads exceeding 50 kW per rack in high-density configurations. These systems employ chilled water loops, refrigerant-based direct expansion, dielectric fluid immersion, or evaporative media to protect computing infrastructure from thermal-induced downtime and performance degradation. Liquid cooling and immersion cooling segments are capturing margin pools as GPU-intensive AI workloads proliferate, while air cooling retains volume leadership in colocation retrofits where infrastructure replacement cycles extend past seven years. Direct expansion systems dominate smaller enterprise installations, though hybrid systems are gaining traction among cloud service providers seeking partial free-cooling utilization during Belgium's temperate months.
Belgium's implementation of the EU Energy Efficiency Directive through regional energy agencies, combined with Flanders' stringent EPB building performance standards and federal green public procurement rules, mandates minimum power usage effectiveness thresholds for new data center constructions. These frameworks shape vendor qualification requirements and channel investment toward heat reuse architectures and low-global-warming-potential refrigerants. Stakeholders must monitor evolving Flemish heat network regulations that could transform waste heat from Brussels facilities into district heating revenue streams.
Market Dynamics
GPU-intensive AI workloads are compressing thermal design power thresholds below what air-cooled infrastructure can sustain, forcing Belgian operators to reengineer legacy facilities around liquid cooling architectures before rack densities breach 100 kW.
Growth Catalysts
- EU Energy Efficiency Directive transposition:Belgium's regional energy agencies mandate power usage effectiveness thresholds that disqualify traditional cooling for new hyperscale builds, channeling capital toward immersion and hybrid systems.
- Cloud service provider expansion:Hyperscale operators are clustering capacity in Flanders and Wallonia near fiber interconnection points, generating concentrated demand for direct liquid cooling infrastructure.
- Heat reuse architectures:Flemish heat network regulations enable Brussels facilities to monetize waste heat through district heating contracts, transforming thermal management from cost center to revenue stream.
Market Restraints
- Dielectric fluid supply concentration:Specialty coolant production concentrates among a limited set of European chemical suppliers, exposing Belgian operators to input cost volatility and allocation constraints.
- EPB building performance standards:Flanders' stringent envelope and mechanical codes impose retrofit compliance timelines that extend legacy air cooling depreciation cycles beyond economic viability.
- Technical limitation in hybrid control:Precise orchestration between free-cooling and mechanical refrigeration remains immature, causing efficiency losses during Belgium's shoulder seasons.
Strategic Opportunities
- Wallonia enterprise retrofits:Underpenetrated industrial zones around Liège and Charleroi host aging colocation facilities with compressed replacement timelines and limited incumbent vendor relationships.
- Refrigerant convergence:Low-global-warming-potential synthetic fluids and natural refrigerant blends are converging in next-generation chiller designs, opening qualification windows for new subsystem suppliers.
- Federal green public procurement rules:Mandatory environmental criteria for government-anchored data center contracts create preferential purchasing pathways for heat-reuse-enabled cooling vendors.
Industry Challenges
- Immersion cooling technician scarcity:Dielectric fluid handling, leak detection, and server-level plumbing require competencies absent from conventional HVAC training pipelines, constraining deployment velocity.
- Legacy integration complexity:Hybrid cooling retrofits must interface with seven-plus-year-old air-cooled infrastructure without triggering facility-wide downtime, compressing installation windows and raising execution risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Cooling Market |
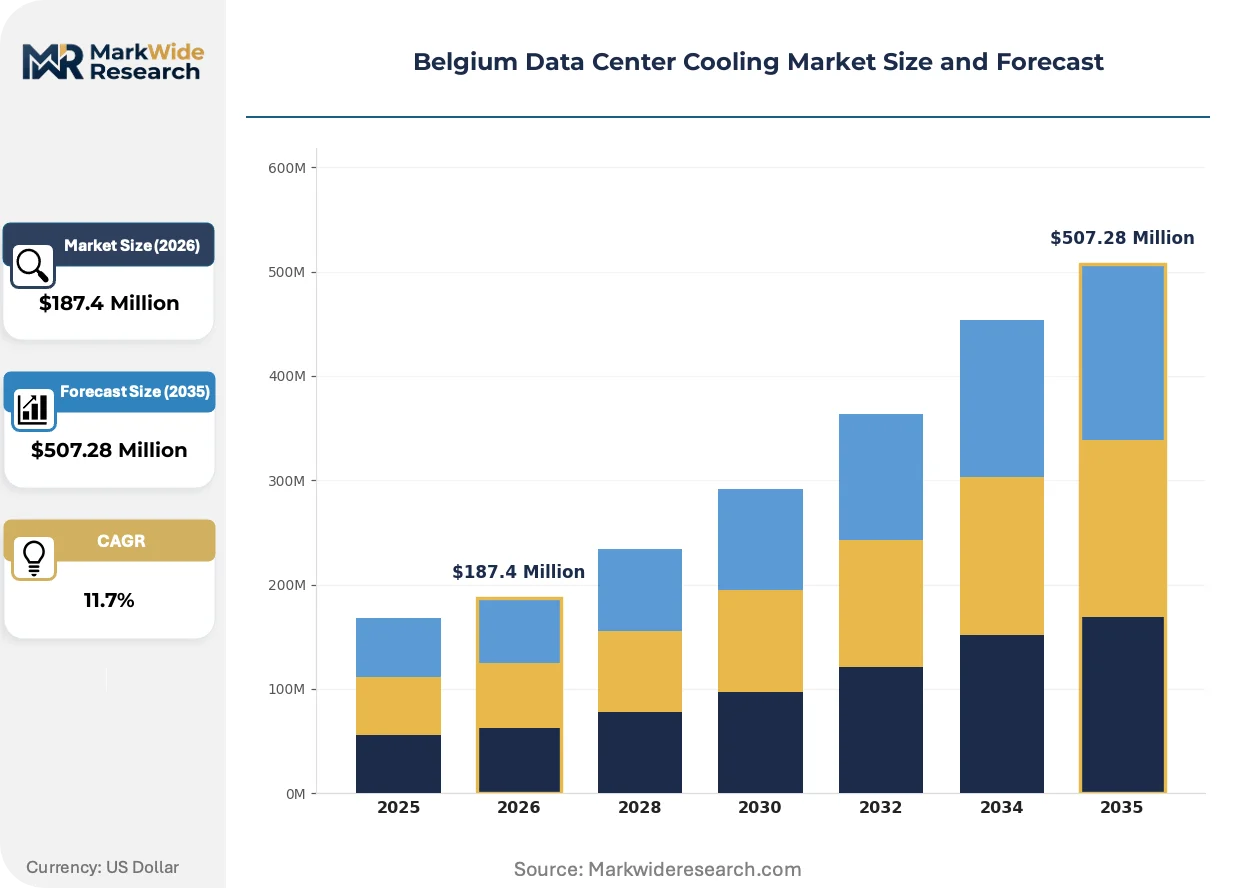
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Phase Change Cooling End User: Cloud Service Providers, Colocation Providers, Enterprises, Government Institutions Cooling Type: Chilled Water Systems, Direct Expansion Systems, Evaporative Cooling Systems, Hybrid Systems Application Area: Telecommunications, Banking, Healthcare, Retail |
| Companies Covered | Schneider Electric, Vertiv Group Corp., STULZ, Rittal GmbH & Co. KG, Alfa Laval AB, Danfoss, Carrier Global Corporation, Mitsubishi Electric, FlaktGroup, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Cooling Market Trends and Innovations
Liquid cooling is compressing the physical footprint of thermal management while elevating precision requirements, reshaping vendor qualification criteria and procurement evaluation frameworks across Belgian data center construction.
Single-phase direct-to-chip cold plates are miniaturizing heat exchanger geometries to fit within standard server form factors while maintaining thermal resistance below 0.1°C per watt. Hyperscale operators in Antwerp and Brussels-Capital are specifying these systems for AI training clusters where rack densities exceed 75 kW. This compression is miniaturizing the competitive set to vendors with precision machining capabilities and direct server OEM relationships.
Belgium's transposition of the EU F-Gas Regulation through federal environmental permits is phasing down hydrofluorocarbon refrigerant quotas for new chiller installations. Equipment suppliers must now qualify natural refrigerant or ultra-low-GWP synthetic alternatives before securing project approvals. Colocation operators in Flanders are responding by accelerating chiller replacement cycles to lock in compliant equipment ahead of tightening allocation limits.
Facility operators are unbundling thermal management from bundled construction contracts, issuing separate RFPs for cooling subsystems with performance-guaranteed efficiency metrics. This disintermediation is compressing general contractor margins while elevating specialist cooling vendors to direct supplier status. The shift is most visible in Brussels-Capital hyperscale projects where operators demand integrated heat-reuse guarantees separate from base mechanical scope.
Belgium Data Center Cooling Market Segmentation
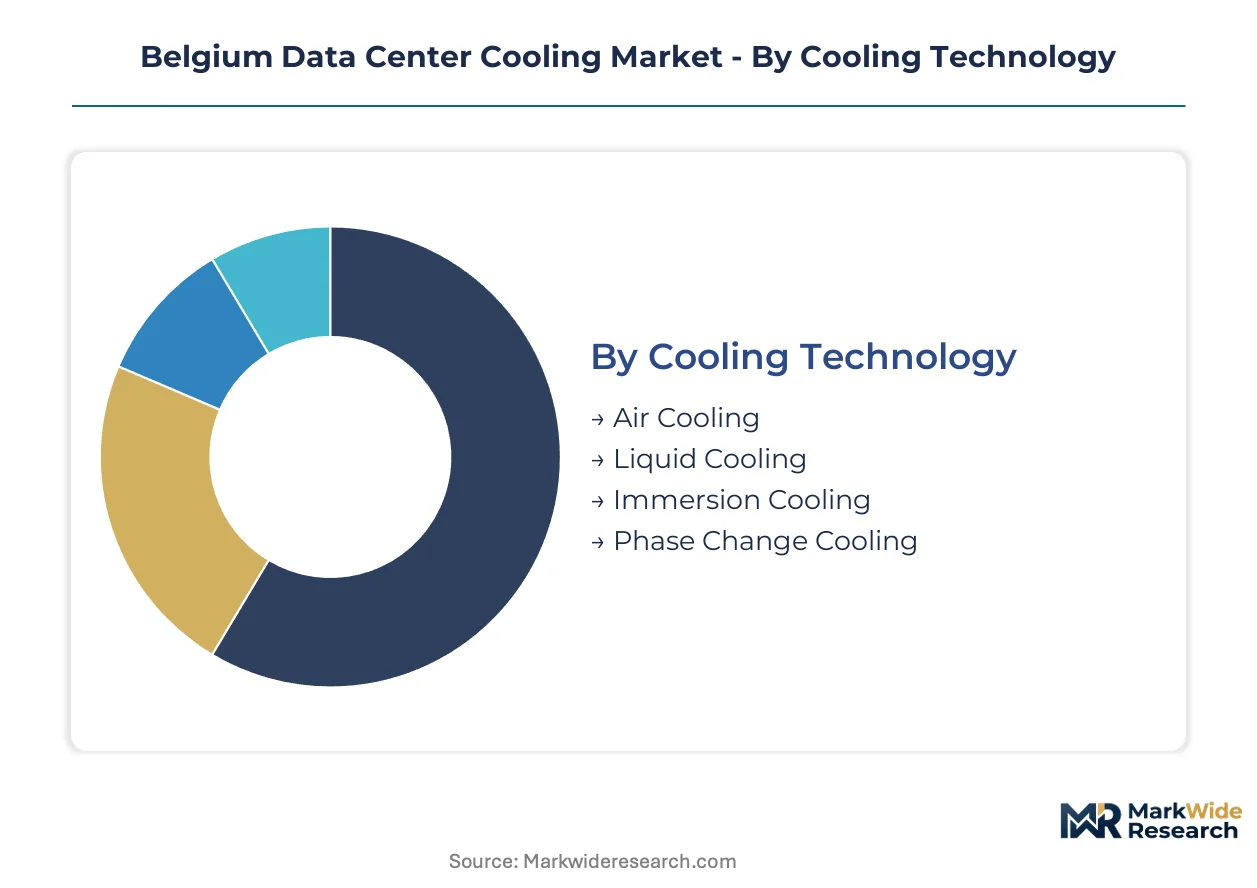
Thermal management procurement in Belgium fragments across technology maturity curves and regulatory exposure levels. Cooling technology selection now determines facility compliance trajectories under Flanders' EPB standards and federal green procurement rules.
Cooling Technology:
Substitution pressure from GPU-intensive AI workloads is compressing air cooling's addressable market while elevating liquid and immersion alternatives from niche to mainstream specification.
- Liquid Cooling:Direct-to-chip cold plates circulate dielectric fluid through micro-channel heat exchangers bonded to processor packages. Brussels-Capital hyperscale facilities specify these systems for AI training clusters where rack densities exceed 75 kW, driven by EU Energy Efficiency Directive PUE thresholds that disqualify air-only architectures.
- Air Cooling:Precision air handlers and hot-aisle containment systems modulate server inlet temperatures through conditioned air distribution. Legacy enterprise colocation in Flanders retains this technology where replacement cycles extend past seven years and capital constraints delay liquid cooling retrofits.
- Immersion Cooling:Dielectric fluid completely submerges server assemblies, eliminating fans and enabling heat capture at the source for district heating integration.
- Phase Change Cooling:Refrigerant evaporation within sealed server enclosures absorbs latent heat at the chip surface.
Air cooling anchors the volume base while liquid cooling gains share at the steepest rate.
End User:
Procurement scale and performance guarantees separate hyperscale operators from constrained enterprise budgets.
- Cloud Service Providers:Hyperscale operators cluster capacity near fiber interconnection points in Antwerp and Brussels-Capital, issuing separate RFPs for cooling subsystems with efficiency guarantees.
- Colocation Providers:Multi-tenant facilities balance legacy air-cooled infrastructure against liquid cooling pods for high-density clients, navigating EPB retrofit timelines that compress depreciation cycles.
- Enterprises:Single-tenant data centers in Wallonia industrial zones around Liège and Charleroi operate aging facilities with limited incumbent vendor relationships and compressed replacement timelines.
- Government Institutions:Federal green public procurement rules mandate environmental criteria that channel contracts toward heat-reuse-enabled cooling vendors.
Cloud service providers dominate capital deployment while government procurement creates preferential pathways for compliant vendors.
Cooling Type:
System architecture selection reflects free-cooling availability and refrigerant regulatory exposure under Belgium's F-Gas transposition.
- Chilled Water Systems:Centralized plants distribute conditioned water through CRAH units, enabling heat recovery for district heating networks. Brussels facilities leverage these systems to monetize waste heat under Flemish heat network regulations.
- Hybrid Systems:Integrated free-cooling and mechanical refrigeration modulate between economizer and compressor operation based on ambient conditions. Cloud providers in Flanders specify these configurations to optimize partial free-cooling utilization during temperate months.
- Direct Expansion Systems:Refrigerant-based cooling dominates smaller enterprise installations where distributed units avoid centralized plant capital.
- Evaporative Cooling:Adiabatic media precool intake air, extending economizer hours but requiring water treatment infrastructure.
Chilled water systems anchor large-facility deployment while hybrid configurations climb fastest among cloud operators optimizing for seasonal efficiency.
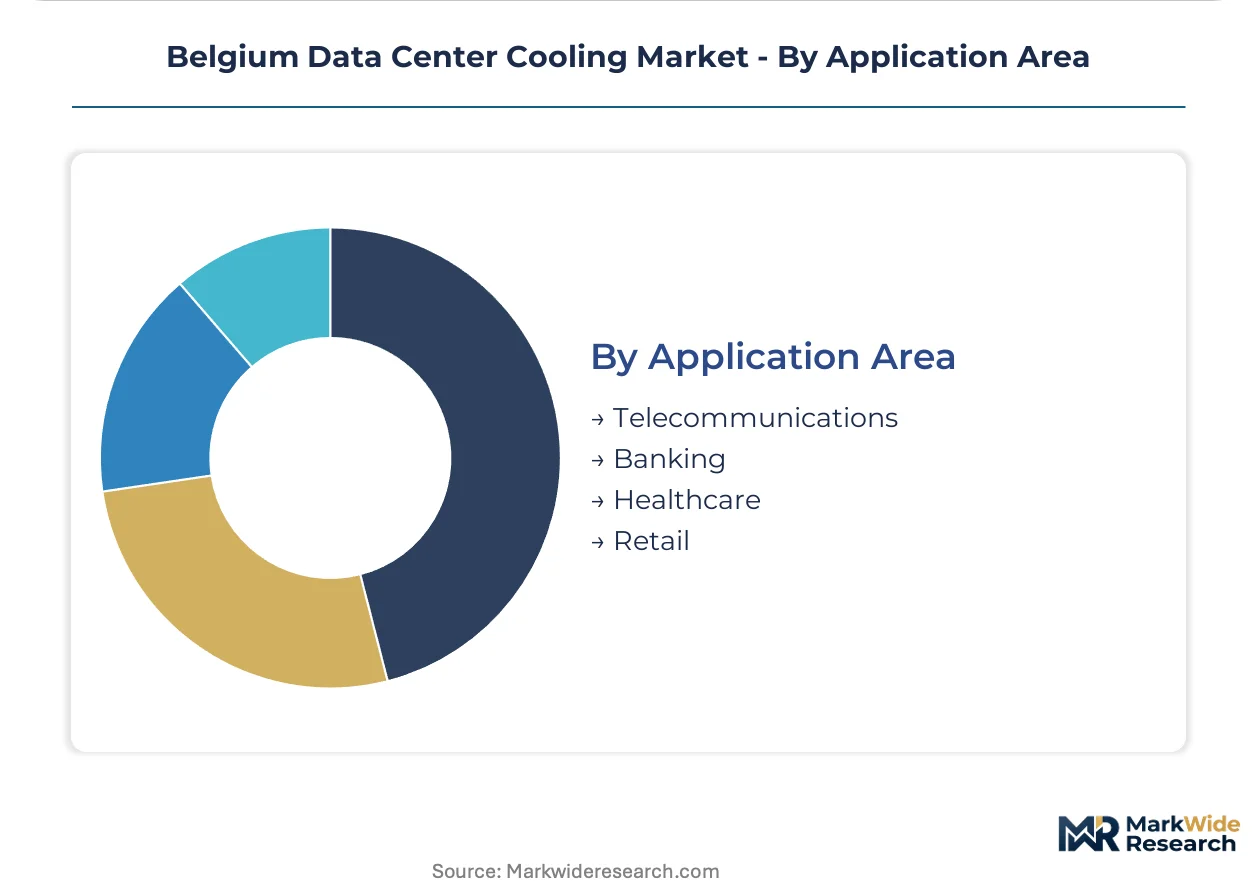
Application Area:
Workload criticality and thermal sensitivity drive specification divergence across verticals.
- Telecommunications:Edge data centers and 5G infrastructure hubs require compact, high-reliability cooling with minimal maintenance windows.
- Banking:Financial services facilities in Brussels-Capital demand precision environmental control for trading floor latency sensitivity and regulatory audit trails.
- Healthcare:Hospital data centers and medical imaging archives require continuous operation with backup redundancy for patient-critical systems.
- Retail:E-commerce fulfillment and POS transaction processing drive distributed edge cooling demand with standardized, rapidly deployable units.
Telecommunications and banking concentrate high-value specification activity while retail expands unit volume through distributed edge deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Belgian sub-regions, with Wallonia enterprise buyers deferring liquid cooling investments while Brussels-Capital hyperscale operators absorb premium thermal infrastructure costs without procurement friction.
Brussels-Capital
Federal government data center consolidation and EU institution proximity drive hyperscale clustering. Belgium's green public procurement rules mandate heat-reuse compliance for public contracts. The capital hosts the densest concentration of AI training facilities requiring direct liquid cooling above 75 kW per rack.
Flanders
Cloud service provider expansion concentrates near Antwerp's fiber interconnection points. Flanders' EPB building performance standards impose stringent envelope codes that accelerate legacy air cooling replacement cycles. Ghent and Leuven anchor R&D partnerships between cooling vendors and research institutions.
Wallonia
Industrial enterprise data centers in Liège and Charleroi operate aging facilities with compressed replacement timelines. Regional energy agencies administer EU Energy Efficiency Directive transposition with extended compliance windows for smaller operators. These zones show underpenetrated demand for hybrid cooling retrofits.
Antwerp Province
Logistics corridor positioning attracts prefabricated modular data center deployments. Proximity to North Sea wind generation enables renewable-powered thermal management. Port-adjacent facilities exploit free-cooling potential during temperate maritime months.
Belgium Data Center Cooling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-solution providers controlling hyperscale procurement while precision component vendors capture retrofit niches. The market structure compresses margins for general HVAC contractors as operators unbundle thermal management from construction contracts. Two strategic archetypes dominate: integrated infrastructure platforms with modular prefabrication capabilities, and precision cooling specialists with direct server OEM relationships. Competitive moves concentrate on R&D partnerships with Belgian research institutions and heat-reuse guarantee structures for district heating integration.
Within the integrated infrastructure tier, Schneider Electric anchors large-scale deployment positioning through its prefabricated modular portfolio, while Vertiv Group Corp. occupies a research-intensive position via partnerships with Leuven-based institutions. STULZ exemplifies the precision retrofit specialist archetype competing on compressed replacement cycles in legacy Flanders facilities.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| STULZ |
| Rittal GmbH & Co. KG |
| Alfa Laval AB |
| Danfoss |
| Carrier Global Corporation |
| Mitsubishi Electric |
| FlaktGroup |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at dielectric fluid production facilities across northwestern Europe sets price floors for liquid cooling deployments in Belgian hyperscale projects. This scale concentration amplifies procurement leverage for operators ordering direct-to-chip systems above 75 kW per rack, while compressing margins for retrofit specialists serving legacy air-cooled facilities in Flanders.
Pricing Analysis
Service contract extensions and preventive maintenance subscriptions generate lifetime value multiples exceeding three times initial equipment revenue for precision cooling vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by heat-reuse integration depth and EPB compliance certification. Cost compression in standard-tier chilled water systems is intensifying because Flemish contractors are absorbing compliance documentation costs to secure public procurement eligibility. Government institutions show lowest price sensitivity due to mandatory green criteria, while Wallonia enterprises defer upgrades amid capital constraints.
Supply Chain Analysis
Dielectric fluid inventory cycles stretching sixteen to twenty-four weeks constrain deployment velocity for immersion cooling projects in Brussels-Capital. Manufacturing concentrates in Germany, the Netherlands, and Belgium for precision air handlers, while specialty coolant production draws from a limited set of European chemical suppliers. Supply chain risk centers on single-source vulnerability for fluorinated fluids facing F-Gas quota restrictions. Distribution runs through authorized systems integrators with direct OEM relationships to hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Belgium data center cooling market constitutes a high-growth disruption as GPU-intensive AI workloads compress thermal design power thresholds below air-cooled infrastructure limits. EU Energy Efficiency Directive transposition through regional energy agencies mandates PUE thresholds that disqualify traditional cooling for new hyperscale builds.
For Market Incumbents: Fortify R&D partnerships with Leuven-based research institutions to anchor direct liquid cooling specifications before rack densities breach 100 kW. Deepen backward integration into dielectric fluid supply chains to offset allocation constraints from European chemical suppliers. Capture heat-reuse guarantee structures that transform thermal management from cost center to district heating revenue stream under Flemish network regulations. For New Entrants and Emerging Players: CE marking fast-track for low-GWP refrigerant chillers opens qualification windows ahead of F-Gas quota tightening. Target underpenetrated Wallonia enterprise retrofits around Liège and Charleroi where aging facilities face compressed replacement timelines with limited incumbent relationships. Lead with modular hybrid systems offering partial free-cooling utilization during Belgium's temperate shoulder seasons. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialist cooling vendors with direct server OEM relationships and long-term service contracts. Five-to-ten year viability favors precision component manufacturers with machining capabilities for micro-channel heat exchangers. Monitor Flemish heat network regulation amendments as the signal indicating district heating monetization viability for Brussels facility operators.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Reuse Architecture Certification | Flemish heat network regulations enable Brussels facilities to monetize waste heat through district heating contracts. |
| Direct Liquid Cooling R&D Partnership | Collaboration with Leuven-based institutions anchors specifications for AI training clusters exceeding 75 kW per rack. |
| Low-GWP Refrigerant Qualification | Belgium's F-Gas transposition phases down hydrofluorocarbon quotas, requiring natural refrigerant alternatives. |
| Prefabricated Modular Deployment | Antwerp logistics corridor positioning enables rapid hyperscale capacity expansion near fiber interconnection points. |
| EPB Compliance Documentation Investment | Flanders' building performance standards mandate envelope and mechanical codes that accelerate replacement cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with data center facility managers, thermal systems procurement officers, HVAC contractor project directors, and regional energy agency compliance officers. Secondary validation drew from EU Energy Efficiency Directive transposition documents, Flanders EPB regulatory filings, federal green public procurement rule sets, and hyperscale operator capex disclosures. Bottom-up installation volume estimates triangulated against top-down market sizing from equipment supplier revenue attribution.
Across the analysis window, forecasts modeled cooling technology substitution curves, end-user procurement scale divergence, and regulatory compliance tier segmentation. CAGRs derived from installed base depreciation cycles, AI workload density projections, and F-Gas quota phase-down schedules. Industry-specific inputs included rack power density trajectories, district heating network expansion timelines, and dielectric fluid supply allocation constraints.
Decision-makers should treat outputs as directional under assumptions of continued GPU-intensive AI workload proliferation and stable Flemish heat network regulation; material deviation in either would warrant model refresh. Specific risk factors include dielectric fluid supply disruption, EPB standard amendment acceleration, and hyperscale operator consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market