
 Denmark Data Center Cooling Market | 2026-2036
Denmark Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Cooling Market Insights
Denmark's national energy efficiency codes for data centers is expanding operational requirements for thermal management across the country's server farm footprint. Schneider Electric SE leverages its integrated building technology portfolio to anchor large-scale projects in the Copenhagen region. Asetek A/S specializes in direct-to-chip liquid cooling systems that dominate high-performance computing installations. Alfa Laval AB extends its heat exchanger expertise into free cooling architectures suited to Denmark's temperate climate.
Data center cooling encompasses the engineered systems that regulate temperature, humidity, and airflow within facilities housing servers, storage, and networking equipment, typically operating within 18-27°C per ASHRAE thermal guidelines to prevent hardware degradation and ensure continuous uptime. Liquid cooling solutions are capturing margin pools as power densities exceed 50 kW per rack in artificial intelligence training clusters. Cloud providers represent the fastest-growing end user segment as Microsoft, Google, and Amazon Web Services expand Danish hyperscale campuses. Free cooling systems lead installation preferences where ambient conditions permit economizer operation for substantial portions of the year.
BIS and the Danish Energy Agency shape equipment efficiency standards through building code amendments and voluntary certification programs that influence procurement specifications. The EU Green Deal and national carbon neutrality commitments are forcing operators to document power usage effectiveness and transition toward lower-global-warming-potential refrigerants. Stakeholders must monitor how Denmark's district heating integration mandates for waste heat recovery alter cooling system design requirements and vendor qualification criteria.
Market Dynamics
Denmark's district heating integration mandates are forcing cooling system redesigns across Odense and Fredericia campuses, as waste heat recovery requirements alter vendor qualification criteria and equipment specifications for hyperscale operators.
Growth Catalysts
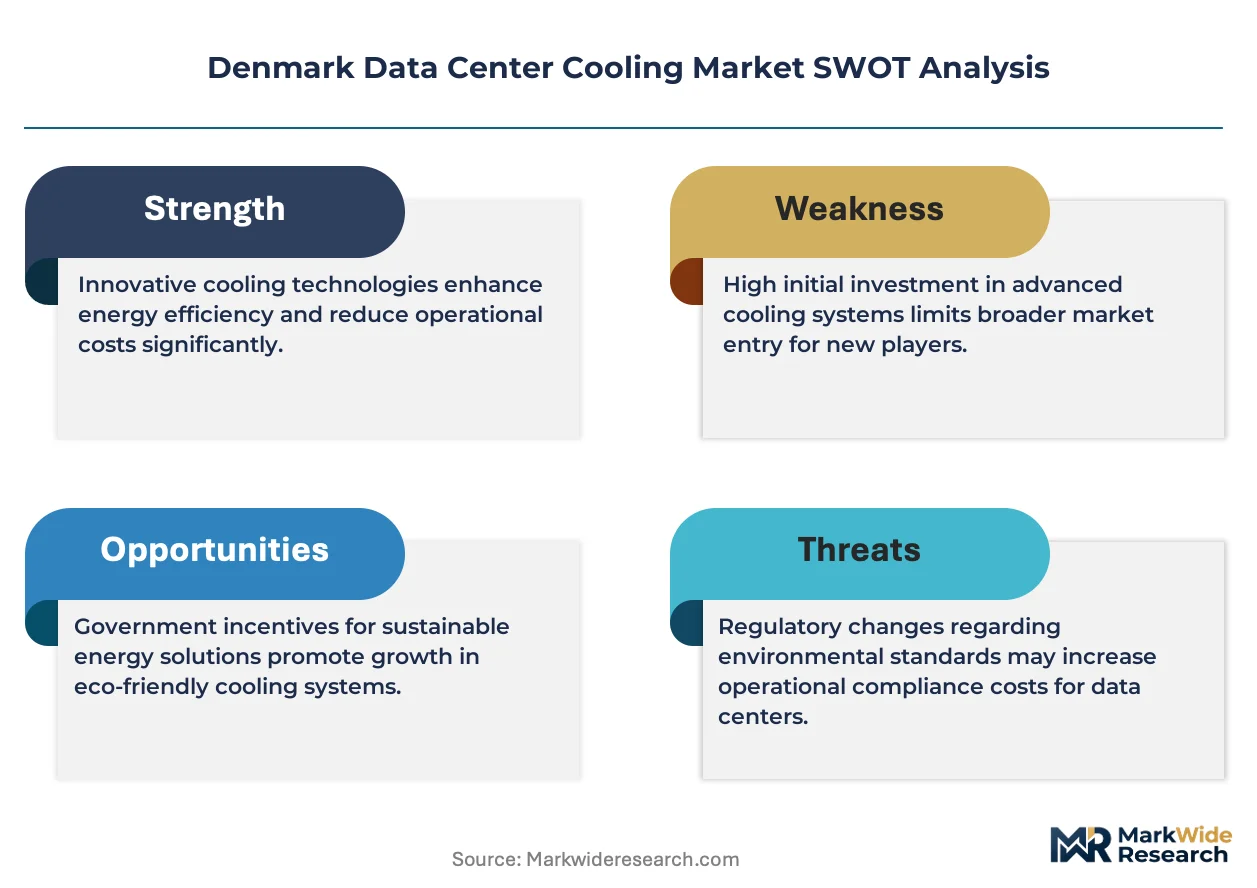
- EU Green Deal carbon neutrality commitments:Danish operators must document power usage effectiveness and transition toward lower-global-warming-potential refrigerants, creating replacement cycles for legacy infrastructure.
- Hyperscale cloud expansion:Microsoft, Google, and Amazon Web Services are commissioning multi-megawatt facilities in the Copenhagen metropolitan cluster and Jutland's renewable energy corridor.
- Direct-to-chip liquid cooling:Artificial intelligence training clusters exceeding 50 kW per rack are displacing air-cooled architectures in high-performance computing installations.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and piping fabrication costs fluctuate with commodity markets, compressing margins on fixed-price installation contracts.
- Specialized component supply concentration:Precision pumps and cold plates for liquid cooling systems source predominantly from German and Swiss precision engineering suppliers.
- F-Gas Regulation phase-down schedules:The EU's hydrofluorocarbon quota reductions limit availability of conventional refrigerants for retrofits and emergency replacements.
Strategic Opportunities
- Free cooling economizer expansion:Denmark's temperate maritime climate permits ambient air cooling for substantial portions of the year, reducing mechanical refrigeration load.
- Waste heat-to-district heating integration:Fredericia and Aarhus municipal utilities now mandate heat recovery interfaces, creating specification advantages for vendors with thermal integration expertise.
- Modular prefabrication:Factory-integrated cooling plants reduce on-site construction timelines and labor requirements for hyperscale campus rollouts.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Direct-to-chip and immersion cooling deployments require specialized expertise in two-phase heat transfer that outpaces Danish technical education output.
- Legacy air-cooled facility retrofit complexity:Existing Copenhagen-area data centers face structural constraints on floor loading and piping routing for liquid cooling conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Cooling Market |
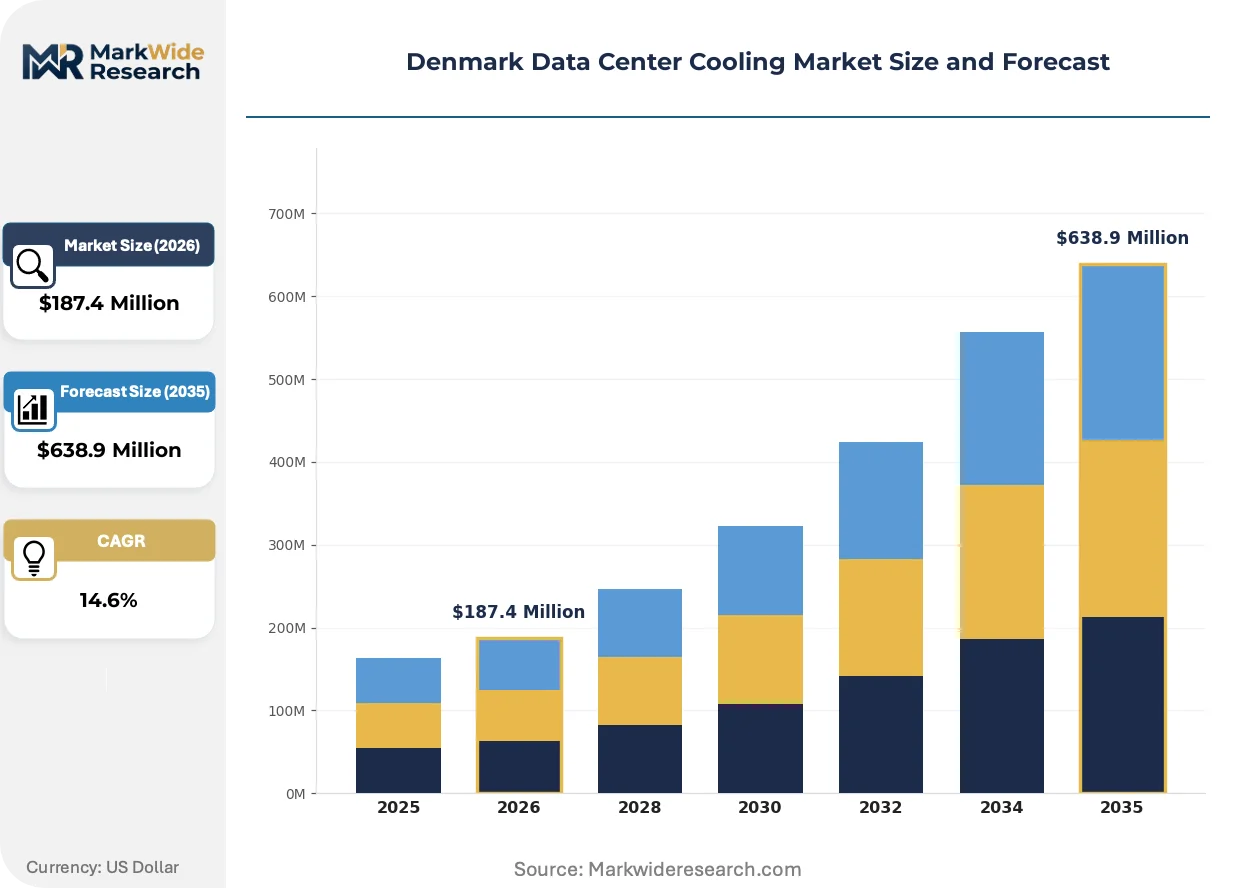
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technique: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling End User: Cloud Providers, Colocation Facilities, Enterprises, Government System Type: Chilled Water System, Direct Expansion System, Immersion Cooling, Free Cooling Installation Type: New Installation, Retrofit Installation, Modular Installation, Pre-assembled Units |
| Companies Covered | Johnson Controls International PLC, Stulz GmbH, Schneider Electric SE, Emerson Electric Co, Daikin Applied Europe S.p.A., Vertiv Group Corp, Asetek A/S, Alfa Laval AB, Rittal GMBH & Co KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are consolidating market position as power densities escalate, while regulatory pressure on refrigerants and waste heat recovery accelerates equipment replacement cycles across Danish facilities.
Direct-to-chip liquid cooling is consolidating its position in artificial intelligence training infrastructure. Hyperscale operators in Odense are specifying cold plate systems as standard for racks above 30 kW. This technology is consolidating supplier relationships around vendors with integrated pumping and heat rejection capabilities.
The EU F-Gas Regulation and Denmark's national energy efficiency codes are tightening operational requirements for thermal management. Equipment procurement specifications now mandate lower-global-warming-potential refrigerants and documented power usage effectiveness ratios. Colocation providers in the Copenhagen metropolitan cluster are responding with accelerated replacement of legacy chillers.
Buyers are unbundling cooling infrastructure from general construction contracts and sourcing directly from specialized thermal management vendors. Hyperscale operators now engage Asetek and Schneider Electric for direct procurement, bypassing traditional mechanical contractors. This pattern is most visible in Fredericia's new campus developments where owners self-perform equipment specification and commissioning.
Denmark Data Center Cooling Market Segmentation
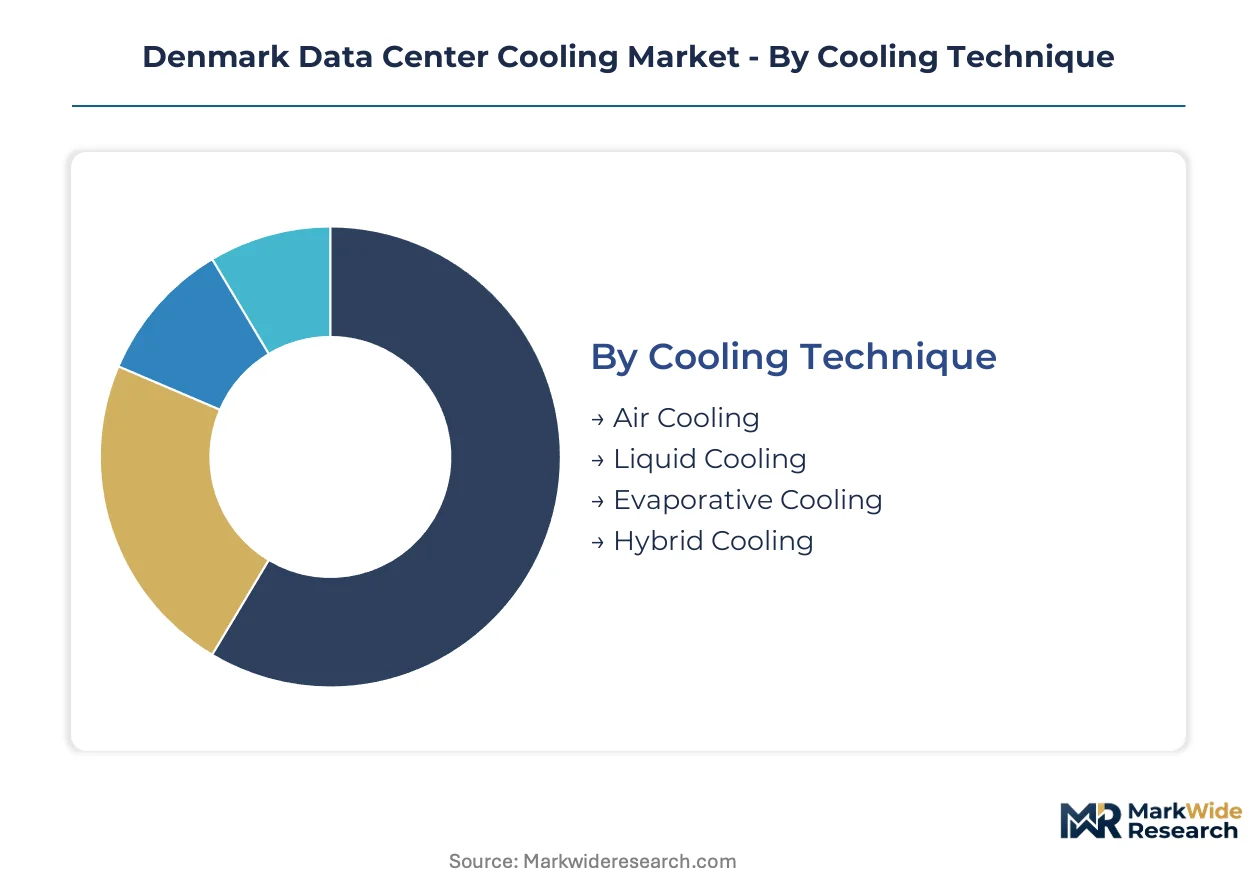
Segmentation reveals how Denmark's data center cooling demand fragments across competing thermal architectures and procurement models. Each dimension exposes distinct vendor qualification requirements and margin structures that shape competitive positioning.
Cooling Technique:
Supply concentration in liquid cooling components is reshaping procurement patterns for high-density deployments.
- Liquid Cooling:Direct-to-chip and immersion architectures circulate dielectric fluid or water-glycol mixtures to capture heat at the processor level. Odense's AI training clusters above 50 kW per rack are standardizing on cold plate systems from specialized vendors.
- Air Cooling:Conventional raised-floor designs with computer room air handlers remain prevalent in legacy Copenhagen facilities where structural constraints limit piping retrofits.
- Evaporative Cooling:Adiabatic systems leverage Denmark's maritime humidity levels to extend free cooling hours beyond pure air-side economizers.
- Hybrid Cooling:Integrated architectures combine mechanical refrigeration with economizer modes to optimize across seasonal ambient variations.
Liquid cooling absorbs the bulk of installed capacity in new hyperscale builds; hybrid configurations are expanding most quickly as operators seek operational flexibility.
End User:
Cost tier differentiation separates specification requirements across buyer categories with divergent technical sophistication.
- Cloud Providers:Microsoft, Google, and Amazon Web Services commission multi-megawatt campuses with direct vendor engagement bypassing traditional contractors. These buyers self-perform equipment specification and commissioning.
- Colocation Facilities:Copenhagen metropolitan operators face accelerated chiller replacement cycles driven by EU F-Gas Regulation mandates and tenant power usage effectiveness requirements.
- Enterprises:Private data centers in Jutland's renewable energy corridor prioritize free cooling architectures to align with corporate carbon neutrality commitments.
- Government:Public sector facilities follow BIS efficiency codes with procurement weighted toward documented lifecycle cost rather than upfront capital expenditure.
Cloud providers command the largest absolute capacity additions; colocation facilities are gaining share fastest as enterprise outsourcing accelerates.
System Type:
Application-specific thermal loads determine which heat rejection architecture delivers optimal power usage effectiveness.
- Free Cooling:Air-side and water-side economizers exploit Denmark's temperate climate to eliminate mechanical refrigeration for substantial annual operating hours. Fredericia municipal utilities now mandate heat recovery interfaces.
- Chilled Water System:Centralized plants with variable-primary pumping serve large campus deployments where thermal storage and district heating integration create operational synergies.
- Direct Expansion System:Refrigerant-based split systems persist in smaller edge facilities and legacy retrofits where chilled water infrastructure proves capital-prohibitive.
- Immersion Cooling:Two-phase dielectric baths capture heat from entire server assemblies, emerging in experimental deployments for cryptocurrency and AI inference workloads.
Free cooling dominates new construction specifications; immersion cooling shows the steepest expansion trajectory as power densities escalate.
Installation Type:
Customer type and project urgency dictate whether owners favor site-built, prefabricated, or retrofit delivery models.
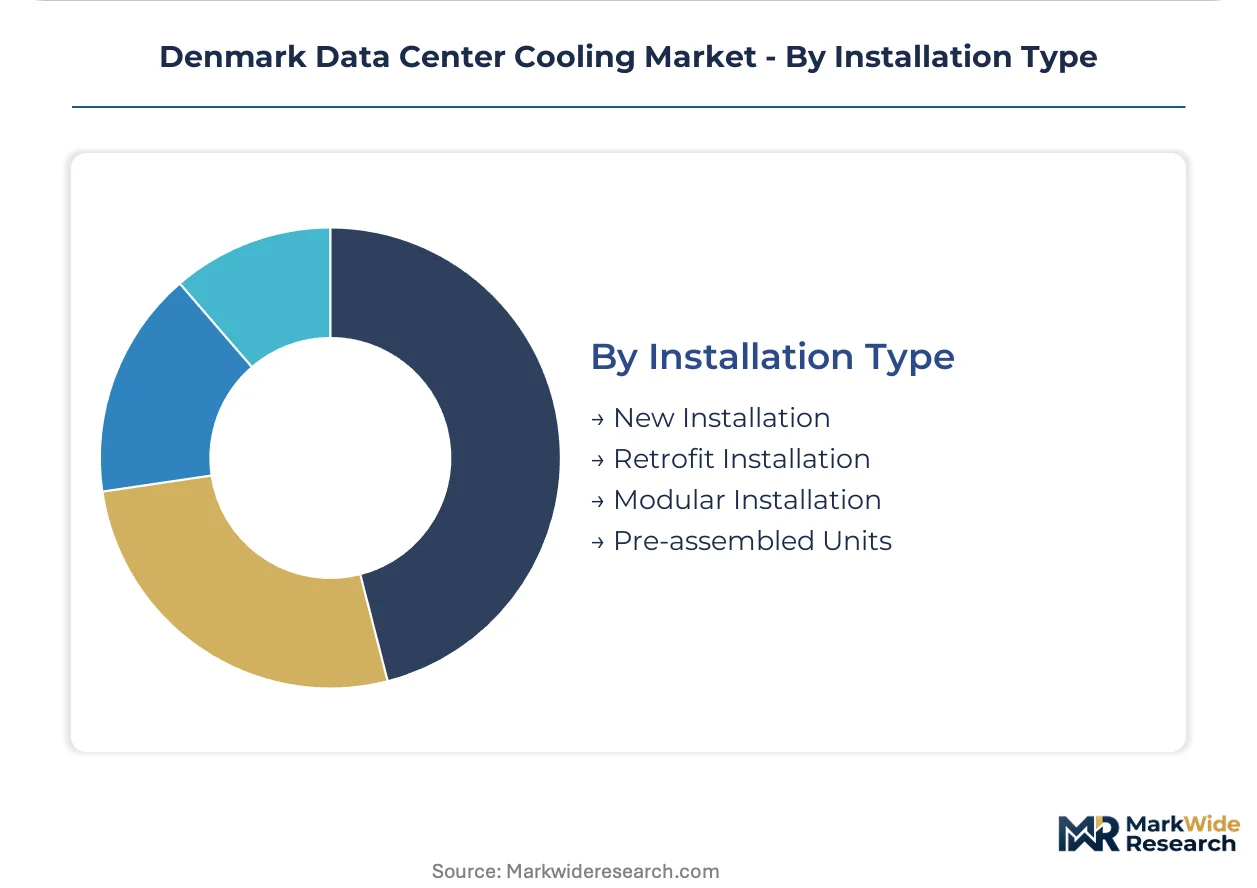
- Modular Installation:Factory-integrated cooling plants reduce on-site construction timelines for hyperscale campus rollouts in Odense and Fredericia. These units arrive with pre-tested piping and controls.
- New Installation:Greenfield developments in Jutland's renewable energy corridor specify liquid-ready infrastructure from foundation design to accommodate future density upgrades.
- Retrofit Installation:Existing Copenhagen-area facilities face structural constraints on floor loading and piping routing when converting from air-cooled to liquid-cooled architectures.
- Pre-assembled Units:Skid-mounted chillers and pumping packages accelerate deployment for colocation providers facing tenant-driven commissioning deadlines.
Modular installations capture the majority of hyperscale procurement volume; retrofit projects are climbing the fastest as legacy infrastructure ages out.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen anchors Denmark's data center cooling demand through its metropolitan cluster of hyperscale campuses and colocation facilities. The Jutland peninsula extends this footprint through renewable energy corridors powering Odense and Fredericia server farms. National energy efficiency codes and EU F-Gas Regulation shape equipment specifications across both concentrations.
Capital Region
Greater Copenhagen concentrates Microsoft's expanding Danish hyperscale campus alongside Google and Amazon Web Services facilities. BIS energy efficiency codes mandate documented power usage effectiveness ratios for new construction. Taastrup and Høje-Taastrup industrial zones host specialized thermal management component fabrication serving regional installations.
Region of Southern Denmark
Odense's artificial intelligence training clusters exceed 50 kW per rack, standardizing direct-to-chip liquid cooling architectures. The EU Green Deal carbon neutrality commitments accelerate chiller replacement cycles among legacy operators. Fredericia municipal utilities now mandate waste heat recovery interfaces for district heating integration.
Central Denmark Region
Aarhus anchors Jutland's renewable energy corridor with enterprise data centers prioritizing free cooling economizers. Denmark's national district heating integration requirements alter vendor qualification criteria for cooling system tenders. Randers and Silkeborg host precision engineering suppliers supporting liquid cooling component fabrication.
North Denmark Region
Aalborg's temperate maritime climate extends free cooling operating hours for edge and enterprise facilities. F-Gas Regulation phase-down schedules limit conventional refrigerant availability for retrofits across northern Jutland. The city harbors specialized heat exchanger engineering expertise serving national cooling infrastructure projects.
Region Zealand
Køge and Roskilde support Copenhagen's overflow demand through modular prefabricated cooling plant deployments. National building code amendments for data center thermal management influence procurement specifications. Næstved hosts logistics infrastructure distributing specialized pumps and cold plates to installation sites nationwide.
Denmark Data Center Cooling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology specialization spectrum, with integrated building technology vendors commanding pricing power over component suppliers. The market structures around three tiers: global multi-technology conglomerates with full thermal portfolios, specialized liquid cooling engineering firms, and regional HVAC contractors. Consolidation pressure intensifies as hyperscale operators bypass traditional mechanical contractors for direct vendor engagement. Strategic moves center on modular prefabrication capabilities and district heating integration expertise.
Among Denmark-based specialists, Asetek A/S anchors the direct-to-chip liquid cooling tier with engineering heritage in high-performance computing thermal management. Schneider Electric SE occupies the integrated building technology position, leveraging multinational scale to capture large-scale Copenhagen metropolitan projects. Alfa Laval AB exemplifies the heat transfer engineering archetype, extending industrial exchanger expertise into free cooling architectures suited to Nordic climate conditions. Stulz GmbH represents German precision climate control engineering, while Vertiv Group Corp and Emerson Electric Co sit within the critical infrastructure power and cooling conglomerate tier serving multi-technology procurement patterns.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Stulz GmbH |
| Schneider Electric SE |
| Emerson Electric Co |
| Daikin Applied Europe S.p.A. |
| Vertiv Group Corp |
| Asetek A/S |
| Alfa Laval AB |
| Rittal GMBH & Co KG |
| Others |
Pricing and Supply Chain Analysis
Performance-certified liquid cooling systems command substantial premiums over conventional air-cooled infrastructure, and this divergence manifests in both procurement economics and supplier qualification pathways across Danish hyperscale developments. EU F-Gas Regulation compliance tiers and power usage effectiveness documentation requirements create pricing ladders that reward vendors with integrated thermal management portfolios, while commodity heat exchanger suppliers face margin compression from volatile copper and aluminum input costs.
Pricing Analysis
Value-based pricing anchored to guaranteed uptime and documented power usage effectiveness ratios dominates hyperscale procurement contracts in Odense and Fredericia. Three-tier pricing structure across premium, standard, and economy levels separates integrated building technology vendors with district heating integration capabilities from component suppliers and regional HVAC contractors. Cost compression in the standard tier is intensifying because hyperscale operators now self-perform equipment specification and bypass traditional mechanical contractors. Cloud providers exhibit the least price sensitivity given total-cost-of-ownership frameworks, while colocation facilities in Copenhagen face tenant-driven pressure on capital recovery timelines.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for liquid cooling systems, while traditional distribution runs through mechanical contractors serving enterprise and government segments. Precision pumps and cold plates for direct-to-chip systems draw from German and Swiss precision engineering suppliers, with heat exchanger fabrication anchored in Nordic industrial zones. Copper and aluminum commodity volatility creates margin risk for fixed-price installation contracts. Single-source vulnerability concentrates in specialized two-phase heat transfer components where Danish technical education output lags deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's data center cooling market operates as a cost-of-compliance story where EU F-Gas Regulation phase-down schedules and national district heating integration mandates erect barrier-to-entry moats for vendors with certified refrigerant portfolios and thermal integration expertise.
For Market Incumbents: Acquire modular prefabrication capabilities to compress on-site construction timelines for hyperscale campus rollouts in Odense and Fredericia. Backward integration into precision pump and cold plate production reduces exposure to German and Swiss supplier concentration. District heating integration expertise represents the priority defensive lever as Fredericia and Aarhus municipal utilities mandate waste heat recovery interfaces. For New Entrants and Emerging Players: Edge computing facilities in North Denmark Region's Aalborg corridor represent an underserved buyer archetype with extended free cooling operating hours and lower technical barriers to entry. Cryptocurrency and AI inference workloads requiring immersion cooling experimental deployments offer white-space penetration with reduced incumbent saturation. Direct vendor engagement models bypassing traditional mechanical contractors provide the most viable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with specialized liquid cooling engineering firms given direct-to-chip standardization for racks above 30 kW across Danish AI training clusters. Long-term viability over a five-to-ten year window favors vendors with integrated pumping, heat rejection, and district heating interface capabilities. The signal to watch is accelerated chiller replacement cycles among Copenhagen metropolitan colocation providers responding to tenant power usage effectiveness requirements.| Strategic Initiative | Industry Significance |
|---|---|
| District Heating Integration Partnership | Fredericia municipal utility mandates create specification advantages for compliant thermal vendors. |
| Modular Prefabrication Scale-Up | Factory-integrated cooling plants reduce hyperscale deployment timelines across Odense campuses. |
| Lower-GWP Refrigerant Transition | EU F-Gas Regulation compliance secures vendor qualification for legacy chiller replacement cycles. |
| Direct-to-Chip Liquid Cooling Specialization | Cold plate standardization for 50 kW racks captures premium margins in AI infrastructure. |
| Waste Heat Recovery Interface Development | National energy efficiency codes alter cooling system design requirements and procurement specifications. |
Research Methodology
Independent corroboration across facility engineering directors, hyperscale procurement officers, municipal utility planners, and precision component suppliers underwrites the qualitative findings in this analysis. Primary interviews with thermal management vendors, district heating network operators, and data center construction contractors combined with secondary validation from BIS efficiency code documentation, EU F-Gas Regulation filings, Danish Energy Agency reports, and hyperscaler capital expenditure disclosures. Bottom-up installation volume tracking and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical deployment data across Copenhagen metropolitan cluster and Jutland renewable energy corridor developments establishes the forecast baseline. Segmentation dimensions modeled include cooling technique, end user archetype, system type, and installation delivery model, with power density thresholds and regulatory compliance tiers as industry-specific forecast inputs. CAGRs were derived through trend extrapolation adjusted for technology substitution patterns and policy-driven replacement cycle acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and aluminum commodity volatility, specialized thermal-fluid engineering talent scarcity, and potential amendments to Denmark's district heating integration mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market