
 Middle East District Cooling Market | 2026-2036
Middle East District Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East District Cooling Market Analysis
ISO 50001 energy management certification is unwinding competitive access across the Middle East district cooling sector. Emirates Central Cooling Systems Corporation leverages its installed base across Dubai to sustain operational economies. Tabreed anchors long-term concessions in Saudi Arabia's emerging economic zones. ADC Energy Systems competes through specialized chilled water distribution engineering in high-density developments.
District cooling delivers centralized air conditioning through insulated piping networks distributing chilled water or secondary refrigerant at temperatures typically between 4°C and 7°C, serving multiple buildings from a shared plant room. Chilled water distribution remains the dominant technology architecture across Gulf Cooperation Council installations. Commercial buildings command the deepest service-type margin pools, particularly in operation and maintenance contracts spanning twenty-year concession periods. New construction installations outpace retrofitting volumes across Riyadh and Dammam master plans.
Saudi Building Code and UAE's Estidama Pearl Rating System impose thermal performance thresholds that filter project eligibility. Dubai Supreme Council of Energy mandates district cooling integration for developments exceeding specified plot ratios. Stakeholders must monitor evolving concession frameworks and carbon intensity benchmarks as Gulf utilities regulators tighten performance accountability without prescribing specific compliance deadlines.
Market Dynamics
Saudi Building Code energy efficiency mandates and Dubai Supreme Council of Energy integration requirements are compressing project timelines and filtering vendor eligibility across Gulf Cooperation Council developments.
Growth Catalysts
- Mega-hotel developments:Arabian Gulf corridor hospitality projects anchor end-use expansion through centralized plant specifications serving multiple towers from single chilled water sources.
- Estidama Pearl Rating System:UAE's thermal performance thresholds filter project eligibility toward district cooling architecture in high-density master plans.
- Chilled water distribution:This technology architecture dominates GCC installations due to operational economies across twenty-year concession periods.
Market Restraints
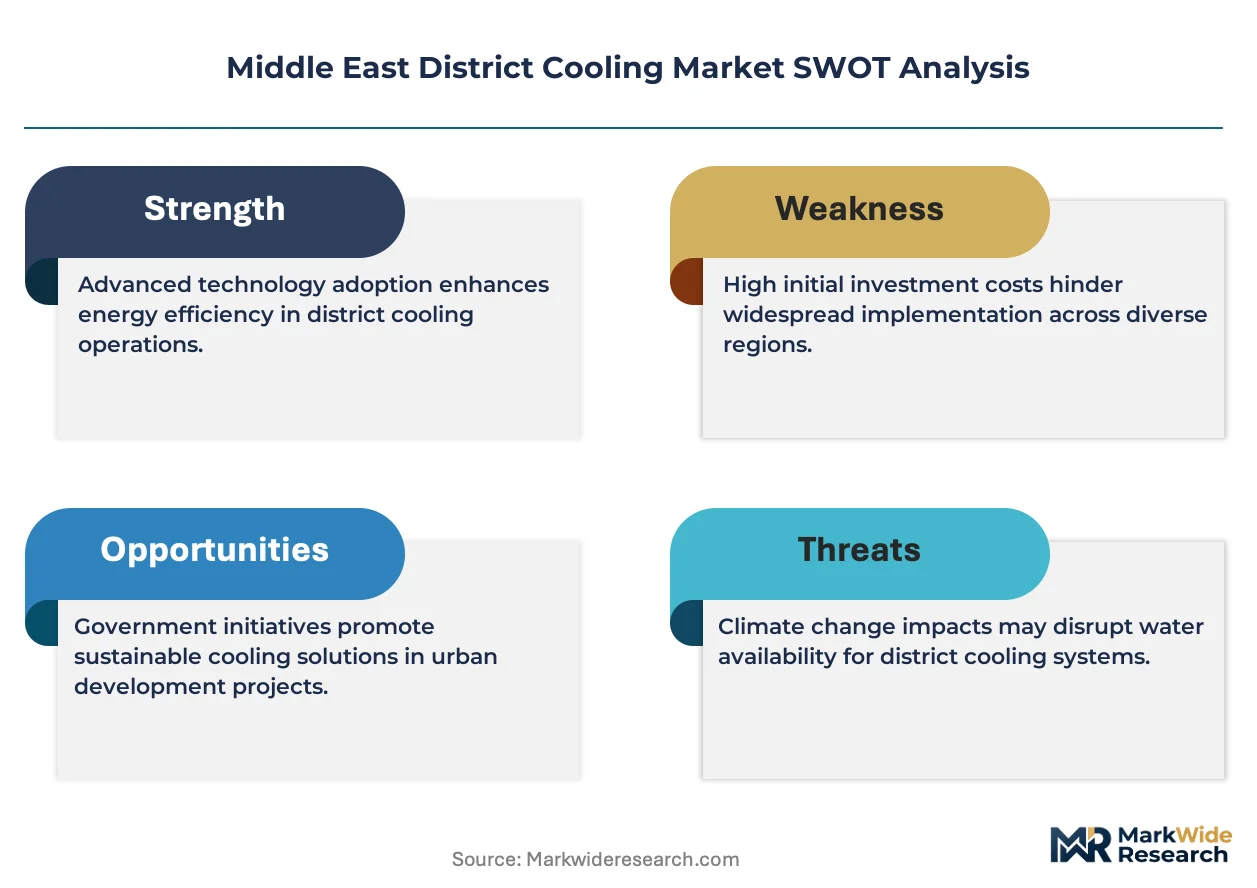
- Capital intensity:Insulated piping networks and centralized plant rooms require substantial upfront investment before revenue generation begins.
- Retrofit limitations:Existing building stock in Riyadh and Dammam presents technical barriers to chilled water integration compared to new construction.
- Regulatory uncertainty:Gulf utilities regulators tighten carbon intensity benchmarks without prescribing specific compliance deadlines, creating planning friction.
Strategic Opportunities
- King Abdullah Financial District:Riyadh's emerging economic zone presents underpenetrated demand for long-term concession arrangements.
- ISO 50001 certification:Energy management standards create competitive access differentiation for operators demonstrating measurable efficiency gains.
- Operation and maintenance contracts:Service-type margin pools deepen as twenty-year concession periods extend revenue visibility for specialized providers.
Industry Challenges
- Concession framework complexity:Evolving regulatory structures across multiple emirates and Saudi economic cities require specialized legal and financial structuring capabilities.
- Integration with legacy systems:Standalone air conditioning infrastructure in existing commercial buildings resists connection to centralized chilled water networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East District Cooling Market |
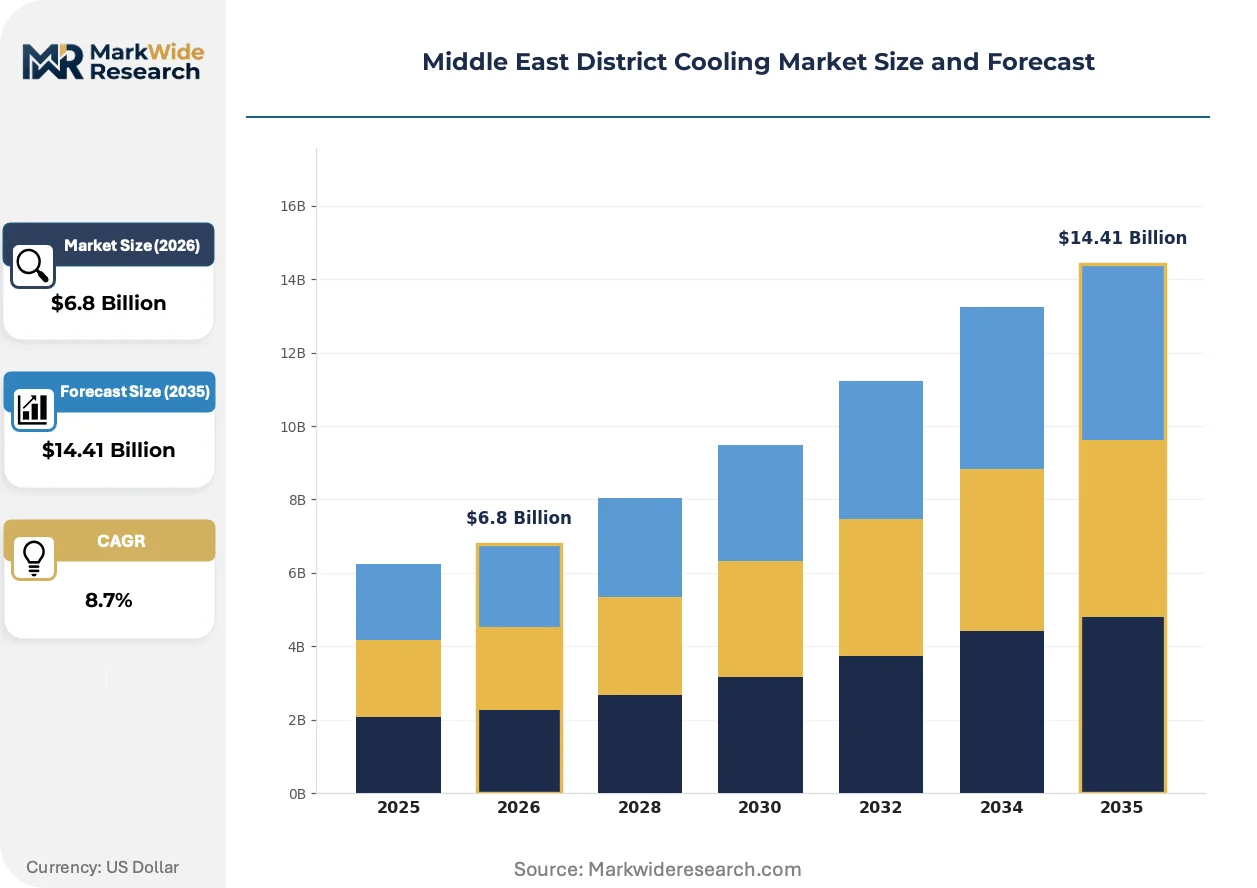
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ice Storage, Chilled Water Distribution, Pumped Thermal Energy, Air Cooled Chilliers End User: Residential Complexes, Commercial Buildings, Hotels, Industrial Facilities Installation: New Construction, Retrofitting, Upgradation, Expansion Service Type: Operation & Maintenance, System Design, Energy Management, Consulting |
| Companies Covered | Danfoss, ADC Energy Systems, Emirates Central Cooling Systems Corporation (Empower), Keppel Corporation Limited, Shinryo Corporation, National Central Cooling Company (Tabreed), Daikin Industries, Araner, Veolia, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East District Cooling Market Emerging Trajectories
Technology convergence and regulatory tightening are reshaping competitive positioning across Middle East district cooling, with efficiency certification and procurement model evolution emerging as primary differentiators.
Variable primary flow systems with intelligent pumping controls are displacing constant-volume chilled water distribution in Dubai South developments. Large-scale mixed-use projects adopt these configurations to reduce pumping energy by modulating flow against actual cooling load rather than design peak. This displacement compresses operational expenditure profiles and extends concession period profitability for plant operators.
UAE's Estidama Pearl Rating System imposes thermal performance thresholds that filter project eligibility toward district cooling architecture. Developers seeking Pearl 2 or higher ratings must demonstrate centralized plant efficiency advantages over standalone systems. Commercial building segments in Abu Dhabi respond by embedding district cooling specifications into early master planning stages rather than retrofitting later.
Long-term concession contracting is consolidating buyer relationships around twenty-year operation and maintenance commitments. Master developers in Saudi Arabia's economic zones favor this structure over capital purchase models, transferring operational risk to specialized cooling providers. Riyadh's King Abdullah Financial District exhibits this pattern most visibly, with bundled construction-plus-operation agreements displacing fragmented procurement.
Middle East District Cooling Market Segmentation
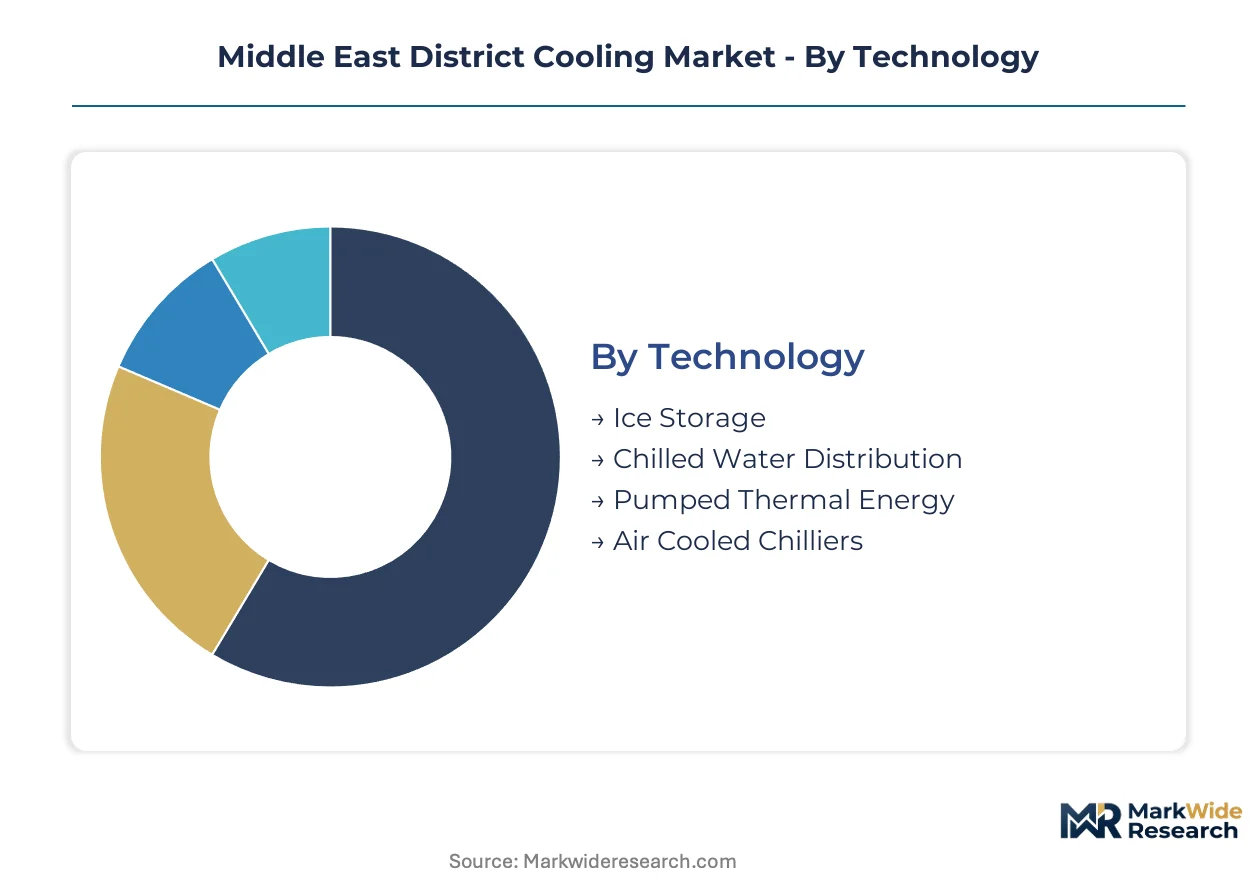
District cooling procurement in the Middle East fragments across technology architectures, end-use applications, and service delivery models. Understanding these segment boundaries reveals where capital deployment concentrates and which operational capabilities command premium positioning across Gulf Cooperation Council developments.
Technology:
Geographic deployment patterns vary sharply across these architectures, with some configurations dominating domestic Gulf installations while others serve export-oriented engineering specifications.
- Chilled Water Distribution:Insulated piping networks circulate water at 4°C to 7°C from centralized plants to multiple buildings. Demand concentrates in Dubai South and Riyadh's King Abdullah Financial District, where master developers favor proven twenty-year operational track records over experimental configurations.
- Ice Storage:Thermal energy banks shift cooling production to off-peak electricity periods, reducing demand charges. Abu Dhabi's Estidama Pearl-rated developments increasingly specify ice storage to meet thermal performance thresholds while managing grid load profiles.
- Pumped Thermal Energy:Emerging mechanical storage systems using reversible heat pumps. Pilot installations in Saudi economic cities test grid-scale flexibility applications.
- Air Cooled Chillers:Standalone refrigeration units deployed where water scarcity or space constraints prevent evaporative cooling towers. Remote industrial zones in Oman and Bahrain deploy these for operational simplicity.
Chilled water distribution holds the largest share; momentum sits with ice storage as regulatory thermal performance thresholds tighten.
End User:
Margin structures diverge significantly across these customer categories, with some segments demanding bundled long-term concessions while others accept transactional service arrangements.
- Commercial Buildings:Office towers and retail complexes generate the deepest operation and maintenance contract pools. Dubai's business district developments anchor this segment through bundled twenty-year concession structures that transfer operational risk to specialized providers.
- Hotels:Mega-hotel developments along the Arabian Gulf corridor require redundant cooling capacity for 24/7 hospitality operations. Saudi Arabia's Red Sea Project and Qiddiya entertainment zones drive specification volumes for multi-tower centralized plants.
- Residential Complexes:Master-planned communities with consistent cooling density profiles. Supply concentrates in high-rise clusters where distribution network economies outweigh standalone unit costs.
- Industrial Facilities:Process cooling and controlled environment manufacturing. Petrochemical adjacencies in Jubail and Yanbu create specialized demand for high-capacity, high-reliability configurations.
Commercial buildings command the most stable revenue streams; hotels are climbing the fastest as hospitality mega-projects multiply across Saudi economic zones.
Installation:
Project origination channels split between greenfield master planning and existing building adaptation, with sharply different technical barriers and procurement timelines.
- New Construction:District cooling integration at master planning stage enables optimized plant sizing and routing. Dubai Supreme Council of Energy mandates drive automatic inclusion for developments exceeding specified plot ratios.
- Retrofitting:Technical barriers include structural constraints on piping routes and disruption to occupied buildings. Riyadh and Dammam present limited retrofit volumes compared to new construction pipelines.
- Upgradation:Capacity expansion and efficiency improvements to existing plants. Aging infrastructure in Dubai's older free zones creates replacement cycles for pumping and control systems.
- Expansion:Network extensions to adjacent parcels under existing concession frameworks. Tabreed and Emirates Central Cooling Systems Corporation leverage installed base proximity for organic growth.
New construction dominates current volumes; upgradation is expanding most quickly as early GCC installations reach mid-life refurbishment cycles.
Service Type:
Customer procurement preferences are shifting from capital purchase toward performance-based arrangements, reconfiguring vendor revenue models across the project lifecycle.
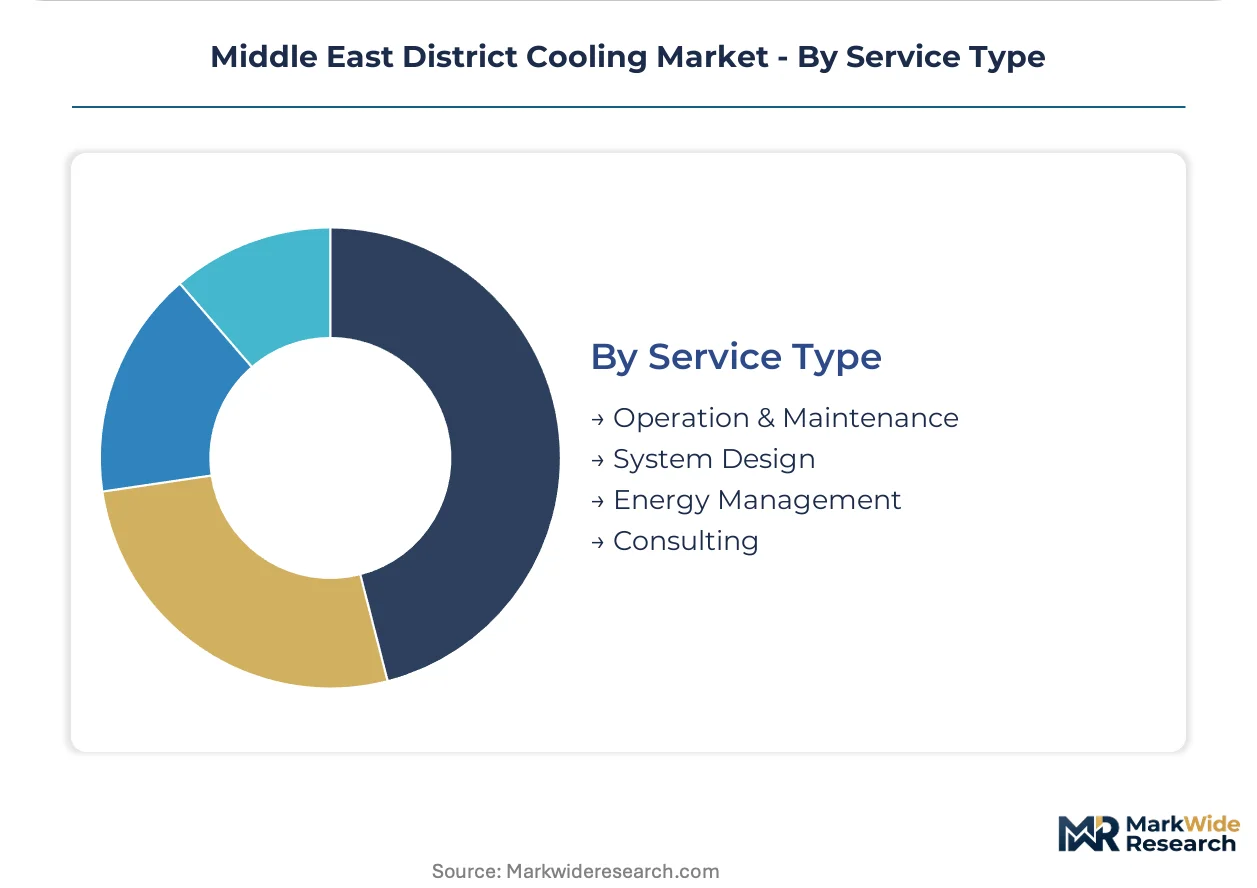
- Operation & Maintenance:Long-term service contracts spanning plant operation, network monitoring, and demand forecasting. Saudi Arabia's economic zones favor twenty-year bundled concessions over fragmented procurement.
- Energy Management:ISO 50001-certified efficiency optimization and demand response integration. Dubai South developments specify intelligent pumping controls and variable primary flow systems under performance guarantees.
- System Design:Front-end engineering for master-planned developments. ADC Energy Systems and specialized engineering firms compete on chilled water distribution optimization for high-density configurations.
- Consulting:Regulatory compliance advisory and concession structuring support. Evolving Saudi Building Code and UAE Estidama requirements create demand for specialized technical guidance.
Operation & maintenance represents the largest revenue pool; energy management is gaining share fastest as efficiency certification becomes a competitive filter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master developers and hospitality operators concentrate procurement authority across Gulf Cooperation Council jurisdictions. Saudi Arabia's economic zones and UAE's master-planned districts anchor capital deployment. Regulatory mandates from Dubai Supreme Council of Energy and Saudi Building Code reshape project specifications.
United Arab Emirates
Dubai South and Business Bay developments drive specification volumes for twenty-year concession structures. Dubai Supreme Council of Energy mandates automatic district cooling inclusion for developments exceeding specified plot ratios. Abu Dhabi's Estidama Pearl-rated master plans filter project eligibility toward centralized chilled water architecture.
Saudi Arabia
Riyadh's King Abdullah Financial District and Red Sea Project anchor mega-hotel and commercial tower demand. Saudi Building Code energy efficiency mandates compress project timelines and filter vendor eligibility toward ISO 50001-certified operators. NEOM's northwest corridor tests pumped thermal energy pilots for grid-scale flexibility applications.
Qatar
Lusail City and Msheireb Downtown Doha concentrate high-rise residential and hospitality cooling density. The country's national utility regulator imposes thermal performance benchmarks for large-scale developments. West Bay's financial district maintains stable operation and maintenance contract pools through bundled long-term concessions.
Kuwait
Sabah Al Ahmad Sea City and South Saad Al Abdullah City master plans generate new construction pipeline volumes. The Ministry of Electricity and Water sets district cooling integration guidelines for government-backed developments. Al Khiran's mixed-use corridor attracts specialized chilled water distribution engineering for high-density configurations.
Bahrain
Diyar Al Muharraq and Bahrain Bay developments concentrate commercial and residential cooling demand. The Electricity and Water Authority promotes centralized plant specifications for waterfront master plans. Manama's financial harbor district presents limited retrofit volumes compared to greenfield construction pipelines.
Middle East District Cooling Market Vendor Landscape
Player mix skews toward utility-affiliated operators and specialized engineering firms with long-term concession expertise. Market structure concentrates around entities controlling installed base proximity across Dubai and Abu Dhabi. Two strategic archetypes dominate: vertically integrated plant owners with captive distribution networks, and specialized engineering consultancies focused on front-end system design. Competitive moves center on concession framework extension and ISO 50001 certification acquisition.
Within the utility-affiliated tier, Emirates Central Cooling Systems Corporation and National Central Cooling Company anchor operational scale across UAE and Saudi economic zones. ADC Energy Systems occupies a position among specialized engineering providers focused on chilled water distribution optimization. Daikin Industries and Danfoss represent equipment supply archetypes serving plant infrastructure requirements. These entities exemplify the segmentation between concession operators and technology vendors.
| Leading Market Players |
|---|
| Danfoss |
| ADC Energy Systems |
| Emirates Central Cooling Systems Corporation (Empower) |
| Keppel Corporation Limited |
| Shinryo Corporation |
| National Central Cooling Company (Tabreed) |
| Daikin Industries |
| Araner |
| Veolia |
| Others |
Supply Flow & Price Mechanics
Centralized plant capacity utilization above eighty percent compresses unit operating costs and anchors price floors across Gulf Cooperation Council concessions. Scale economies in Dubai South and Riyadh's King Abdullah Financial District concentrate procurement leverage among vertically integrated operators, filtering smaller engineering providers toward specialized distribution design contracts.
Pricing Analysis
Cost-plus contracts with electricity tariff indexation dominate twenty-year concession structures across UAE and Saudi Arabia. Price differentiation rests on ISO 50001 certification tier and bundled after-sales service depth. Margins are tightening due to Saudi Building Code compliance costs and extended commissioning timelines. Master developers in mega-hotel projects exhibit lowest price sensitivity; retrofit commercial clients in Riyadh's older districts demonstrate highest.
Supply Chain Analysis
Strategic stockpiling of copper piping and chiller compressors prevails over just-in-time approaches given eighteen-month equipment lead times from European and East Asian manufacturers. Supply concentrates in Germany, South Korea, and China for centrifugal chillers and intelligent pumping controls. Single-source vulnerability runs through specialized insulation material providers facing UAE import documentation delays. Distribution feeds from centralized fabrication yards into project-specific site assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
District cooling incumbents must defend against distributed solar-powered absorption cooling systems that bypass centralized infrastructure entirely. Substitution threats intensify as Saudi economic zones experiment with building-integrated renewable thermal solutions.
For Market Incumbents: Shield concession renewals through ISO 50001 certification investment and captive maintenance workforce deployment. Lock master developers into exclusive twenty-year operation contracts before commissioning completion. Defend against modular solar-thermal entrants by embedding efficiency guarantees that standalone systems cannot match.
For New Entrants and Emerging Players: Differentiate on pumped thermal energy storage integration for grid flexibility services in NEOM and Saudi economic cities. Target upgradation cycles in Dubai's aging free zones where incumbent operators face mid-life refurbishment obligations. Lead with energy management consulting to establish relationships before concession competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with installed base proximity across multiple emirates. Five-to-ten-year viability hinges on concession portfolio duration rather than equipment manufacturing scale. Watch Saudi Building Code amendment timing as inflection signal for compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Acquisition | Unlocks eligibility for Saudi Building Code-mandated projects in Riyadh economic zones. |
| Twenty-Year Concession Extension | Transfers operational risk to operators while securing revenue visibility across Dubai South developments. |
| Variable Primary Flow Retrofit | Reduces pumping energy in aging Dubai plants facing mid-life efficiency benchmarks. |
| Ice Storage Capacity Addition | Enables Abu Dhabi developers to meet Estidama Pearl thermal performance thresholds. |
| Pumped Thermal Energy Pilot | Tests grid-scale flexibility applications in NEOM before broader Saudi economic zone deployment. |
Methodological Framework
Operator-level perspectives from district cooling plant managers, master developer procurement leads, Saudi Building Code compliance officers, and UAE energy regulatory staff anchored the qualitative base. Secondary validation drew from Dubai Supreme Council of Energy mandates, Saudi Building Code amendments, Estidama Pearl Rating System documentation, and Gulf Cooperation Council utilities regulatory filings. Bottom-up project pipeline enumeration triangulated against top-down market sizing from concession contract values.
Sensitivity analysis tested demand elasticity against regulatory mandate timing and electricity tariff trajectory assumptions across the projection horizon. Segmentation modeling incorporated technology architecture, end-use application, installation type, and service delivery mode dimensions. CAGRs derived from fitted growth curves against historical concession award patterns and announced master plan cooling capacity specifications.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of Saudi Building Code efficiency thresholds would require recalibration. Forecasts reflect assumptions regarding concession framework stability and grid electricity pricing continuity. Revision becomes warranted when distributed renewable thermal substitution crosses twenty percent of new cooling capacity additions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Canada Data Center Cooling Market