
 Philippines Data Center Cooling Market | 2026-2036
Philippines Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Cooling Market Insights
Aftermarket service revenue is reshaping margin capture in the Philippines data center cooling sector, pulling value away from one-time equipment sales toward long-term thermal performance contracts. Vertiv Co leverages its local service infrastructure to anchor recurring revenue streams across Manila-based facilities. Schneider Electric SE competes through integrated building-to-IT cooling platforms that extend vendor stickiness with colocation operators. Stulz GmbH specializes in precision air conditioning units engineered for tropical humidity conditions, occupying a defensible niche in mission-critical deployments.
Data center cooling encompasses the engineered systems that regulate temperature, humidity, and airflow within server environments, typically operating within ASHRAE guidelines of 18°C to 27°C dry-bulb temperature to prevent thermal throttling and hardware degradation. These systems employ vapor-compression chillers, cooling towers, and heat exchangers to reject waste heat from IT equipment into the ambient environment, with liquid-cooled and immersion configurations gaining traction as rack densities exceed 30 kW per cabinet. Air-cooled solutions still dominate installed capacity across Philippine facilities, though liquid-cooled architectures represent the fastest-growing segment as AI training clusters drive power-per-rack requirements upward. Edge data centers constitute an emerging deployment type where compact, modular cooling units command premium pricing due to remote-site service constraints and limited redundancy options.
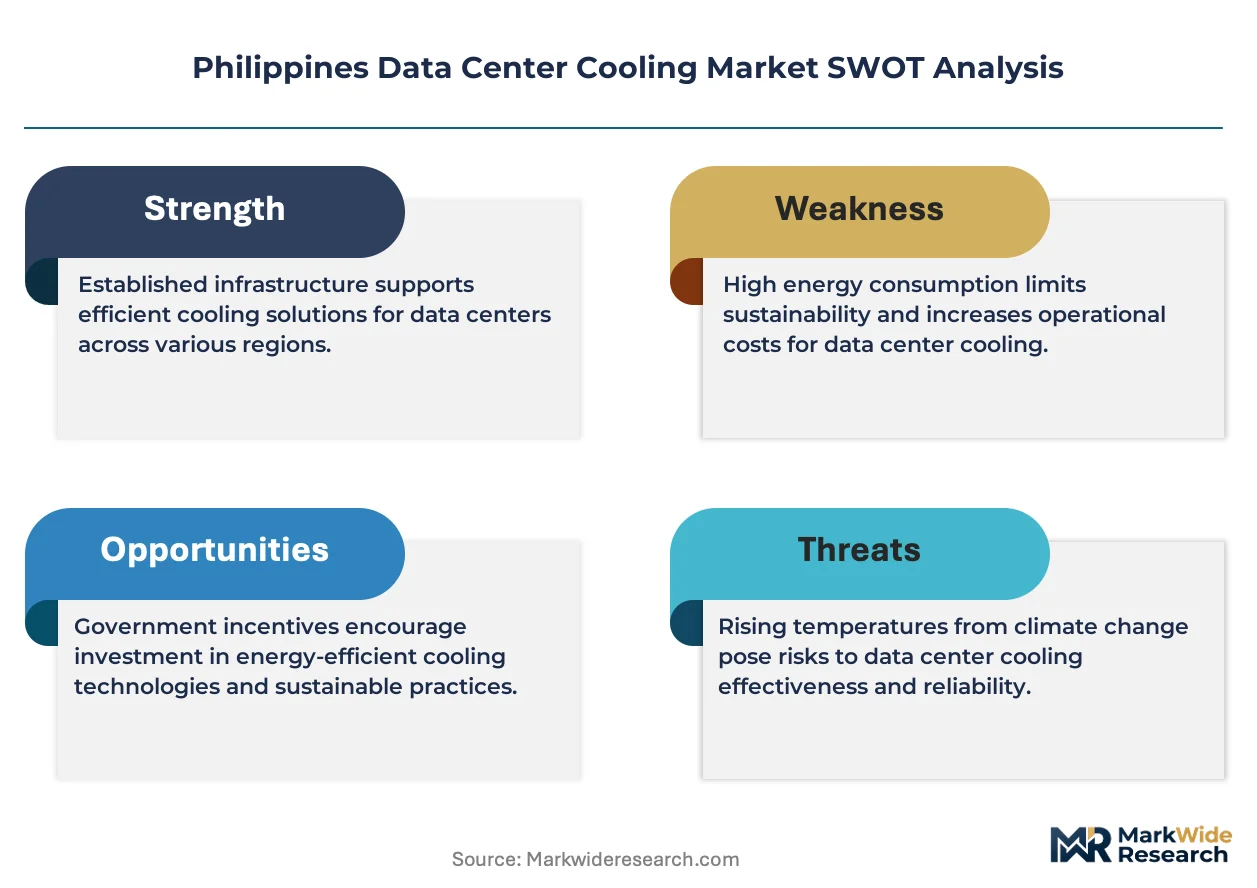
The Philippines Department of Energy enforces minimum energy performance standards for cooling equipment, while the Climate Change Commission promotes low-global-warming-potential refrigerants under national carbon reduction commitments. BIS-aligned testing protocols for chillers and air handlers shape product certification requirements for imported equipment, creating compliance barriers for non-certified suppliers. Stakeholders must monitor how evolving efficiency mandates and refrigerant phase-down schedules will reshape equipment replacement cycles and supplier qualification criteria across the archipelago.
Market Dynamics
AI training clusters are compressing thermal design cycles across Philippine facilities, forcing operators to abandon legacy air-cooled architectures before depreciation schedules complete. Rack densities exceeding 30 kW per cabinet now dominate hyperscale specifications in Metro Manila colocation builds.
Growth Catalysts
- Department of Energy efficiency mandates:Minimum energy performance standards for cooling equipment accelerate replacement of legacy chillers in Luzon-based facilities.
- Cloud service expansion:Hyperscale tenants in Metro Manila and Cebu drive demand for precision thermal management systems supporting GPU-intensive workloads.
- Tropical ambient temperatures:Sustained heat stress degrades air-cooled system efficiency, pushing operators toward liquid-cooled and hybrid architectures.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger fabrication costs fluctuate with commodity markets, compressing equipment margins for local distributors.
- Imported equipment dependency:BIS-aligned certification requirements create compliance barriers for non-certified suppliers, concentrating supply among established multinationals.
- Liquid cooling technical limitation:Immersion systems require specialized facility infrastructure incompatible with legacy raised-floor designs, constraining retrofit adoption.
Strategic Opportunities
- Cebu secondary market:Emerging hyperscale builds outside Metro Manila offer first-mover positioning for modular cooling system providers.
- Low-GWP refrigerant transition:Climate Change Commission carbon reduction commitments create replacement demand for chiller fleets using phased-down refrigerants.
- Edge deployment channel:Remote-site data centers with limited redundancy options command premium pricing for compact, service-integrated cooling units.
Industry Challenges
- Thermal engineering talent scarcity:Liquid-cooled system design and commissioning expertise remains concentrated among a limited pool of specialists in Metro Manila.
- ASHRAE compliance timeline:Certification testing for tropical-humidity-rated precision air conditioning units extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Cooling Market |
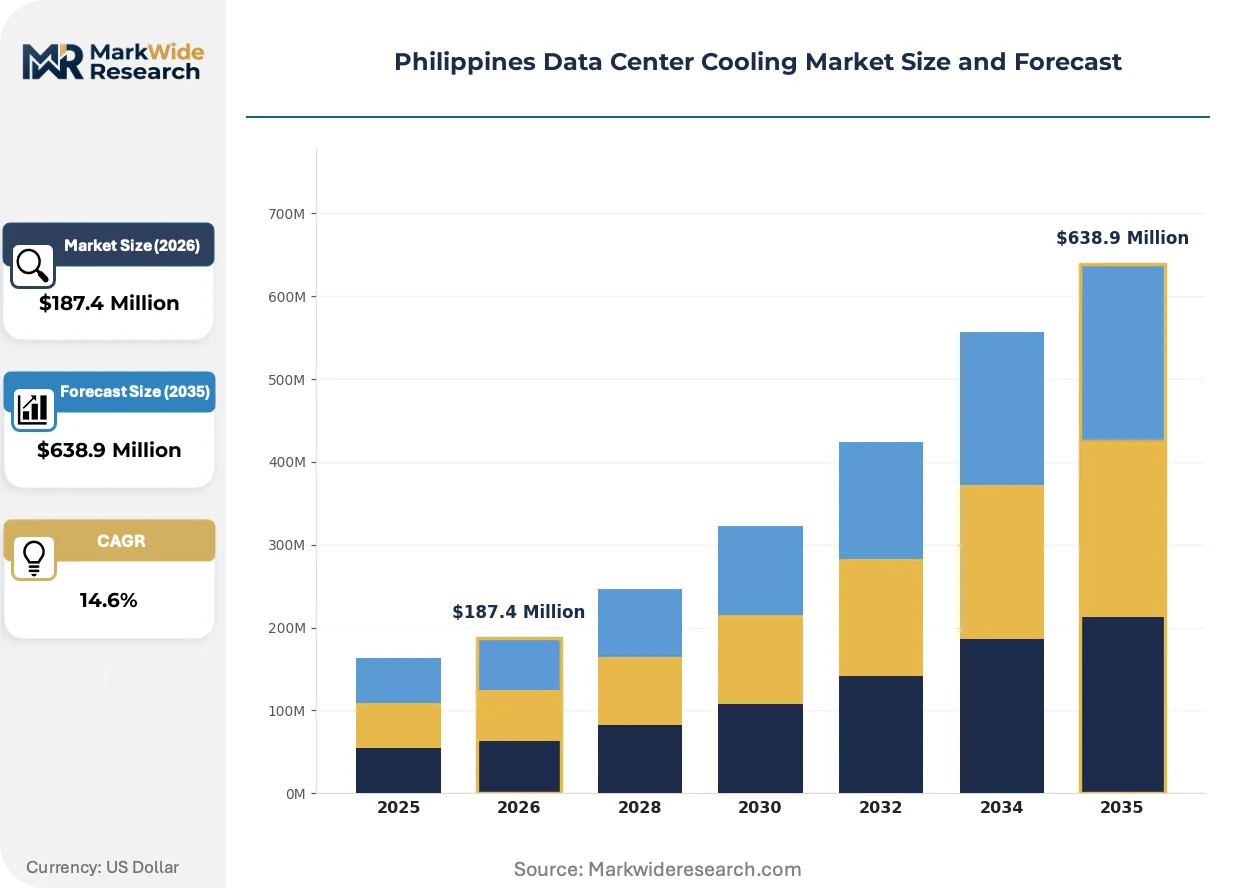
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Air-Cooled, Liquid-Cooled, Hybrid Cooling, Immersion Cooling Component: Chillers, Cooling Towers, Air Handlers, Heat Exchangers End User: IT Service Providers, Telecom Companies, Financial Institutions, Cloud Services Deployment Type: On-Premise, Colocation, Edge Data Centers, Managed Services |
| Companies Covered | Vertiv Co, Schneider Electric SE, Stulz GmbH, Rittal GmbH & Co KG, Mitsubishi Electric Hydronics & IT Cooling Systems SpA, Johnson Controls Inc, Emerson Electric Co, CoolIT Systems Inc, Danfoss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Cooling Market Trends and Innovations
Cooling architectures are fragmenting across performance tiers as AI workloads bifurcate the market between legacy air-cooled retrofits and purpose-built liquid-cooled facilities. Equipment vendors now engineer product lines for distinct thermal envelopes rather than universal deployment.
Direct-to-chip liquid cooling is hybridizing thermal management strategies in Philippine hyperscale builds. This technology circulates dielectric fluid through cold plates mounted directly on processors, extracting heat at the source before it enters the data hall air stream. Colocation operators in Metro Manila are specifying hybrid configurations for new AI training halls, compressing the addressable market for standalone air-cooled chiller replacements.
The Department of Energy's minimum energy performance standards are tightening compliance thresholds for imported cooling equipment. This regulatory pressure disqualifies legacy chiller models from new facility approvals and accelerates depreciation of installed base assets. Imported precision air conditioning units now require BIS-aligned testing documentation, reshaping supplier qualification criteria for equipment distributors serving Luzon colocation markets.
Service contract unbundling is fragmenting vendor-customer relationships across Philippine facilities. Colocation operators now separate equipment procurement from long-term thermal performance guarantees, awarding maintenance and optimization contracts to specialized service providers independent of original equipment manufacturers. This behavioral shift concentrates in Metro Manila hyperscale deployments where uptime penalties exceed equipment capital costs.
Philippines Data Center Cooling Market Segmentation
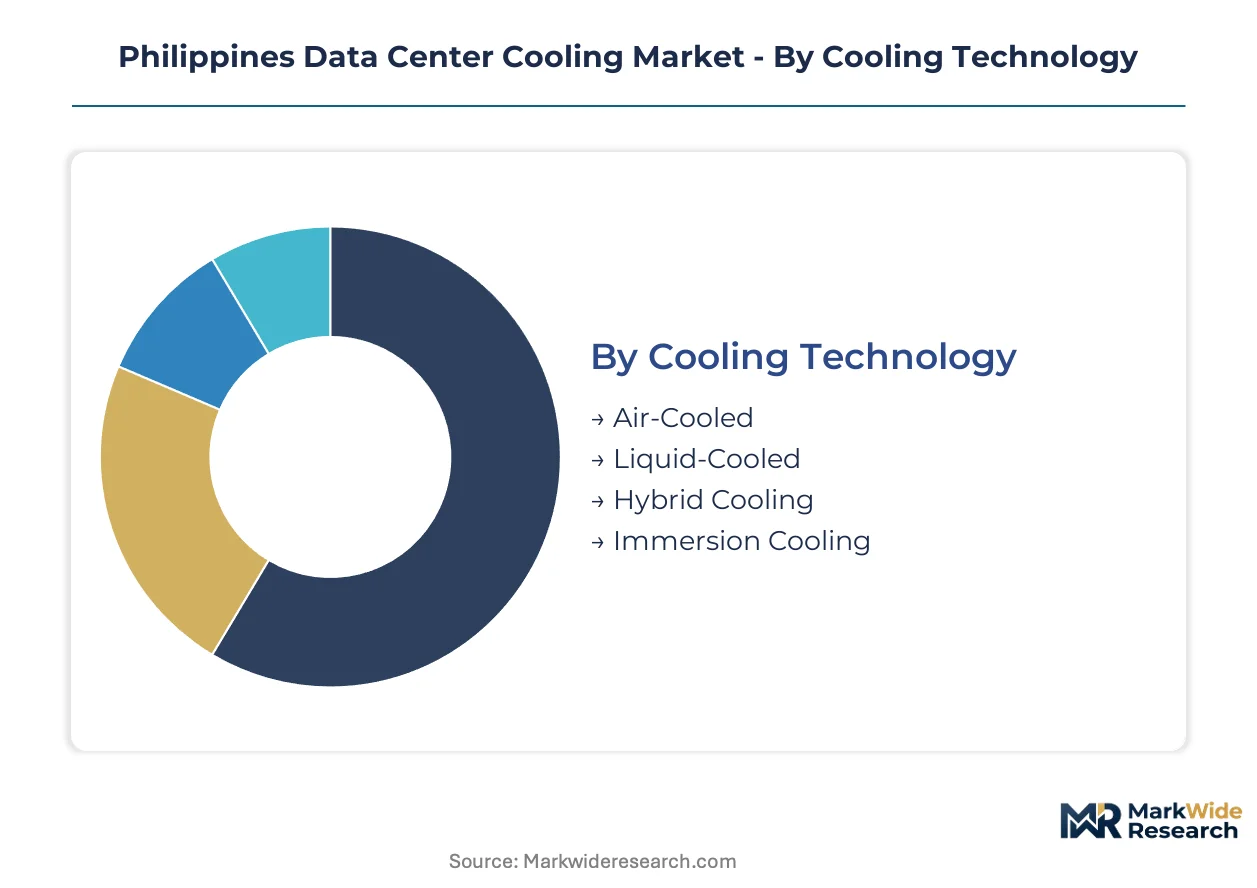
Cooling technology selection in Philippine facilities directly determines long-term service contract structures and vendor retention economics. Operators segment procurement strategies around thermal performance guarantees rather than upfront capital expenditure alone.
Cooling Technology:
After-sales service intensity varies dramatically across thermal architectures, with liquid-cooled systems demanding specialized commissioning expertise that anchors multi-year vendor relationships.
- Air-Cooled:Vapor-compression and direct-expansion units circulate conditioned air through raised-floor plenums. Demand concentrates in legacy Luzon colocation facilities where operators delay full infrastructure replacement despite efficiency penalties from tropical ambient heat.
- Liquid-Cooled:Dielectric fluid loops extract processor heat at the rack level, enabling densities above 30 kW per cabinet. Metro Manila hyperscale builds specify these systems for GPU-intensive AI training clusters where thermal throttling risks exceed infrastructure capital costs.
- Hybrid Cooling:Combines air-side economization with supplemental liquid loops for peak loads. Cebu emerging facilities favor this architecture for its operational flexibility across variable workload profiles.
- Immersion Cooling:Fully submerges servers in dielectric fluid, eliminating air-handling infrastructure. Niche adoption in experimental AI labs where rack densities exceed 50 kW.
Air-Cooled holds the largest share; momentum sits with Liquid-Cooled.
Component:
Component selection tracks facility scale and redundancy tier, with enterprise builds prioritizing modular redundancy over capital efficiency.
- Chillers:Centralized vapor-compression plants generate chilled water for air-handling distribution. Department of Energy efficiency mandates accelerate replacement cycles in Luzon facilities using legacy refrigerants targeted for phase-down.
- Cooling Towers:Open-loop and closed-circuit designs reject waste heat to ambient air. Coastal Cebu deployments specify corrosion-resistant materials for saline atmospheric exposure.
- Air Handlers:Precision units maintain ASHRAE temperature and humidity bands within white space. Metro Manila colocation operators demand tropical-humidity-rated configurations with extended economizer hours.
- Heat Exchangers:Plate-and-frame and shell-and-tube designs transfer thermal energy between fluid loops. Copper and aluminum input volatility compresses distributor margins on these fabrication-intensive components.
Chillers dominate installed value; Heat Exchangers gain share fastest as liquid-cooled adoption accelerates.
End User:
End-user thermal specifications diverge sharply between latency-sensitive financial workloads and batch-optimized AI training.
- IT Service Providers:Enterprise outsourcing specialists operate multi-tenant facilities with heterogeneous cooling requirements across client racks.
- Telecom Companies:Carrier-neutral facilities prioritize uptime redundancy over peak efficiency, driving N+1 chiller configurations.
- Financial Institutions:Banking and insurance data centers in Makati CBD demand precision humidity control for tape storage and mainframe environments.
- Cloud Services:Hyperscale tenants specify liquid-cooled architectures for Metro Manila AI training halls, compressing deployment timelines for compatible infrastructure.
Cloud Services command premium thermal specifications; Financial Institutions drive replacement demand for legacy precision units.
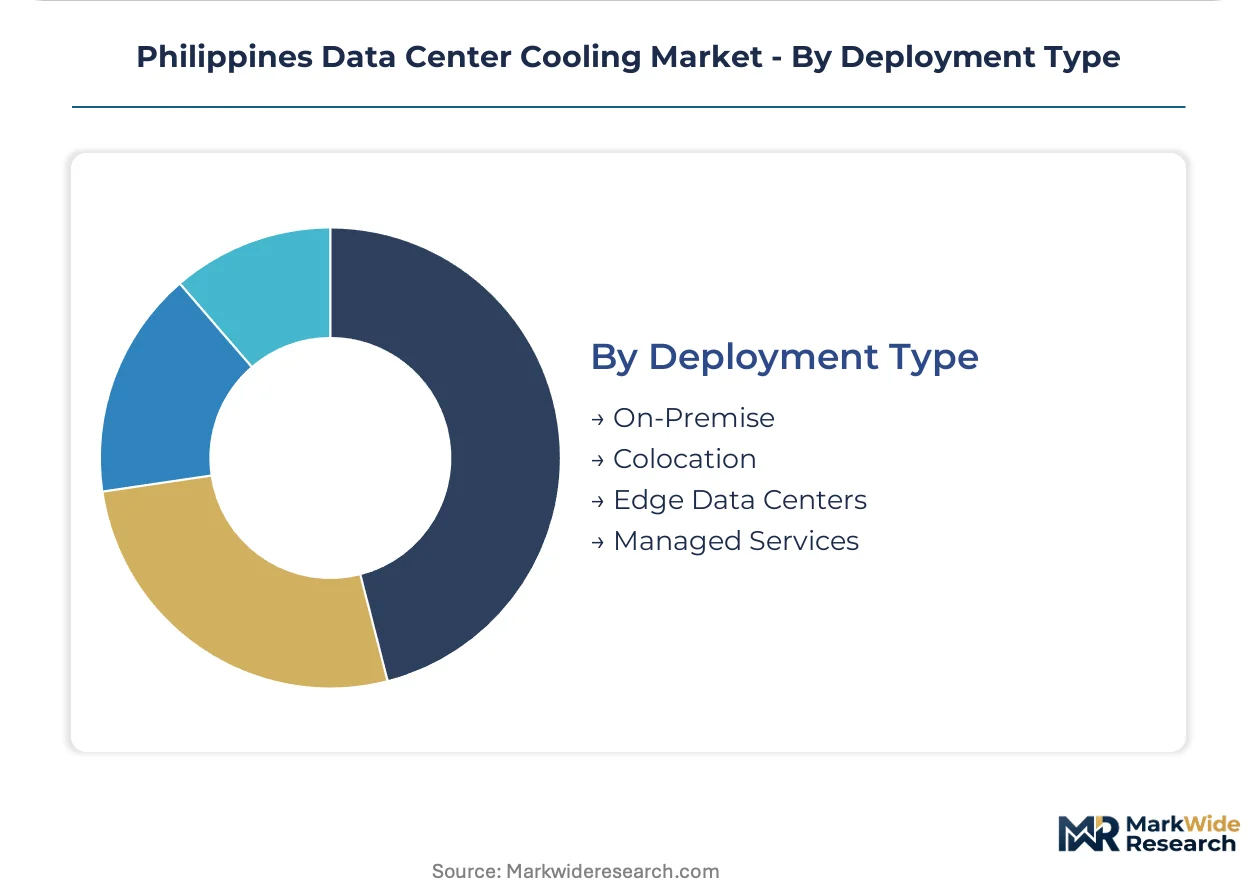
Deployment Type:
Deployment configuration determines cooling redundancy architecture and remote service accessibility.
- On-Premise:Enterprise-owned facilities in Bonifacio Global City integrate cooling with building management systems under single-tenant control.
- Colocation:Multi-tenant Metro Manila facilities segment thermal zones by client density requirements, complicating shared infrastructure optimization.
- Edge Data Centers:Compact modular units in provincial locations command premium pricing for limited-redundancy cooling with remote monitoring integration.
- Managed Services:Third-party operators assume thermal performance risk through outcome-based service contracts.
Colocation captures majority volume; Edge Data Centers expand most quickly outside Metro Manila core.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila consumes cooling infrastructure differently than provincial markets, prioritizing liquid-cooled precision systems for AI workloads while secondary cities retain air-cooled legacy architectures longer. Cebu and Davao favor hybrid configurations balancing capital efficiency with tropical climate adaptation. The Department of Energy's efficiency mandates apply nationwide but enforcement concentrates in Luzon hyperscale corridors.
Metro Manila
Hyperscale cloud tenants in Bonifacio Global City and Makati CBD specify direct-to-chip liquid cooling for GPU clusters exceeding 30 kW per rack. The Department of Energy enforces minimum energy performance standards through facility licensing reviews. Colocation operators in Taguig and Pasig compress deployment timelines to capture AI training demand before depreciation cycles complete on legacy air-cooled plants.
Central Luzon
Clark Freeport Zone and Subic Bay emerging data center parks attract modular cooling deployments with lower land costs than Metro Manila core. BIS-aligned certification requirements for imported chillers create compliance friction for non-established distributors. New hyperscale builds in Pampanga specify tropical-humidity-rated precision air conditioning with extended economizer hours.
Cebu
Secondary market hyperscale expansion favors hybrid cooling architectures balancing operational flexibility across variable workload profiles. Coastal saline atmospheric exposure drives specification of corrosion-resistant cooling tower materials. Mactan Newtown and Cebu Business Park developments command first-mover positioning for modular system providers escaping Metro Manila saturation.
Davao
Mindanao's emerging edge data center deployments prioritize compact cooling units with remote monitoring integration for limited-redundancy provincial sites. The Climate Change Commission's low-GWP refrigerant commitments accelerate chiller replacement cycles in government-linked facilities. Davao City IT parks attract managed service operators assuming thermal performance risk through outcome-based contracts.
Iloilo and Bacolod
Visayas secondary cities exhibit delayed infrastructure refresh cycles compared to Luzon, extending air-cooled system depreciation timelines. Edge deployment channels command premium pricing for service-integrated cooling units addressing remote-site accessibility constraints. Negros Occidental and Iloilo enterprise facilities favor hybrid configurations as transitional architectures before full liquid-cooled adoption.
Philippines Data Center Cooling Market Competitive Landscape
Capability concentration sits with specialized thermal engineering firms possessing liquid-cooled commissioning expertise; scale advantage sits with integrated building technology conglomerates with established distribution networks. The vendor base organizes around three archetypes: precision air conditioning specialists with tropical-climate engineering depth, integrated power and cooling platforms extending vendor stickiness through building-to-IT convergence, and direct-to-chip liquid cooling innovators capturing AI workload specifications. Dominant competitive moves include strategic partnerships between equipment vendors and local service integrators, plus portfolio diversification into thermal performance contracting unbundled from equipment sales.
Within the precision air conditioning tier, Stulz GmbH and Rittal GmbH & Co KG exemplify European engineering specialists occupying defensible positions in mission-critical humidity control. Among integrated platform providers, Schneider Electric SE and Vertiv Co anchor recurring revenue streams through local service infrastructure and building-to-IT cooling convergence. At the liquid-cooled innovation vector, CoolIT Systems Inc represents the direct-to-chip architecture specialists capturing hyperscale AI specifications. Mitsubishi Electric Hydronics & IT Cooling Systems SpA and Johnson Controls Inc occupy intermediate positions spanning chiller manufacturing and controls integration. Emerson Electric Co and Danfoss supply component and controls layers across multiple vendor ecosystems rather than competing at system level.
| Leading Market Players |
|---|
| Vertiv Co |
| Schneider Electric SE |
| Stulz GmbH |
| Rittal GmbH & Co KG |
| Mitsubishi Electric Hydronics & IT Cooling Systems SpA |
| Johnson Controls Inc |
| Emerson Electric Co |
| CoolIT Systems Inc |
| Danfoss |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum input volatility compresses equipment margins across Philippine distribution channels, forcing pricing stratification across premium, standard, and economy tiers while simultaneously reshaping procurement toward long-term offtake contracts with Chinese and Japanese fabricators. This commodity exposure concentrates pricing power among integrated multinationals with captive heat exchanger supply, while local distributors absorb margin compression through service bundling.
Pricing Analysis
Long-term thermal performance contracts dominate hyperscale procurement in Metro Manila, displacing spot equipment purchases as colocation operators unbundle hardware from service obligations. Price differentiation rests on BIS-aligned certification tiers and after-sales commissioning depth, with tropical-humidity-rated precision units commanding premiums over standard configurations. Cost compression in air-cooled retrofits intensifies as legacy depreciation cycles collide with Department of Energy efficiency mandates, making hyperscale cloud tenants least price-sensitive while provincial edge operators face acute capital constraints.
Supply Chain Analysis
Tariff exposure between China and ASEAN trading partners dominates supply chain risk planning for Philippine distributors importing chillers and precision air handlers. Manufacturing concentrates in China, Japan, and South Korea, with dielectric fluids and copper tubing drawing from specialized chemical and metallurgical suppliers. Single-source vulnerability around direct-to-chip cold plate fabrication forces operators to maintain dual-qualified vendor rosters. Distribution runs through authorized service integrators in Luzon, with Cebu and Davao served via satellite logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal performance contracting expands faster than hardware sales across Philippine facilities, creating service-attach economics that favor vendors with local commissioning infrastructure over pure equipment manufacturers.
For Market Incumbents: Build switching-cost moats through captive service infrastructure anchoring multi-year thermal performance guarantees. Defend against direct-to-chip liquid cooling specialists by certifying legacy chiller fleets for hybrid retrofit compatibility. Prioritize backward integration into heat exchanger fabrication to insulate margins from copper volatility. For New Entrants and Emerging Players: Pursue white-space positioning in Cebu's emerging hyperscale corridor before Metro Manila saturation hardens incumbent relationships. Target provincial edge deployments where limited-redundancy cooling commands premium pricing and remote monitoring integration lowers service cost structures. Enter through modular system partnerships with local integrators lacking liquid-cooled commissioning expertise. For Investors and Strategic Acquirers: The Climate Change Commission's low-GWP refrigerant phase-down reshapes the acquisition landscape toward chiller replacement demand. Long-term viability favors targets with tropical-climate engineering depth and established BIS certification pathways. Watch for hyperscale tenants specifying immersion cooling at densities exceeding 50 kW per rack as the inflection signal for architectural displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Separates equipment procurement from thermal performance guarantees, concentrating value with specialized maintenance providers. |
| Hybrid Cooling Deployment | Combines air-side economization with liquid loops, enabling operational flexibility across variable AI workload profiles in Cebu. |
| Low-GWP Refrigerant Transition | Accelerates chiller replacement cycles in Luzon facilities as Climate Change Commission commitments phase down legacy refrigerants. |
| Direct-to-Chip Liquid Cooling | Circulates dielectric fluid through processor-mounted cold plates, capturing hyperscale AI specifications in Bonifacio Global City. |
| Edge Data Center Expansion | Deploys compact modular cooling units with remote monitoring integration for limited-redundancy provincial sites in Davao. |
Research Methodology
Initial hypotheses were tested against primary input from data center operations directors, thermal engineering consultants, colocation procurement managers, and Department of Energy efficiency auditors, then refined through secondary validation against SEC filings from hyperscale cloud providers, customs import records for cooling equipment, BIS certification databases, and Climate Change Commission policy documents. Bottom-up facility build tracking triangulated with top-down vendor revenue analysis.
Demand-supply balance modeling across the analysis window integrated cooling technology segmentation, deployment type distribution, and end-user density specifications with regional construction permitting data. CAGRs derived from facility capacity expansion announcements and equipment procurement timelines, incorporating tropical ambient temperature degradation curves for air-cooled efficiency penalties and liquid-cooled adoption elasticity above 30 kW per rack.
Sensitivities concentrate around Department of Energy mandate enforcement timing and hyperscale tenant migration to immersion architectures. Forecasts reflect assumptions on refrigerant phase-down schedules and AI training cluster density trajectories. Material shifts in BIS certification requirements or copper price volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Liquid Cooling Racks Market