
 Israel Data Center Cooling Market | 2026-2036
Israel Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Data Center Cooling Market Insights
Modular rack-level cooling configurations is broadening buyer choice beyond traditional perimeter HVAC designs. Schneider Electric leverages its integrated power and cooling portfolio to anchor large colocation contracts in central Israel. Daikin Applied Israel competes through localized service networks and rapid deployment capabilities for enterprise facilities. Rittal GmbH & Co. KG extends its edge-computing enclosure expertise into precision cooling modules suited for defense and telecom applications.
Data center cooling encompasses thermal management systems engineered to maintain IT equipment within operational temperature bands, typically 18°C to 27°C per ASHRAE guidelines, using chilled water loops, refrigerant-based direct expansion, or dielectric fluid immersion to reject heat generated by processors, storage arrays, and power distribution units. Liquid cooling segments are capturing margin pools as GPU-intensive AI workloads exceed air-cooling thresholds, while hybrid systems retain share in legacy retrofit environments where infrastructure constraints prevent full liquid conversion. Air cooling remains mature in smaller on-premises deployments across Israeli government and financial institutions with moderate power densities.
The Israel Standards Institution sets energy efficiency benchmarks for cooling equipment, while the Israel Electric Corporation's demand response programs shape operational cost structures for facility operators. The Ministry of Environmental Protection enforces refrigerant phase-down schedules aligned with Kigali Amendment commitments, restricting hydrofluorocarbon-based systems in new construction. Stakeholders must monitor how grid capacity allocations and carbon reporting obligations reshape cooling technology selection for planned hyperscale campuses.
Market Dynamics
GPU-intensive AI workloads are compressing air-cooling viability thresholds across Tel Aviv corridor facilities, forcing infrastructure operators to reconfigure thermal architectures mid-deployment cycle.
Growth Catalysts
- Israel Electric Corporation efficiency mandates:Demand response programs penalize high PUE operations, accelerating liquid cooling adoption in hyperscale campuses.
- Cloud service provider facility expansion:Central Israel's financial services clusters require dense compute footprints that exceed conventional HVAC capacity.
- Ambient temperature escalation:Rising summer peaks degrade air-cooling effectiveness, pushing operators toward dielectric fluid immersion for critical workloads.
Market Restraints
- Liquid cooling capex intensity:Infrastructure conversion costs constrain mid-tier colocation operators with legacy raised-floor investments.
- Refrigerant supply concentration:Kigali Amendment phase-down schedules restrict hydrofluorocarbon availability for new direct-expansion installations.
- Grid allocation bottlenecks:Israel Electric Corporation capacity reservations for planned hyperscale projects face multi-year lead times.
Strategic Opportunities
- Edge computing enclosure integration:Defense and telecom applications in southern Israel demand precision cooling modules for distributed deployments.
- Ministry of Environmental Protection carbon reporting:Mandatory disclosure obligations create preference for low-GWP refrigerant systems in new construction.
- Modular rack-level service models:Rapid deployment capabilities enable vendor capture of enterprise retrofit cycles without full facility shutdown.
Industry Challenges
- Thermal engineering skill scarcity:Liquid cooling system design and maintenance expertise concentrates among specialized contractors, inflating labor costs.
- Legacy infrastructure interoperability:Hybrid cooling architectures require complex control system integration with existing building management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Data Center Cooling Market |
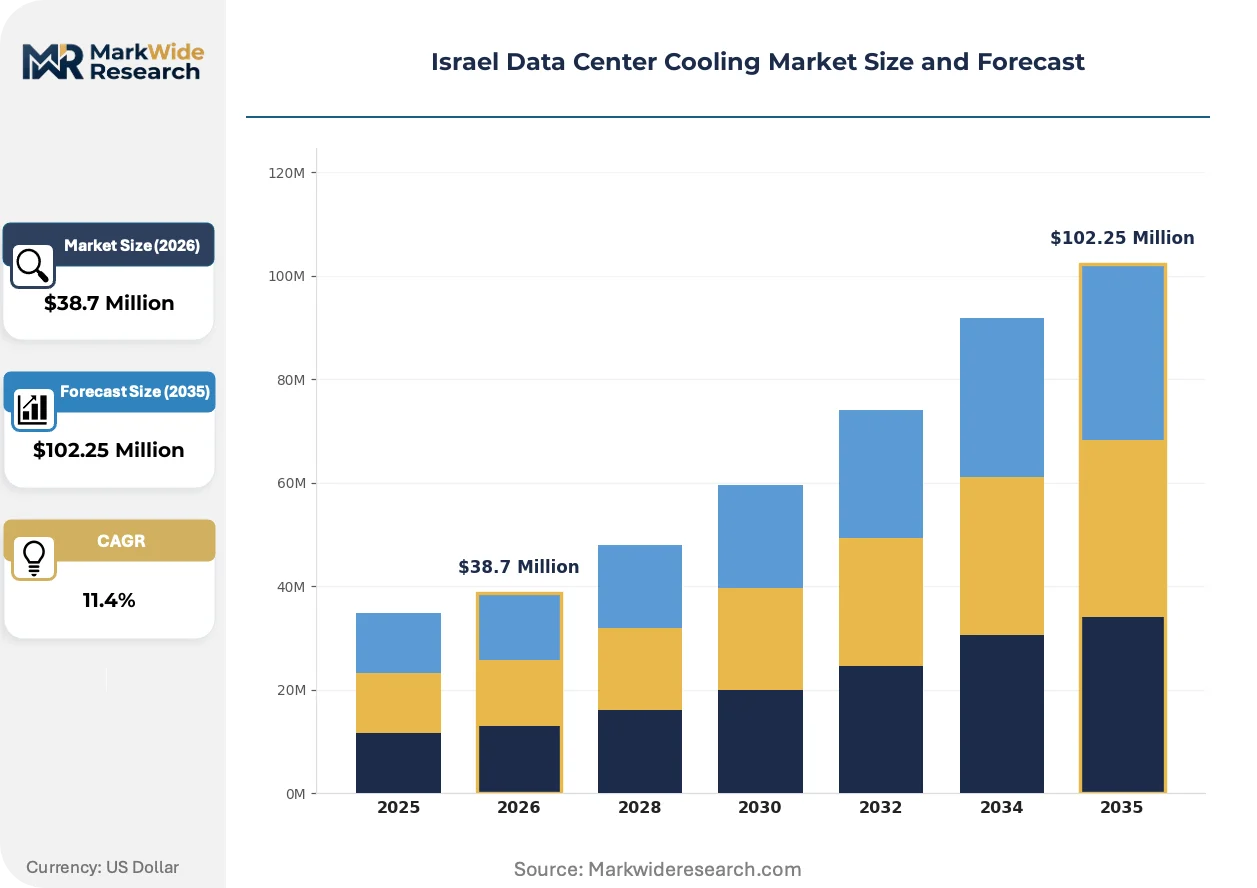
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chilled Water Systems, Direct Contact Cooling, Evaporative Cooling, Heat Exchangers Technology: Liquid Cooling, Air Cooling, Immersion Cooling, Hybrid Systems End User: Telecommunications, Cloud Service Providers, Financial Services, Government Agencies Deployment: On-Premises, Colocation, Hyperscale, Modular Solutions |
| Companies Covered | Rittal GmbH & Co. KG, Johnson Controls International plc, Schneider Electric, Daikin Applied Israel, Asetek A/S, Vertiv Group Corp., Mitsubishi Electric Corporation, Accelsius, STULZ GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Data Center Cooling Market Trends and Innovations
Cooling technology trajectories in Israel are compressing deployment timelines as AI workload densities outpace conventional thermal design margins. Facility operators now face forced architectural decisions between incremental retrofit and full infrastructure replacement.
Direct-to-chip liquid cooling is overtaking rear-door heat exchanger configurations in high-density GPU clusters. Financial services operators in Tel Aviv are adopting cold-plate architectures for algorithmic trading infrastructure. This technology is overtaking traditional approaches by enabling power densities above 50 kW per rack without facility-level HVAC expansion.
Israel Standards Institution energy efficiency benchmarks now mandate minimum performance coefficients for cooling equipment deployed in new data center construction. The Israel Electric Corporation incorporates these standards into demand response incentive calculations. Colocation providers in central Israel are responding by specifying variable-speed compressor systems and intelligent airflow management.
Service unbundling is fragmenting traditional equipment-procurement relationships. Facility operators now source cooling hardware, installation, and ongoing maintenance through separate vendor channels rather than single-source contracts. This pattern is most visible among government and defense installations with specialized security clearance requirements for maintenance personnel.
Israel Data Center Cooling Market Segmentation
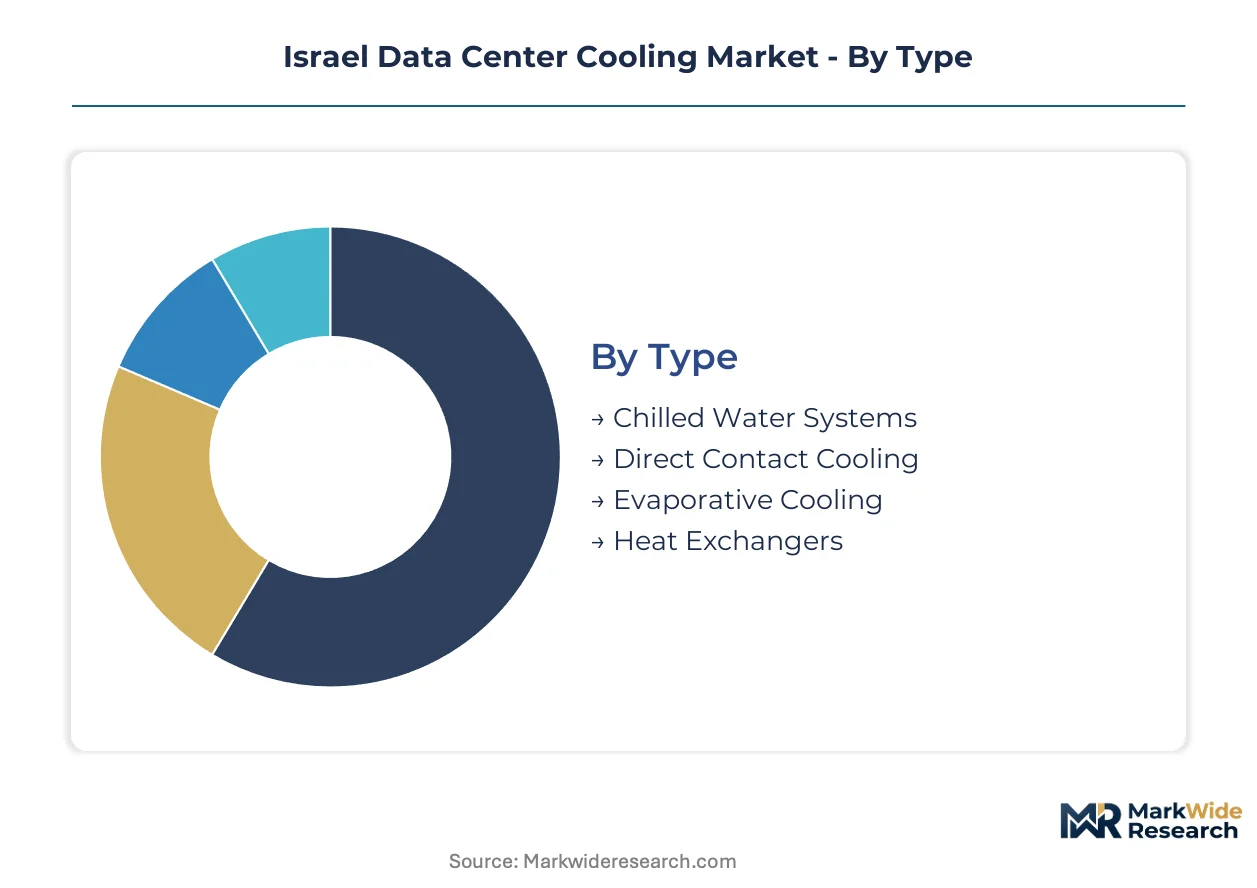
Thermal management architectures in Israeli data centers fragment across multiple technical and commercial axes. Each segmentation layer reveals distinct procurement patterns, regulatory exposures, and infrastructure investment cycles that shape vendor positioning.
Type:
Cooling system configurations diverge by heat rejection mechanism and fluid handling architecture, determining capital intensity and operational flexibility for facility operators across central Israel's dense compute clusters.
- Chilled Water Systems:Centralized refrigeration plants distribute temperature-controlled water through insulated piping networks to computer room air handlers. Tel Aviv financial services operators favor these for legacy trading floor retrofits where infrastructure replacement windows are narrow.
- Direct Contact Cooling:Refrigerant or water-based circuits interface directly with server heat sinks, eliminating intermediate air exchange. Hyperscale campuses under Israel Electric Corporation efficiency mandates are specifying these for GPU-intensive AI training workloads exceeding 30 kW per rack.
- Evaporative Cooling:Adiabatic processes reduce incoming air temperature through water evaporation, cutting compressor energy consumption. Southern Israel edge deployments leverage these for defense and telecom applications with moderate power densities and ambient humidity tolerance.
- Heat Exchangers:Plate-and-frame or shell-and-tube configurations transfer thermal energy between isolated fluid loops. Colocation providers integrate these for tenant-specific cooling isolation without facility-wide infrastructure disruption.
Chilled water systems lead on scale; direct contact cooling leads on momentum.
Technology:
Heat extraction methodologies stratify by thermal conductivity medium, with liquid-based approaches displacing conventional air handling as power densities escalate across Israeli cloud and financial infrastructure.
- Liquid Cooling:Dielectric fluids or water-glycol mixtures absorb processor heat through cold plates or immersion baths. Cloud service providers in the Tel Aviv corridor are deploying these for algorithmic infrastructure where air-cooling thresholds collapsed.
- Air Cooling:Forced convection through precision air handlers maintains traditional 18°C to 27°C operational bands. Government agencies retain these for moderate-density on-premises deployments with extended equipment refresh cycles.
- Immersion Cooling:Fully submerged server assemblies in engineered fluids enable extreme density without mechanical refrigeration. Early adopters include defense contractors with specialized security requirements and limited facility footprints.
- Hybrid Systems:Architectures combine air and liquid handling for staged infrastructure transitions. Enterprise colocation operators specify these to preserve raised-floor investments while accommodating isolated high-density tenant requirements.
Air cooling retains installed base dominance; liquid cooling commands expansion capex.
End User:
Demand concentration varies by sector-specific compute intensity, regulatory compliance burden, and infrastructure ownership model across Israel's digital economy.
- Telecommunications:5G core network and edge aggregation facilities require distributed thermal management. Bezeq and Cellcom are retrofitting central office buildings with modular cooling for virtualized network functions.
- Cloud Service Providers:Hyperscale operators drive liquid cooling specification at facility design stage. Microsoft and Amazon Web Services expansion in central Israel is compressing deployment timelines for direct-to-chip architectures.
- Financial Services:Low-latency trading infrastructure demands precise temperature stability. Tel Aviv Stock Exchange proximity hosting and algorithmic trading floors prioritize redundant chilled water loops over efficiency optimization.
- Government Agencies:Classified data handling and sovereign cloud requirements shape procurement. Ministry of Defense and National Cyber Directorate installations emphasize service unbundling with security-cleared maintenance personnel.
Cloud service providers lead on scale; government agencies lead on specification complexity.
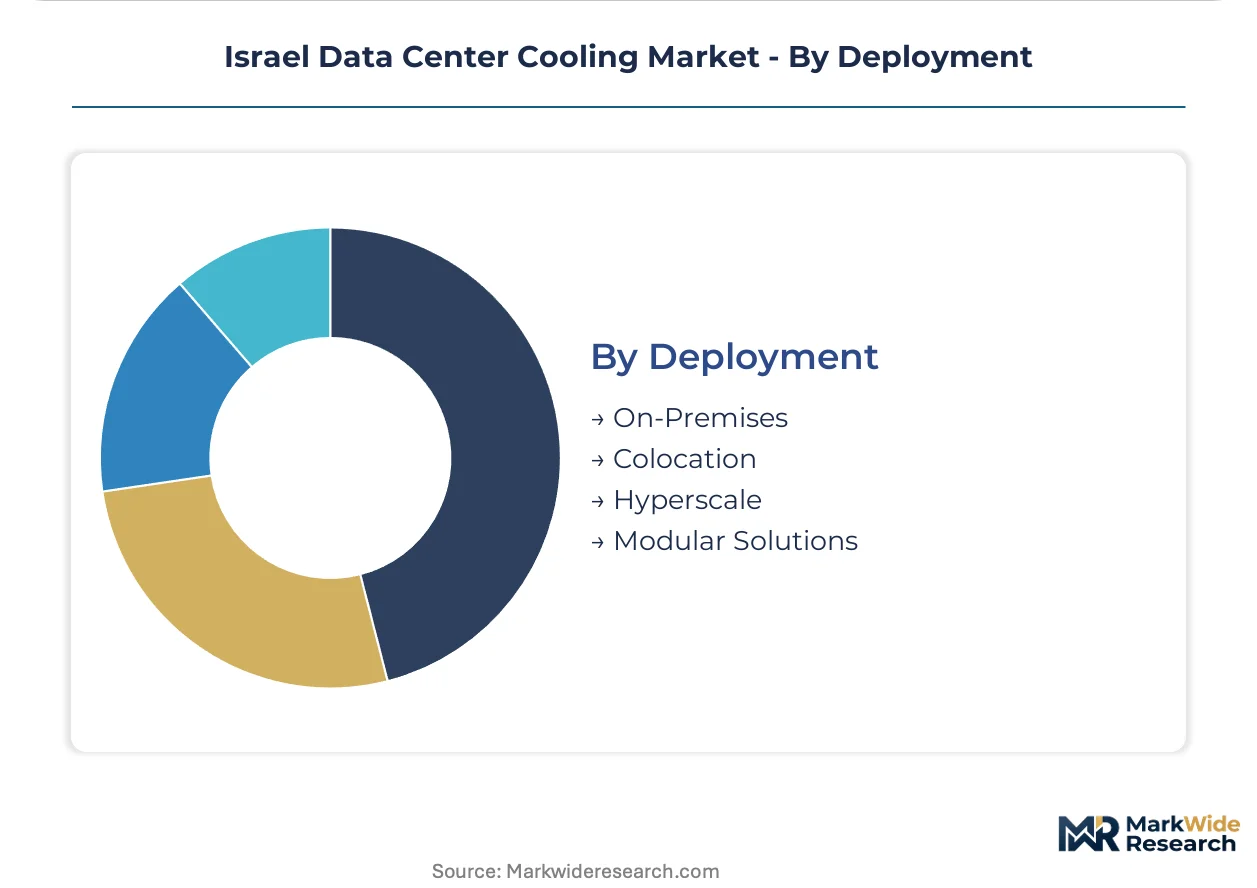
Deployment:
Infrastructure delivery models determine cooling system ownership, operational responsibility, and technology refresh cadence for Israeli facility operators.
- On-Premises:Enterprise-owned facilities with captive cooling infrastructure. Bank Leumi and Bank Hapoalim maintain these for core banking systems with stringent uptime requirements.
- Colocation:Multi-tenant facilities where providers manage shared cooling plant. Interxion and MedOne compete on power density guarantees and Israel Electric Corporation demand response program participation.
- Hyperscale:Single-tenant campuses exceeding 10 MW designed for specific operator requirements. These drive liquid cooling adoption through direct vendor relationships with infrastructure OEMs.
- Modular Solutions:Factory-integrated cooling and power skids for rapid deployment. Defense and telecom applications in southern Israel favor these for expeditionary or distributed compute requirements.
Hyperscale deployments lead on technology advancement; modular solutions lead on deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center cooling infrastructure in Israel traces its modern lineage to the 1990s telecommunications privatization, when Bezeq's central office modernizations introduced precision environmental controls to the region. The sector matured through financial services digitization in Tel Aviv and defense sector compute expansion, establishing thermal management as a critical facility discipline before cloud hyperscale arrival.
Tel Aviv Metropolitan Area
Financial services algorithmic trading and cloud service provider campuses drive dense compute demand across the Gush Dan region. The Israel Electric Corporation's demand response programs penalize high PUE operations, pushing Interxion and Microsoft facilities toward liquid cooling architectures. Herzliya Pituach hosts the densest concentration of colocation capacity, where direct-to-chip systems now displace legacy chilled water loops.
Central District
Modular data center deployments for defense contractors and government cloud infrastructure concentrate in Petah Tikva and Ramla sub-districts. The Ministry of Environmental Protection's carbon reporting mandates shape procurement for National Cyber Directorate facilities. These installations favor precision cooling modules with security-cleared maintenance protocols over integrated single-source contracts.
Haifa Bay Area
Industrial research campuses and maritime logistics data processing create moderate-density cooling requirements. The Israel Standards Institution energy efficiency benchmarks apply to new construction at the Haifa port's digital trade infrastructure. Local operators retain air-cooling systems with intelligent airflow management rather than full liquid conversion.
Be'er Sheva and Southern District
Edge computing for defense applications and telecom network aggregation drives distributed thermal management needs. Bezeq and Cellcom retrofit central offices with modular cooling skids for virtualized network functions. The region's ambient humidity tolerance enables evaporative cooling adoption where power densities permit.
Jerusalem District
Government data centers and classified sovereign cloud installations prioritize operational security over efficiency optimization. The Ministry of Defense maintains captive cooling infrastructure with service unbundling requirements for maintenance personnel. These specifications fragment vendor relationships compared to commercial hyperscale procurement patterns.
Israel Data Center Cooling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and service bundling scope in Israel's data center cooling market. The vendor base stratifies between integrated infrastructure OEMs with power and cooling portfolios, specialized liquid cooling technology developers, and localized service providers with rapid deployment capabilities. Three archetypes dominate: full-stack infrastructure integrators, precision cooling specialists, and regional service arms of global HVAC manufacturers. Competitive moves concentrate on strategic partnerships for hyperscale campus contracts and modular product line extensions for edge deployment velocity.
Within the integrated infrastructure tier, Schneider Electric anchors large colocation relationships through combined power and cooling specification. Daikin Applied Israel occupies a position among localized service providers competing on deployment speed for enterprise retrofits. Rittal GmbH & Co. KG exemplifies the precision enclosure specialist archetype, extending edge-computing expertise into thermal modules for defense applications. These three represent distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Johnson Controls International plc |
| Schneider Electric |
| Daikin Applied Israel |
| Asetek A/S |
| Vertiv Group Corp. |
| Mitsubishi Electric Corporation |
| Accelsius |
| STULZ GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive power and cooling integration by Schneider Electric anchors both supply security and pricing leverage across central Israel's hyperscale corridor. This vertical control over critical infrastructure components enables premium positioning against unbundled competitors while insulating margin structures from refrigerant cost volatility under Israel Electric Corporation efficiency mandates.
Pricing Analysis
Project-based equipment procurement with lifecycle service bundling dominates Israeli data center cooling transactions. Price differentiation hinges on Israel Standards Institution certification tier and liquid cooling technology complexity, with GPU-ready cold-plate systems commanding substantial premiums over air-cooled alternatives. Cost compression in mid-tier colocation retrofits is intensifying because legacy raised-floor operators delay full infrastructure replacement. Government agencies exhibit lowest price sensitivity due to security-cleared maintenance requirements, while financial services operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Precision compressor and heat exchanger manufacturing rests on German, Japanese, and South Korean specialty industrial producers. Dielectric fluid formulations draw from Belgian and American chemical suppliers, while control system electronics source from Taiwanese semiconductor fabricators. Single-source vulnerability concentrates in specialized refrigerant compounds facing Kigali Amendment phase-down restrictions. Distribution runs through Tel Aviv-based systems integrators with direct OEM relationships for hyperscale campus fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's data center cooling market offers margin expansion through liquid cooling premiumization as AI workload densities compress air-cooling viability. Cost-down drivers include modular rack-level deployment models that reduce field engineering overhead.
For Market Incumbents: Hedge against refrigerant supply disruption by accelerating low-GWP alternative qualification with the Ministry of Environmental Protection. Anchor colocation relationships through Israel Electric Corporation demand response program co-participation, converting compliance burden into switching cost. Defensive patent positioning around direct-to-chip cold-plate geometries protects premium tier from Asetek and Accelsius encroachment. For New Entrants and Emerging Players: Defense contractors with classified facility requirements represent an underserved buyer archetype fragmented across southern Israel's distributed edge deployments. Modular cooling skid specifications for Bezeq and Cellcom central office retrofits offer faster penetration than hyperscale campus competition. Security-cleared maintenance service bundling creates differentiation against equipment-only vendors. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because thermal engineering skill scarcity inflates labor costs and fragments vendor relationships. Long-term viability centers on capabilities spanning air-to-liquid technology transitions across the analysis window. Acquisition targets should demonstrate installed base in government or financial services verticals with sticky maintenance contracts. Watch Israel Electric Corporation grid allocation announcements as inflection indicator for hyperscale capex timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Chip Liquid Cooling Deployment | Enables GPU densities above 50 kW per rack for Tel Aviv algorithmic trading infrastructure. |
| Low-GWP Refrigerant Certification Investment | Aligns new construction with Ministry of Environmental Protection Kigali Amendment compliance schedules. |
| Security-Cleared Maintenance Capability Buildout | Captures government and defense contracts requiring personnel vetting beyond commercial standards. |
| Modular Rack-Level Service Model Launch | Reduces enterprise retrofit deployment timelines without facility-wide shutdown requirements. |
| Israel Electric Corporation Demand Response Partnership | Converts efficiency mandate participation into colocation contract switching costs. |
Research Methodology
Coverage spans Israel's central district, Tel Aviv metropolitan area, and southern defense corridor, with primary inputs from each. Data collection combined structured interviews with data center facility managers, thermal engineering contractors, Israel Electric Corporation grid planning officers, and cooling equipment procurement leads at cloud service providers. Secondary validation drew from Israel Standards Institution technical bulletins, Ministry of Environmental Protection regulatory filings, hyperscaler capex disclosure documents, and customs import records for precision cooling equipment. Bottom-up facility-level capacity estimates triangulated against top-down sectoral demand projections.
Granularity-level modeling deployed segment-specific CAGRs across cooling type, technology, end user, and deployment mode dimensions. Power density thresholds by workload category shaped technology adoption curves throughout the forecast period. Input assumptions incorporated Israel Electric Corporation efficiency mandate enforcement timelines, refrigerant phase-down schedules, and hyperscale campus construction permit approvals.
Underlying measurement precision varies by segment; hyperscale and cloud service provider deployments carry tighter precision than fragmented government installations. Forecasts reflect documented assumptions regarding grid capacity allocation timelines and AI workload penetration rates. Material deviation in Israel Electric Corporation demand response program structure or Ministry of Environmental Protection carbon reporting enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market