
 Nigeria Data Center Cooling Market | 2026-2036
Nigeria Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Data Center Cooling Market Insights
Aftermarket service revenue is narrowing as original equipment manufacturers consolidate lifecycle contracts. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments across Lagos. Vertiv Group Corp competes through thermal management specialization in edge and hyperscale configurations. STULZ GmbH differentiates via precision air conditioning systems engineered for West African humidity profiles.
Nigeria data center cooling encompasses engineered thermal management systems that regulate temperature, humidity, and airflow within server environments, typically operating within N+1 redundancy architectures with chilled water supply temperatures of 7-12°C to maintain ASHRAE-recommended IT inlet conditions. These systems prevent thermal throttling, extend hardware lifespan, and sustain uptime for digital infrastructure serving financial services, telecommunications, and cloud platforms. Air cooling retains dominant share in existing facilities due to lower capital requirements and simpler maintenance protocols, while liquid cooling segments are gaining traction among colocation providers deploying high-density GPU clusters for artificial intelligence workloads. Capacity deployments above 2 MW are expanding fastest as international cloud operators establish regional availability zones in Nigeria.
The National Information Technology Development Agency sets mandatory efficiency benchmarks for federal data centers, while the country's central electricity regulator enforces grid interconnection standards that directly influence backup cooling power architecture. The Standards Organisation of Nigeria certifies equipment safety and energy performance, creating compliance thresholds for imported precision cooling units. Stakeholders must monitor evolving carbon reporting obligations and local content requirements that will reshape procurement criteria and vendor qualification pathways.
Market Dynamics
International cloud operators are compressing deployment timelines for regional availability zones, forcing cooling infrastructure vendors to pre-qualify equipment for Nigerian voltage standards and humidity profiles before procurement cycles conclude.
Growth Catalysts
- GPU Cluster Density:Artificial intelligence training workloads are driving rack power densities above 30 kW in Lagos colocation facilities, necessitating liquid cooling retrofits that expand addressable market scope for precision thermal management suppliers.
- NITDA Efficiency Mandates:The National Information Technology Development Agency's mandatory energy benchmarks for federal data centers are accelerating replacement cycles for legacy air-cooled systems that fail to meet power usage effectiveness thresholds.
- Lekki Corridor Concentration:Hyperscale facility clustering along the Lekki Free Trade Zone is creating economies of scale for chilled water infrastructure shared across multiple tenant environments.
Market Restraints
- Grid Instability:The Nigerian Electricity Regulatory Commission's interconnection standards impose redundant backup cooling power architectures that add 25-40% to capital deployment costs for facilities above 5 MW capacity.
- Import Duty Structure:Precision cooling equipment faces multi-layered tariffs and foreign exchange access restrictions that extend procurement lead times for colocation operators without established vendor financing relationships.
- Technical Labor Scarcity:Certified refrigeration technicians with data center-specific credentials remain concentrated in Lagos and Abuja, limiting expansion feasibility for edge deployments in secondary cities.
Strategic Opportunities
- Abuja Government Cloud:Federal digital transformation initiatives are creating dedicated demand for sovereign data center capacity with cooling systems meeting national security certification requirements.
- Free Cooling Hybridization:Evaporative and economizer technologies adapted to West African wet-bulb temperature profiles offer pathways to reduce mechanical refrigeration dependency during harmattan season operations.
- Edge Micro-Modular Units:Containerized cooling systems prefabricated for rapid deployment are capturing share in banking sector edge installations requiring sub-500 kW capacity with 12-week delivery windows.
Industry Challenges
- ASHRAE Compliance Verification:Local testing facilities lack accreditation for thermal testing to international standards, forcing vendors to ship equipment to South Africa or Europe for certification, extending product launch timelines by 4-6 months.
- Legacy Integration Complexity:Existing facilities built for 5-8 kW average rack densities require structural reinforcement and piping infrastructure upgrades before accommodating liquid cooling manifolds, complicating retrofit economics for operators with multi-year lease commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Data Center Cooling Market |
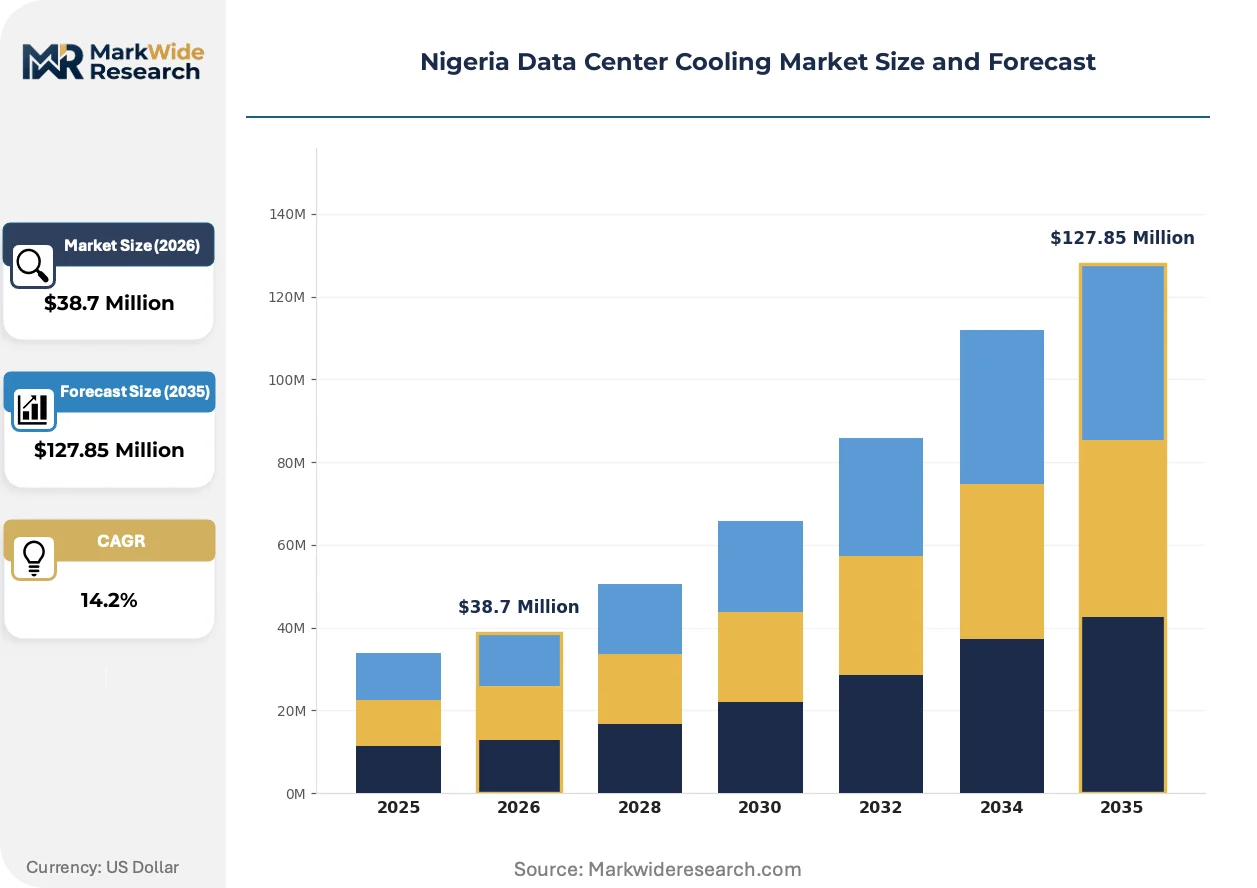
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Liquid Cooling, Air Cooling, Immersion Cooling, Hybrid Cooling End User: Telecommunications, Cloud Service Providers, IT Companies, Colocation Providers Technology: Evaporative Cooling, Chilled Water Systems, Free Cooling, Direct Expansion Capacity: Below 500 kW, 500 kW - 1 MW, 1 MW - 2 MW, Above 2 MW |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, STULZ GmbH, Rittal GmbH & Co. KG, Johnson Controls International plc, Mitsubishi Electric Corporation, Daikin Industries, Ltd., Emerson Electric Co, Carrier, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are transitioning from experimental deployments to standard procurement specifications as rack densities escalate, while regulatory pressure on energy performance intensifies compliance requirements across facility tiers.
Direct-to-chip liquid cooling is collapsing the thermal design power ceiling that previously constrained artificial intelligence server deployment in Nigerian facilities. Colocation operators in Lagos are specifying cold plate manifolds and coolant distribution units for new builds above 15 kW per rack. This technology is collapsing the historical trade-off between compute density and facility cooling capacity, enabling hyperscale tenants to match European deployment densities without ambient temperature penalties.
NITDA's forthcoming carbon reporting guidelines for federal data centers are mandating granular energy consumption disclosure that exposes mechanical cooling loads to procurement scrutiny. The Standards Organisation of Nigeria is aligning equipment safety certifications with IEC 62368-1 standards, creating dual compliance pathways for imported precision cooling units. Tier-III facility developers are responding by specifying cooling plant instrumentation compatible with automated sustainability reporting platforms.
Service contract unbundling is fragmenting the vendor-customer relationship that previously locked operators into single-source lifecycle agreements. Financial services buyers are separating commissioning and preventive maintenance scopes, awarding multi-year operations contracts to local mechanical contractors with NITDA-certified technicians. This pattern is most pronounced among second-tier banks establishing primary data centers in Abuja, where vendor presence remains thinner than in Lagos.
Nigeria Data Center Cooling Market Segmentation
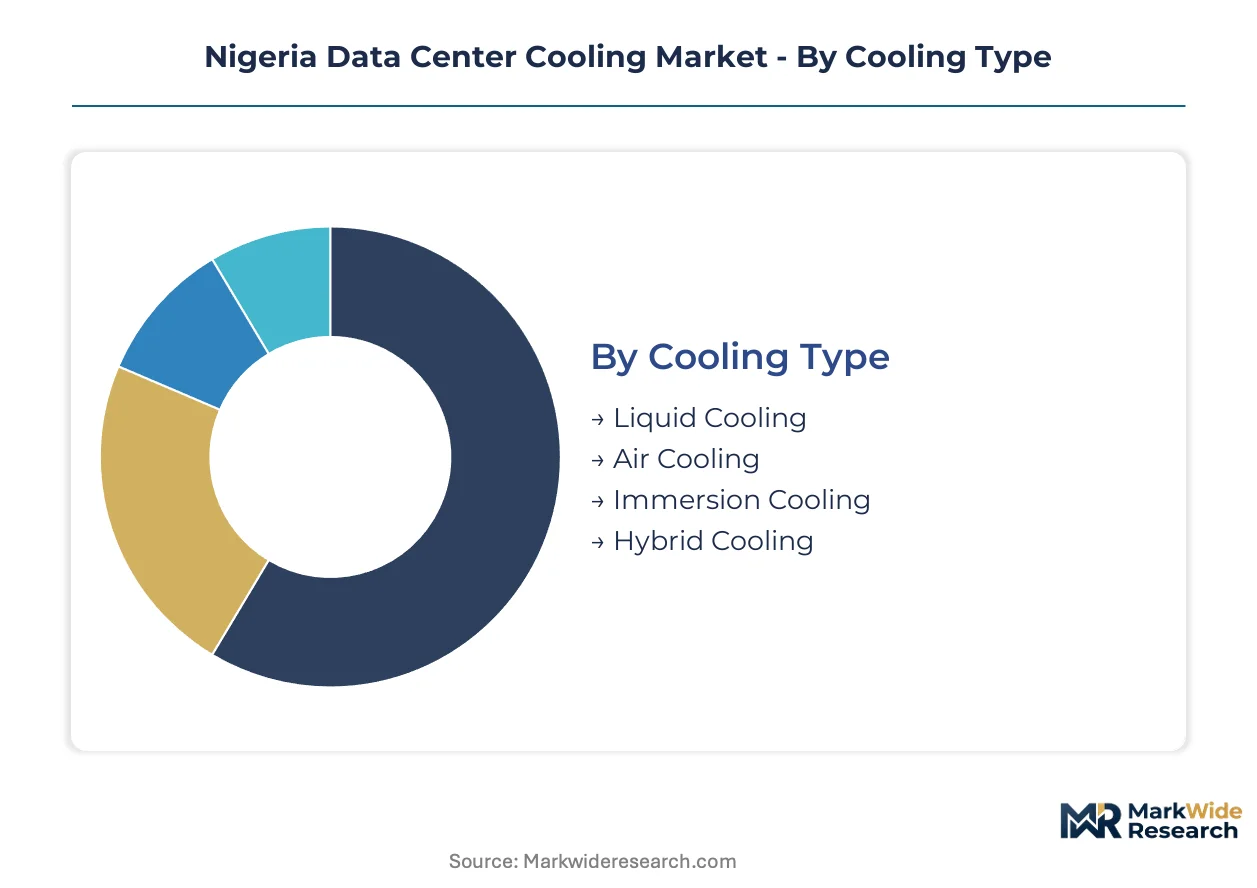
Cooling infrastructure procurement in Nigeria stratifies across technology maturity, facility scale, and end-user risk tolerance. Each segmentation dimension reveals distinct vendor qualification pathways and capital deployment patterns that shape competitive positioning across Lagos and Abuja corridors.
Cooling Type:
Technology cost tiers separate established mechanical approaches from emerging thermal architectures requiring specialized maintenance capabilities.
- Air Cooling:Precision air conditioning units and computer room air handlers dominate existing facility footprints across Lagos. Demand concentrates in banking sector edge deployments where 5-8 kW rack densities and limited technical labor pools favor familiar maintenance protocols.
- Liquid Cooling:Direct-to-chip cold plate systems and coolant distribution units are displacing legacy architectures in hyperscale facilities along the Lekki corridor. GPU cluster deployments above 30 kW per rack are forcing colocation operators to specify liquid manifolds for artificial intelligence training workloads.
- Hybrid Cooling:Economizer-mechanical combinations adapted to West African wet-bulb profiles reduce mechanical refrigeration dependency during harmattan season operations.
- Immersion Cooling:Dielectric fluid tank systems remain pre-commercial in Nigeria due to ASHRAE compliance verification gaps and import certification delays.
Air cooling holds installed capacity. Liquid cooling is rotating up the share rankings.
End User:
Customer type determines redundancy architecture, procurement timeline compression, and sovereign compliance requirements.
- Cloud Service Providers:Hyperscale operators deploying regional availability zones in Lagos specify N+1 chilled water plants with 7-12°C supply temperatures. International operators compress deployment timelines, forcing vendors to pre-qualify equipment for Nigerian voltage standards before procurement cycles conclude.
- Colocation Providers:Multi-tenant facility operators balance density flexibility against capital efficiency, driving demand for modular cooling plants that scale from 500 kW to 2 MW increments. Lekki Free Trade Zone clustering creates economies of scale for shared chilled water infrastructure.
- Telecommunications:Mobile network operators prioritize air-cooled edge cabinets for base station aggregation points in secondary cities where technical labor scarcity limits liquid cooling feasibility.
- IT Companies:Enterprise captive facilities in Abuja face NITDA efficiency mandates that accelerate replacement cycles for legacy air-cooled systems failing power usage effectiveness thresholds.
Colocation providers anchor current procurement volume. Cloud service providers are climbing the fastest.
Technology:
System maturity and local climate adaptability shape specification patterns across facility tiers.
- Chilled Water Systems:Centralized chiller plants with cooling towers serve facilities above 2 MW capacity in Lagos hyperscale clusters. These systems enable shared infrastructure across multiple tenant environments.
- Direct Expansion:Packaged DX units with split or packaged configurations dominate sub-1 MW deployments where simplified maintenance protocols offset efficiency penalties.
- Evaporative Cooling:Adiabatic and wet media systems engineered for West African humidity profiles offer partial load efficiency gains during dry season operations.
- Free Cooling:Air-side and water-side economizer technologies remain limited by Lagos wet-bulb temperature profiles but gain traction in Abuja's elevated plateau climate.
Direct expansion holds installed capacity. Chilled water systems are gaining share fastest.
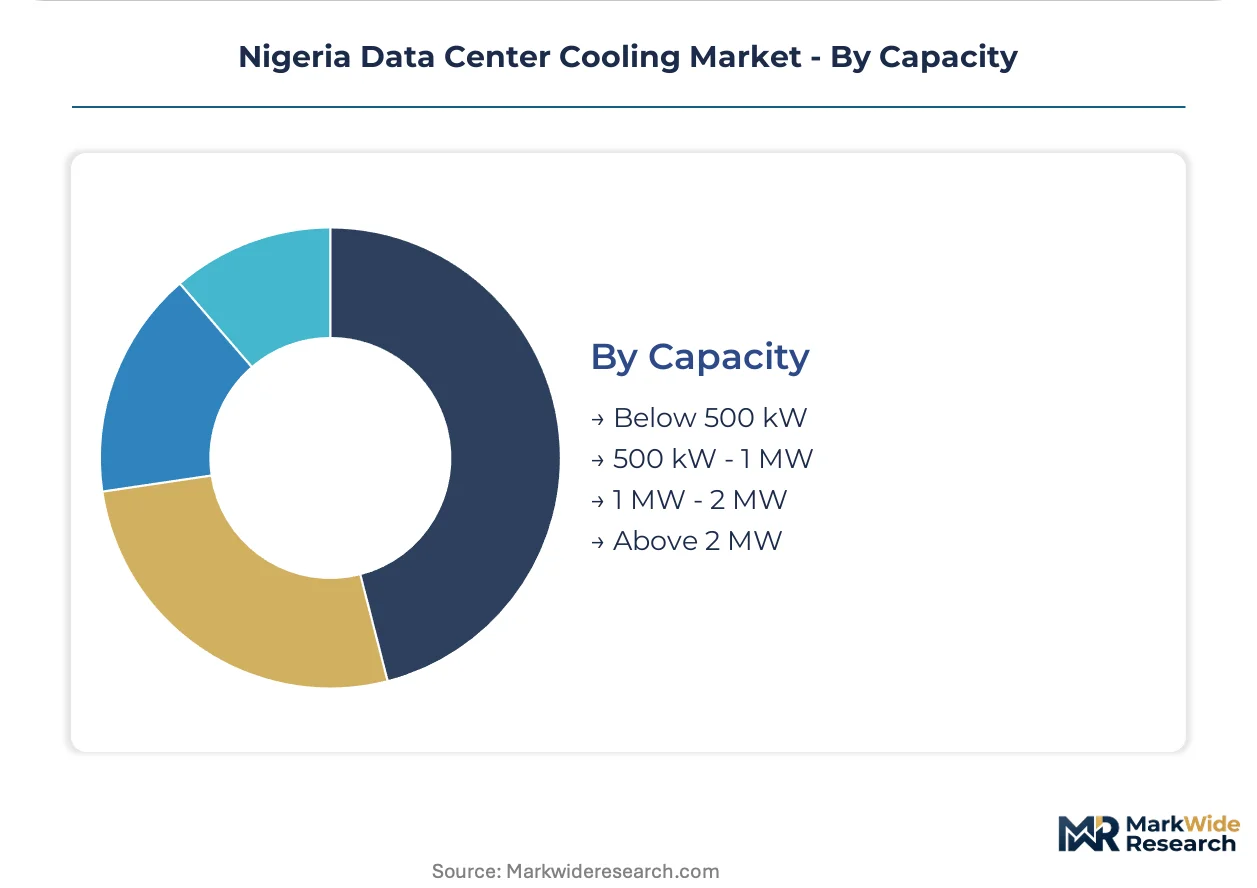
Capacity:
Facility scale determines infrastructure architecture, backup power requirements, and vendor engagement models.
- Above 2 MW:Hyperscale facilities require centralized chilled water plants with N+1 redundancy and redundant backup cooling power architectures compliant with Nigerian Electricity Regulatory Commission interconnection standards.
- 1 MW - 2 MW:Mid-scale colocation facilities in Abuja government cloud initiatives specify cooling systems meeting national security certification requirements.
- 500 kW - 1 MW:Regional banking data centers favor modular air-cooled plants with containerized delivery for 12-week deployment windows.
- Below 500 kW:Edge micro-modular units capture banking sector installations requiring rapid deployment with limited on-site technical labor.
Sub-500 kW capacity holds installed base. Above 2 MW deployments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Nigerian data center corridors. Lagos buyers absorb premium pricing for liquid cooling infrastructure, while Abuja government procurement prioritizes compliance-certified systems regardless of cost. Secondary city deployments remain highly price-sensitive due to constrained capital budgets.
Lagos State
Hyperscale cloud operators and colocation providers drive concentrated demand along the Lekki Free Trade Zone corridor. The National Information Technology Development Agency's efficiency mandates apply to federal facilities, while state-level investment promotion authorities fast-track power infrastructure for certified data center zones. Lekki-Epe Expressway clustering enables shared chilled water infrastructure across multiple tenant environments.
Federal Capital Territory (Abuja)
Federal digital transformation initiatives anchor sovereign cloud capacity requirements. The National Information Technology Development Agency enforces mandatory energy benchmarks for government data centers, accelerating replacement cycles for legacy cooling systems. Central Business District and Jabi district deployments concentrate Tier-III facilities serving national security and financial regulatory functions.
Rivers State (Port Harcourt)
Oil and gas sector captive data centers sustain demand for ruggedized cooling systems adapted to humid coastal conditions. The country's central electricity regulator imposes grid interconnection standards that inflate backup power architecture costs. Onne Free Zone industrial clustering supports energy sector-specific facilities with N+1 redundancy requirements.
Oyo State (Ibadan)
Regional banking data centers and educational institution servers represent emerging edge deployment opportunities. Technical labor scarcity limits liquid cooling feasibility, favoring air-cooled modular units with simplified maintenance protocols. Moniya technology corridor development is attracting containerized cooling system deployments with rapid delivery requirements.
Kano State
Northern Nigeria's commercial hub generates demand for telecommunications aggregation points and retail banking infrastructure. Grid instability drives specification of diesel-integrated backup cooling power architectures. Bompai industrial district hosts legacy facilities undergoing efficiency retrofits to meet evolving power usage effectiveness thresholds.
Nigeria Data Center Cooling Market Competitive Landscape
Capability concentration sits with European and North American engineering specialists; scale advantage sits with integrated power and infrastructure conglomerates. The vendor base stratifies into three tiers: full-lifecycle service providers, precision thermal management specialists, and modular equipment fabricators. Dominant competitive moves include pre-qualification of equipment for Nigerian voltage standards and humidity profiles, plus localization of technical certification pathways to compress deployment timelines.
Within the integrated infrastructure tier, Schneider Electric SE anchors large-scale deployments through combined power and cooling portfolio offerings. Vertiv Group Corp occupies a position among thermal management specialists targeting edge and hyperscale configurations. STULZ GmbH exemplifies precision air conditioning engineering adapted to regional climate profiles. These three European-headquartered entities represent distinct archetypes: the converged infrastructure provider, the thermal specialist, and the climate-adapted precision engineer.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| STULZ GmbH |
| Rittal GmbH & Co. KG |
| Johnson Controls International plc |
| Mitsubishi Electric Corporation |
| Daikin Industries, Ltd. |
| Emerson Electric Co |
| Carrier |
| Others |
Pricing and Supply Chain Analysis
Lekki Free Trade Zone clustering concentrates precision cooling equipment staging capacity, compressing procurement timelines for hyperscale operators and amplifying vendor pricing power through reduced logistics friction. This geographic concentration shapes how colocation providers negotiate lifecycle service contracts against compressed deployment schedules.
Pricing Analysis
Lifecycle service revenue tiers—spanning preventive maintenance contracts, emergency response retainers, and extended warranty packages—drive lifetime value capture for cooling infrastructure vendors. Three-tier pricing structure across premium, standard, and economy levels separates N+1 redundant chilled water plants from modular DX units and basic air-cooled edge cabinets. Cost compression in standard-tier equipment is intensifying because original equipment manufacturers consolidate aftermarket service scopes. Banking sector edge deployments exhibit highest price sensitivity due to constrained capital budgets, while federal government cloud initiatives in Abuja demonstrate lowest sensitivity given sovereign compliance mandates.
Supply Chain Analysis
Contract manufacturing concentration for precision cooling components rests with European and North American engineering specialists, with Schneider Electric SE, Vertiv Group Corp, and STULZ GmbH anchoring fabrication networks. Supply draws from Germany, France, and the United States for chiller compressors and control systems; copper tubing and aluminum heat exchangers feed from Chinese and Indian metalworking clusters. Single-source vulnerability concentrates in refrigerant supply chains subject to F-Gas Regulation alignment delays. Distribution runs through Lagos-based mechanical contractors with NITDA-certified technicians, extending to Abuja government procurement offices and Port Harcourt energy sector facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU cluster density above 30 kW per rack is disrupting legacy air-cooled architectures, creating a narrow window for thermal management vendors to capture hyperscale contracts before procurement specifications standardize around liquid cooling.
For Market Incumbents: Entrench N+1 service capabilities through captive certification programs for Nigerian refrigeration technicians, insulating against emerging local mechanical contractors unbundling preventive maintenance scopes. Deepen upstream control over coolant distribution unit fabrication to defend margin position against European competitors pre-qualifying equipment for West African humidity profiles. For New Entrants and Emerging Players: Establish a beachhead in Abuja government cloud initiatives where sovereign security certification requirements create procurement friction for established Lagos-focused vendors. Target Tier-III facility developers in the Central Business District with rapid-deployment containerized cooling systems, leveraging thinner incumbent presence outside Lekki corridor clustering. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision thermal management specialists with liquid cooling IP portfolios over integrated infrastructure conglomerates exposed to air-cooled legacy revenue erosion. Long-term viability hinges on ASHRAE compliance verification capabilities as NITDA carbon reporting guidelines mature. Monitor NITDA efficiency mandate enforcement intensity as the inflection signal distinguishing replacement cycle acceleration from status quo maintenance spend.| Strategic Initiative | Industry Significance |
|---|---|
| Local Technician Certification Program | NITDA-certified labor pools reduce deployment risk for Abuja government cloud contracts. |
| Liquid Cooling IP Acquisition | Cold plate manifold patents secure positioning for GPU cluster density above 30 kW. |
| Harmattan-Season Economizer Development | Evaporative hybrid systems reduce mechanical refrigeration dependency during dry operations. |
| Free Trade Zone Staging Facility | Lekki corridor presence compresses procurement timelines for hyperscale availability zones. |
| Carbon Reporting Platform Integration | Automated sustainability instrumentation aligns with forthcoming NITDA federal data center guidelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center engineering directors, colocation procurement leads, NITDA compliance officers, and mechanical contracting firms; and secondary validation through Standards Organisation of Nigeria equipment safety filings, Nigerian Electricity Regulatory Commission interconnection standards, and hyperscaler capex disclosure documents. Bottom-up facility-level capacity assessments and top-down macro infrastructure investment flows were triangulated to anchor market sizing.
Forecast inputs considered cooling technology substitution curves, regulatory compliance timeline acceleration, and hyperscale deployment pipeline visibility across the analysis window. Segmentation dimensions modeled include cooling type, facility capacity tier, end-user risk profile, and regional infrastructure maturity. CAGRs were derived from installed base replacement cycles and new build pipeline conversion rates, incorporating GPU cluster density ramp assumptions and NITDA efficiency mandate enforcement scenarios.
Stress conditions across grid stability deterioration, foreign exchange access restriction intensity, and ASHRAE compliance verification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding international cloud operator commitment persistence and federal digital transformation budget continuity. Quarterly review of NITDA guideline publication cadence and Lekki corridor power infrastructure commissioning schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market