
 Europe District Cooling Market | 2026-2036
Europe District Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe District Cooling Market Analysis
Chilled water distribution architecture is fragmenting across decentralized thermal energy storage nodes and smart metering overlays. Veolia leverages its multi-city concession footprint to anchor large-scale district cooling operations in Paris and Lyon. Vattenfall competes through deep geothermal and seawater integration in Stockholm and Amsterdam. Engie differentiates via combined heat and power synergies that sustain year-round plant utilization across its Southern European networks.
District cooling delivers centralized refrigeration through insulated pipe networks distributing chilled water or secondary coolant to multiple buildings, typically operating at supply temperatures between 4°C and 7°C with return differentials of 8°C to 12°C. The technology displaces individual rooftop units in dense urban zones where heat rejection constraints and noise limits apply. Ice storage and thermal energy storage segments capture peak-shaving value where time-of-use electricity tariffs create arbitrage opportunities for chilled inventory. Commercial buildings represent the mature revenue base, while district energy systems integration with municipal heat networks constitutes the fastest-growing structural opportunity as cities pursue sector coupling.
The EU Green Deal and F-Gas Regulation constrain synthetic refrigerant deployment, pushing operators toward natural refrigerants and seawater loops that ECHA evaluates under REACH chemical safety protocols. CE marking and MDR conformity requirements shape equipment procurement standards for network components and heat exchangers that Alfa Laval and Danfoss supply. Stakeholders must monitor how CSRD disclosure mandates alter capital allocation toward retrofitted distribution infrastructure versus greenfield pipeline investments.
Market Dynamics
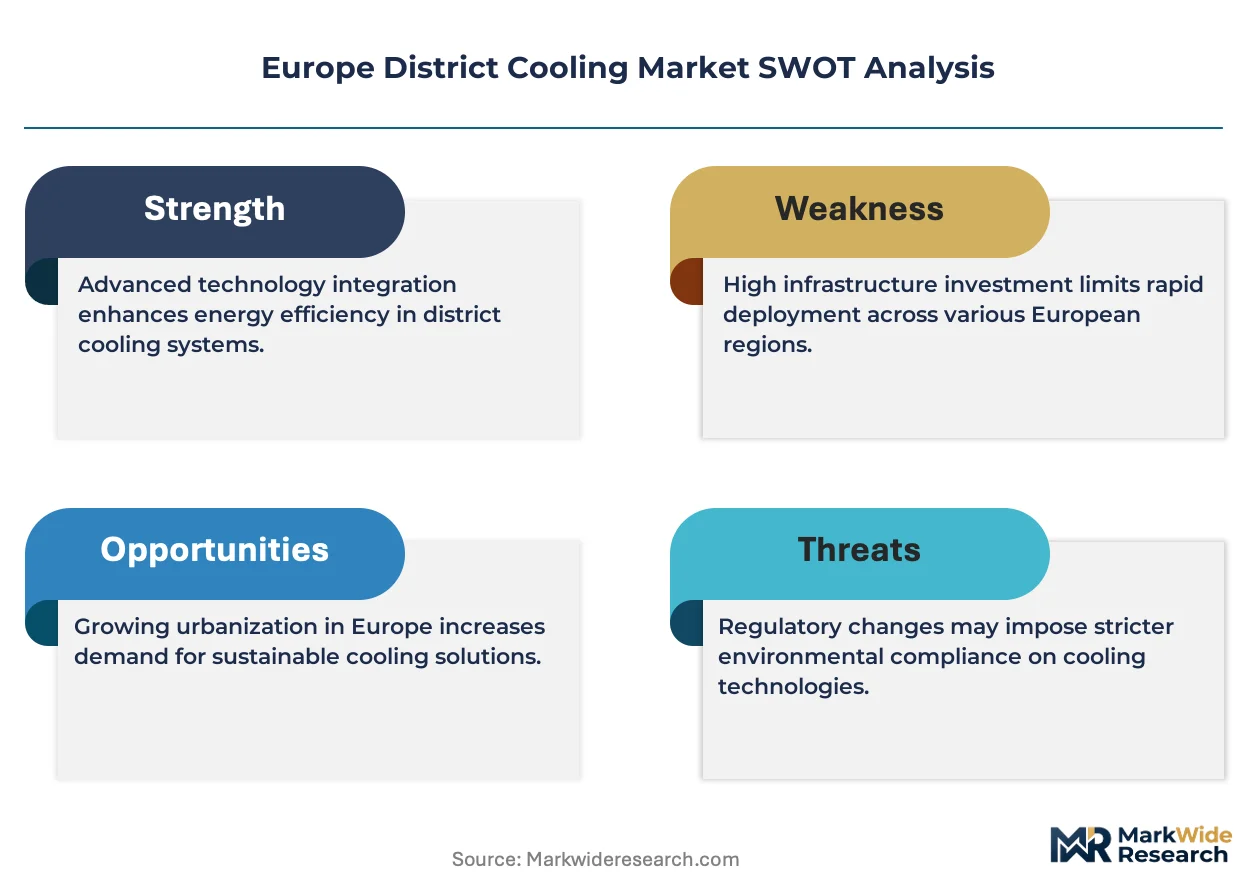
The EU Green Deal's building efficiency mandates are forcing commercial property operators across Stockholm, Paris, and Dubai to abandon standalone rooftop cooling in favor of networked thermal infrastructure. This regulatory pressure is compressing payback periods for district cooling investments and accelerating utility concession renewals.
Growth Catalysts
- EU Green Deal building mandates:The European Commission's 2030 energy performance targets require commercial buildings over 5,000 square meters to meet stringent cooling efficiency benchmarks, directly expanding district cooling connections in Lyon and Frankfurt.
- Seawater source availability:Scandinavian urban clusters leverage cold Baltic Sea and North Atlantic water loops to deliver near-zero carbon cooling, creating cost advantages that individual building systems cannot replicate.
- Commercial real estate consolidation:Institutional investors in Paris, Amsterdam, and Stockholm are bundling cooling procurement across multi-building portfolios, favoring centralized thermal service contracts over fragmented equipment ownership.
Market Restraints
- Copper and polymer pipe input volatility:Insulated distribution network materials face price swings tied to global commodity markets, squeezing contractor margins on fixed-price infrastructure projects.
- Geographic supply concentration:Specialized district cooling engineering expertise clusters in Nordic and Benelux consultancies, creating bottlenecks for Southern European greenfield deployments.
- F-Gas Regulation refrigerant constraints:The European Commission's phasedown of hydrofluorocarbons limits synthetic coolant options, forcing costly plant retrofits toward ammonia or seawater alternatives.
Strategic Opportunities
- Spanish and Italian district heating convergence:Underpenetrated Southern European cities including Madrid and Milan offer white space for integrated heat-and-cool networks that improve year-round plant utilization rates.
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive requires granular Scope 2 emissions tracking, pushing commercial landlords toward metered district cooling with verified carbon accounting.
- Thermal storage and smart grid convergence:Ice storage systems paired with demand-response platforms enable arbitrage against time-of-use electricity tariffs, creating new revenue streams for network operators.
Industry Challenges
- Refrigeration technician scarcity:Natural refrigerant expertise remains concentrated in Northern European training programs, slowing ammonia-based plant commissioning in newer markets.
- Legacy building retrofit complexity:Integrating 19th-century Parisian and Viennese structures with modern chilled water distribution requires bespoke engineering that extends project timelines.
- CE marking and MDR compliance timelines:Heat exchanger and valve certification under updated medical device and machinery directives delays equipment procurement for network expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe District Cooling Market |
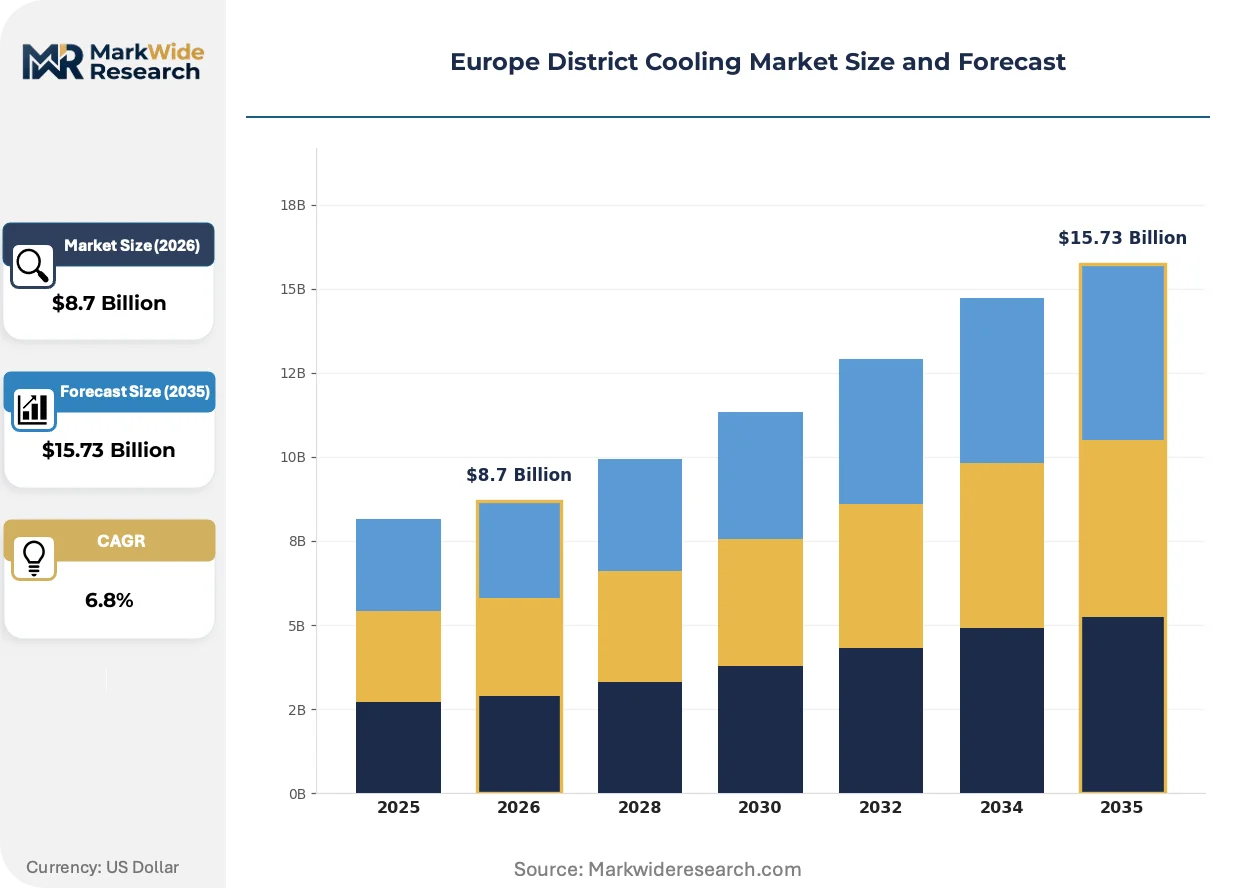
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chilled Water Systems, Ice Storage, Thermal Energy Storage, Air Cooled Systems Application: Commercial Buildings, Residential Complexes, Industrial Facilities, District Energy Systems End User: Property Developers, Facility Managers, Municipalities, Energy Providers Service Type: Design & Installation, Operation & Maintenance, Consulting Services, Technology Solutions |
| Companies Covered | Veolia, Vattenfall, Fortum, Engie, Danfoss, Logstor, Ramboll, Alfa Laval, Siemens, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe District Cooling Market Emerging Trajectories
Digital instrumentation and predictive analytics are transforming how district cooling networks balance load, detect leaks, and optimize energy consumption across multi-kilometer pipe infrastructure. These capabilities are compressing operational margins for operators who fail to modernize.
Advanced metering infrastructure is digitizing thermal energy accounting at the building level. Commercial landlords in Stockholm and Amsterdam are deploying sub-hourly consumption tracking to align cooling charges with actual usage patterns. This granularity is digitizing tenant billing relationships and enabling dynamic pricing structures that reflect real-time grid conditions.
The F-Gas Regulation's refrigerant phase-down is accelerating natural coolant adoption across EU member states. Ammonia and carbon dioxide systems now dominate new plant specifications in Germany and France, displacing hydrofluorocarbon-based equipment. District cooling operators in Copenhagen and Helsinki are responding by retrofitting existing plants and securing long-term service contracts for natural refrigerant maintenance.
Building operators are unbundling cooling service procurement from capital equipment ownership. Institutional investors in Paris and Lyon now favor thermal energy supply agreements with guaranteed efficiency performance over direct chiller purchases. This preference shift is most visible in commercial office segments, where facility managers prioritize operational expenditure predictability over asset control.
Europe District Cooling Market Segmentation
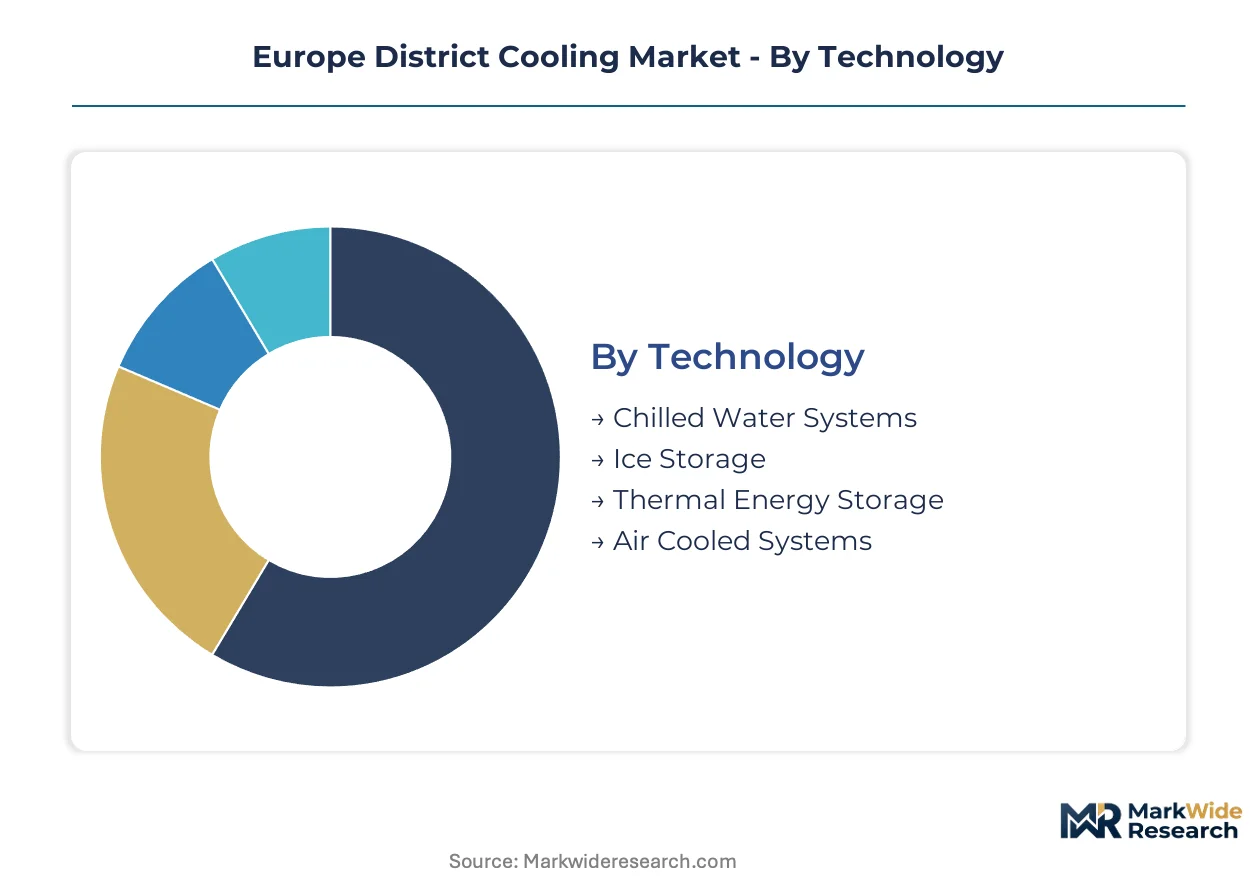
District cooling networks fragment across technology generations, application contexts, and procurement models that shape capital deployment patterns. Understanding these divides reveals where infrastructure investments concentrate and which service relationships sustain recurring revenue.
Technology:
The use-case spectrum spans legacy chilled water distribution to emerging thermal storage architectures that arbitrage electricity tariffs.
- Chilled Water Systems:Conventional insulated pipe networks circulate water at 4°C to 7°C supply temperatures across urban districts. Swedish and Finnish operators prioritize these systems in dense Stockholm and Helsinki commercial cores where seawater source availability minimizes refrigeration load.
- Thermal Energy Storage:Underground tanks and stratified storage vessels inventory chilled capacity for peak-shaving operations. German facility managers in Frankfurt and Munich deploy these systems where time-of-use electricity pricing creates arbitrage value against afternoon cooling peaks.
- Ice Storage:Phase-change systems freeze water during off-peak hours for daytime discharge. French operators integrate these units in Lyon and Paris where nuclear baseload electricity supports overnight charging economics.
- Air Cooled Systems:Dry cooler configurations serve Southern European extensions where water scarcity constrains evaporative cooling. Italian deployments in Milan favor these units for satellite network nodes.
The dominant share belongs to Chilled Water Systems, while Thermal Energy Storage is closing the gap fastest.
Application:
Cost tier differentiation separates premium urban core installations from peripheral extensions where load density thins.
- Commercial Buildings:Office towers, retail complexes, and hospitality assets above 5,000 square meters constitute the revenue anchor. Parisian La Défense and Amsterdam Zuidas business districts concentrate connection volumes where EU Green Deal efficiency mandates compel networked cooling over rooftop units.
- District Energy Systems:Integrated heat-and-cool networks couple municipal thermal infrastructure for year-round plant utilization. Copenhagen and Stockholm operators expand these configurations to improve asset turnover across heating and cooling seasons.
- Industrial Facilities:Data centers, pharmaceutical manufacturing, and cold chain logistics drive precision cooling demand. Dutch greenhouse operators in Westland deploy district cooling for climate-controlled agriculture.
- Residential Complexes:Multi-family housing developments in Mediterranean cities adopt shared cooling where individual unit installation proves impractical. Spanish social housing programs in Madrid pilot these connections.
Commercial Buildings command the installed base, though District Energy Systems show the steepest expansion trajectory as cities pursue sector coupling.
End User:
Customer type determines contract structure, with institutional procurement favoring long-term concessions over transactional equipment sales.
- Property Developers:Pre-construction cooling service agreements secure thermal infrastructure for mixed-use projects. Benelux developers in Rotterdam and Brussels bundle district connections into building certification packages.
- Facility Managers:Operational control over existing building portfolios drives retrofit decisions. Swedish commercial landlords in Stockholm's Kista district convert rooftop chiller fleets to networked supply.
- Municipalities:City-owned utilities anchor network expansion through concession financing. French municipal operators in Lyon and Grenoble extend pipe infrastructure via public-private partnerships.
- Energy Providers:Integrated utilities cross-sell cooling alongside electricity and heat contracts. Vattenfall and Engie leverage generation assets to underwrite thermal network investments.
Property Developers hold the contract origination edge, while Energy Providers are gaining share fastest through bundled utility offerings.
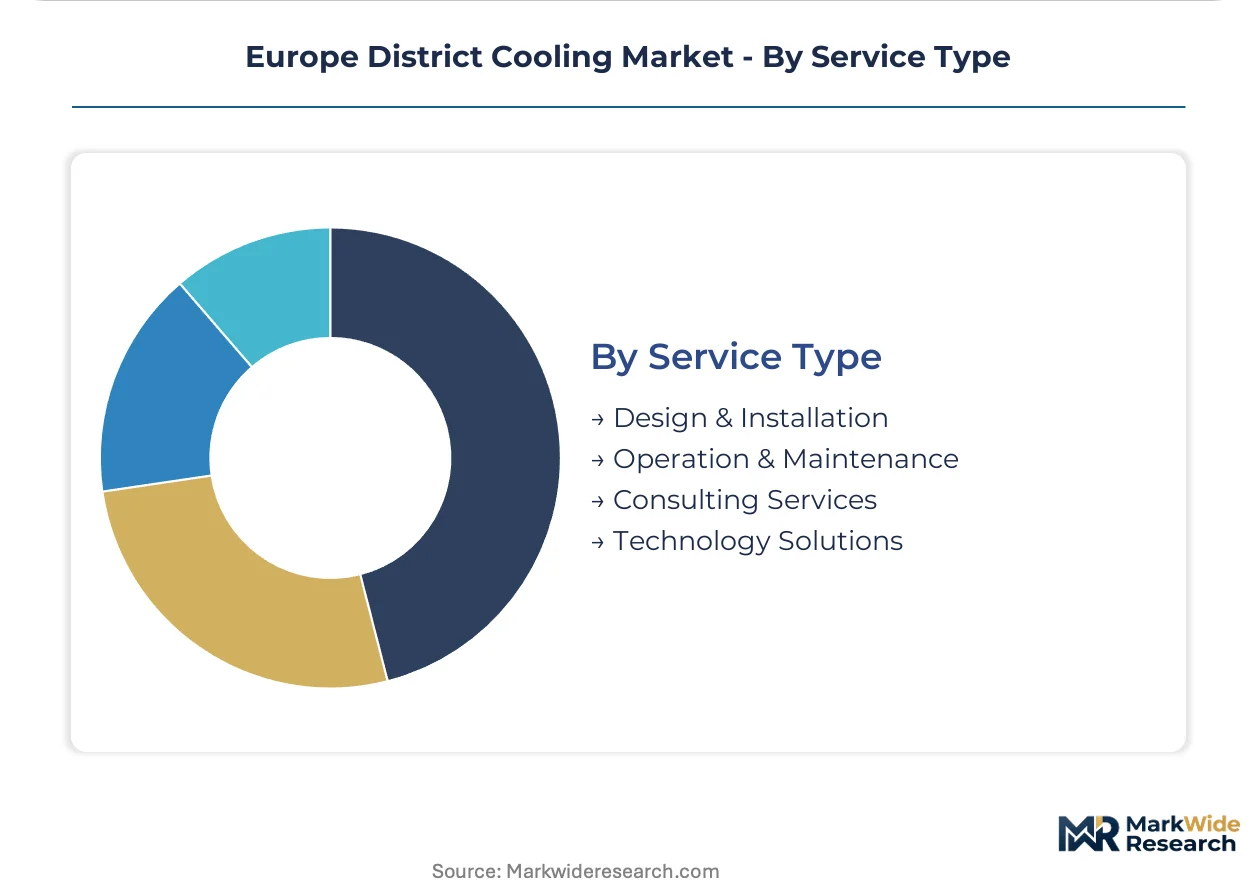
Service Type:
Margin structure varies sharply between capital-intensive installation phases and recurring operational contracts.
- Operation & Maintenance:Long-term service agreements covering plant operation, pipe monitoring, and energy optimization. German operators in Hamburg and Berlin secure 15-20 year contracts that lock in recurring revenue streams.
- Design & Installation:Front-end engineering and construction of distribution networks and central plants. Nordic consultancies concentrate this expertise for complex seawater intake and geothermal integration projects.
- Technology Solutions:Digital platforms for predictive maintenance, demand forecasting, and smart metering integration. Dutch startups supply cloud-based thermal accounting to Amsterdam network operators.
- Consulting Services:Feasibility studies, regulatory compliance support, and financing structure advisory. French engineering firms advise on CSRD disclosure alignment for commercial landlord clients.
Operation & Maintenance captures the dominant value pool, while Technology Solutions is climbing the fastest as digital instrumentation penetrates legacy networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish engineering consultancies export district cooling expertise to German and French municipal utilities, anchoring cross-border technology transfer corridors that shape European infrastructure deployment patterns.
Sweden
Stockholm's Kista district and Gothenburg harbor zones drive connection growth through seawater source integration. The EU Green Deal's building efficiency mandates compress payback periods for networked cooling retrofits. Vattenfall operates deep geothermal and Baltic Sea loops across the capital region.
Germany
Frankfurt's banking district and Munich's commercial cores abandon rooftop chillers for centralized thermal service. The F-Gas Regulation forces synthetic refrigerant phase-out, accelerating ammonia plant adoption. Hamburg operators secure 15-20 year operation contracts locking recurring revenue streams.
France
Paris La Défense and Lyon commercial towers bundle cooling procurement through concession agreements. CE marking and MDR conformity requirements shape heat exchanger procurement from equipment suppliers. Engie leverages combined heat and power synergies across Southern European networks.
Netherlands
Amsterdam Zuidas and Rotterdam port districts integrate district cooling with municipal heat networks for year-round plant utilization. The CSRD disclosure mandate pushes commercial landlords toward metered thermal accounting. Dutch greenhouse operators in Westland deploy precision cooling for climate-controlled agriculture.
Finland
Helsinki's dense commercial core prioritizes chilled water networks where Gulf of Finland seawater minimizes refrigeration load. REACH chemical safety protocols evaluate natural refrigerant alternatives under ECHA oversight. Fortum anchors network expansion through integrated utility offerings across the capital region.
Europe District Cooling Market Vendor Landscape
On the supply side, the industry is consolidating around multi-utility conglomerates with generation assets and municipal concession relationships. Tiered competitive positioning separates integrated energy providers from specialized engineering consultancies and component fabricators. Strategic archetypes include seawater-cooling specialists, thermal storage integrators, and digital platform vendors. Dominant competitive moves encompass concession renewal acceleration and cross-border technology licensing partnerships.
Among Nordic integrated utilities, Vattenfall and Fortum exemplify the asset-heavy archetype leveraging generation portfolios to underwrite network investments. Veolia occupies a position representing the multi-service concession model spanning Paris and Lyon operations. These three entities anchor competitive dynamics through bundled thermal service contracts that displace fragmented equipment ownership across commercial building portfolios.
| Leading Market Players |
|---|
| Veolia |
| Vattenfall |
| Fortum |
| Engie |
| Danfoss |
| Logstor |
| Ramboll |
| Alfa Laval |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Swedish and Finnish engineering consultancies anchor specialized district cooling design expertise, concentrating margin capture in the front-end engineering phase where Nordic firms command premium rates for seawater intake and geothermal integration projects. This upstream knowledge concentration shapes downstream procurement patterns as French and German utilities pay licensing premiums for cross-border technology transfer.
Pricing Analysis
Legacy chilled water systems trade at commodity rates while thermal energy storage and ice storage configurations capture generation premiums. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in standard-tier installations intensifies as copper and polymer pipe volatility squeezes contractor margins. Municipal utilities exhibit highest price sensitivity due to concession financing constraints, while institutional investors in commercial real estate portfolios prioritize operational expenditure predictability over upfront capital minimization.
Supply Chain Analysis
CE marking and MDR conformity requirements function as de facto export controls limiting equipment flows from non-compliant fabricators. Component sourcing concentrates in Germany, Denmark, and Sweden for heat exchangers and insulated pipe networks. Supply chains draw from copper smelters, polymer resin producers, and specialized refrigeration compressor manufacturers. Single-source vulnerability persists for ammonia-compatible heat exchanger designs certified under REACH protocols. Distribution runs through municipal utility procurement channels and EPC contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
District cooling networks constitute a defensive-moat business where regulatory entrenchment through EU Green Deal building mandates creates durable competitive positioning. Incumbent operators leverage concession relationships and physical infrastructure lock-in to sustain returns.
For Market Incumbents: Build switching-cost moats through 15-20 year operation and maintenance contracts that embed digital metering infrastructure. Deepen backward integration into thermal energy storage manufacturing to capture margin from ice storage and stratified tank deployments. Defend against municipal utility insourcing threats by accelerating smart grid integration investments that demonstrate operational superiority.
For New Entrants and Emerging Players: Establish a beachhead in Spanish and Italian district heating convergence opportunities where integrated heat-and-cool networks remain underpenetrated. Target Madrid and Milan municipal utilities with white-label engineering partnerships that transfer Nordic seawater-cooling expertise. Lead with technology solutions offerings—predictive maintenance platforms and demand-response software—that require lower capital commitment than physical infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated utilities with generation assets and established concession footprints across multiple city regions. Monitor CSRD disclosure mandate enforcement intensity as the inflection indicator for accelerated commercial landlord procurement of metered district cooling services. Long-term viability hinges on operators' ability to cross-sell thermal services alongside electricity and heat contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal Acceleration | Extends contract lock-in with Paris and Lyon municipal utilities beyond 2040. |
| Thermal Storage Integration | Captures peak-shaving arbitrage value against French nuclear baseload pricing. |
| Natural Refrigerant Retrofit | Future-proofs German and Danish plants against F-Gas Regulation phase-down timelines. |
| Digital Metering Platform Deployment | Enables CSRD-compliant Scope 2 emissions tracking for Amsterdam commercial landlords. |
| Cross-Border Technology Licensing | Monetizes Swedish seawater-cooling expertise in Southern European greenfield markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with district cooling network operators, municipal utility planning officers, EPC contractors, and commercial real estate facility managers; and secondary validation against EU Green Deal regulatory filings, F-Gas Regulation implementation reports, ECHA REACH chemical safety assessments, and municipal concession contract databases. Bottom-up connection volume estimates triangulated against top-down market sizing derived from utility generation asset disclosures.
Forecast inputs considered technology generation adoption curves, application segment penetration rates, and regulatory compliance cost trajectories across the projection horizon. Segmentation modeling spanned chilled water systems, thermal energy storage, ice storage, and air-cooled configurations crossed with commercial building, district energy system, industrial facility, and residential application contexts. CAGRs were derived from installed base expansion rates and average revenue per connection assumptions. Industry-specific inputs included EU building efficiency mandate enforcement timelines and natural refrigerant technician training program graduation rates.
Stress conditions across copper and polymer commodity price bands, F-Gas Regulation phase-down acceleration scenarios, and municipal concession renewal success rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost decline curves. Material shifts in EU Green Deal building mandate scope or REACH chemical safety protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market