
 Japan Data Center Cooling Market | 2026-2036
Japan Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Cooling Market Insights
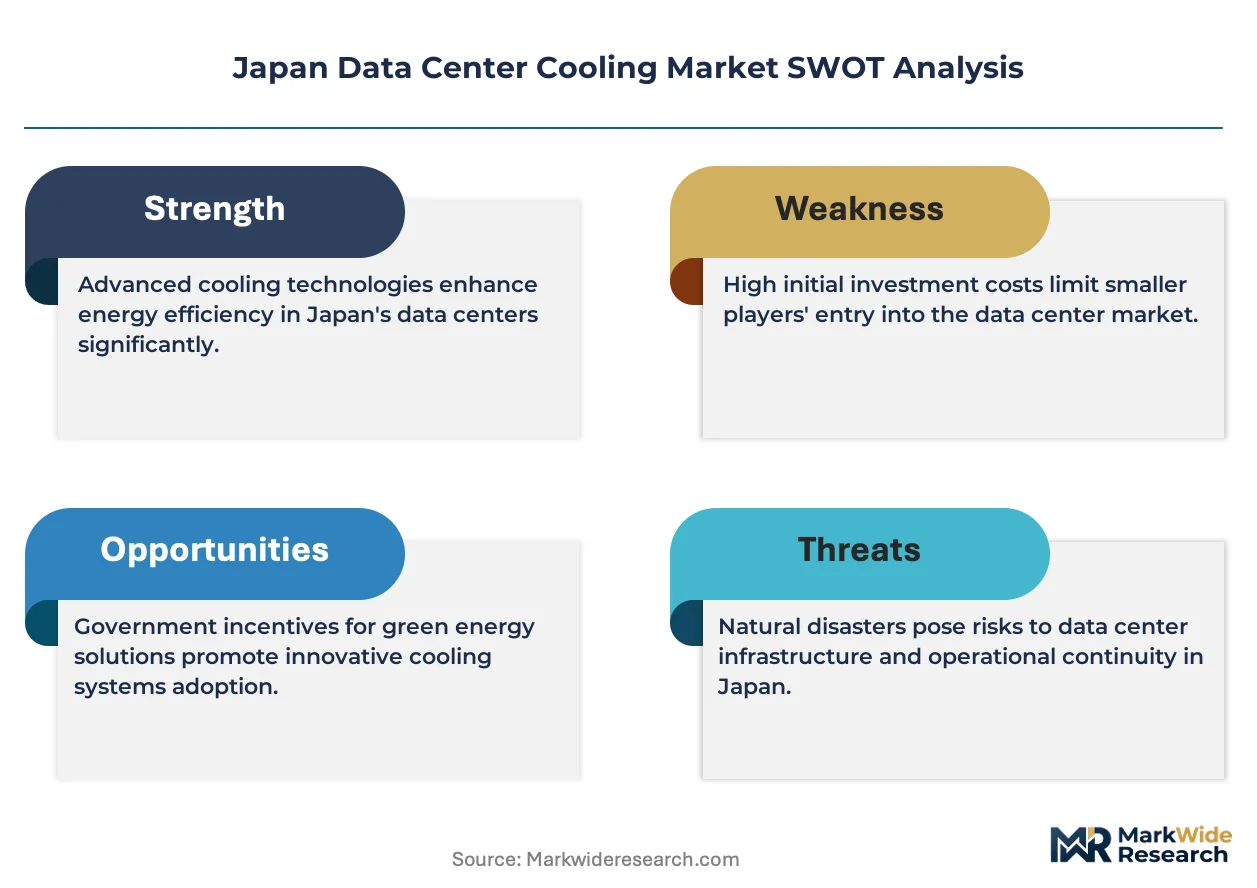
Fluorinated refrigerant phase-down is hardening cost structures for legacy chiller retrofits. Daikin Industries leverages its in-house refrigerant chemistry pipeline to anchor premium positioning in next-generation systems. Mitsubishi Electric dominates precision air conditioning for hyperscale builds through manufacturing scale in domestic plants. Fujitsu differentiates via liquid cooling integration with its own server architectures.
Data center cooling encompasses thermal management systems engineered to maintain IT equipment within operational temperature bands, typically between 18°C and 27°C with humidity controls between 40% and 60% RH, using heat rejection media ranging from compressed refrigerants to dielectric fluids. Liquid cooling is displacing air-based architectures in GPU-dense facilities where rack densities exceed 30 kW per cabinet. Free cooling technology leads deployment economics in Hokkaido and Tohoku zones with lower ambient wet-bulb temperatures. Colocation providers represent the most concentrated buyer segment, with procurement patterns favoring modular, scalable chiller plants.
METI enforces building energy codes that mandate annual power usage effectiveness reporting for facilities above threshold capacities, while JIS standards govern refrigerant leakage detection and containment system integrity. The national regulator's carbon neutrality roadmap is forcing cooling equipment refresh cycles shorter than historical ten-year replacement norms. Stakeholders must monitor refrigerant quota allocations under the revised Fluorocarbons Management Act and assess liquid cooling capex against tightening operational carbon intensity targets.
Market Dynamics
GPU-dense AI infrastructure is compressing cooling refresh cycles across Japanese facilities, forcing operators to abandon ten-year replacement norms in favor of continuous thermal architecture upgrades that align with METI's tightening carbon intensity benchmarks.
Growth Catalysts
- Cloud capacity expansion:Hyperscale providers are scaling domestic infrastructure to serve generative AI training workloads, driving concentrated demand for high-density cooling systems in Greater Tokyo.
- Fluorocarbons Management Act quotas:Refrigerant phase-down mandates are accelerating equipment turnover toward low-GWP alternatives, creating replacement pull across legacy chiller fleets.
- Liquid cooling maturation:Dielectric fluid architectures are crossing cost thresholds that enable adoption beyond supercomputing into mainstream colocation facilities.
Market Restraints
- Refrigerant input volatility:HFC quota allocations under METI enforcement are constraining supply predictability for service-intensive chiller maintenance contracts.
- Geographic supply concentration:Precision air conditioning manufacturing clusters in domestic industrial corridors, exposing procurement timelines to localized logistics disruptions.
- Free cooling zone limitation:Ambient wet-bulb economics restrict passive heat rejection architectures to Hokkaido and Tohoku, excluding high-demand southern prefectures.
Strategic Opportunities
- Fukuoka demand emergence:Submarine cable landing density and earthquake risk diversification are positioning Kyushu as a secondary data center cluster requiring scaled cooling infrastructure.
- JIS refrigerant containment standards:Leak detection and recovery system mandates are creating aftermarket service revenue streams for compliance-certified contractors.
- Modular chiller plant formats:Factory-integrated thermal units are enabling faster deployment timelines that align with cloud provider capacity scaling rhythms.
Industry Challenges
- Thermal-fluid engineering scarcity:Specialized expertise in two-phase cooling system design remains concentrated among a limited pool of domestic practitioners, constraining deployment velocity.
- Legacy integration friction:Retrofitting liquid cooling manifolds into existing raised-floor facilities requires structural modifications that compress project margins and extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Cooling Market |
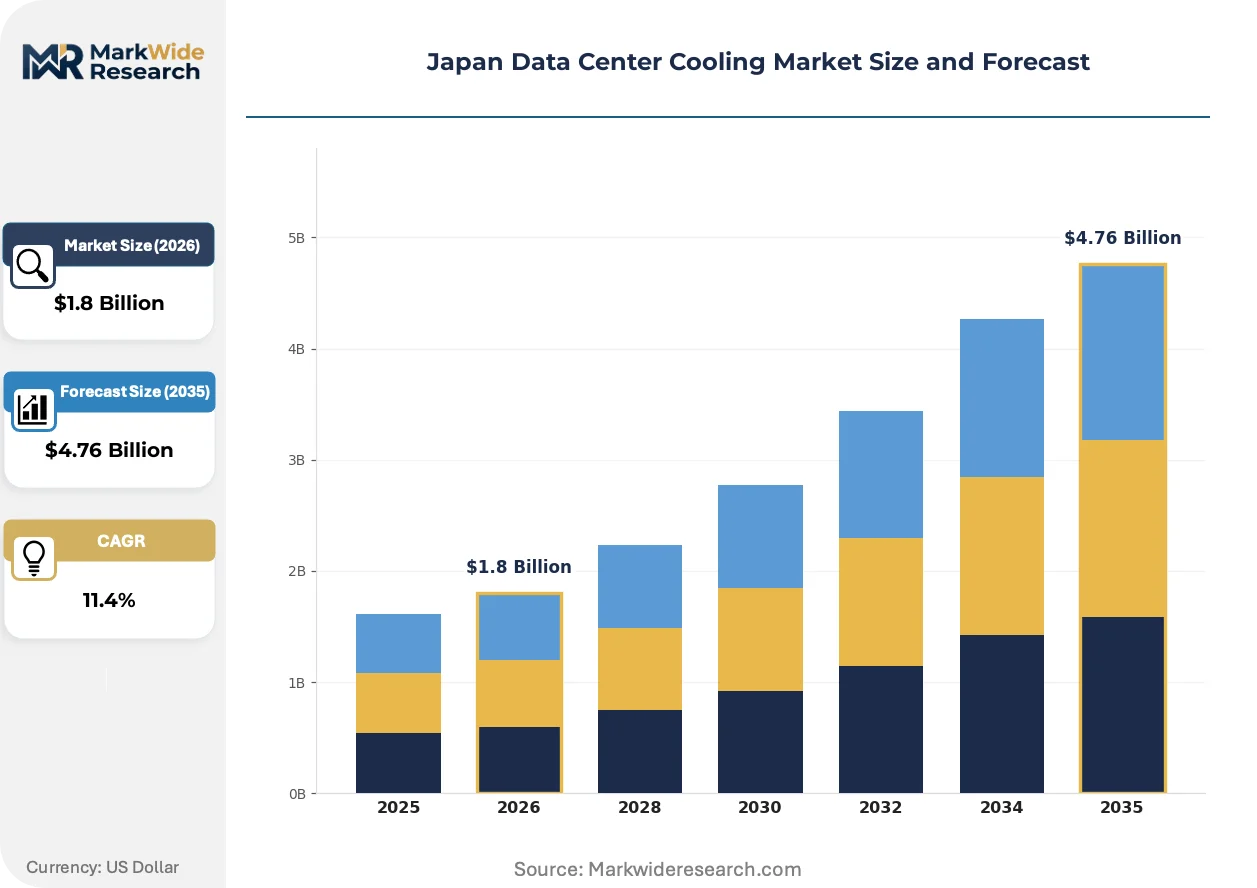
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Chilled Water, Direct Expansion, Liquid Cooling, Air Cooling Technology: Airflow Management, Free Cooling, Evaporative Cooling, Immersion Cooling End User: Colocation Providers, Cloud Service Providers, Enterprises, Telecom Providers Deployment Model: On-Premises, Off-Premises, Hybrid, Multi-Cloud |
| Companies Covered | Daikin Industries Ltd, Schneider Electric SE, Vertiv Group Corp, Mitsubishi Electric Corporation, Johnson Controls Inc, Trane Inc, STULZ GmbH, Fujitsu Limited, Hitachi Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Cooling Market Trends and Innovations
Cooling architectures are fragmenting across thermal management modalities as rack power densities bifurcate the market into air-cooled commodity tiers and liquid-cooled premium tiers with diverging supply chain requirements.
Direct-to-chip liquid cooling is decentralizing thermal management authority from facility-level chiller plants to rack-integrated cooling distribution units. Colocation operators in Osaka are piloting these architectures for 50kW-plus GPU cabinets. The shift is compressing mechanical infrastructure capex into server-adjacent equipment budgets.
METI's carbon neutrality roadmap is mandating annual power usage effectiveness disclosure for facilities above capacity thresholds. Equipment refresh cycles are compressing toward seven-year norms as operators chase efficiency gains. Hyperscale builds in Greater Tokyo are prioritizing systems that demonstrate measurable PUE improvement under JIS measurement protocols.
Colocation procurement is fragmenting across ownership models as operators unbundle thermal infrastructure from facility leases. Cloud providers are negotiating direct equipment purchase agreements with cooling vendors, bypassing traditional contractor intermediaries. This pattern is most visible in Tokyo Bay corridor developments where lease structures now separate shell from mechanical fit-out.
Japan Data Center Cooling Market Segmentation
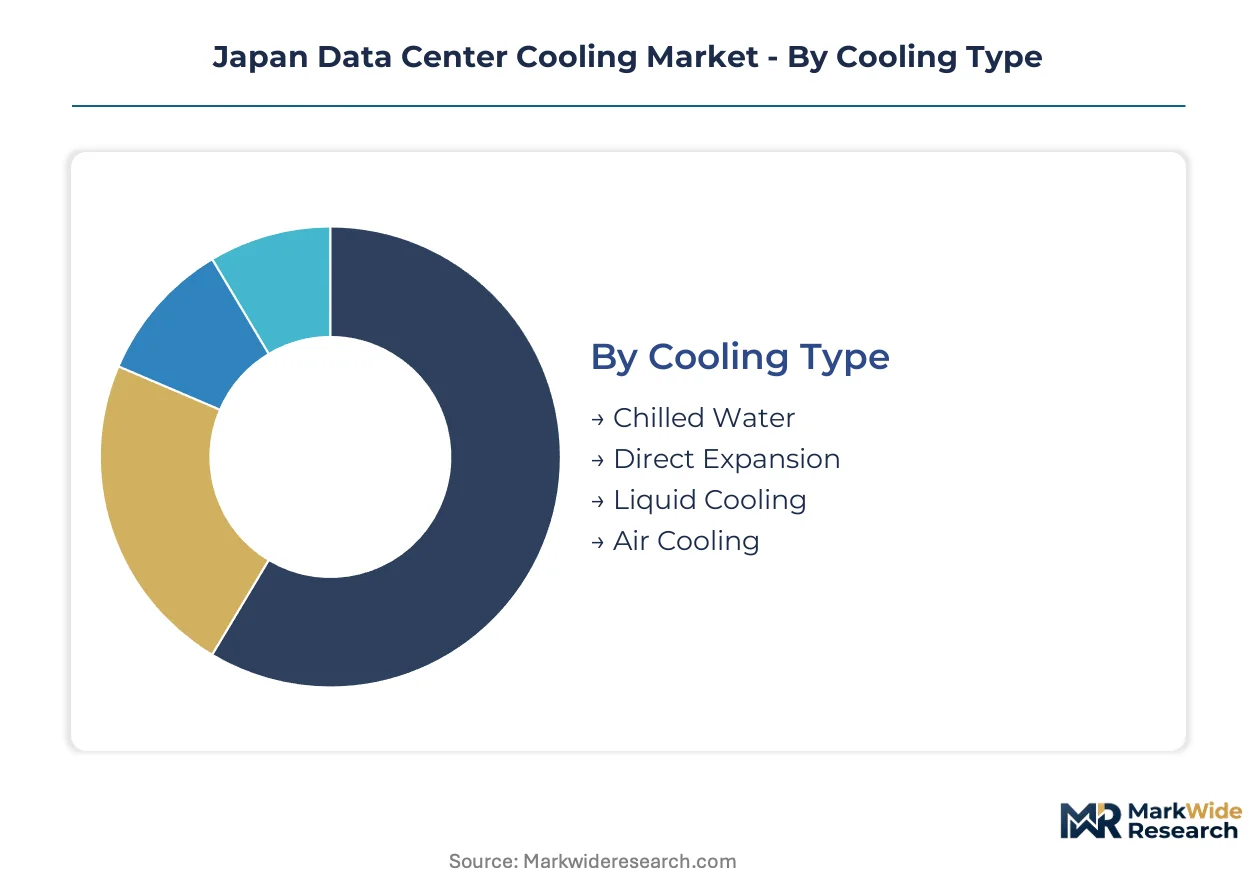
Cooling architecture selection in Japan follows rack density thresholds and METI efficiency mandates. Procurement patterns diverge sharply between legacy facility retrofits and hyperscale new builds.
Cooling Type:
Volume deployment favors established thermal rejection methods. Premium tiers concentrate in GPU-dense configurations.
- Liquid Cooling:Dielectric fluid or water-glycol loops conduct heat directly from high-wattage processors. Cloud service providers in Greater Tokyo deploy these systems for AI training clusters exceeding 50 kW per rack, driven by METI carbon intensity disclosure requirements.
- Chilled Water:Centralized plants distribute conditioned water through facility loops to computer room air handlers. Osaka colocation facilities favor this architecture for its operational familiarity and maintenance contractor availability.
- Direct Expansion:Refrigerant-based split systems eliminate water distribution infrastructure.
- Air Cooling:Conventional raised-floor pressurization dominates legacy enterprise facilities.
Mature deployment sits with Chilled Water. Newer deployment is concentrated in Liquid Cooling.
Technology:
Passive and active thermal management methods compete on ambient climate economics and IT load predictability.
- Free Cooling:Air-side or water-side economizers exploit low wet-bulb temperatures to bypass mechanical refrigeration. Hokkaido hyperscale campuses leverage this method for extended annual operating hours, constrained by southern prefecture humidity levels.
- Immersion Cooling:Servers submerge in engineered dielectric fluids, eliminating fans and air handlers. Fukuoka emerging facilities pilot these systems for earthquake-resilient submarine cable landing stations.
- Airflow Management:Containment and pressurization optimization extends conventional infrastructure viability.
- Evaporative Cooling:Adiabatic processes supplement mechanical cooling in dry climate windows.
Established deployment centers on Airflow Management. Experimental deployment is expanding in Immersion Cooling.
End User:
Customer scale and thermal expertise determine ownership model and procurement channel.
- Cloud Service Providers:Hyperscale operators design bespoke thermal architectures aligned with server refresh cycles. These buyers negotiate direct equipment procurement, bypassing traditional contractor relationships in Tokyo Bay corridor developments.
- Colocation Providers:Multi-tenant facility operators standardize on modular, scalable chiller plants to accommodate diverse client densities. Osaka and Fukuoka markets show concentrated demand from this segment.
- Enterprises:Corporate captive data centers favor conservative replacement timelines.
- Telecom Providers:Edge and central office facilities prioritize footprint minimization.
Consolidated procurement sits with Colocation Providers. Direct vendor engagement is expanding fastest among Cloud Service Providers.
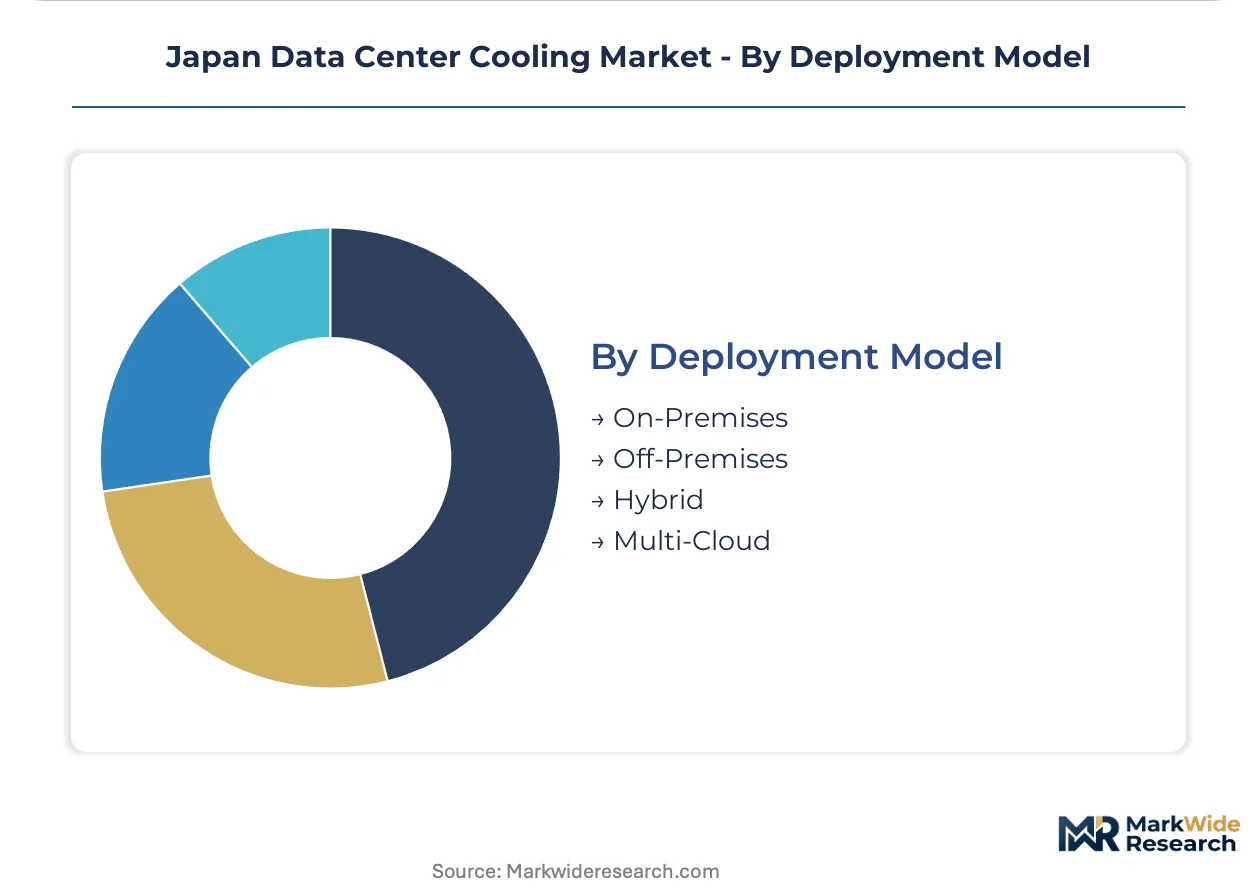
Deployment Model:
Infrastructure location strategy shapes cooling redundancy requirements and energy sourcing options.
- On-Premises:Captive facilities integrate cooling with corporate real estate portfolios. Enterprises in Greater Tokyo maintain these deployments for latency-sensitive workloads, constrained by urban land scarcity and METI building energy codes.
- Off-Premises:Third-party operated facilities unbundle thermal infrastructure from IT equipment ownership. Cloud providers favor this model for rapid capacity scaling without capital commitment.
- Hybrid:Split workload placement across owned and leased infrastructure.
- Multi-Cloud:Distributed architecture across competing service providers.
Legacy ownership sits with On-Premises. Capacity expansion is concentrating in Off-Premises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's special data center zones concentrate national capacity. METI's building energy codes and carbon neutrality mandates are compressing equipment refresh cycles across all prefectures.
Kanto/Tokyo
Hyperscale cloud providers and colocation operators drive concentrated demand for liquid cooling systems. METI enforces annual power usage effectiveness reporting for facilities above threshold capacities. The Tokyo Bay corridor hosts the densest cluster of GPU-dense AI training facilities requiring continuous thermal architecture upgrades.
Kansai/Osaka
Colocation providers favor modular chiller plants for multi-tenant operational familiarity. JIS standards govern refrigerant leakage detection and containment system integrity. Osaka's industrial corridor maintains precision air conditioning manufacturing scale serving domestic hyperscale builds.
Kyushu/Fukuoka
Submarine cable landing density and earthquake risk diversification are positioning the region as a secondary data center cluster. The Fluorocarbons Management Act accelerates equipment turnover toward low-GWP alternatives. Fukuoka emerging facilities pilot immersion cooling systems for resilient infrastructure.
Hokkaido
Low ambient wet-bulb temperatures enable extended free cooling operating hours for hyperscale campuses. METI's carbon neutrality roadmap forces cooling equipment refresh cycles shorter than historical norms. Sapporo and surrounding zones attract facilities prioritizing passive heat rejection economics.
Tohoku
Cooler climate conditions support air-side and water-side economizer deployment. The revised Fluorocarbons Management Act constrains refrigerant quota allocations for service-intensive maintenance contracts. Sendai anchors regional data center development with modular thermal infrastructure scaling.
Japan Data Center Cooling Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Domestic industrial conglomerates with captive refrigerant chemistry and precision manufacturing capabilities anchor premium positioning. Foreign multinationals compete through global service networks and modular system portfolios. Competitive moves center on direct equipment procurement agreements with hyperscale operators and factory-integrated thermal unit formats that compress deployment timelines.
Among Japan-based industrial groups, Daikin Industries Ltd, Mitsubishi Electric Corporation, and Fujitsu Limited exemplify distinct competitive archetypes. Daikin Industries Ltd leverages in-house refrigerant chemistry pipelines. Mitsubishi Electric Corporation occupies a position in precision air conditioning manufacturing scale. Fujitsu Limited represents integration between liquid cooling architectures and server system design. These domestic entities compete with foreign specialists including Schneider Electric SE, Vertiv Group Corp, and Johnson Controls Inc, which anchor global service and modular platform capabilities.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Schneider Electric SE |
| Vertiv Group Corp |
| Mitsubishi Electric Corporation |
| Johnson Controls Inc |
| Trane Inc |
| STULZ GmbH |
| Fujitsu Limited |
| Hitachi Ltd |
| Others |
Pricing and Supply Chain Analysis
Cloud service provider procurement of liquid cooling systems for GPU-dense AI clusters is compressing supplier lead times and forcing domestic manufacturers to reconfigure production schedules, which in turn is bifurcating pricing into expedited-premium and standard-contract tiers.
Pricing Analysis
Expedited lead-time premiums now dominate pricing negotiations for hyperscale builds in Greater Tokyo. Three-tier pricing structure across premium, standard, and economy levels separates factory-integrated modular units from site-assembled chiller plants and refurbished legacy equipment. Cost compression in standard-tier air-cooled systems is intensifying because refrigerant quota constraints under METI enforcement are elevating service contract costs. Colocation providers exhibit the highest price sensitivity due to multi-tenant margin pressure, while cloud service providers prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Specialized thermal-fluid engineering talent scarcity in Osaka and Nagoya industrial corridors is constraining precision air conditioning output expansion. Manufacturing concentrates in Japan, South Korea, and Germany for compressor assemblies, heat exchangers, and refrigerant chemistry. Supply chains draw from copper tubing, rare-earth magnets, and engineered dielectric fluids as critical inputs. Single-source vulnerability sits with domestic refrigerant formulation capacity under Fluorocarbons Management Act quotas. Distribution runs through direct equipment procurement agreements with hyperscale operators, bypassing traditional contractor intermediaries in Tokyo Bay corridor developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's carbon neutrality roadmap and annual power usage effectiveness disclosure mandates have erected a cost-of-compliance barrier that favors incumbents with established JIS certification pathways and refrigerant containment system expertise.
For Market Incumbents: Anchor defensive positioning through captive refrigerant chemistry pipelines that secure quota allocation priority under the Fluorocarbons Management Act. Deepen backward integration into dielectric fluid formulation to capture margin from liquid cooling adoption curves. Expand factory-integrated modular chiller capacity in Osaka industrial corridors to compress deployment timelines for hyperscale cloud contracts.
For New Entrants and Emerging Players: Direct-to-cloud-provider digital sales channels bypass entrenched contractor relationships and enable rapid credentialing for JIS refrigerant containment compliance. Target Fukuoka's emerging submarine cable landing cluster where earthquake risk diversification is creating greenfield demand for immersion cooling pilots. Lead with aftermarket leak detection and recovery service contracts to establish recurring revenue footholds before equipment refresh cycles accelerate.
For Investors and Strategic Acquirers: The window for entry favors domestic mid-cap specialists with METI-certified manufacturing footprints and established relationships with Greater Tokyo hyperscale operators. Long-term viability hinges on refrigerant chemistry capabilities that survive fluorocarbon phase-down trajectories. Monitor JIS standard revision announcements as the inflection signal for compliance investment urgency and equipment turnover acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Pipeline Investment | Captive low-GWP formulation capacity secures METI quota allocation priority for hyperscale contracts. |
| Modular Chiller Plant Factory Integration | Osaka-based manufacturing compresses deployment timelines to match cloud provider capacity scaling rhythms. |
| Direct Equipment Procurement Agreements | Bypassing contractor intermediaries in Tokyo Bay corridor developments captures margin from unbundled lease structures. |
| JIS Containment System Certification | Compliance-certified positioning creates aftermarket service revenue streams under tightening leakage detection mandates. |
| Liquid Cooling Architecture Partnership | Server-integrated thermal management alliances with Fujitsu and domestic GPU cluster operators secure premium tier placement. |
Research Methodology
Multi-period observation of METI power usage effectiveness disclosure trends, hyperscale capex deployment patterns, and refrigerant quota allocation trajectories anchored the trend analysis, supplemented by interviews with data center facility engineers, thermal system procurement officers at cloud service providers, colocation operations directors, precision air conditioning manufacturing plant managers, and JIS certification auditors. Secondary validation drew from METI building energy code filings, Fluorocarbons Management Act enforcement records, hyperscaler sustainability disclosures, and domestic industrial production statistics. Bottom-up equipment shipment tracking and top-down infrastructure investment flow analysis were triangulated to cross-verify market sizing.
Input-output matrix modeling connected rack density thresholds, cooling architecture adoption curves, and regional climate economics to project segment-level demand across the projection horizon. Segmentation dimensions included cooling type, technology modality, end-user archetype, and deployment model, with additional layering by prefectural regulatory cluster and free cooling zone eligibility. CAGRs were derived from fitted growth curves against historical equipment refresh cycle compression patterns and METI carbon intensity benchmark tightening schedules. Forecast inputs incorporated GPU cluster power density trajectories and low-GWP refrigerant cost transition curves.
The model holds under continued METI enforcement of annual PUE disclosure and Fluorocarbons Management Act quota phase-down schedules; deviation in refrigerant chemistry breakthrough timelines or hyperscaler workload placement shifts would shift equipment mix assumptions and regional demand distribution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
China Data Center Cooling Market