
 South Korea Data Center Power Market | 2026-2036
South Korea Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Power Market Insights
Hyperscale cloud operators is rotating toward dedicated server deployments, displacing traditional enterprise colocation contracts. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale campus developments in Pangyo. ABB Ltd competes on medium-voltage switchgear specialization for high-density halls. Vertiv Holdings Co sustains technology leadership in thermal management systems tailored to liquid-cooled server racks.
South Korea data center power encompasses the generation, conditioning, distribution, and backup infrastructure that delivers continuous electrical supply to IT equipment, typically operating at voltages from 480V downstream to 208V rack-level with redundancy tiers from N+1 to 2N configurations. Its primary purpose is eliminating downtime in facilities where power interruption causes immediate revenue loss and regulatory non-compliance. Liquid cooling is capturing margin pools as rack densities exceed 50kW in AI training clusters, while air cooling retains volume leadership in legacy enterprise halls. Colocation service type is fragmenting as hyperscalers demand bespoke power architectures distinct from multi-tenant standards.
KEPCO grid interconnection rules and NIS Act cybersecurity standards constrain facility design and operational certification timelines. MFDS data integrity requirements for pharmaceutical and biotech workloads impose additional power quality specifications on GMP-certified data halls. Stakeholders must weigh captive renewable generation against KEPCO tariff structures as carbon accounting tightens.
Market Dynamics
Hyperscale cloud operators are consolidating power procurement under single-vendor campus contracts, compressing margins for multi-tenant colocation providers while liquid cooling architectures reshape electrical distribution topologies across Gyeonggi Province facilities.
Growth Catalysts
- AI Training Cluster Expansion:Domestic hyperscalers are commissioning 100MW+ campuses in Pangyo and Yongin, requiring dedicated 2N substations and medium-voltage switchgear configurations that favor specialized power infrastructure vendors.
- MFDS GMP Certification:Pharmaceutical and biotech workloads in Songdo Biocluster now mandate uninterruptible power quality standards, creating premium tier demand for power conditioning equipment in GMP-certified data halls.
- NIS Act Cybersecurity Mandates:Critical infrastructure classification under the National Intelligence Service standards requires redundant power monitoring systems with air-gapped control networks, expanding addressable market for integrated power management platforms.
Market Restraints
- KEPCO Interconnection Queues:Grid connection approvals for facilities exceeding 50MW now extend 18-24 months, delaying revenue recognition for campus developments in Seoul metropolitan area.
- Copper and Rare Earth Price Volatility:Medium-voltage switchgear and transformer manufacturing faces input cost pressure from commodity markets, compressing margins for equipment suppliers serving domestic EPC contractors.
- Land Scarcity in Seoul Ring:Suitable parcels within 30 kilometers of Seoul command premiums exceeding industrial zoning benchmarks, forcing developers toward secondary locations with inferior grid redundancy.
Strategic Opportunities
- Busan-Ulsan Corridor:Underdeveloped coastal markets offer lower land costs and submarine cable connectivity to Japan, positioning the region for disaster-recovery and latency-sensitive workloads.
- Renewable Power Purchase Agreements:KEPCO green tariff structures and corporate renewable energy certificate mandates create arbitrage opportunities for facilities with captive solar or offshore wind offtake.
- Liquid-to-Chip Cooling Convergence:Integration of direct-to-processor cooling with power distribution units enables rack densities above 75kW, opening service contracts for thermal-electrical hybrid system specialists.
Industry Challenges
- High-Voltage Engineering Talent Scarcity:Domestic universities produce insufficient graduates with 154kV substation design expertise, forcing operators to recruit from heavy industry or overseas markets.
- Legacy Air-Cooled Retrofit Complexity:Existing enterprise halls in Seoul and Daegu require complete electrical reconfiguration to support liquid cooling manifolds, extending downtime windows and migration risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Power Market |
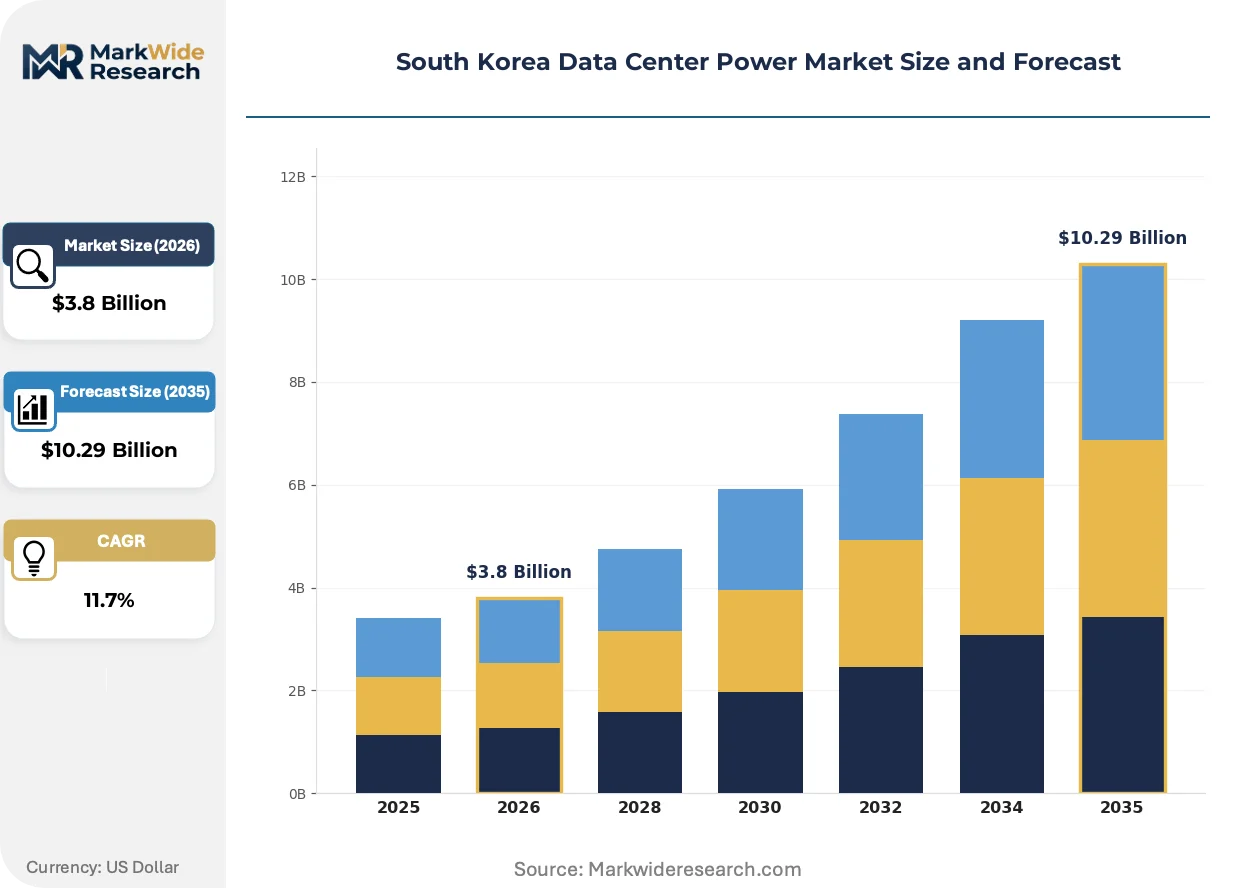
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable, Solar, Wind, Hydro Service Type: Colocation, Managed Services, Cloud Hosting, Dedicated Servers Cooling Technology: Air Cooling, Liquid Cooling, Free Cooling, Evaporative Cooling End User: Enterprises, SMEs, Government, Telecom |
| Companies Covered | Schneider Electric SE, ABB Ltd, Rittal GmbH & Co. KG, Fujitsu Limited, Legrand Group, Eaton Corp PLC, Vertiv Holdings Co, Delta Electronics, LG CNS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Power Market Trends and Innovations
Power infrastructure is converging with thermal management as rack densities breach conventional cooling thresholds, while regulatory frameworks harden facility certification requirements and procurement models consolidate under hyperscale direct contracting.
Busway power distribution with integrated tap-off boxes is displacing traditional raised-floor PDU configurations in new AI training facilities. Naver and Kakao Enterprise are specifying busway architectures for 50kW+ racks in Pangyo developments. This technology is displacing cable tray installations and enabling faster reconfiguration cycles as workload densities shift between training and inference phases.
NIS Act enforcement rules now mandate encrypted power monitoring telemetry and physical access logging for critical infrastructure classification. Facility operators must deploy air-gapped SCADA networks with redundant authentication layers. Colocation providers serving financial services and government workloads face the steepest compliance timelines, with certification audits extending commissioning schedules by four to six months.
Direct equipment procurement by hyperscale end-users is consolidating vendor relationships and disintermediating traditional systems integrators. Cloud operators now specify switchgear, UPS, and cooling as integrated packages rather than discrete purchases. This pattern concentrates procurement volume with manufacturers offering full-stack power and thermal portfolios, compressing addressable market for component specialists in Seoul-Incheon corridor developments.
South Korea Data Center Power Market Segmentation
Power infrastructure procurement in South Korea fragments across four distinct axes. Each segmentation layer reveals divergent vendor priorities, compliance burdens, and margin structures that reshape facility economics across Gyeonggi Province and emerging coastal corridors.
Power Source:
Domestic generation assets dominate procurement in Seoul metropolitan developments, while offshore wind and cross-border solar imports concentrate in Busan-Ulsan disaster recovery clusters seeking carbon accounting arbitrage.
- Renewable:KEPCO green tariff structures and corporate renewable energy certificate mandates drive offtake agreements. Pangyo hyperscale campuses now specify 30% minimum renewable content in power purchase contracts, with Songdo Biocluster pharmaceutical facilities following MFDS carbon disclosure requirements.
- Solar:Captive photovoltaic arrays on facility rooftops and adjacent land parcels supply auxiliary loads during peak tariff windows. Yongin and Anseong developments integrate battery storage to firm intermittent output for critical 2N substation feeds.
- Wind:Offshore wind offtake from western coastal projects serves Busan-Ulsan corridor facilities with submarine cable resilience against Seoul grid congestion.
- Hydro:Pumped hydro storage contracts from mountain province reservoirs provide frequency regulation services for AI training clusters with strict power quality specifications.
Renewable commands the established base. The steepest expansion runs through solar with integrated storage.
Service Type:
Hyperscale direct contracting compresses multi-tenant margins while liquid cooling requirements split procurement specifications between bespoke campus builds and legacy hall retrofits.
- Colocation:Multi-tenant facilities in Seoul and Daegu face margin compression as Naver and Kakao Enterprise migrate to dedicated deployments. Remaining colocation demand concentrates in MFDS GMP-certified halls serving pharmaceutical workloads with premium power quality tiers.
- Managed Services:Third-party operational contracts for power and cooling infrastructure expand among SMEs lacking 154kV substation expertise. Providers bundle NIS Act compliance monitoring with routine maintenance to extend contract durations.
- Cloud Hosting:Domestic hyperscalers consolidate procurement under single-vendor campus contracts, displacing traditional systems integrator relationships. Pangyo developments specify integrated switchgear, UPS, and cooling as unified packages.
- Dedicated Servers:Single-tenant power architectures with 2N redundancy and direct liquid cooling manifolds dominate new AI training clusters. Rack densities above 75kW require medium-voltage switchgear specialization from ABB and Schneider Electric.
Cloud hosting absorbs the dominant procurement volume. Dedicated servers capture the fastest margin expansion.
Cooling Technology:
Power distribution topologies diverge sharply between air-cooled legacy halls and liquid-cooled AI facilities, with electrical infrastructure vendors repositioning around thermal-electrical integration.
- Air Cooling:Raised-floor PDU configurations persist in enterprise colocation and government workloads with sub-15kW rack densities. Seoul and Daegu legacy facilities face complete electrical reconfiguration costs when retrofitting for higher densities.
- Liquid Cooling:Direct-to-processor cooling converges with power distribution units at rack densities exceeding 50kW. Busway architectures with integrated tap-off boxes displace cable tray installations in Pangyo AI training facilities specified by Naver.
- Free Cooling:Economizer systems leveraging Gangwon Province mountain temperatures reduce mechanical cooling loads for seasonal inference workloads. Power savings translate to deferred substation expansion in secondary locations.
- Evaporative Cooling:Adiabatic systems supplement liquid cooling in coastal Busan facilities with abundant water access and lower land costs than Seoul Ring.
Air cooling retains volume leadership. Liquid cooling gains share fastest through thermal-electrical hybrid contracts.
End User:
Regulatory compliance burdens stratify sharply between NIS Act critical infrastructure classification and standard commercial deployments, with government and telecom workloads facing the steepest certification timelines.
- Enterprises:Financial services and pharmaceutical firms in Songdo Biocluster drive premium tier demand for GMP-certified power quality. MFDS data integrity requirements impose uninterruptible specifications on UPS and switchgear configurations.
- SMEs:Cost-sensitive deployments in secondary cities favor managed service contracts over captive engineering teams. Daejeon and Gwangju facilities outsource NIS Act compliance monitoring to specialized operators.
- Government:National Intelligence Service critical infrastructure classification mandates air-gapped SCADA networks with encrypted power monitoring telemetry. Certification audits extend commissioning schedules by four to six months.
- Telecom:KT and SK Telecom edge computing nodes require redundant power architectures for latency-sensitive 5G workloads. KEPCO interconnection queues for sub-10MW facilities move faster than hyperscale campus approvals.
Enterprises anchor revenue concentration. Government workloads expand most quickly under NIS Act enforcement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale power infrastructure procurement concentrates in the Seoul Capital Area, where KEPCO grid capacity and fiber density attract cloud operators. Secondary corridors in Busan-Ulsan and Daegu-Gyeongbuk offer land cost arbitrage for disaster recovery workloads.
Seoul Capital Area
Pangyo and Yongin host 100MW+ AI training campuses from Naver and Kakao Enterprise. MFDS GMP certification requirements in Songdo Biocluster impose premium power quality tiers on pharmaceutical data halls. KEPCO interconnection queues for facilities exceeding 50MW now extend 18-24 months.
Busan-Ulsan
Submarine cable connectivity to Japan positions this corridor for latency-sensitive and disaster recovery workloads. Lower land costs than Seoul Ring attract developers seeking carbon accounting arbitrage through offshore wind offtake. NIS Act compliance timelines remain shorter than metropolitan critical infrastructure classifications.
Daegu-Gyeongbuk
Legacy enterprise colocation facilities face complete electrical reconfiguration costs when retrofitting for liquid cooling. Free cooling economizer systems leveraging mountain temperatures reduce mechanical loads for seasonal inference workloads. Government edge computing nodes for 5G infrastructure require redundant power architectures.
Daejeon-Sejong
Public sector data concentration drives NIS Act critical infrastructure certification demand. SMEs outsource power infrastructure management to specialized operators lacking 154kV substation expertise. KEPCO green tariff structures create procurement complexity for facilities balancing captive renewable generation against grid tariffs.
Gwangju-Honam
Underdeveloped coastal markets offer industrial zoning premiums below Seoul benchmarks. Secondary grid redundancy forces developers toward captive generation or battery storage configurations. Regional universities produce insufficient high-voltage engineering graduates, intensifying recruitment competition.
South Korea Data Center Power Market Competitive Landscape
Concentration sits with integrated power and cooling portfolio vendors anchoring large-scale campus developments. The vendor base stratifies across three tiers: full-stack infrastructure providers, medium-voltage electrical specialists, and thermal management technology vendors. M&A activity targets thermal-electrical integration capabilities, while direct hyperscale procurement consolidates vendor relationships and disintermediates traditional systems integrators.
Among global electrical infrastructure providers, Schneider Electric SE, ABB Ltd, and Vertiv Holdings Co occupy distinct positioning archetypes. Schneider Electric exemplifies the integrated campus development anchor through its combined power and cooling portfolio. ABB represents medium-voltage switchgear specialization for high-density hall configurations. Vertiv sits within thermal management leadership tailored to liquid-cooled server rack architectures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Rittal GmbH & Co. KG |
| Fujitsu Limited |
| Legrand Group |
| Eaton Corp PLC |
| Vertiv Holdings Co |
| Delta Electronics |
| LG CNS |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with KEPCO lock in both grid interconnection priority and tariff visibility for hyperscale developers, while commodity-linked equipment procurement exposes EPC contractors to copper and rare earth price swings that compress margins on fixed-bid switchgear installations.
Pricing Analysis
Volume-discount tiering separates dedicated campus deployments from multi-tenant colocation contracts, with hyperscalers commanding 15-25% unit cost advantages on medium-voltage switchgear through single-vendor consolidated procurement. Price differentiation rests on NIS Act certification grade and liquid cooling integration complexity, with GMP-certified pharmaceutical halls carrying premium tiers. Cost compression in standard colocation is intensifying because Naver and Kakao Enterprise are displacing legacy contracts with direct builds. SMEs in Daejeon and Gwangju exhibit highest price sensitivity, while government workloads under critical infrastructure classification show lowest elasticity due to compliance mandates.
Supply Chain Analysis
China and Japan anchor medium-voltage switchgear component fabrication, while South Korea domestic foundries produce specialized transformer cores for 154kV substation deployments. Raw material dependencies draw from Chilean copper cathodes, Chinese rare earth magnets, and Japanese electrical steel laminations. Single-source vulnerability concentrates in gas-insulated switchgear GIS modules where ABB and Schneider Electric control proprietary designs. Distribution runs through domestic EPC contractors with KEPCO-certified installation licenses, bypassing traditional systems integrator channels as hyperscalers specify direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where NIS Act compliance monitoring contracts and liquid cooling maintenance agreements are expanding faster than hardware sales, creating recurring revenue layers with superior margin profiles.
For Market Incumbents: Fortify thermal-electrical integration capabilities through captive engineering teams specializing in 75kW+ rack density configurations, defending against specialist HVAC contractors encroaching from adjacent building systems. Deepen backward integration into busway manufacturing to capture margin pools from Pangyo AI campus specifications. Prioritize MFDS GMP certification consulting as a service wrapper to differentiate premium tier offerings.
For New Entrants and Emerging Players: Lead with managed NIS Act compliance services targeting SME facilities in Daejeon-Sejong lacking 154kV substation expertise, where outsourcing demand runs ahead of supply. Penetrate the Busan-Ulsan corridor through offshore wind PPA advisory bundled with power quality equipment, exploiting carbon accounting arbitrage opportunities. Position around liquid-to-chip cooling convergence as thermal-electrical hybrid specialists serving retrofit demand in legacy Seoul enterprise halls.
For Investors and Strategic Acquirers: Thermal management technology vendors with direct-to-processor cooling IP represent the priority acquisition archetype, given rack density inflection above 50kW. Long-term viability centers on service contract duration and recurring revenue share rather than equipment shipment volumes. Watch KEPCO interconnection queue clearance rates as the signal for hyperscale campus commissioning velocity and downstream equipment procurement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal-Electrical System Integration | Captures margin pools from Naver's 75kW+ rack specifications in Pangyo developments. |
| NIS Act Compliance Service Layer | Extends contract duration through air-gapped SCADA monitoring for government workloads. |
| Offshore Wind PPA Structuring | Enables carbon accounting arbitrage for Busan-Ulsan disaster recovery facilities. |
| Busway Manufacturing Capacity | Displaces cable tray installations with faster reconfiguration cycles for AI training clusters. |
| 154kV Substation Engineering Talent | Addresses scarcity constraining commissioning timelines for 100MW+ hyperscale campuses. |
Research Methodology
Cross-validation between primary interviews with data center operators, EPC contractors, and KEPCO grid planning officers anchors the qualitative findings against secondary validation from equipment supplier SEC filings, hyperscaler capex disclosures, and MFDS regulatory bulletins. Bottom-up triangulation aggregates facility-level power infrastructure procurement patterns across Gyeonggi Province developments, while top-down reconciliation checks against KEPCO interconnection queue data and NIS Act certification registry trends.
Sensitivity analysis around KEPCO tariff structures and copper price volatility bounds the forecast range across the projection horizon. Segmentation dimensions model power source, service type, cooling technology, and end user vertical, with CAGRs derived from facility commissioning timelines and equipment replacement cycles. Industry-specific inputs include liquid cooling adoption curves from Naver and Kakao Enterprise specifications, plus MFDS GMP certification expansion rates in Songdo Biocluster.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale investment in Pangyo and Yongin, or accelerated KEPCO queue processing, would require recalibration. Forecasts reflect documented assumptions regarding NIS Act enforcement intensity and rare earth supply continuity. Recalibration cycles align with material shifts in hyperscaler procurement consolidation patterns and liquid cooling technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Market