
 South Korea Battery Management Systems Market | 2026-2036
South Korea Battery Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Battery Management Systems Market Analytics
ISO 26262 functional safety certification is reorganizing competitive access in the South Korea Battery Management Systems Market, disqualifying suppliers lacking ASIL-D validation for high-voltage platforms. LG Energy Solutions Ltd leverages captive cell production to anchor integrated BMS-cell offerings across Hyundai-Kia supply chains. SK On Co Ltd sustains R&D intensity in wireless BMS architectures that reduce wiring weight in next-generation packs. Panasonic Holdings Corporation competes through manufacturing scale in cylindrical-cell BMS modules optimized for Tesla-aligned Korean EV programs.
A battery management system governs cell-level voltage, temperature, and state-of-charge monitoring through analog front-end acquisition circuits and balancing algorithms to prevent thermal runaway and optimize cycle life. The architecture typically incorporates AEC-Q100-qualified integrated circuits, CAN or Ethernet communication buses, and electrochemical impedance spectroscopy for state-of-health estimation in automotive traction packs. Lithium-ion BMS units dominate value generation given their deployment in electric vehicle platforms where cell count and safety criticality drive per-unit pricing. Smart Systems technology is expanding fastest as AI-driven predictive diagnostics replace rule-based fault detection, shifting margin pools toward software-defined battery intelligence. Automotive end users absorb the majority of domestic output as Korean OEMs electrify model lineups and localize BMS sourcing.
MFDS, KATS, and the Ministry of Trade, Industry and Energy shape market access through battery safety certification mandates and K-Battery roadmap localization requirements that prioritize domestic BMS procurement. The Ministry of Environment enforces EV battery traceability rules that force BMS suppliers to embed lifecycle data logging for recycling compliance. Stakeholders must monitor how upcoming revisions to the Electrical Appliances and Consumer Products Safety Act expand BMS testing scope beyond automotive into energy storage installations.
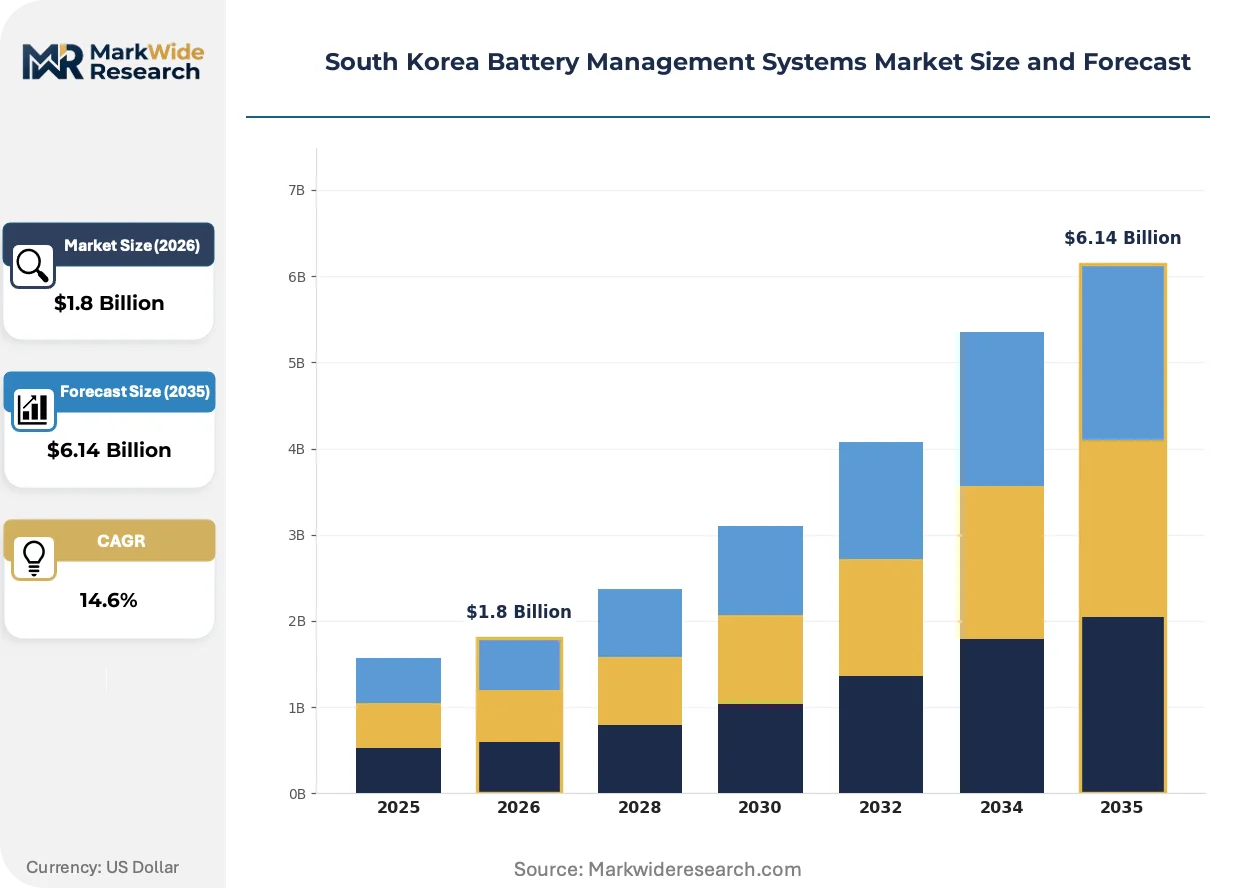
Market Dynamics
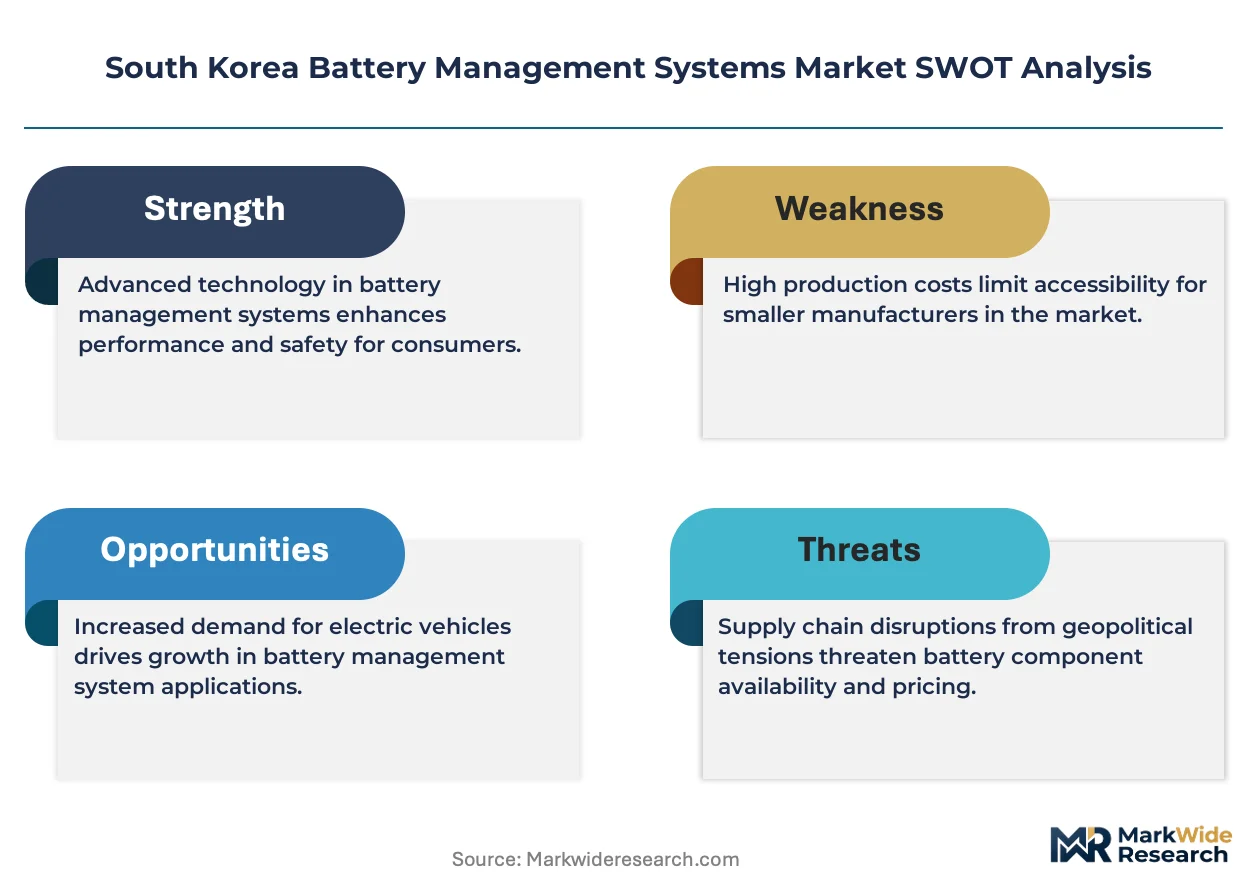
Cell-to-pack architecture adoption is compressing BMS component counts while elevating functional safety requirements under MFDS-aligned certification frameworks. This structural shift rewards suppliers with captive cell production and ASIL-D validation capabilities.
Growth Catalysts
- K-Battery Localization Mandates:Government procurement preferences under the Ministry of Trade, Industry and Energy roadmap compel domestic EV manufacturers to source BMS from Korean-certified suppliers, tightening supply chain control.
- Wireless BMS Architectures:Elimination of wiring harnesses reduces pack weight and assembly complexity, accelerating adoption in premium electric vehicle platforms targeting extended range specifications.
- Gyeonggi-Seoul-Incheon Manufacturing Corridor:Concentrated cell production investments by LG Energy Solutions and SK On create co-located BMS integration demand, reducing logistics costs and technical coordination friction.
Market Restraints
- ASIL-D Certification Barriers:ISO 26262 functional safety validation requires 18-24 month development cycles and specialized fault-injection testing infrastructure, excluding mid-tier electronics suppliers from high-voltage platform access.
- Lithium-Ion Cell Supply Concentration:Dependence on three domestic cell producers for BMS integration partnerships limits pricing leverage and creates single-source vulnerability during capacity allocation disputes.
- Analog Front-End Chip Import Dependency:AEC-Q100-qualified voltage monitoring ICs remain concentrated among US and European semiconductor suppliers, exposing Korean BMS manufacturers to foundry allocation constraints.
Strategic Opportunities
- Energy Storage System Expansion:Utility-scale battery installations under Korea's renewable energy portfolio standards create demand for grid-tied BMS with multi-string balancing and fire-suppression integration.
- Second-Life Battery Repurposing:Ministry of Environment traceability mandates position BMS data logging capabilities as critical infrastructure for residual value assessment in stationary storage redeployment.
- AI-Driven Predictive Diagnostics:Machine learning algorithms analyzing electrochemical impedance spectroscopy data enable warranty risk transfer to BMS vendors through performance-guarantee contracting models.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:ASIL-D certified firmware architects and hardware reliability engineers command premium compensation, constraining R&D scaling for emerging BMS entrants.
- Cell Chemistry Heterogeneity:Concurrent development of NCM, LFP, and solid-state cell formats forces BMS suppliers to maintain parallel algorithm development tracks, fragmenting software validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Battery Management Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lithium Polymer, Nickel-cadmium, Lead Acid End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Equipment Technology: Analog, Digital, Hybrid, Smart Systems Application: Electric Vehicles, Energy Storage Systems, Uninterruptible Power Supply, IoT Devices |
| Companies Covered | LG Energy Solutions Ltd, SK On Co Ltd, Panasonic Holdings Corporation, NXP Semiconductors NV, Renesas Electronics Corporation, Schneider Electric SE, Ficosa International SA, AVL List GmbH, Avnet Asia Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Battery Management Systems Market Evolving Landscape
Software-defined battery intelligence is displacing hardware-centric protection architectures, shifting margin capture toward predictive analytics and cloud-connected diagnostics. This transformation reconfigures supplier competitive positioning around data infrastructure rather than circuit design alone.
Electrochemical impedance spectroscopy integration is supplanting traditional voltage-temperature monitoring as the primary state-of-health estimation method. Tier-one automotive suppliers are embedding EIS-capable analog front-ends in next-generation pack designs. This capability compression enables real-time degradation modeling that extends warranty coverage terms and supports residual value financing for battery assets.
MFDS battery safety certification revisions are expanding testing scope from automotive traction packs to stationary energy storage systems. The Ministry of Food and Drug Safety alignment with UN ECE R100 standards forces BMS suppliers to redesign thermal runaway propagation prevention for grid-scale installations. Commercial and industrial storage integrators in the Seoul metropolitan area are accelerating procurement of certified systems ahead of enforcement deadlines.
Cell-to-pack procurement models are consolidating BMS specification authority with cell manufacturers rather than tier-one automotive electronics suppliers. Hyundai-Kia and affiliated EV platforms now source integrated cell-BMS modules directly from LG Energy Solutions and SK On, compressing traditional tiered supply chain margins. This concentration is most pronounced in the Gyeonggi province manufacturing cluster where co-located engineering teams enable rapid design iteration cycles.
South Korea Battery Management Systems Market Segmentation
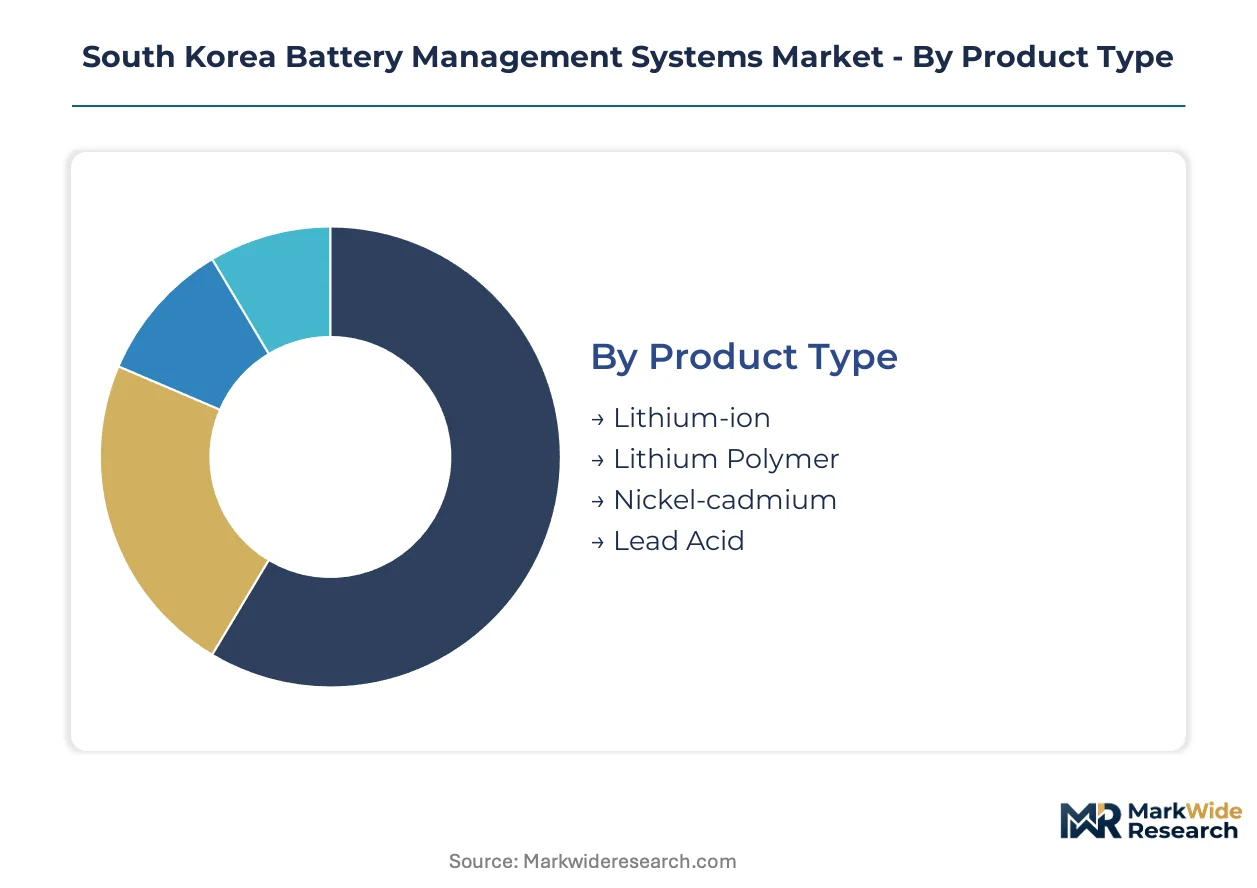
South Korea's BMS market segments reflect the country's concentrated battery manufacturing base and evolving regulatory landscape. Cell chemistry choices, end-use applications, and functional safety tiers create distinct margin pools that suppliers must navigate strategically.
Product Type:
Margin concentration tracks directly to cell chemistry complexity and thermal management requirements, with high-voltage automotive platforms commanding premium pricing over consumer-grade alternatives.
- Lithium-ion:NCM and LFP cylindrical and prismatic cell formats dominate Korean automotive traction packs. Hyundai-Kia EV platforms and domestic cell producers anchor demand in the Gyeonggi-Seoul-Incheon corridor, where ASIL-D certification requirements elevate per-unit value capture.
- Lithium Polymer:Pouch cell architectures enable higher packaging efficiency in premium electric vehicles. SK On and LG Energy Solutions leverage polymer flexibility for cell-to-pack integration, though thermal runaway propagation risks demand sophisticated balancing algorithms that compress hardware margins.
- Nickel-cadmium:Industrial backup power and legacy railway applications sustain niche procurement in Korean manufacturing zones.
- Lead Acid:Starter battery replacement and cost-sensitive uninterruptible power supplies retain volume in commercial vehicle segments.
The dominant share belongs to Lithium-ion, while Lithium Polymer is closing the gap fastest.
End User:
Application-driven procurement patterns split the market between safety-critical automotive specifications and cost-optimized industrial deployments.
- Automotive:Electric vehicle platforms absorb the majority of domestic BMS output. Hyundai Motor Group's electrification roadmap and K-Battery localization mandates concentrate demand among Korean-certified suppliers capable of MFDS-aligned functional safety validation.
- Renewable Energy:Utility-scale battery installations under Korea's renewable portfolio standards require grid-tied BMS with multi-string balancing and fire-suppression integration. The Ministry of Environment's traceability mandates embed lifecycle data logging as a procurement prerequisite.
- Consumer Electronics:Smartphone and laptop battery packs prioritize miniaturization and cost efficiency over diagnostic sophistication.
- Industrial Equipment:Forklift and material handling equipment demand ruggedized enclosures and extended temperature operating ranges.
Automotive commands the largest revenue pool, though Renewable Energy is expanding most quickly as grid-scale storage procurement accelerates.
Technology:
Architecture choices determine software versus hardware margin capture, with predictive analytics capabilities reshaping supplier competitive positioning.
- Smart Systems:AI-driven predictive diagnostics replace rule-based fault detection through electrochemical impedance spectroscopy integration. Cloud-connected battery intelligence shifts value toward software-defined platforms, attracting venture investment and partnership activity from domestic semiconductor firms.
- Digital:Microcontroller-based architectures with CAN and Ethernet communication buses serve mainstream automotive and industrial applications. AEC-Q100-qualified integrated circuits from US and European suppliers constrain Korean BMS manufacturers to assembly and firmware development.
- Hybrid:Mixed-signal designs balance analog precision with digital flexibility in mid-tier energy storage systems.
- Analog:Discrete voltage monitoring and passive balancing circuits retain cost-sensitive consumer electronics and legacy industrial niches.
Smart Systems is climbing the fastest as warranty risk transfer models favor predictive analytics vendors, while Digital retains the volume base.
Application:
Deployment context dictates functional safety tier, environmental sealing requirements, and communication protocol selection.
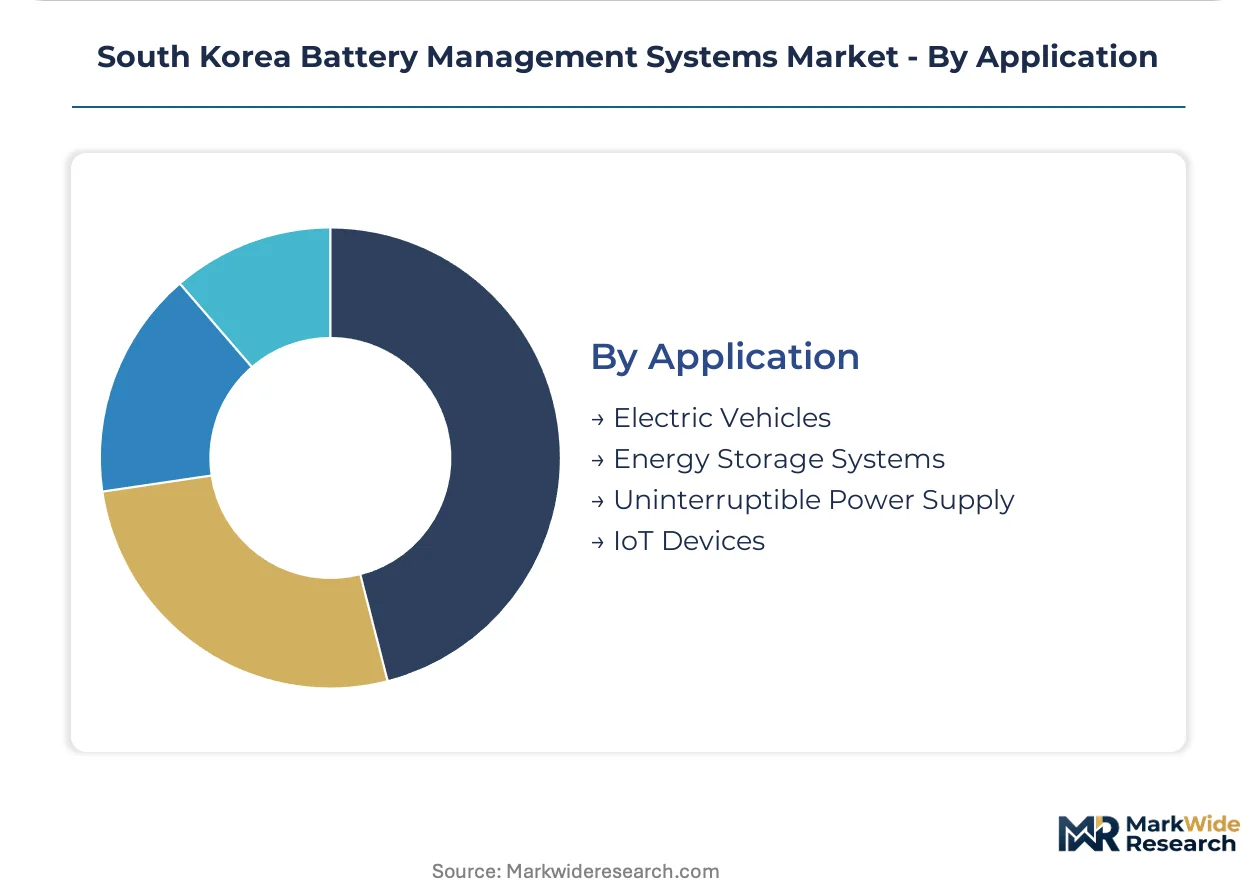
- Electric Vehicles:High-voltage traction packs require ISO 26262 ASIL-D validation and MFDS battery safety certification. Cell-to-pack integration trends consolidate BMS specification authority with LG Energy Solutions and SK On, compressing traditional tier-one automotive electronics margins.
- Energy Storage Systems:Stationary installations under Korea's renewable energy portfolio standards create demand for multi-string balancing and thermal runaway propagation prevention. MFDS certification expansion to grid-scale systems ahead of enforcement deadlines accelerates procurement of certified architectures.
- Uninterruptible Power Supply:Data center and critical infrastructure backup systems prioritize reliability and rapid switching response.
- IoT Devices:Low-power wireless sensor networks drive ultra-miniaturized BMS with Bluetooth Low Energy connectivity.
Electric Vehicles holds the dominant position, while Energy Storage Systems is gaining share fastest as utility procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
K-Battery roadmap localization mandates and MFDS battery safety certification requirements are reshaping procurement patterns across Korean manufacturing zones. The Ministry of Trade, Industry and Energy prioritizes domestic BMS sourcing for electric vehicle platforms.
Seoul Capital Area
Hyundai Motor Group headquarters and K-Battery strategy coordination centers drive specification authority for integrated cell-BMS modules. MFDS-aligned functional safety requirements under the Electrical Appliances and Consumer Products Safety Act elevate ASIL-D certification as a procurement gate. The Gyeonggi-Seoul-Incheon corridor concentrates LG Energy Solutions and SK On engineering teams for rapid design iteration.
Busan-Ulsan
Automotive component manufacturing heritage supports tier-one supplier ecosystems for BMS assembly and testing infrastructure. The Ministry of Environment enforces EV battery traceability rules that mandate lifecycle data logging capabilities in regional production facilities. Ulsan's industrial port infrastructure enables cell import logistics for BMS integration operations serving export-oriented EV programs.
Daegu-Gyeongbuk
Electronics manufacturing clusters supply AEC-Q100-qualified integrated circuits and passive components for BMS analog front-end assemblies. Korea Testing Laboratory (KTL) certification facilities in the region accelerate MFDS battery safety validation timelines for domestic suppliers. Daegu's semiconductor packaging expertise supports mixed-signal BMS architectures for mid-voltage energy storage applications.
Daejeon-Sejong
Government research institutes anchor electrochemical impedance spectroscopy algorithm development for predictive diagnostics. Korea Institute of Energy Research (KIER) programs under the Ministry of Science and ICT fund wireless BMS architecture R&D initiatives. Sejong's administrative city status concentrates regulatory coordination for K-Battery roadmap implementation across procurement agencies.
Gwangju-Honam
Renewable energy portfolio standards drive utility-scale battery installation demand for grid-tied BMS with multi-string balancing. Korea Electric Power Corporation (KEPCO) transmission infrastructure investments position the region for stationary storage deployment. Gwangju's smart grid demonstration zones test fire-suppression-integrated BMS architectures ahead of MFDS certification expansion to energy storage systems.
South Korea Battery Management Systems Market Competitive Landscape
Player mix skews toward captive cell producers with integrated BMS capabilities and automotive-tier electronics suppliers with functional safety validation infrastructure. Market structure concentrates around three domestic cell manufacturers exercising specification authority through cell-to-pack procurement models. Strategic archetypes include vertically integrated battery majors, semiconductor-centric BMS module suppliers, and specialist firmware developers. Dominant competitive moves encompass ASIL-D certification acceleration and wireless BMS architecture R&D partnerships.
Within the integrated battery major tier, LG Energy Solutions Ltd and SK On Co Ltd exemplify suppliers leveraging captive cell production to anchor BMS specification authority. Panasonic Holdings Corporation occupies a position representing foreign cell producers competing through manufacturing scale in cylindrical-cell formats. These three companies sit within the premium-tier competitive vector where MFDS-aligned functional safety requirements and K-Battery localization mandates determine market access.
| Leading Market Players |
|---|
| LG Energy Solutions Ltd |
| SK On Co Ltd |
| Panasonic Holdings Corporation |
| NXP Semiconductors NV |
| Renesas Electronics Corporation |
| Schneider Electric SE |
| Ficosa International SA |
| AVL List GmbH |
| Avnet Asia Pte Ltd |
| Others |
Value Network & Pricing Analysis
Wireless BMS module substitution for wired architectures is redrawing component sourcing maps and compressing assembly labor costs while elevating semiconductor content value. This transition simultaneously concentrates procurement leverage with Korean cell producers and fragments tier-one automotive electronics margins.
Pricing Analysis
Certification level under ISO 26262 ASIL-D creates the primary spread between premium integrated modules and commodity discrete controllers. Pricing stratifies across ASIL-D validated, ASIL-B compliant, and non-automotive grade tiers, with the automotive segment absorbing cost premiums for MFDS-aligned safety validation. Cost compression in standard-grade digital BMS is intensifying because analog front-end chip import dependency exposes Korean assemblers to foundry allocation constraints. Renewable energy integrators exhibit highest price sensitivity due to project finance pressures, while captive cell producers maintain lowest sensitivity through backward integration into semiconductor sourcing.
Supply Chain Analysis
Strategic stockpiling of AEC-Q100-qualified voltage monitoring ICs dominates inventory strategy over just-in-time preferences given foundry allocation volatility. Korean BMS manufacturing draws from Taiwan for advanced semiconductor foundry services, the United States for analog front-end IC design houses, and domestic facilities for final assembly and firmware integration. Single-source vulnerability in 16-channel battery monitor supply creates structural risk during automotive platform ramp cycles. Distribution runs through direct cell producer procurement channels rather than traditional tier-one automotive electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's BMS market sits in early-cycle expansion as K-Battery localization mandates force domestic procurement preferences across Hyundai-Kia electrification roadmaps. Utility-scale energy storage deployment under renewable portfolio standards compounds addressable demand beyond automotive traction packs.
For Market Incumbents: Consolidate specification authority through accelerated ASIL-D certification completion before MFDS enforcement deadlines tighten. Deepen captive semiconductor sourcing relationships to offset analog front-end import dependency. Lock in multi-year cell-to-pack partnership terms with LG Energy Solutions and SK On engineering teams to defend against emerging firmware specialists. For New Entrants and Emerging Players: Differentiate on AI-driven predictive diagnostics capabilities that enable warranty risk transfer contracting models. Target utility-scale energy storage BMS procurement as the most penetrable segment given less concentrated incumbent positioning versus automotive. Pursue Korea Institute of Energy Research partnership channels for wireless architecture validation credentials. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive electronics suppliers lacking ASIL-D validation infrastructure. Five-to-ten year viability hinges on software-defined battery intelligence platform development rather than hardware assembly scale. Watch MFDS certification expansion timing to stationary storage as the inflection signal for grid-tied BMS valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | MFDS-aligned validation unlocks high-voltage platform access across Hyundai-Kia supply chains. |
| Wireless BMS Architecture Development | Korea Institute of Energy Research funding positions Korean suppliers for next-generation pack weight reduction. |
| Energy Storage System Certification Expansion | MFDS testing scope broadening to grid-scale installations creates first-mover advantage in utility procurement. |
| Predictive Diagnostics Platform Launch | Electrochemical impedance spectroscopy integration enables warranty risk transfer and recurring revenue models. |
| Semiconductor Sourcing Partnership | AEC-Q100-qualified IC supply agreements mitigate foundry allocation exposure in analog front-end procurement. |
Research Methodology
Cross-validation between primary interviews with BMS platform engineers, tier-one automotive procurement directors, and MFDS regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from Korea Testing Laboratory certification records, Ministry of Trade Industry and Energy K-Battery roadmap publications, and vehicle production databases. Bottom-up cell-to-pack integration demand modeling triangulates against top-down electric vehicle electrification spend projections.
Sensitivity analysis across cell chemistry adoption scenarios, ASIL-D certification timeline variations, and wireless architecture penetration rates shapes the analytical framework. Segmentation dimensions span product type, end user, technology architecture, and application context throughout the forecast period. CAGRs derive from installed base growth, content-per-vehicle trajectories, and utility-scale storage procurement schedules under renewable portfolio standards.
Material uncertainties — lithium-ion cell supply concentration disputes, analog front-end semiconductor allocation shocks, and MFDS certification requirement revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding K-Battery localization enforcement continuity and Hyundai-Kia platform electrification cadence. Revision becomes warranted when wireless BMS architecture adoption crosses threshold penetration in premium electric vehicle segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
North America Micro Inverter Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Power Electronics Market
Power Systems
Vehicle Inverter Market
Power Systems
Shunt Capacitor Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
String Inverter Market
Power Systems
Global Inverter Market
Power Systems
Battery Balancer Market