
 Vehicle Inverter Market | 2026-2036
Vehicle Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Inverter Market Analysis
Fleet operators are redrawing procurement priorities toward high-voltage inverters as electrified commercial transport scales. Robert Bosch GmbH leverages its power electronics foundry network to sustain cost leadership across European OEM channels. Denso Corporation anchors Japanese supply chains through captive semiconductor partnerships and thermal management integration. Mitsubishi Electric Corporation differentiates via SiC module expertise that commands premium positioning in 800-volt architectures.
A vehicle inverter converts direct current from a battery into alternating current for electric traction motors, typically operating at switching frequencies between 2 kHz and 20 kHz with efficiency targets exceeding 97 percent. The device governs torque response, regenerative braking recovery, and thermal stability across variable load profiles. Pure sine wave inverters dominate passenger electric vehicle applications where motor harmonic distortion must stay below 5 percent, while modified sine wave units retain cost advantages in auxiliary power conversion for commercial fleets. PWM technology leads volume production due to mature gate driver ecosystems, though isolated topologies gain traction in premium segments demanding reinforced insulation for 800-volt platforms.
China's NMPA and MIIT enforce GB standards for electromagnetic compatibility and functional safety that gate market access for imported inverter assemblies. Europe's ECHA REACH restrictions on hexavalent chromium plating reshape cooling channel metallurgy, while CE marking mandates under the EU AI Act extend to predictive thermal management algorithms. Stakeholders must monitor how semiconductor export controls and carbon border adjustments reconfigure sourcing economics for power module substrates.
Market Dynamics
Silicon carbide semiconductor transitions are compressing inverter footprints while forcing wholesale redesigns of thermal management architectures across passenger and commercial vehicle platforms.
Growth Catalysts
- Electrification mandates:China's MIIT enforces dual carbon goals that tighten NEV production quotas, compelling domestic OEMs to expand high-voltage inverter procurement.
- 800-volt platform proliferation:Commercial fleet operators across European logistics corridors are retrofitting charging infrastructure to accommodate faster-charging architectures.
- SiC module maturation:Power semiconductor foundries in Japan and Germany are scaling 6-inch and 8-inch wafer production, reducing substrate costs for traction inverter applications.
Market Restraints
- Substrate supply concentration:High-purity silicon carbide boule production concentrates among three Japanese and US suppliers, creating single-source vulnerability for power module fabricators.
- REACH metallurgy compliance:ECHA restrictions on hexavalent chromium plating force cooling channel redesigns, extending validation cycles for European-bound inverter assemblies.
- Copper busbar cost volatility:Electrified commercial vehicle inverters require 40-60 kg of high-conductivity copper per unit, exposing margins to LME price swings.
Strategic Opportunities
- Second-life inverter refurbishment:Battery-electric bus fleets in Shenzhen and Guangzhou are creating aftermarket demand for remanufactured power electronics with certified thermal performance.
- AI Act compliance services:CE marking mandates under the EU AI Act extend to predictive thermal management algorithms, opening consultative revenue streams for firmware developers.
- V2H integration:Bidirectional charging hardware in Japanese residential markets requires grid-synchronization inverters with islanding capabilities, a specification gap most mass-market suppliers have not addressed.
Industry Challenges
- Power electronics talent scarcity:Gate driver design and electromagnetic compatibility testing require specialized engineers concentrated in Germany, Japan, and Taiwan, constraining R&D scaling.
- Functional safety certification timelines:ISO 26262 ASIL-D validation for 800-volt architectures demands 18-24 months of fault-injection testing, delaying platform launches.
- Legacy 400-volt integration friction:Mixed-voltage fleets require dual-spec inverter inventories, complicating procurement and service training for commercial operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Inverter Market |
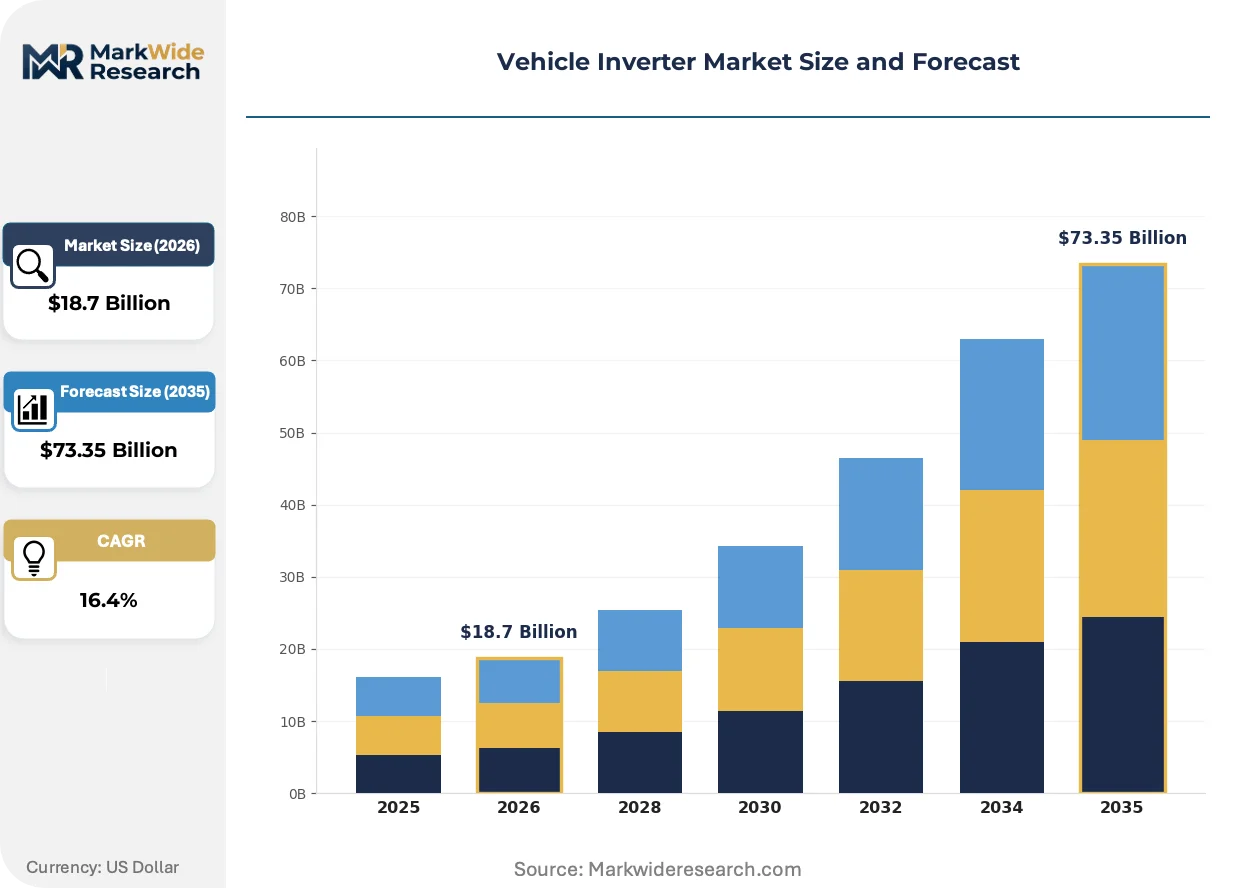
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Sine Wave, Pure Sine Wave, Grid-tie, Off-grid Technology: Switching, Linear, PWM, Isolated Application: Electric Vehicles, Hybrid Vehicles, Commercial Fleets, Power Tools Customer Type: OEMs, Aftermarket Providers, Component Suppliers, Retail Consumers |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Mitsubishi Electric Corporation, Toyota Industries Corporation, Valeo SA, Continental AG, BorgWarner Inc., Vitesco Technologies, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Inverter Market Emerging Trajectories
Thermal management architectures, semiconductor material transitions, and procurement model compression are restructuring how power electronics reach vehicle platforms.
Silicon carbide MOSFETs are displacing silicon IGBTs in 800-volt traction inverters by enabling switching frequencies above 50 kHz with 40 percent lower switching losses. European premium OEMs have adopted SiC exclusively for performance variants since 2023. This displacement is compressing inverter volume by 30 percent while doubling power density targets.
ECHA REACH restrictions on hexavalent chromium plating are forcing cooling channel metallurgy shifts toward nickel-boron or electroless nickel alternatives. German and Czech inverter suppliers report 6-9 month validation extensions for corrosion-resistant coatings. The commercial vehicle segment faces the steepest compliance burden due to longer duty cycles and harsher thermal loading.
Fleet procurement departments are consolidating inverter specifications across mixed OEM portfolios to reduce spare parts complexity. Large European logistics operators now mandate unified 800-volt architectures and common CAN communication protocols regardless of vehicle brand. This standardization push concentrates in Germany's Rhine-Ruhr freight corridor and the Netherlands' Randstad distribution hub.
Vehicle Inverter Market Segmentation
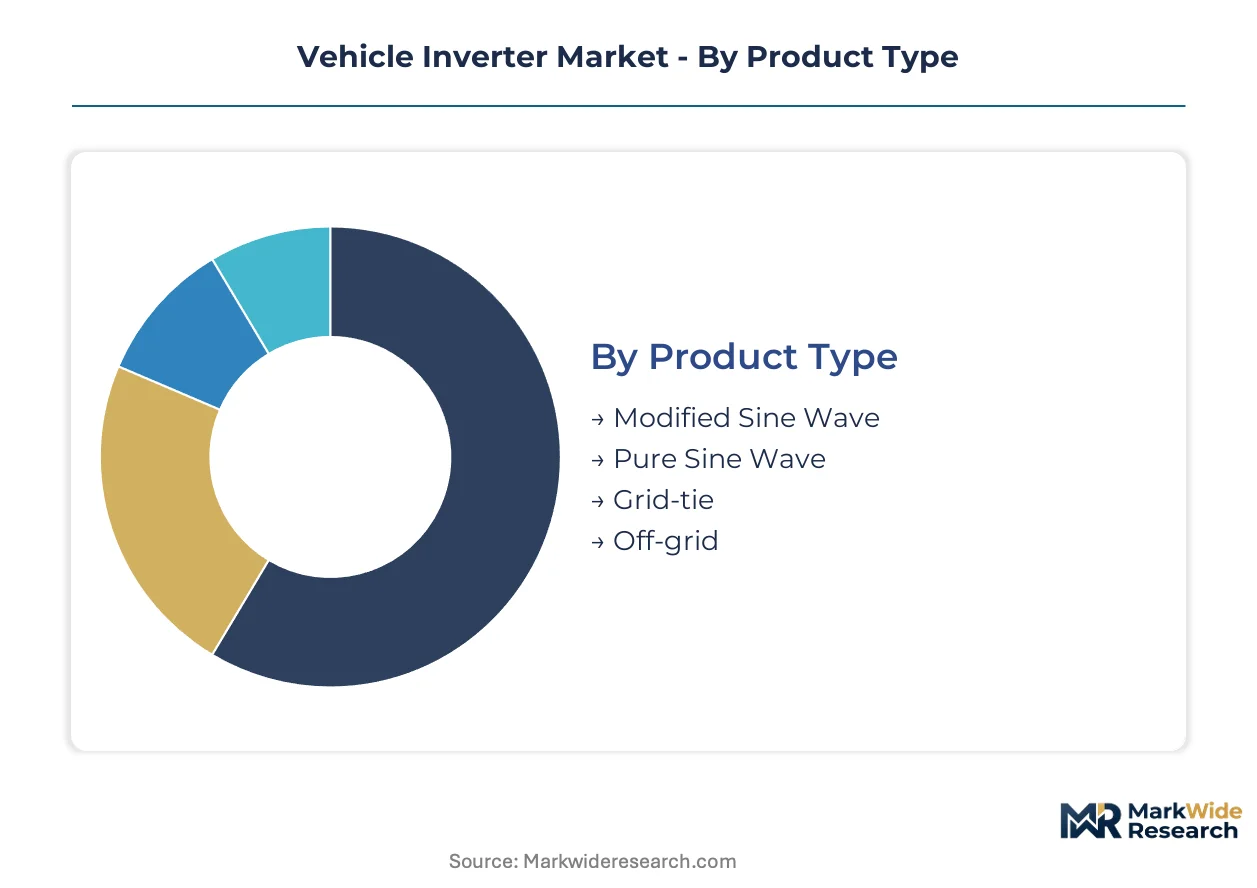
Vehicle inverter procurement flows through distinct technical and commercial channels, each commanding different margin structures and validation requirements. Understanding how product specifications, technology choices, and customer relationships intersect reveals where pricing power concentrates and where commoditization pressures mount.
Product Type:
Pure sine wave and modified sine wave units follow divergent channel strategies, with premium passenger OEMs demanding harmonic precision while commercial fleets prioritize cost efficiency in auxiliary power conversion.
- Pure Sine Wave:Delivers total harmonic distortion below 5 percent through sophisticated filtering architectures, essential for sensitive traction motor control. Passenger EV manufacturers in China's NEV manufacturing belt specify these exclusively for drivetrain applications, with procurement volumes scaling alongside 800-volt platform rollouts.
- Modified Sine Wave:Generates stepped approximations of AC waveforms using simpler switching topologies, sacrificing harmonic purity for cost reduction. Commercial fleet operators across European logistics corridors specify these for cabin HVAC and auxiliary loads, where motor sensitivity is lower and procurement budgets are tighter.
- Grid-tie:Synchronizes output phase and frequency with utility infrastructure, enabling bidirectional power flow for V2H applications. Japanese residential markets under METI guidelines show concentrated demand for these capabilities.
- Off-grid:Operates autonomously without utility reference, serving remote charging installations and mobile service vehicles. Mining and construction equipment OEMs in Australia and Canada specify these for site-independent operation.
By volume, modified sine wave leads in commercial fleet procurement. By growth pace, pure sine wave is climbing the fastest as 800-volt passenger platforms expand.
Technology:
Technology selection maps directly to thermal management investment and semiconductor bill-of-materials, with PWM architectures dominating high-volume production while isolated topologies capture premium positioning.
- PWM:Pulse-width modulation achieves voltage conversion through high-frequency switching with mature gate driver ecosystems and established EMI mitigation techniques. Mass-market passenger EV platforms specify PWM for traction inverters, with foundry capacity concentrated in Taiwan and Germany.
- Isolated:Galvanic separation between input and output stages through transformers or optocouplers enables reinforced insulation for 800-volt architectures. Premium European OEMs mandate these for high-voltage platforms, accepting 15-20 percent cost premiums for safety margin expansion.
- Switching:Encompasses resonant and soft-switching variants that reduce switching losses through zero-voltage or zero-current transitions. Niche applications in high-performance EVs leverage these for efficiency gains above 98 percent.
- Linear:Provides ripple-free output through continuous semiconductor operation, sacrificing efficiency for electromagnetic cleanliness. Audio and precision instrumentation subsystems in luxury vehicles retain limited demand for these.
PWM technology captures the largest production volumes. Isolated topologies show the steepest expansion trajectory as voltage architectures migrate toward 800V.
Application:
Application segmentation reveals divergent duty cycle requirements, with passenger EVs optimizing for intermittent peak loads while commercial fleets prioritize continuous thermal stability.
- Electric Vehicles:Traction inverters for battery-electric platforms must sustain 97+ percent efficiency across variable torque demands while managing regenerative braking energy recovery. China's domestic OEMs anchor global procurement volumes, with MIIT production quotas forcing rapid capacity expansion.
- Commercial Fleets:Delivery vans, buses, and heavy trucks require inverters rated for continuous operation at elevated thermal loads, with service intervals measured in years rather than months. European logistics operators under EU Green Deal mandates are retrofitting depot infrastructure to support electrified fleet charging.
- Hybrid Vehicles:Power-split architectures demand rapid switching between electric and combustion modes, stressing inverter transient response capabilities. Japanese OEMs retain technology leadership in these integrated systems.
- Power Tools:Cordless equipment and mobile workshop applications require compact, lightweight inverters with battery interface flexibility. Construction and agricultural equipment manufacturers specify these for field service vehicles.
Electric vehicles dominate absolute unit demand. Commercial fleets are gaining share fastest as electrification mandates tighten across logistics corridors.
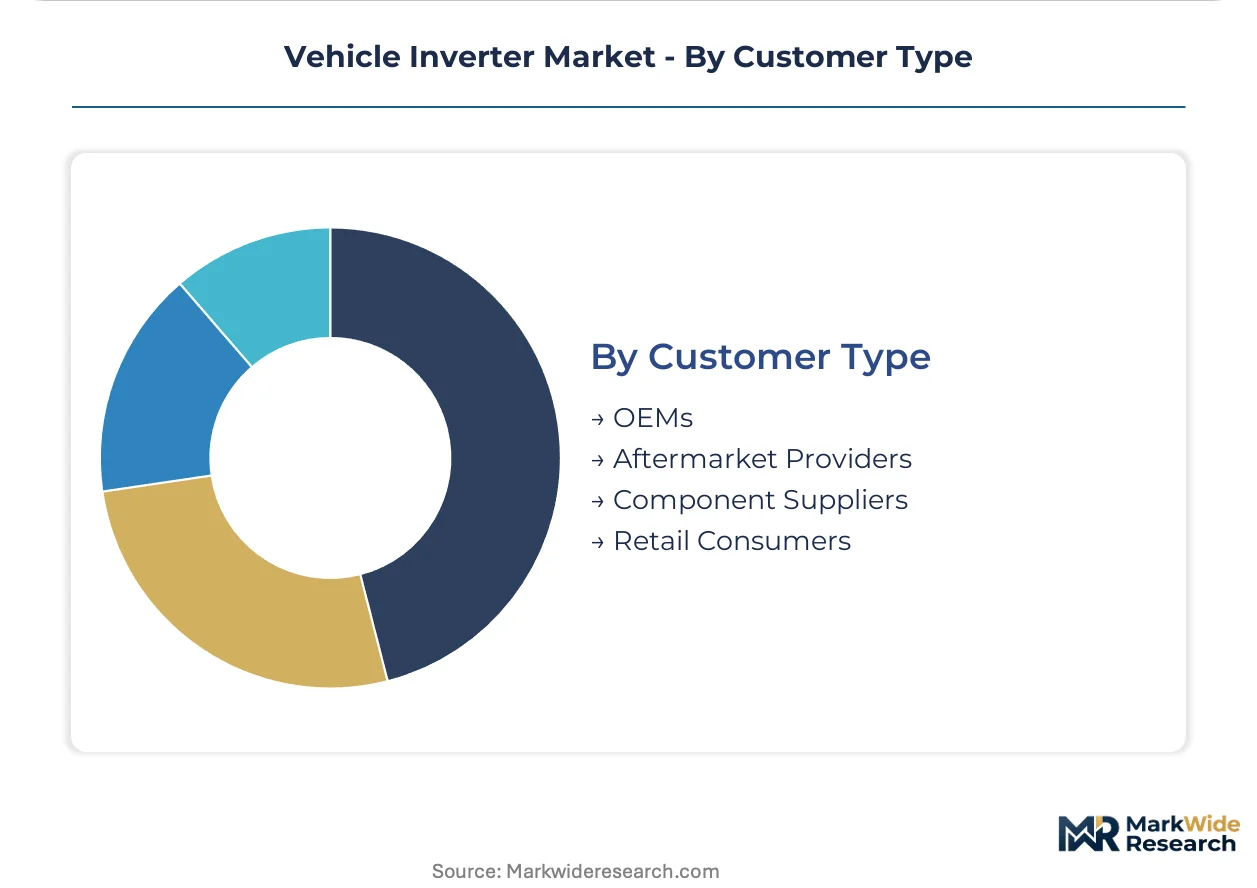
Customer Type:
Customer relationships determine specification control, with OEMs dictating thermal and electromagnetic requirements while aftermarket providers compete on refurbishment speed and inventory breadth.
- OEMs:Original equipment manufacturers specify inverter architectures during platform development, locking in semiconductor and thermal management suppliers for production runs. Chinese NEV producers exercise particular procurement leverage given their manufacturing scale.
- Aftermarket Providers:Remanufacturing specialists and independent service networks address replacement demand from out-of-warranty fleets, with Shenzhen and Guangzhou battery-electric bus operators creating certified refurbishment demand.
- Component Suppliers:Tier-2 and Tier-3 fabricators supply power modules, gate drivers, and thermal substrates to integrated inverter manufacturers, with substrate supply concentrating among Japanese and US SiC boule producers.
- Retail Consumers:Individual purchasers acquire inverters for recreational vehicles, marine applications, and residential energy storage, representing fragmented demand with limited pricing power.
OEMs command the largest contract values. Aftermarket providers are expanding most quickly as first-generation EV fleets age out of warranty coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon carbide boule fabrication concentrates among Japanese and US suppliers, forcing inverter manufacturers to secure long-term substrate contracts. China's NEV manufacturing belt dominates assembly capacity while European logistics corridors drive fleet electrification procurement. Regulatory fragmentation across MIIT quotas, ECHA REACH restrictions, and EPA emissions standards shapes regional sourcing strategies.
China
Domestic OEMs anchor global inverter procurement volumes as MIIT enforces dual carbon goals tightening NEV production quotas. GB standards for electromagnetic compatibility and functional safety gate market access for imported assemblies. The Yangtze River Delta manufacturing cluster around Shanghai hosts captive power electronics foundries serving BYD and CATL supply chains.
Germany
Commercial fleet operators across the Rhine-Ruhr freight corridor mandate unified 800-volt architectures regardless of vehicle brand. ECHA REACH restrictions on hexavalent chromium plating force cooling channel metallurgy redesigns extending validation cycles. Bavaria's automotive electronics corridor houses Robert Bosch GmbH power electronics foundry network sustaining cost leadership across European OEM channels.
United States
EPA emissions standards and California Air Resources Board mandates accelerate electrified commercial transport procurement. Silicon carbide substrate supply vulnerability concentrates among three Japanese and US boule producers. The Detroit automotive cluster sees Tier-1 suppliers consolidating inverter specifications across mixed OEM portfolios to reduce spare parts complexity.
Japan
METI guidelines drive concentrated demand for grid-synchronization inverters with bidirectional V2H capabilities in residential markets. Power semiconductor foundries scale 6-inch and 8-inch SiC wafer production reducing substrate costs for traction applications. The Nagoya-Tokyo corridor anchors Denso Corporation captive semiconductor partnerships integrating thermal management systems.
South Korea
Hyundai-Kia Group platform rollouts expand 800-volt inverter procurement as MFDS-equivalent automotive safety standards tighten validation requirements. Battery-electric bus fleets in Seoul and Busan create aftermarket demand for remanufactured power electronics. The Seoul Capital Area concentrates gate driver design and electromagnetic compatibility testing engineering talent.
Vehicle Inverter Market Vendor Landscape
Concentration sits with diversified automotive electronics conglomerates controlling captive semiconductor supply and thermal management integration. Tier-1 suppliers fragment across technology specialization vectors with SiC module expertise commanding premium positioning in 800-volt architectures. Two strategic archetypes dominate: integrated power electronics foundry operators and thermal-management-integrated system suppliers. Competitive moves center on backward integration into substrate sourcing and strategic partnerships securing wafer allocation.
Among diversified automotive electronics conglomerates, Robert Bosch GmbH exemplifies the integrated foundry archetype leveraging power electronics manufacturing scale across European OEM channels. Denso Corporation occupies the thermal-integration specialist position through captive semiconductor partnerships. Mitsubishi Electric Corporation represents the SiC module premium-tier vector commanding positioning in high-voltage architectures. These three anchors illustrate how technology specialization and supply chain control separate competitive tiers.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Toyota Industries Corporation |
| Valeo SA |
| Continental AG |
| BorgWarner Inc. |
| Vitesco Technologies |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for high-purity silicon carbide boules lock in substrate access and price visibility for inverter manufacturers serving China's NEV manufacturing belt and European logistics corridors. These arrangements insulate power module fabricators from spot market volatility while committing buyers to volume minimums that strain working capital.
Pricing Analysis
ECHA REACH restrictions dictate the pricing tier structure across European-bound inverter assemblies. Three-tier pricing structure across premium, standard, and economy levels separates SiC-enabled 800-volt architectures from silicon IGBT platforms and modified sine wave auxiliary units. Cost compression in standard-tier PWM inverters is intensifying because foundry capacity expansion in Taiwan and Germany outpaces near-term demand absorption. Commercial fleet operators exhibit the highest price sensitivity, while premium passenger OEMs prioritize thermal efficiency and ASIL-D certification over unit cost.
Supply Chain Analysis
High-purity silicon carbide boule production concentrates among Japanese and US suppliers, creating single-source vulnerability for power module fabricators in Germany and South Korea. Inverter manufacturing draws from copper busbar feedstock, gate driver ICs, and thermal substrate materials. Tariff exposure on semiconductor substrates threatens margin stability for European and North American assemblers. Distribution runs through captive OEM supply chains and Tier-1 system integrators, with aftermarket channels gaining share as first-generation battery-electric bus fleets age.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle inverter demand sits in early-cycle expansion as 800-volt platform proliferation accelerates across passenger and commercial segments. Electrification mandates in China and Europe are compressing adoption timelines beyond historical replacement rates.
For Market Incumbents: Shield foundry utilization rates through multi-year capacity reservations with Japanese SiC boule suppliers. Deepen backward integration into thermal management system production to defend against thermal-integration specialists capturing margin from power electronics commoditization. Lock in OEM platform engineering relationships before ISO 26262 ASIL-D validation timelines harden supplier selection.
For New Entrants and Emerging Players: Anchor in second-life inverter refurbishment for Shenzhen and Guangzhou battery-electric bus operators, where certified remanufacturing demand outpaces established service capacity. Target V2H grid-synchronization specifications under Japan METI guidelines, a capability gap most mass-market suppliers have not addressed. Pursue direct fleet procurement relationships bypassing consolidated Tier-1 channels.
For Investors and Strategic Acquirers: Capital is best deployed toward thermal-management-integrated system suppliers with captive semiconductor partnerships, as these archetypes command durable pricing power through the technology transition. Monitor silicon carbide substrate allocation announcements from Japanese foundries as the inflection signal for supply constraint easing versus persistence.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Substrate Supply Agreement | Long-term offtake contracts with Japanese boule producers secure allocation ahead of capacity constraints. |
| Thermal Management Integration | In-house production of cooling systems captures margin from power module commoditization pressures. |
| Second-Life Refurbishment Certification | Certified remanufacturing capabilities address aftermarket demand from aging Chinese battery-electric bus fleets. |
| V2H Grid-Synchronization Development | Bidirectional inverter capabilities under Japan METI guidelines unlock residential energy storage adjacencies. |
| 800-Volt Platform Standardization | Unified architectures across mixed OEM portfolios reduce spare parts complexity for European logistics operators. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and power semiconductor foundry production data anchors the qualitative findings. Primary interviews with Tier-1 supplier procurement officers, OEM traction inverter engineers, aftermarket service network managers, and thermal substrate specialists were synthesized with secondary validation from vehicle production databases, customs and trade flow records, SEC filings from automotive electronics suppliers, and regulatory filings with China's MIIT and Japan's METI. Bottom-up unit demand estimates and top-down market sizing were triangulated to constrain projection variance.
Sensitivity analysis around SiC adoption pace and copper price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, voltage platform, semiconductor technology, vehicle class, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to historical penetration patterns and policy mandate enforcement trajectories. Forecast inputs incorporate MIIT NEV production quota trajectories and ECHA REACH compliance timeline assumptions.
Material uncertainties — semiconductor export control expansions, carbon border adjustment implementations, and functional safety certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology transition pacing and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as substrate supply concentration and fleet electrification mandate stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Gan Power Device Market
Power Systems
Battery Balancer Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Solid State Transformer Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Synchrophasors Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Laptop Battery Market
Power Systems
Automotive Power Electronics Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Global Excitation Systems Market
Power Systems
Thermoelectric Generator (TEG) Market