
 Battery Monitor Market | 2026-2036
Battery Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Monitor Market Analytics
The capital-intensity divergence between custom ASIC designers and modular software-defined platforms is unwinding competitive hierarchies in battery management electronics. Texas Instruments leverages its foundry partnerships and analog IP portfolio to sustain pricing power in high-voltage automotive segments. Analog Devices competes through precision sigma-delta architectures that dominate current-sensing accuracy benchmarks for grid-scale storage installations.
A battery monitor is an electronic subsystem that measures electrochemical cell parameters including terminal voltage, charge/discharge current, and internal temperature to prevent operational failure and extend cycle life. These devices employ precision analog front-ends, coulomb-counting algorithms, and often isolated communication interfaces to relay state-of-charge and state-of-health data to host controllers. Lithium-ion monitoring leads product type revenue due to the chemistry's dominance in automotive and stationary storage applications, while integrated solutions represent the fastest-growing technology segment as OEMs consolidate voltage, current, and thermal sensing into single-chip architectures. Onboard systems anchor installation demand because embedded monitors eliminate wiring complexity and reduce latency in safety-critical shutdown sequences.
The EU Battery Regulation and ECHA REACH compliance frameworks now require portable and industrial battery producers to disclose carbon footprint data and recyclability metrics, directly elevating monitor specifications for lifecycle traceability. In the United States, NHTSA and FAA guidelines for lithium-ion transportation safety mandate continuous thermal monitoring in commercial vehicle and aviation battery packs, tightening certification thresholds for monitor suppliers. Stakeholders must track how emerging solid-state chemistries alter voltage measurement tolerances and whether regional recycling mandates expand monitor functionality to include material provenance logging.
Market Dynamics
The transition from discrete multi-chip battery management architectures toward integrated single-die solutions is compressing bill-of-materials counts while elevating functional safety requirements for automotive qualification.
Growth Catalysts
- EU Battery Regulation:Mandated state-of-health disclosure for industrial batteries sold across member states is forcing OEMs to install continuous monitoring infrastructure, expanding addressable hardware demand.
- Electric vehicle fleet operators:Real-time cell surveillance systems are becoming standard equipment to prevent thermal runaway incidents and satisfy insurer liability requirements.
- Second-life storage:Battery recyclers and stationary storage developers in Germany require electrochemical performance verification across repurposed automotive packs, creating parallel demand streams.
Market Restraints
- Silicon foundry concentration:Advanced BCD (Bipolar-CMOS-DMOS) process capacity for high-voltage analog front-ends concentrates among Taiwan-based pure-play foundries, exposing supply continuity risk.
- Palladium and nickel input volatility:Precision shunt resistor and contact material costs fluctuate with battery metal commodity cycles, compressing gross margins for monitor module suppliers.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for automotive monitors extends development cycles to 24-36 months, freezing smaller competitors from premium segments.
Strategic Opportunities
- India stationary storage:CEA mandates and state-level renewable purchase obligations are accelerating grid-scale battery deployment where integrated monitor-communication modules remain underpenetrated.
- Solid-state chemistry convergence:Emerging sulfide and oxide electrolyte formulations require recalibrated voltage measurement tolerances, creating replacement demand for next-generation sensing architectures.
- Material provenance logging:EU Battery Regulation recyclability metrics and carbon footprint disclosure rules are expanding monitor functionality requirements toward blockchain-traceable lifecycle documentation.
Industry Challenges
- Signal integrity engineering talent:Isolated delta-sigma modulator design expertise for high-voltage battery stacks remains concentrated among analog semiconductor veterans, constraining product development velocity.
- Legacy vehicle integration:Retrofit monitor installations in existing commercial fleets face CAN protocol fragmentation and physical packaging constraints that delay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Monitor Market |
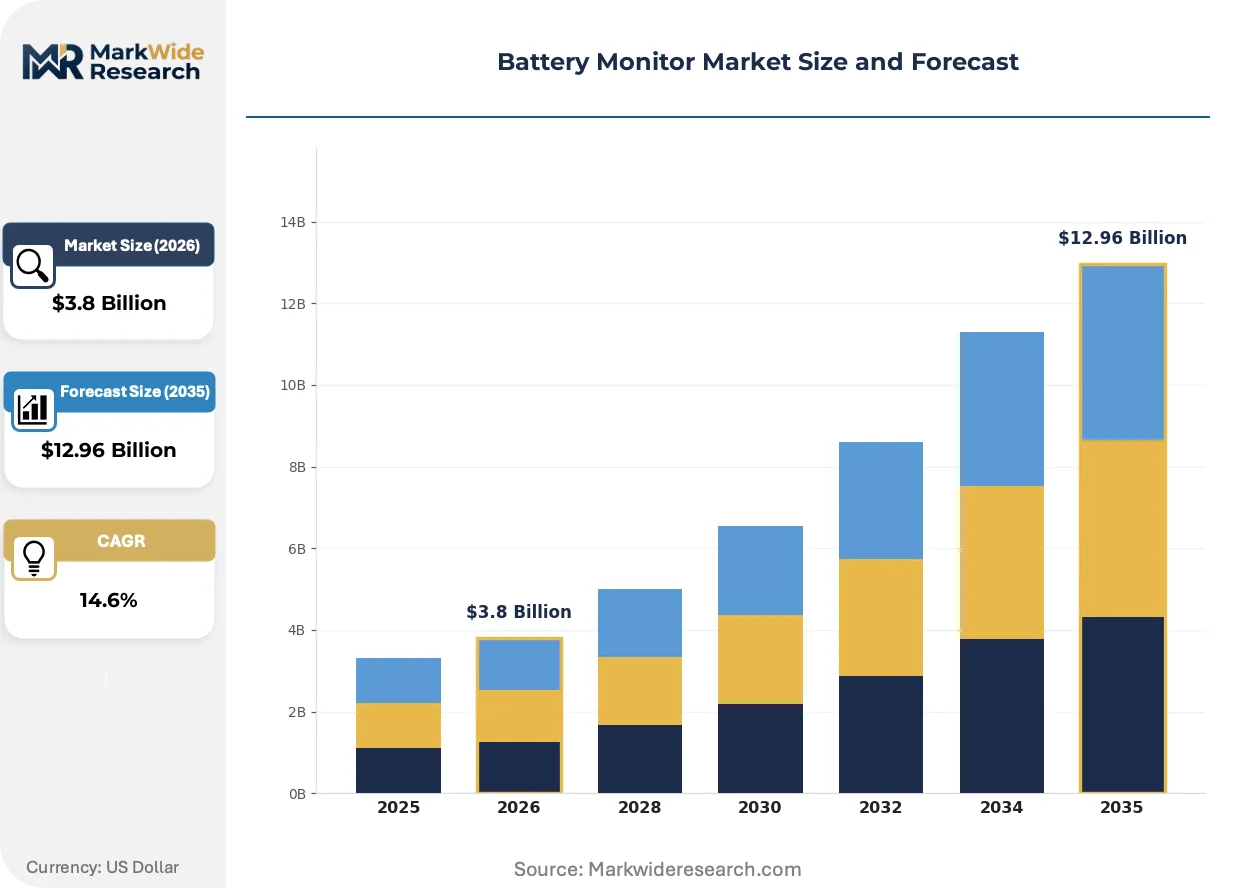
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Others Technology: Voltage Monitoring, Current Monitoring, Temperature Monitoring, Integrated Solutions End User: Automotive, Aerospace, Consumer Electronics, Industrial Applications Installation: Onboard Systems, Offboard Systems, Plug-in Monitoring, Portable Units |
| Companies Covered | Texas Instruments, ABB, Schneider Electric, Analog Devices, NXP Semiconductors, Eagle Eye Power Solutions, Curtis Instruments, BatteryDAQ, Vertiv Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Monitor Market Evolving Landscape
Convergence between electrochemical sensing precision and edge-computing capability is redefining how battery state estimation occurs, shifting computational load from host controllers toward distributed monitor nodes.
Integrated single-chip battery monitors combining voltage, current, and temperature sensing with embedded ARM Cortex-M0 processing cores are miniaturizing module footprints while enabling local state-of-charge estimation without host controller intervention. Automotive OEMs in Germany and Japan are qualifying these devices for 800V architectures ahead of 2025 platform launches. The compression of multi-function integration into single-die solutions is eliminating wiring harness complexity and reducing latency in safety-critical shutdown sequences.
REACH compliance frameworks and the EU Battery Regulation's carbon footprint disclosure mandates are elevating monitor specifications to include lifecycle traceability and recyclability verification. Industrial battery producers must now embed documentation capabilities that track material provenance from cell manufacturing through second-life deployment. Grid-scale storage installations across member states are responding by specifying monitors with extended data logging and secure communication interfaces.
Fleet operators and energy storage developers are consolidating procurement around vertically integrated subsystem suppliers who deliver pre-qualified monitor-inverter combinations rather than discrete components. This pattern compresses vendor counts while elevating certification and liability requirements for remaining participants. The shift is most visible in California and Texas utility-scale storage markets, where engineering-procurement-construction firms now specify turnkey power conversion and monitoring packages.
Battery Monitor Market Segmentation
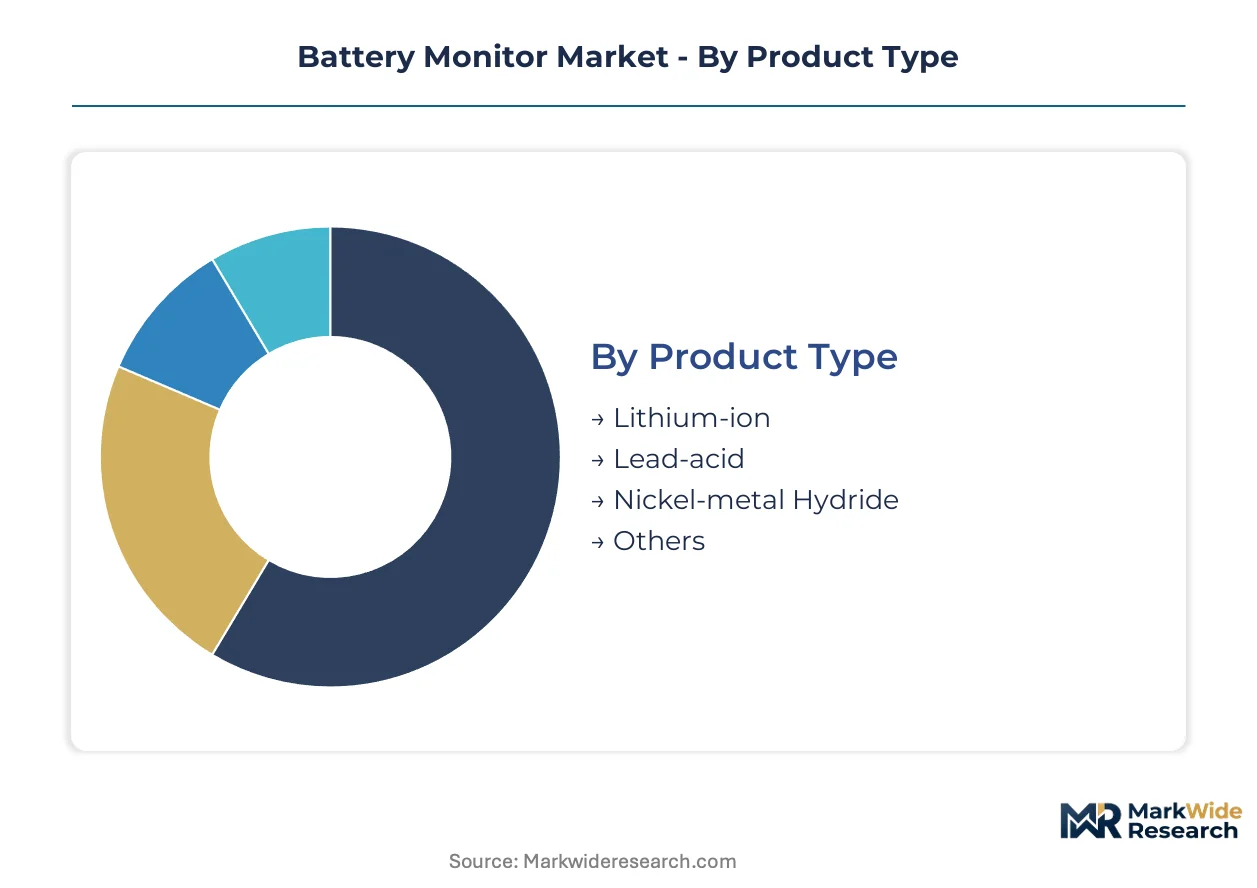
Battery monitor segmentation reveals how technical specifications, integration depth, and end-use criticality channel hardware procurement decisions across automotive, grid storage, and aviation applications. Distinct qualification thresholds and functional safety requirements create segment-specific supplier ecosystems that resist cross-selling.
Product Type:
Channel mix varies sharply by chemistry: lithium-ion flows through automotive Tier-1 distributors and direct OEM contracts, while lead-acid concentrates in aftermarket service networks and industrial battery resellers.
- Lithium-ion:Precision analog front-ends measure cell-level voltage, current, and thermal parameters with millivolt accuracy for high-cobalt and LFP chemistries alike. Automotive OEMs in Germany and Japan specify these monitors for 800V platforms, driven by thermal runaway prevention mandates from NHTSA and EU Battery Regulation state-of-health disclosure rules.
- Lead-acid:Simpler voltage threshold detection dominates forklift, telecom backup, and starter battery applications where cost sensitivity overrides precision requirements. Stationary storage developers in India specify lead-acid monitors for rural microgrid installations where supply chain simplicity outweighs energy density considerations.
- Nickel-metal Hydride:Legacy hybrid vehicle platforms and aviation auxiliary power units sustain demand for NiMH-specific monitoring algorithms.
- Others:Sodium-ion and solid-state prototype monitors serve pilot production lines and research consortium validation programs.
By volume, lead-acid leads. By growth pace, lithium-ion is expanding most quickly.
Technology:
Cost tier stratification separates discrete sensing modules from premium integrated solutions, with margin compression most severe in single-function voltage monitoring.
- Integrated Solutions:Single-die architectures combine sigma-delta ADCs, ARM Cortex-M0 processing cores, and isolated communication interfaces for local state-of-charge estimation. Automotive qualification timelines of 24-36 months for ISO 26262 ASIL-D certification restrict supply to analog semiconductor veterans with foundry partnerships.
- Voltage Monitoring:Cell-level potential measurement remains the foundational sensing layer, with stackable front-ends addressing 400V-800V architectures. Grid-scale storage installations in Texas and California specify redundant voltage channels for warranty compliance.
- Current Monitoring:Precision shunt-based and Hall-effect architectures dominate coulomb-counting accuracy benchmarks.
- Temperature Monitoring:NTC thermistor and isolated delta-sigma modulator combinations address thermal propagation detection requirements.
By revenue concentration, integrated solutions command premium positioning. By deployment velocity, voltage monitoring scales fastest.
End User:
Customer type determines procurement modality: automotive demands pre-qualified subsystem bundles, while industrial buyers accept discrete component sourcing with extended validation cycles.
- Automotive:OEMs specify monitor-inverter combinations from vertically integrated Tier-1 suppliers to compress vendor counts and centralize liability. Fleet operators expanding electric vehicle deployments require continuous cell surveillance to satisfy insurer requirements and prevent thermal runaway incidents.
- Industrial Applications:Battery recyclers and second-life storage developers in Germany require electrochemical performance verification across repurposed automotive packs. CEA mandates and state-level renewable purchase obligations in India accelerate grid-scale deployment where integrated monitor-communication modules remain underpenetrated.
- Aerospace:FAA guidelines for lithium-ion transportation safety mandate continuous thermal monitoring in commercial aviation battery packs.
- Consumer Electronics:Smartphone and laptop OEMs prioritize miniaturized single-cell monitors with minimal bill-of-materials overhead.
By absolute unit volume, consumer electronics dominates. By specification intensity, aerospace maintains the steepest expansion trajectory.
Installation:
Supply concentration in onboard systems reflects automotive platform integration, while aftermarket channels sustain offboard and portable alternatives.
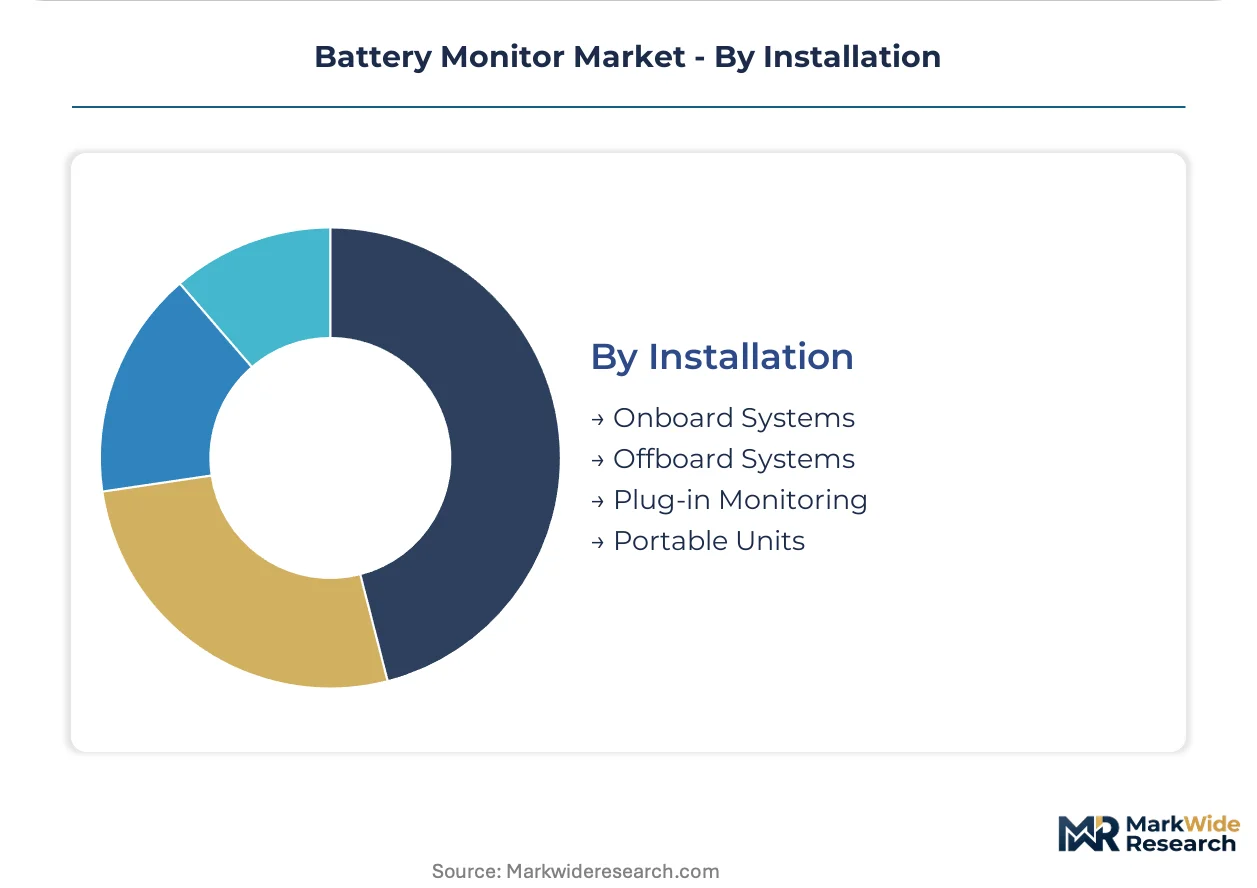
- Onboard Systems:Embedded monitors eliminate wiring complexity and reduce latency in safety-critical shutdown sequences. CAN protocol integration and physical packaging constraints complicate retrofit deployment in existing commercial fleets.
- Offboard Systems:Diagnostic stations and service bay equipment serve warranty validation and second-life assessment workflows.
- Plug-in Monitoring:Temporary measurement interfaces support field troubleshooting and maintenance operations.
- Portable Units:Handheld analyzers address small-scale industrial and commercial vehicle service requirements.
By platform integration depth, onboard systems anchor demand. By channel accessibility, portable units gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in battery monitor hardware reveal a pronounced tilt toward manufacturing economies with captive automotive and electronics demand. Net importers cluster in Western Europe and North America, while East Asian fabrication hubs supply precision analog components to global OEMs.
United States
NHTSA thermal monitoring mandates for commercial vehicle battery packs and FAA guidelines for aviation lithium-ion safety create dual regulatory pressure. Fleet operators expanding electric vehicle deployments require continuous cell surveillance systems to satisfy insurer liability requirements. California and Texas utility-scale storage markets concentrate procurement around vertically integrated monitor-inverter combinations from engineering-procurement-construction firms.
Germany
EU Battery Regulation state-of-health disclosure requirements for industrial batteries force OEMs to install continuous monitoring infrastructure. Automotive OEMs in Stuttgart and Munich specify integrated single-chip monitors for 800V architectures ahead of 2025 platform launches. Battery recyclers and second-life storage developers require electrochemical performance verification across repurposed automotive packs.
China
Domestic electric vehicle production exceeding seven million units annually generates massive demand for precision battery management electronics. MIIT new energy vehicle safety standards mandate thermal runaway detection within five minutes. Shenzhen and Shanghai fabrication clusters concentrate BCD process capacity for high-voltage analog front-ends serving both domestic OEMs and export markets.
India
CEA mandates and state-level renewable purchase obligations accelerate grid-scale battery deployment where integrated monitor-communication modules remain underpenetrated. BIS certification requirements for stationary storage systems elevate specification intensity for imported precision sensing hardware. Karnataka and Gujarat industrial corridors attract module assembly investments targeting rural microgrid installations.
Japan
METI carbon neutrality roadmaps drive solid-state battery pilot production requiring recalibrated voltage measurement tolerances. Automotive OEMs in Toyota City and Nagoya qualify next-generation sensing architectures for sulfide and oxide electrolyte formulations. Precision sigma-delta design expertise for isolated delta-sigma modulators remains concentrated among analog semiconductor veterans.
Battery Monitor Market Competitive Landscape
Concentration sits with diversified analog semiconductor houses possessing captive foundry partnerships and automotive qualification track records. The vendor base stratifies across three tiers: integrated device manufacturers with in-house BCD fabrication, fabless specialists licensing precision ADC architectures, and modular subsystem assemblers serving aftermarket channels. Dominant competitive moves include backward integration into precision shunt resistor manufacturing and strategic partnerships with Tier-1 automotive suppliers to compress vendor counts in OEM procurement.
Among diversified analog semiconductor manufacturers, Texas Instruments, Analog Devices, and NXP Semiconductors exemplify the integrated architecture tier. These companies occupy positions where foundry partnerships and precision sigma-delta IP portfolios sustain pricing power in high-voltage automotive segments. Texas Instruments represents the foundry-anchored model with analog IP depth, Analog Devices exemplifies precision current-sensing specialization for grid-scale benchmarks, and NXP Semiconductors sits within the automotive-qualified subsystem tier addressing functional safety requirements.
| Leading Market Players |
|---|
| Texas Instruments |
| ABB |
| Schneider Electric |
| Analog Devices |
| NXP Semiconductors |
| Eagle Eye Power Solutions |
| Curtis Instruments |
| BatteryDAQ |
| Vertiv Holdings |
| Others |
Value Network & Pricing Analysis
Long-term foundry capacity reservations lock in both BCD process access and wafer pricing visibility for automotive-qualified battery monitor suppliers, insulating Tier-1 procurement teams from Taiwan fab spot-market volatility while compressing margin flexibility for fabless competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 26262 ASIL-D certification and foundry partnership depth driving differentiation between tiers. Cost compression in standard-grade voltage monitoring modules is intensifying because palladium and nickel shunt resistor volatility feeds directly into bill-of-materials exposure. Aftermarket service networks exhibit highest price sensitivity, whereas grid-scale EPC firms prioritize warranty-backed subsystem bundles over unit economics.
Supply Chain Analysis
Strategic stockpiling of precision analog components dominates automotive procurement, contrasting with just-in-time preferences in consumer electronics where miniaturized single-cell monitors tolerate shorter lead times. BCD process capacity concentrates in Taiwan, South Korea, and China, with advanced node availability drawing from captive foundry partnerships and analog IP licensing arrangements. Palladium, nickel, and high-purity silicon substrates constitute critical input dependencies. Single-source vulnerability around Taiwan-based pure-play foundries elevates supply continuity risk. Distribution runs through Tier-1 automotive subsystem suppliers and specialized industrial battery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent analog semiconductor houses must defend against substitution from modular software-defined platforms that displace custom ASIC architectures in cost-sensitive stationary storage applications.
For Market Incumbents: Shield automotive market share through backward integration into precision shunt resistor manufacturing and accelerated ISO 26262 ASIL-D certification pipelines that freeze out fabless competitors. Prioritize foundry partnership renewals in Taiwan to secure BCD capacity allocation against emerging Chinese domestic suppliers. For New Entrants and Emerging Players: UL 1973 fast-track certification for grid-scale storage monitors opens white-space penetration in India and Texas utility markets where integrated monitor-communication modules remain underdeployed. Target second-life battery assessment workflows in German recycling corridors through portable diagnostic equipment channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subsystem suppliers delivering pre-qualified monitor-inverter combinations to California and Texas EPC firms. Long-term viability hinges on solid-state chemistry readiness and material provenance logging capabilities. Watch for EU Battery Regulation enforcement intensity as inflection indicator for lifecycle traceability hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Renewal | Secures BCD process allocation for 800V automotive monitor qualification ahead of German OEM platform launches. |
| ISO 26262 ASIL-D Certification Investment | Creates 24-36 month qualification moats against fabless competitors in thermal runaway prevention segments. |
| Backward Integration into Shunt Resistors | Captures margin compression from palladium and nickel commodity cycles affecting precision current sensing. |
| Solid-State Chemistry Sensing Development | Positions architectures for sulfide and oxide electrolyte voltage tolerance requirements from Japan METI pilots. |
| Material Provenance Logging Capability | Addresses EU Battery Regulation recyclability mandates and carbon footprint disclosure for industrial battery producers. |
Research Methodology
The analysis maps lithium-ion, lead-acid, and solid-state monitor sub-sectors, each validated through semiconductor procurement directors, Tier-1 automotive supplier engineers, and grid-scale EPC project managers. Primary interviews with analog front-end designers and battery recycling facility operators combined with secondary validation from SEC semiconductor filings, MIIT new energy vehicle safety standards, and EU Battery Regulation implementation guidance. Bottom-up unit shipment modeling and top-down value chain sizing provided cross-check triangulation.
Consistency checks against IEA stationary storage deployment data and IHS Markit vehicle production databases validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include chemistry type, integration depth, end-use criticality, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to technology adoption S-cycles, with solid-state chemistry transition timelines and EU state-of-health disclosure enforcement serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Battery Regulation enforcement and Taiwan foundry capacity stability; material deviation would warrant model refresh. Revision becomes warranted when BCD process allocation constraints or solid-state chemistry commercialization timelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Russia Non-Contact Infrared Thermometer Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Global Rotation Laser Market