
 Global Inverter Market | 2026-2036
Global Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inverter Market Intelligence
Software-defined grid-forming capabilities is hardening the distinction between hardware providers and energy management platform operators. Huawei leverages its deep telecommunications expertise to integrate advanced digital controls and cloud analytics into its inverter solutions. SMA specializes in system technology for photovoltaics, offering a broad portfolio for various scales. Enphase differentiates with its unique microinverter technology, which optimizes power generation at the individual panel level.
An inverter is an electronic power device that converts direct current (DC) to alternating current (AC). This conversion is achieved through a high-frequency switching process using semiconductors to produce outputs like a Pure Sine Wave. Microinverter and Hybrid technologies are seeing rapid uptake for their modularity and energy storage integration. Centralized inverters continue to serve large-scale utility projects, though String inverters gain share in commercial applications.
Grid-interconnection standards from bodies like the IEEE in the United States and compliance with Europe's RoHS directive on hazardous substances dictate product design. In China, national GB standards for power quality and electrical safety are mandatory for market access, creating a significant technical barrier. Future competitive advantage will depend on navigating these fragmented regulatory landscapes while advancing power density and digital integration.
Market Dynamics
The convergence of distributed energy resources with grid modernization mandates is the central market force, compelling firms to embed advanced grid-support functions directly into inverter software and hardware platforms.
Growth Catalysts
- National Policies:China's dual carbon goals and Europe's Green Deal fund massive renewable energy deployments, pulling demand for solar and storage inverters.
- Technology Modularity:Microinverters and string inverters with optimizers enable scalable and resilient designs for residential and commercial solar installations.
- Electrification Demand:The growth of electric vehicle charging infrastructure creates a large-scale end-market for high-efficiency power conversion technology.
Market Restraints
- Component Volatility:Supply chain dependence on a few semiconductor foundries and fluctuating magnetic material prices create production bottlenecks and margin pressure.
- Grid Interconnection Hurdles:Divergent grid codes, such as IEEE 1547 in the US and VDE in Germany, complicate product development and prolong certification.
- Thermal Management Limits:Increasing power density generates significant heat, a key engineering constraint that can limit reliability without advanced cooling solutions.
Strategic Opportunities
- Emerging Geographies:Off-grid and microgrid projects in Sub-Saharan Africa and Southeast Asia represent an opportunity for modular, battery-ready hybrid inverters.
- Bidirectional Power Flow:Vehicle-to-grid (V2G) and vehicle-to-home (V2H) applications open a new market for bidirectional inverters managing energy flow from EV batteries.
- Software as a Service:Offering grid services and virtual power plant (VPP) participation through subscription software creates new recurring revenue streams.
Industry Challenges
- Talent Scarcity:A shortage of power electronics engineers and software developers with expertise in grid-forming algorithms hinders product development capacity.
- Compliance Overhead:Adhering to global regulations, including Europe's RoHS directive and country-specific electrical safety standards, adds significant cost and delay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inverter Market |
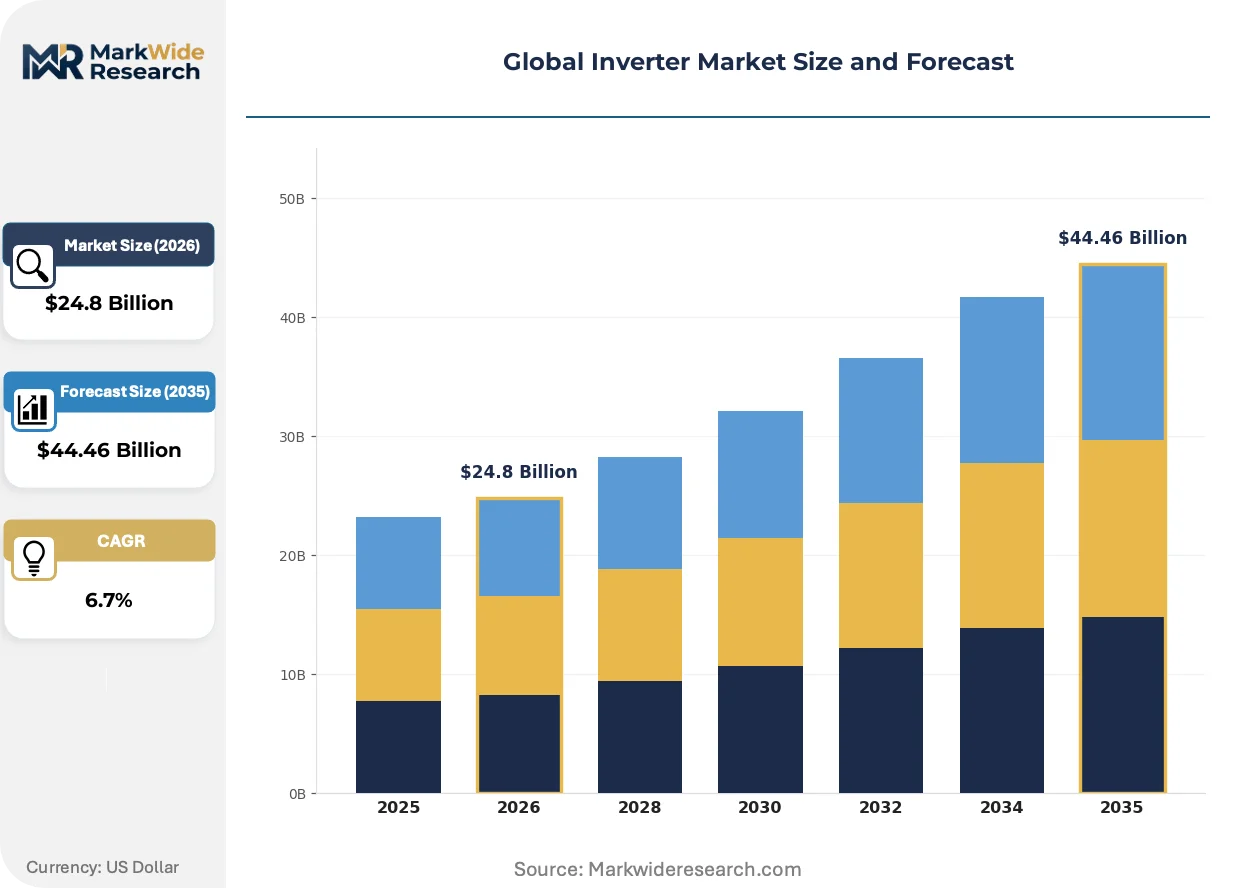
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Sine Wave, Modified Sine Wave, Square Wave, Multilevel Inverter, High Frequency Inverter Technology: Centralized, String, Microinverter, Hybrid, Module Integrated Application: Residential Power Backup, Telecommunication Equipment, Renewable Energy Systems, Industrial Automation, Data Centers End User: Utility Providers, Solar Power Installers, Commercial Facilities, Off-grid Operators, Marine Systems |
| Companies Covered | Fronius, GoodWe, Huawei, TMEIC, SolarEdge, Sungrow, Ginlong Solis, Enphase, SMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inverter Market Strategic Shifts & Innovations
A fundamental transition from hardware-centric products to software-defined energy platforms is redefining value. Inverter intelligence, not just power conversion efficiency, is becoming the primary axis of competition for grid-interactive systems.
Wide-bandgap semiconductors like Silicon Carbide (SiC) provide superior thermal conductivity and support higher switching frequencies. Solar and EV charging sectors are adopting these materials for next-generation designs. This advanced semiconductor technology is absorbing the role of bulky passive components, enabling smaller and more powerful inverter hardware.
The US Inflation Reduction Act (IRA) establishes long-term tax credits and domestic content bonuses for clean energy equipment. This policy directly incentivizes the onshoring of manufacturing for renewable energy components. North American utility-scale and residential solar segments are most impacted as firms re-evaluate supply chains to capture incentives.
Buying patterns are shifting from transactional hardware purchases to procuring fully integrated energy management systems. This change challenges traditional electrical distributors, creating openings for direct-to-installer digital platforms. The behavior is most visible in Germany's residential solar-plus-storage sector, where system interoperability is a key purchasing criterion.
Global Inverter Market Segmentation
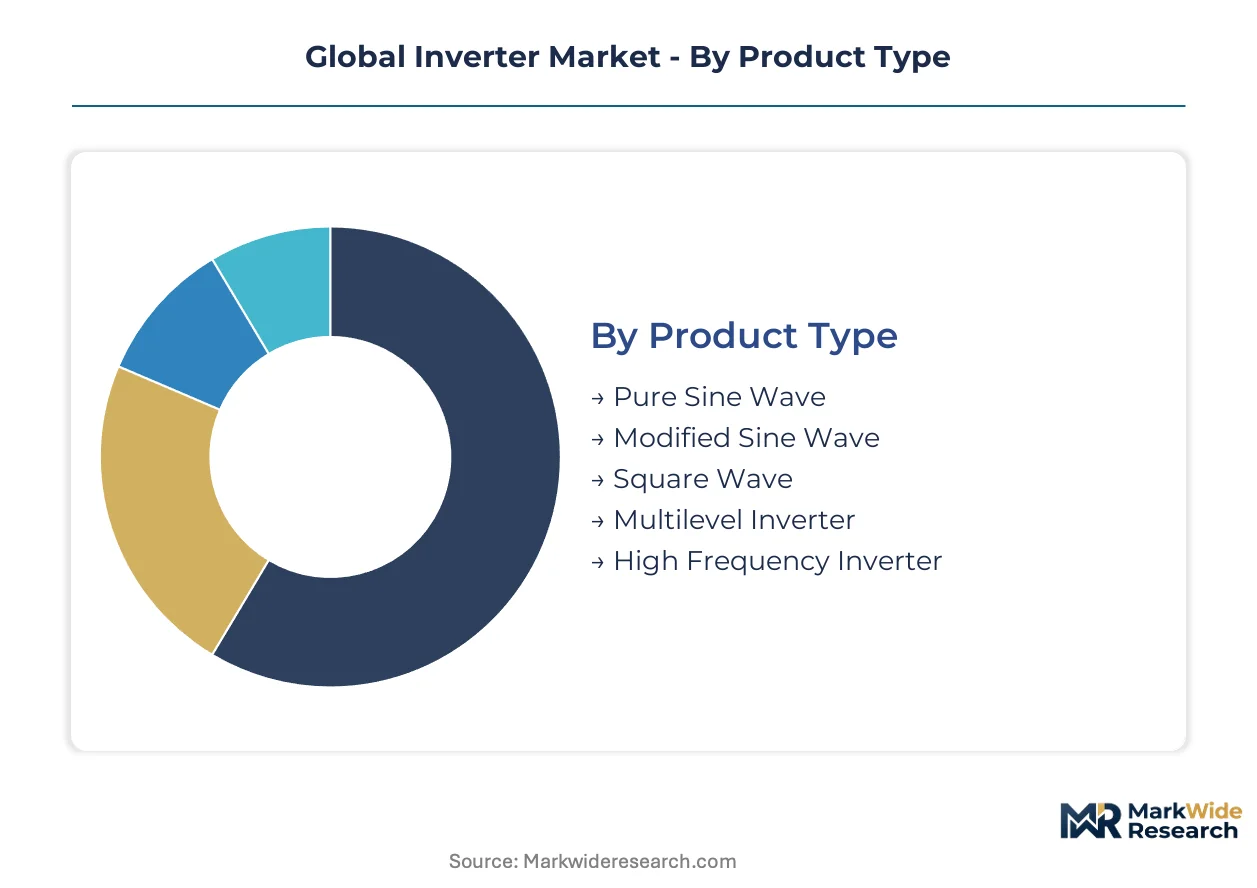
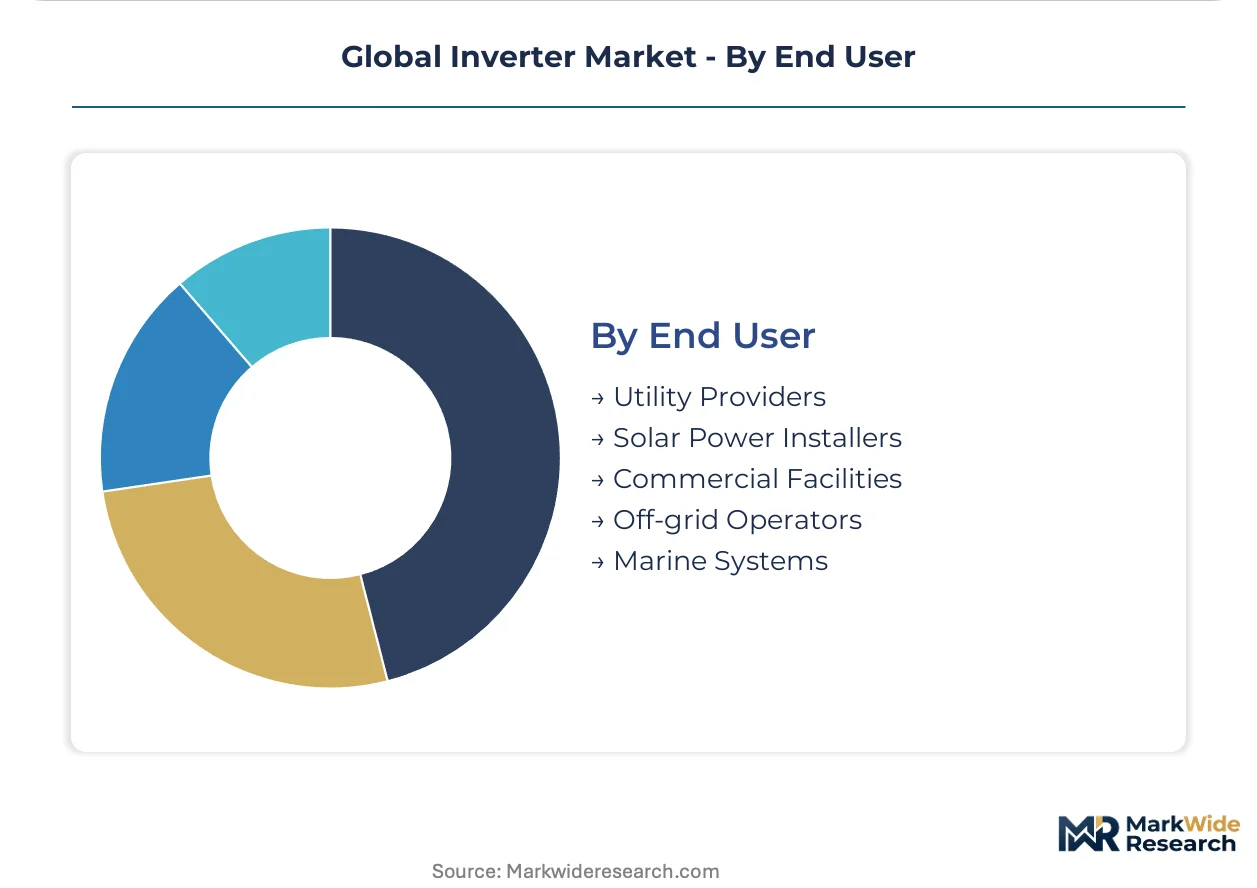
The Global Inverter Market exhibits diversification across product types, core technologies, distinct applications, and various end-user segments. Understanding these categories is essential for identifying specific growth pockets and navigating the complex regulatory and technical landscapes influencing product development.
Product Type:
Buyer decisions for inverter product types hinge on the specific load requirements and sensitivity of connected devices.
- Pure Sine Wave:This inverter produces high-quality alternating current output, mirroring grid power, making it indispensable for sensitive electronics, medical equipment, and precision machinery. Demand concentrates in residential solar-plus-storage systems in Germany, driven by stringent grid-interconnection standards.
- High Frequency Inverter:Utilizing advanced switching techniques, these inverters offer superior power density and reduced physical footprint, often incorporating wide-bandgap semiconductors. Electric vehicle charging infrastructure in China drives demand for these efficient, compact units.
- Modified Sine Wave:These inverters provide a cost-effective power conversion solution suitable for less sensitive loads, finding use in basic off-grid installations.
- Square Wave:The simplest and most economical inverter type, it generates a basic square-wave AC output primarily for resistive loads in low-cost backup power systems.
- Multilevel Inverter:This technology synthesizes AC waveforms from multiple DC voltage levels, improving power quality and efficiency for utility-scale grid applications.
Pure Sine Wave leads on scale; High Frequency Inverter leads on momentum.
Technology:
Technology selection for inverters is primarily dictated by the scale and architectural demands of the energy system.
- Microinverter:This technology optimizes power generation at the individual solar panel level, enhancing system resilience, modularity, and shade tolerance. Residential installations across the United States drive demand, incentivized by the IRA's clean energy provisions.
- Hybrid:Combining grid-tied and off-grid functionalities with integrated battery storage capabilities, hybrid inverters provide energy independence and reliable backup power. Off-grid projects in Sub-Saharan Africa represent a significant demand center for these versatile units.
- Centralized:Large, single inverter units serve utility-scale solar farms, efficiently converting bulk direct current power for grid integration.
- String:This common technology connects multiple solar panels in a series, balancing cost-effectiveness with performance for commercial rooftop installations.
- Module Integrated:This approach integrates power electronics directly into the solar module, simplifying installation and improving panel-level performance.
Microinverter technology dominates in distributed generation, while Hybrid technology shows the steepest expansion trajectory.
Application:
Inverter application varies significantly based on the operational needs and power stability requirements of specific end-use sectors.
- Renewable Energy Systems:Inverters are fundamental components for converting direct current power from solar panels or wind turbines into usable alternating current electricity for grid integration. China's dual carbon goals drive immense demand for these systems in large-scale solar projects.
- Residential Power Backup:This application provides uninterrupted power supply to homes during grid outages, often integrating solar energy and battery storage solutions. Demand in regions prone to grid instability, such as parts of India, supports this application.
- Telecommunication Equipment:Inverters ensure reliable and continuous power for critical communication infrastructure, maintaining network uptime and service continuity.
- Industrial Automation:These inverters power motor drives and control systems in manufacturing, enabling precision control and energy efficiency across various industrial processes.
- Data Centers:Inverters supply stable and clean power to sensitive servers and networking equipment, preventing data loss and ensuring continuous operation.
Renewable Energy Systems command the largest volume, with Residential Power Backup gaining market share fastest.
End User:
End-user categories reflect distinct procurement models and installation expertise required for inverter deployment.
- Utility Providers:These entities procure large-scale inverters for grid-connected solar farms and energy storage projects, prioritizing grid stability, power quality, and compliance with regulations. FERC regulations in the US influence their purchasing decisions for grid-forming capabilities.
- Solar Power Installers:These professionals purchase various inverter types for residential and commercial solar installations, prioritizing ease of integration, system reliability, and customer satisfaction. The EU Green Deal's incentives for distributed solar drive their demand in Europe.
- Commercial Facilities:Businesses deploy inverters for rooftop solar, backup power, and electric vehicle charging stations, seeking operational cost reductions and energy independence.
- Off-grid Operators:These users utilize hybrid and microinverters in remote locations, requiring robust, self-sufficient, and dependable power solutions.
- Marine Systems:Specialized inverters are integrated into various vessels for onboard power generation, battery management, and auxiliary system operation.
Utility Providers drive high-capacity inverter sales, while Solar Power Installers represent a broad and expanding customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-driven production shifts are influencing inverter manufacturing locations, as firms navigate cost-of-compliance gaps between various jurisdictions. Countries with less stringent environmental or labor regulations often attract certain manufacturing processes, while markets with robust clean energy incentives drive demand for advanced products. This dynamic creates a fragmented global supply chain for power electronics components.
China
China's dual carbon goals and extensive solar infrastructure programs drive immense demand for utility-scale inverters, particularly for renewable energy systems. National GB standards for power quality and electrical safety create significant technical barriers, favoring domestic manufacturers. The Yangtze River Delta region, with its dense electronics manufacturing base, serves as a major production hub for high-frequency inverters.
United States
Demand for microinverters and string inverters in residential and commercial solar installations is strong across the United States. The Inflation Reduction Act (IRA) establishes long-term tax credits and domestic content bonuses, incentivizing the onshoring of renewable energy component manufacturing. California and Texas lead in solar deployments, creating concentrated demand for grid-interconnection compliant devices meeting IEEE 1547 standards.
Germany
Germany's residential solar-plus-storage sector exhibits high demand for pure sine wave inverters, prioritizing system interoperability and energy independence. Europe's Green Deal policies and stringent CE marking requirements influence product development cycles, emphasizing efficiency and safety. Bavaria and North Rhine-Westphalia house significant engineering expertise and manufacturing facilities for advanced inverter technology.
India
Residential power backup applications represent a significant demand center for inverters in India, driven by grid instability and the need for uninterrupted power supply. The country's push for solar energy adoption, supported by various state-level incentives, further boosts the market. Karnataka and Gujarat are emerging as key manufacturing and deployment hubs for solar inverters and associated energy storage solutions.
Brazil
Brazil's growing distributed generation market, particularly for solar PV, creates demand for string and hybrid inverters suitable for diverse climatic conditions. Government incentives for renewable energy projects, including net metering policies, encourage adoption across residential and commercial sectors. The Southeast region, including São Paulo and Minas Gerais, leads in solar installation capacity and associated inverter deployment.
Global Inverter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market entry strategies and technological focus. The market structure exhibits a tiered consolidation, with a few large players dominating utility-scale projects and numerous smaller firms serving niche distributed generation markets. Strategic archetypes include integrated energy solution providers, pure-play inverter manufacturers, and component-focused suppliers. Geographic expansion and technology licensing represent dominant competitive moves among market participants.
Pure-play inverter manufacturers like SMA and Enphase exemplify specialized approaches, offering distinct technologies such as system technology for photovoltaics and microinverters, respectively. Huawei, a diversified technology giant, represents an integrated energy solution provider, leveraging its deep telecommunications expertise to embed advanced digital controls and cloud analytics into its inverter offerings. These companies anchor different segments of the market, from utility-scale to residential, by focusing on unique value propositions and technological differentiation.
| Leading Market Players |
|---|
| Fronius |
| GoodWe |
| Huawei |
| TMEIC |
| SolarEdge |
| Sungrow |
| Ginlong Solis |
| Enphase |
| SMA |
| Others |
Cost & Logistics Intelligence
Silicon Carbide material costs directly influence inverter module pricing, cascading through the supply chain into distinct pricing tiers for different end-user applications. This fundamental input cost affects both hardware manufacturers and system integrators.
Pricing Analysis
Direct-to-installer margins significantly impact final system costs for residential and commercial solar projects. Transactional per-unit pricing dominates hardware sales, though subscription models for energy management software are gaining traction. Price differentiation stems from certification levels, such as CE marking compliance for European markets, and the depth of after-sales service offerings. Pricing pressure intensifies for basic string inverters due to component volatility and increased competition. Residential solar installers exhibit higher price sensitivity compared to utility providers, who prioritize grid stability and long-term reliability.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume inverter procurement for utility-scale projects, while specialized electrical distributors serve residential and commercial installers. Geographic supply concentrates heavily in China for manufacturing, with Taiwan and South Korea dominating advanced semiconductor production. Key raw material dependencies include wide-bandgap semiconductors like Silicon Carbide, magnetic materials, and copper. Single-source vulnerability for specialized power electronics components represents a significant structural risk. The dominant downstream distribution model remains multi-tiered, blending direct sales for large-scale buyers with extensive channel partner networks for distributed generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Inverter Market operates as a regulatory compounder, with the EU Green Deal funding massive renewable energy deployments driving sustained demand. Policy frameworks accelerate technology adoption and shape market dynamics.
For Market Incumbents:
Hedge against the threat of software-defined energy platforms by deepening vertical integration into wide-bandgap semiconductor manufacturing. Invest heavily in advanced grid-forming algorithm research and development to maintain technological leadership. Expand manufacturing capacity in North America to capture incentives from the US Inflation Reduction Act. Focus on comprehensive energy management solutions rather than just hardware sales.
For New Entrants and Emerging Players:
Launch via digital platforms to connect directly with residential and commercial solar installers, bypassing traditional distribution channels. Target underpenetrated off-grid and microgrid projects in Sub-Saharan Africa with modular, battery-ready hybrid inverters. Bidirectional inverters for Vehicle-to-Grid (V2G) and Vehicle-to-Home (V2H) applications represent a significant white-space opportunity. Offer subscription software for grid services and virtual power plant participation as a primary go-to-market angle.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized software providers offering grid services and virtual power plant capabilities. The market demonstrates long-term viability driven by global energy transition mandates. Seek acquisition targets with proprietary grid-forming software, advanced power electronics IP, or established digital-first distribution platforms. Rapid utility adoption of VPP platforms serves as a crucial signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in North America | This move captures US Inflation Reduction Act incentives for domestic content, reducing supply chain risk. |
| Software Platform Development | Monetizing grid services and virtual power plant participation creates new recurring revenue streams. |
| Wide-Bandgap Semiconductor R&D | Improving power density and thermal management leads to smaller, more efficient inverter hardware. |
| Bidirectional Inverter Product Launch | Addressing the emerging EV-to-grid and EV-to-home market opens significant new revenue opportunities. |
| Strategic Partnership with Utilities | Co-developing grid-support functionalities ensures product compliance and market access for advanced inverters. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a robust market perspective. Primary research included discussions with power electronics engineers, utility planning officers, solar power installers, and procurement leads. Secondary validation drew from IEA reports, national energy agency data like EIA and NREL, corporate financial disclosures, and academic research papers, triangulating findings through bottom-up and top-down approaches.
The forecast framework anchored the projection horizon to comparable historical reference periods, establishing a baseline for future growth. Segmentation dimensions modeled included product type, core technology, application, end-user segment, and geographic region. Compound annual growth rates were derived from a multi-factor analysis considering renewable energy deployment targets, electric vehicle charging infrastructure growth, and semiconductor material price trends across the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions like geopolitical instability affecting supply chains or sudden shifts in regulatory incentives. Forecasts reflect assumptions regarding component availability, grid interconnection standard evolution, and talent pool development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Global Gan Power Device Market
Power Systems
Digital Inverter Market
Power Systems
Modular Inverter Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
PV Inverter Market
Power Systems
Integrated UPS Market
Power Systems
AC DC Power Adapter Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
USB Power Adapters Market
Power Systems
Telecom Battery Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Photovoltaic Inverters Market