
 String Inverter Market | 2026-2036
String Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
String Inverter Market Analysis
Utility procurement concentration is rebalancing as independent power producers consolidate into larger portfolio operators with multi-gigawatt pipelines. Sungrow Power Supply Co. Ltd. leverages its manufacturing scale to anchor utility-scale contracts across Asia. SMA Solar Technology AG competes through European channel control and service density. Huawei Technologies Co. Ltd. differentiates via integrated smart photovoltaic solutions that bundle string inverters with power electronics.
A string inverter converts direct current from serially connected photovoltaic modules into grid-compliant alternating current, typically handling input voltages up to 1,500 V DC in modern utility-scale designs. Its primary purpose is maximizing energy harvest while ensuring grid stability through reactive power control and anti-islanding protection. Three-phase string inverters dominate commercial and utility installations where higher power density reduces balance-of-system costs. Smart inverter technology is gaining fastest as grid codes in Germany, Australia, and California mandate ride-through and remote dispatch capabilities. Hybrid configurations that couple solar with battery storage command premium positioning as residential and commercial users seek backup power resilience.
FERC Order 2023 in the United States accelerates interconnection queue reform, directly shaping string inverter procurement timelines for utility developers. IEC 61727 and IEEE 1547 standards define voltage and frequency response thresholds that manufacturers must embed in firmware, creating compliance barriers for non-certified suppliers. The EU Green Deal and F-Gas Regulation pressure supply chains to eliminate sulfur hexafluoride from auxiliary switchgear, extending design requirements beyond the inverter core. Stakeholders must monitor how grid code divergence across jurisdictions fragments product certification burdens and influences regional manufacturing location decisions.
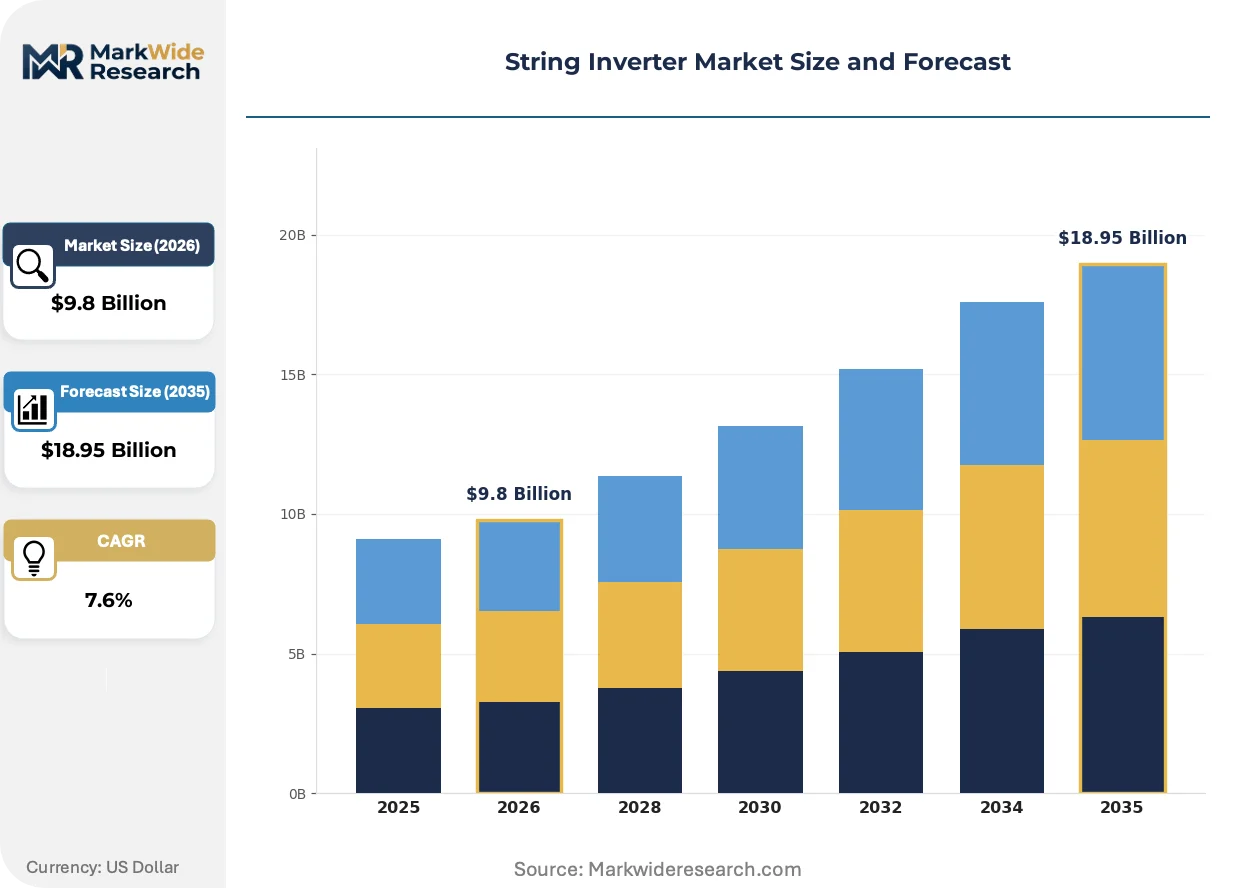
Market Dynamics
Utility-scale solar developers are consolidating procurement around fewer independent power producers with multi-gigawatt pipelines, compressing vendor negotiation cycles and favoring manufacturers with captive component supply.
Growth Catalysts
- IEEE 1547-2018:Tightened reactive power and voltage ride-through mandates in the United States force inverter replacements and firmware upgrades across existing fleets.
- State renewable purchase obligations:India's state-level RPO enforcement accelerates utility-scale solar tenders in Rajasthan, Gujarat, and Karnataka.
- 1500 V DC architecture:Higher voltage string designs reduce copper conductor mass and balance-of-system labor hours in utility installations.
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor fabrication concentrates in Taiwan and Germany, exposing inverter OEMs to foundry allocation volatility.
- Grid code fragmentation:Divergent voltage-frequency response curves between Germany's BDEW and California's Rule 21 multiply firmware certification costs.
- Central inverter residual demand:Large-scale solar plus storage projects in the Middle East retain central inverter architectures for single-point maintenance access.
Strategic Opportunities
- Hybrid inverter-battery integration:DC-coupled storage architectures eliminate separate battery inverter costs and capture backup power premiums in residential and commercial segments.
- EU F-Gas Regulation phase-down:Sulfur hexafluoride elimination mandates in auxiliary switchgear create openings for gas-insulated alternatives in European utility tenders.
- Aftermarket firmware services:Grid code updates and cybersecurity patches generate recurring revenue streams as installed bases age beyond warranty periods.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent in magnetics design and thermal management remains concentrated among legacy industrial drive manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous UL 1741, IEC 62109, and local grid code approvals extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | String Inverter Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Hybrid, Battery Storage Technology: Grid-Tied, Off-Grid, Microinverter, Smart Inverter End User: Residential, Commercial, Industrial, Utilities Installation: Roof-Mounted, Ground-Mounted, Building-Integrated, Solar Farm |
| Companies Covered | Huawei Technologies Co. Ltd., Sungrow Power Supply Co. Ltd., SMA Solar Technology AG, SolarEdge Technologies Ltd., Ginlong Technologies, Growatt New Energy Technology Co. Ltd., Fimer S.p.A., Delta Electronics Public Co. Ltd., Chint Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
String Inverter Market Emerging Trajectories
String inverter architecture is fusing with power electronics and digital control layers to deliver grid-forming capabilities that previously required separate plant-level equipment.
Silicon carbide MOSFETs are replacing silicon IGBTs in 1500 V string inverters to cut switching losses and enable higher power densities per rack unit. European and North American utility developers are specifying SiC-based designs for new procurement cycles starting in 2024-2025. This semiconductor transition is converging with modular power block architectures that compress substation footprints and reduce AC cabling runs.
Germany's BDEW-MV guideline and the EU's Network Code on Requirements for Generators are mandating synthetic inertia and fast frequency response from distributed generation assets. Inverter OEMs must embed grid-forming firmware that emulates rotating mass behavior without physical synchronous condensers. Commercial and industrial installations above 1 MW face the steepest compliance curves, with certification deadlines cascading through 2026-2027.
Independent power producers are unbundling engineering-procurement-construction contracts from long-term service agreements, forcing inverter suppliers to compete on equipment margin alone. This purchasing behavior is fragmenting vendor relationships that previously spanned 15-20 year asset lifecycles. The disaggregation is most pronounced in the United States, where FERC Order 2023 interconnection reforms accelerate developer procurement velocity.
String Inverter Market Segmentation
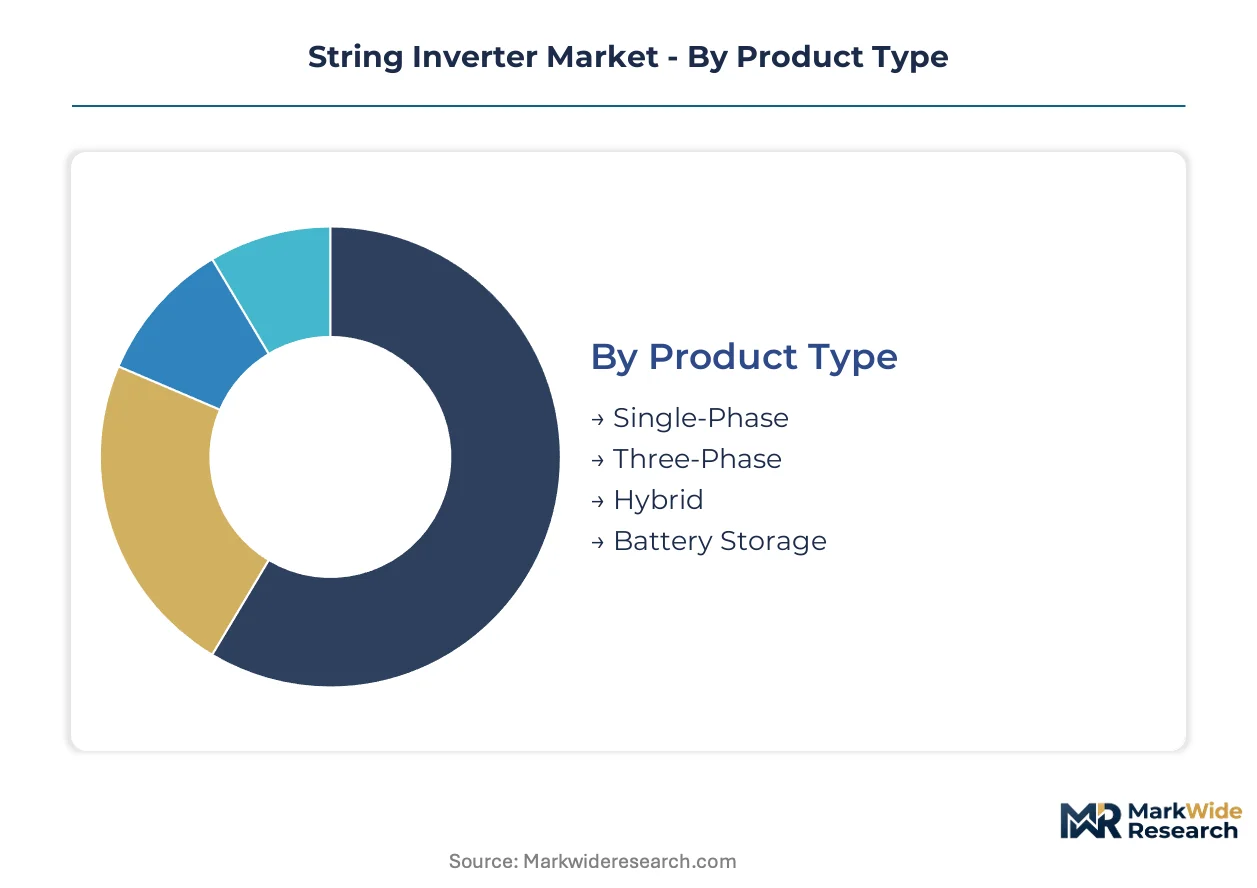
String inverter procurement patterns diverge sharply across application contexts, with voltage architecture and grid-interaction requirements dictating vendor selection. Manufacturers configure product portfolios around these segment boundaries to capture margin pools in utility-scale deployment versus distributed generation.
Product Type:
Supply concentration in high-voltage power electronics favors manufacturers with captive semiconductor sourcing and magnetics fabrication capabilities.
- Three-Phase:Handles input voltages up to 1,500 V DC with three AC output phases, enabling higher power density per unit. Utility-scale solar farms in Rajasthan and Gujarat specify three-phase designs to minimize conductor mass and installation labor across multi-megawatt arrays.
- Hybrid:Integrates solar DC input with battery storage DC coupling through a single power conversion stage. Residential and commercial installations in Germany and Australia command backup power resilience premiums, accelerating procurement of hybrid configurations that eliminate separate battery inverter hardware.
- Single-Phase:Converts DC to single AC output phase for low-voltage residential connections, typically rated below 10 kW.
- Battery Storage:Dedicated bidirectional inverter for standalone energy storage systems without solar DC input.
Three-phase units absorb the bulk of installed capacity; hybrid configurations are expanding most quickly.
Technology:
Grid code mandates in multiple jurisdictions are segmenting procurement around firmware capabilities rather than hardware specifications alone.
- Smart Inverter:Embeds ride-through, remote dispatch, and grid-forming firmware per IEEE 1547-2018 and Germany's BDEW-MV guideline. California's Rule 21 and Australian standards mandate these capabilities for new interconnections, forcing replacement cycles across existing fleets.
- Grid-Tied:Synchronizes output with utility frequency and voltage without standalone operation capability. Commercial and industrial rooftops in India and the United States deploy grid-tied designs where backup power is not a procurement priority.
- Off-Grid:Operates independently of utility connection with battery buffering for remote or islanded applications.
- Microinverter:Module-level power electronics converting DC to AC at each panel, eliminating string-level mismatch losses.
Grid-tied technology retains the largest installed base; smart inverter specifications are climbing the fastest as code compliance deadlines cascade through 2026-2027.
End User:
Procurement scale and contract structure vary dramatically across customer types, with utilities consolidating around multi-gigawatt master service agreements.
- Utilities:Procure string inverters for solar farms exceeding 100 MW through competitive tenders with 20-25 year service attachments. India's state-level renewable purchase obligations concentrate demand in Rajasthan, Gujarat, and Karnataka, where independent power producers aggregate pipeline scale.
- Residential:Distributed rooftop installations under 20 kW where homeowners prioritize warranty terms and installer availability over unit economics.
- Commercial:Mid-scale rooftops and carport canopies from 20 kW to 1 MW, often financed through power purchase agreements.
- Industrial:On-site solar for manufacturing facilities with high load coincidence and demand charge reduction objectives.
Utilities absorb the bulk of installed capacity; commercial segment procurement is expanding most quickly behind favorable PPA economics.
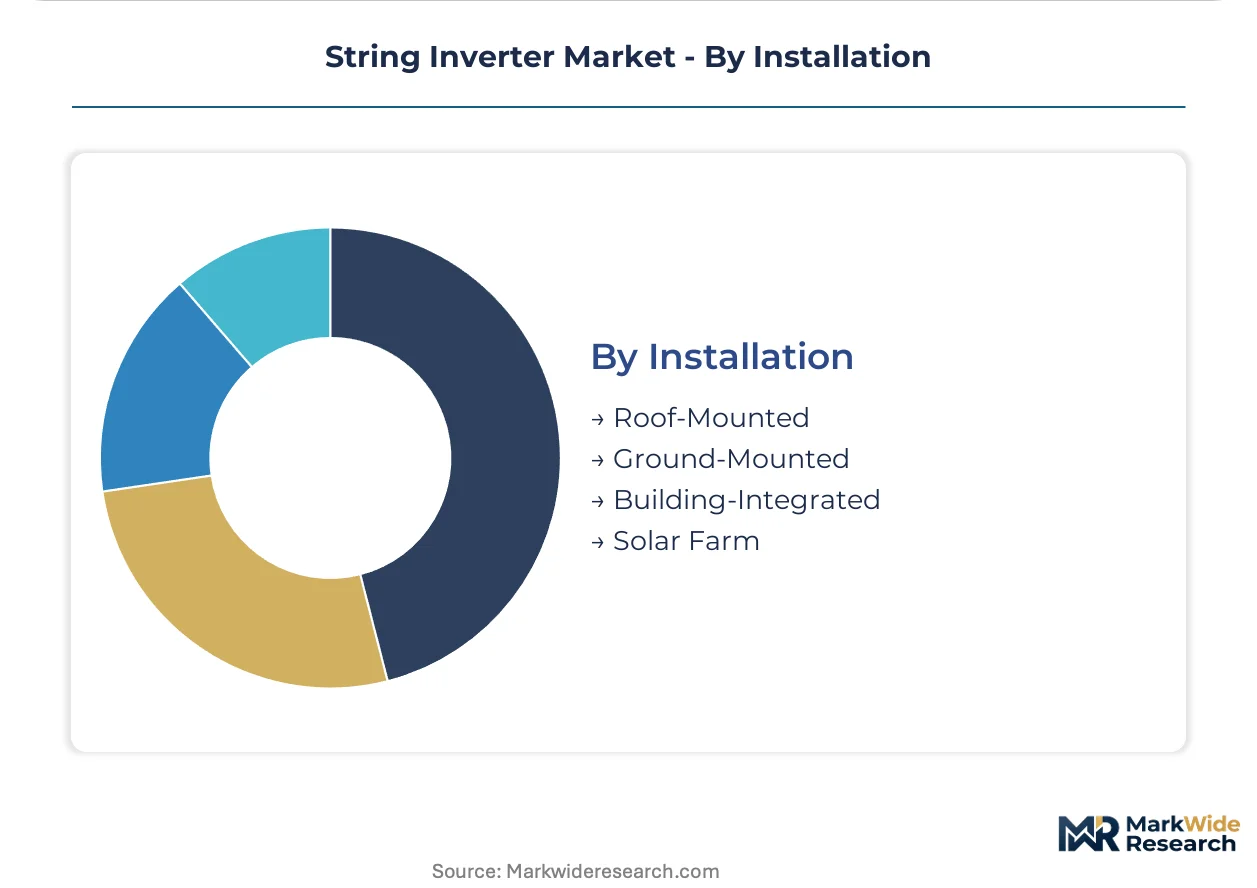
Installation:
Mounting configuration dictates environmental sealing ratings, cooling architecture, and accessibility for maintenance over 20-year asset lifecycles.
- Solar Farm:Ground-mounted utility-scale arrays with centralized inverter stations and medium-voltage step-up. Middle Eastern developers retain central inverter preference for single-point maintenance access, though string architectures gain share in Asian and North American markets.
- Roof-Mounted:Distributed generation on residential and commercial building envelopes with weight and wind-load constraints.
- Ground-Mounted:Fixed-tilt or tracking arrays below utility scale, typically 1-20 MW commercial installations.
- Building-Integrated:Photovoltaic elements structurally integrated into building facades or roofing materials with aesthetic and architectural constraints.
Solar farm installations absorb the bulk of installed capacity; roof-mounted distributed generation is expanding most quickly behind net metering policy support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon refineries in Xinjiang and wafer fabrication clusters in Jiangsu province anchor the upstream solar supply chain that feeds string inverter assembly across Asia. Manufacturing gravity follows this raw-material geography, concentrating power electronics production in eastern Chinese industrial zones before distribution to end markets.
United States
Utility-scale developers in Texas and California drive procurement volumes as interconnection queues clear under FERC Order 2023 reforms. The IEEE 1547-2018 standard mandates smart inverter capabilities including voltage ride-through and remote dispatch for all new grid connections. Arizona and Nevada host testing facilities where manufacturers validate firmware compliance before national deployment.
Germany
Commercial rooftop installations above 1 MW face accelerating compliance deadlines under the BDEW-MV guideline for synthetic inertia and fast frequency response. The EU F-Gas Regulation pressures auxiliary switchgear suppliers to eliminate sulfur hexafluoride from substation designs. Bavaria and Baden-Württemberg concentrate engineering talent for grid-forming firmware development.
India
State-level renewable purchase obligations in Rajasthan, Gujarat, and Karnataka accelerate utility-scale solar tenders exceeding 500 MW each. The Central Electricity Authority mandates compliance with IEC 61727 voltage and frequency response thresholds for all grid-connected inverters. Manufacturing incentives under the PLI scheme attract component assembly to Tamil Nadu and Telangana.
Australia
Residential and commercial segments command backup power resilience premiums following grid instability events in South Australia and Victoria. Network standards mandate anti-islanding protection and reactive power control that mirror California's Rule 21 framework. Queensland and New South Wales lead distributed generation deployment behind favorable net metering policy support.
Japan
Feed-in tariff reductions shift procurement toward self-consumption models for commercial and industrial facilities in Kanto and Kansai regions. METI grid codes require ride-through capabilities for voltage dips that exceed earlier technical standards. Kyushu and Hokkaido test islanded operation modes where string inverters must synchronize without utility reference.
String Inverter Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated smart photovoltaic solutions that bundle power conversion with digital control layers. The vendor base stratifies around manufacturing scale, regional channel density, and firmware certification breadth. Three archetypes dominate: Asian-scale manufacturers with captive component supply, European specialists with service network depth, and technology conglomerates with integrated energy management platforms. Competitive moves concentrate on backward integration into power semiconductors and geographic expansion through localized certification partnerships.
Within the scale-driven tier, Sungrow Power Supply Co. Ltd. and Huawei Technologies Co. Ltd. exemplify Asian manufacturers with integrated supply chains. SMA Solar Technology AG occupies a position among European specialists emphasizing channel control and long-term service attachments. These three anchors represent divergent strategic postures: volume manufacturing with utility-scale contract concentration, technology bundling across the solar-plus-storage stack, and regional market penetration through installer network density.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Sungrow Power Supply Co. Ltd. |
| SMA Solar Technology AG |
| SolarEdge Technologies Ltd. |
| Ginlong Technologies |
| Growatt New Energy Technology Co. Ltd. |
| Fimer S.p.A. |
| Delta Electronics Public Co. Ltd. |
| Chint Group |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor sourcing anchors both supply resilience and pricing power for string inverter OEMs, with manufacturers controlling upstream silicon carbide and IGBT fabrication commanding premium positioning in utility-scale tenders.
Pricing Analysis
Warranty and service unbundling separates equipment-only transactions from long-term maintenance contracts, with independent power producers now negotiating hardware margins independently of 20-year service attachments. Pricing stratifies across premium, standard, and economy tiers based on grid-code certification breadth and captive component supply. Cost compression in standard-tier units is intensifying as Asian-scale manufacturers leverage in-house power electronics to undercut channel-dependent competitors. Commercial installers exhibit highest price sensitivity, while utilities prioritize firmware compliance over unit economics.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale developer demand, while distributor networks serve fragmented commercial and residential segments. Power semiconductor fabrication concentrates in Taiwan, Germany, and China, with magnetics assembly clustering in eastern Chinese industrial zones. Raw material dependencies include silicon carbide wafers, copper magnet wire, and aluminum heat sink extrusions. Single-source vulnerability in 1500 V-rated silicon carbide MOSFETs exposes procurement timelines to foundry allocation volatility. Distribution runs through regional EPC contractors and specialized solar distributors with local grid-code certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
String inverter manufacturing is consolidating around multi-gigawatt contract winners as IEEE 1547-2018 compliance costs force sub-scale competitors toward exit.
For Market Incumbents: Cement firmware certification leadership by embedding grid-forming capabilities ahead of BDEW-MV and California Rule 21 deadlines. Deepen backward integration into silicon carbide packaging to secure foundry allocation during semiconductor supply crunches. Acquire regional service networks in India and Australia to capture 20-year maintenance revenue streams as procurement disaggregates from EPC contracts. For New Entrants and Emerging Players: The gap between premium smart-inverter pricing and economy grid-tied tiers offers entry space for hybrid-focused specialists. Target Australia's residential backup-power segment where resilience premiums offset hardware costs. Pursue white-label partnerships with Indian EPC contractors seeking IEC 61727-compliant alternatives to established suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial conglomerates seeking energy-transition platforms. Five-to-ten year viability hinges on grid-forming firmware capabilities and captive semiconductor supply. Watch for FERC Order 2023 interconnection queue clearance rates as inflection indicator for North American procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Vertical Integration | In-house SiC MOSFET packaging reduces switching losses and secures supply allocation from Taiwan foundries. |
| Grid-Forming Firmware Certification | BDEW-MV and IEEE 1547-2018 compliance unlocks German and Californian utility tenders above 100 MW. |
| Hybrid Inverter-Storage Integration | DC-coupled architectures eliminate separate battery inverter costs in Australian and German residential markets. |
| Regional Service Network Expansion | Localized maintenance capabilities capture 20-year service agreements as IPPs unbundle EPC contracts. |
| India PLI Manufacturing Localization | Tamil Nadu and Telangana assembly incentives reduce landed costs for Rajasthan and Gujarat utility projects. |
Methodological Framework
Independent corroboration across utility procurement officers, EPC project developers, and power electronics engineers underwrites the qualitative findings. Primary interviews with inverter OEM product managers, grid operator interconnection specialists, and solar distributor channel heads combined with secondary validation from FERC filings, IEA renewable deployment databases, and CEA tender documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon. Segmentation dimensions modeled include product architecture (three-phase, hybrid, single-phase), technology tier (smart inverter, grid-tied), end-user scale (utility, commercial, residential), and regional regulatory framework. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs from polysilicon supply forecasts and grid-code implementation timelines.
Inputs from OEM shipment disclosures and utility procurement databases were available through the study window; gaps in commercial segment distributor sell-through data introduce uncertainty bands in residential and small-commercial estimates. Forecasts reflect assumptions regarding IEEE 1547-2018 enforcement consistency and silicon carbide foundry capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Automotive Power Electronics Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
EV Power Module Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Burner Management System (BMS) Market
Power Systems
HVDC Converters Market
Power Systems
Global Plasma Generators Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Voltage Regulators Market