
 Asia-Pacific Passenger Vehicles Lubricants Market | 2026-2036
Asia-Pacific Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Passenger Vehicles Lubricants Market Outlook
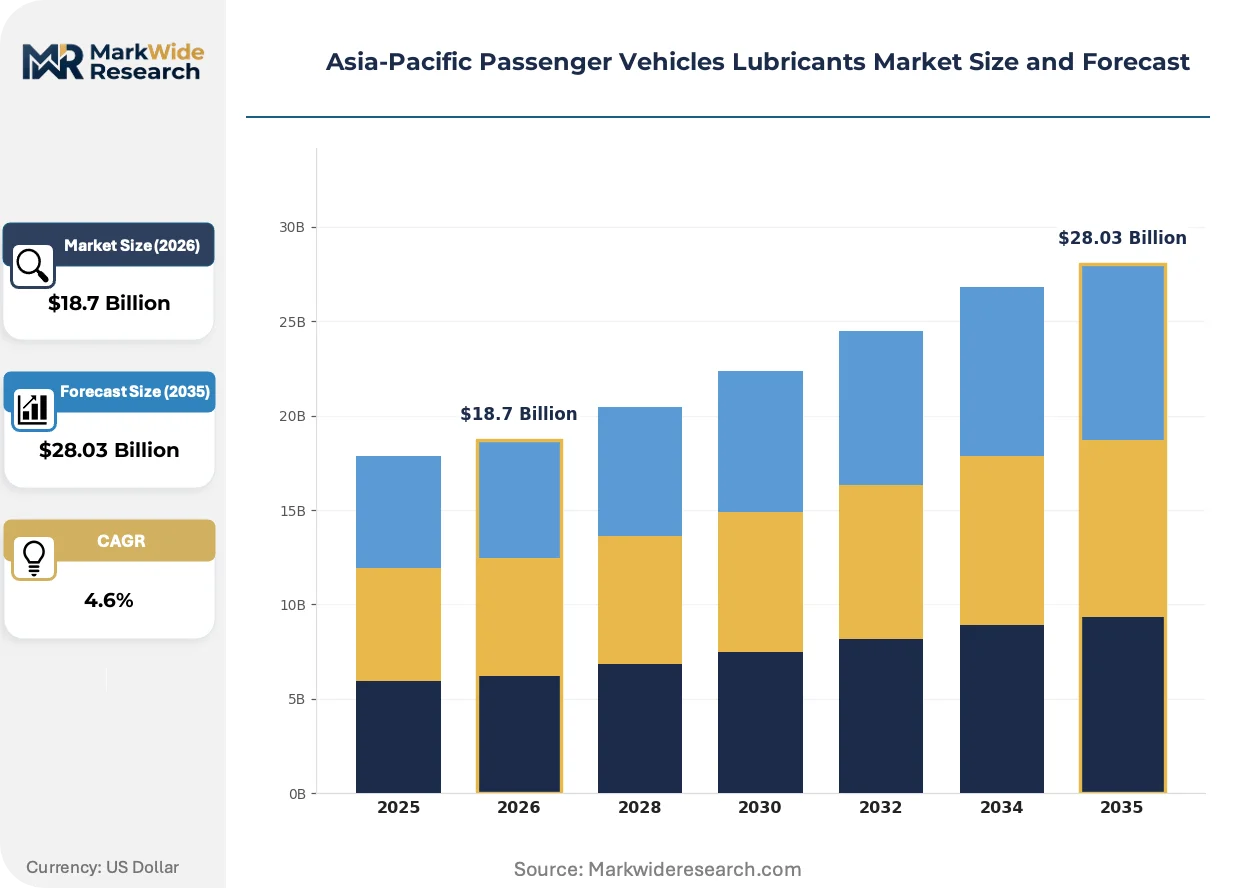
China's dual carbon goals is shifting lubricant demand toward lower-viscosity, fuel-efficient formulations across the Asia-Pacific passenger vehicle parc. ExxonMobil Corporation leverages its integrated base oil and additive supply chain to serve OEM fill markets in Thailand and Indonesia. ENEOS Corporation anchors its position through captive refinery linkages and dominant share in Japan's dealer service channel. Idemitsu Kosan Co Ltd differentiates via high-performance synthetic portfolios aligned with Korean and Taiwanese OEM specifications.
Asia-Pacific passenger vehicles lubricants encompass refined petroleum-based or synthetic fluid formulations engineered to reduce friction, dissipate heat, and protect powertrain components in gasoline and diesel passenger cars, typically characterized by SAE viscosity grades, API service categories, and OEM-specific approvals. Their primary commercial purpose is to extend engine life, maintain fuel economy certification, and ensure warranty compliance across diverse climatic operating conditions. Engine oil commands the largest volume share given universal powertrain application, while synthetic formulations are expanding fastest as OEMs tighten drain interval requirements and cold-start performance standards. Service stations retain the dominant distribution channel for immediate consumption, though online platforms are capturing growing share among DIY maintenance segments in Australia and South Korea.
Japan's METI enforces fuel economy standards that directly cascade into lubricant viscosity grade requirements for domestic passenger vehicles. China's SAMR and GB standards authorities mandate evolving specifications that restrict certain additive chemistries and mandate compatibility with gasoline particulate filters. India's BIS certification and forthcoming CAFE-equivalent regulations will force reformulation of mineral-dominant portfolios serving the mass-market segment. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid portfolio fragmentation and compliance cost escalation.
Market Dynamics
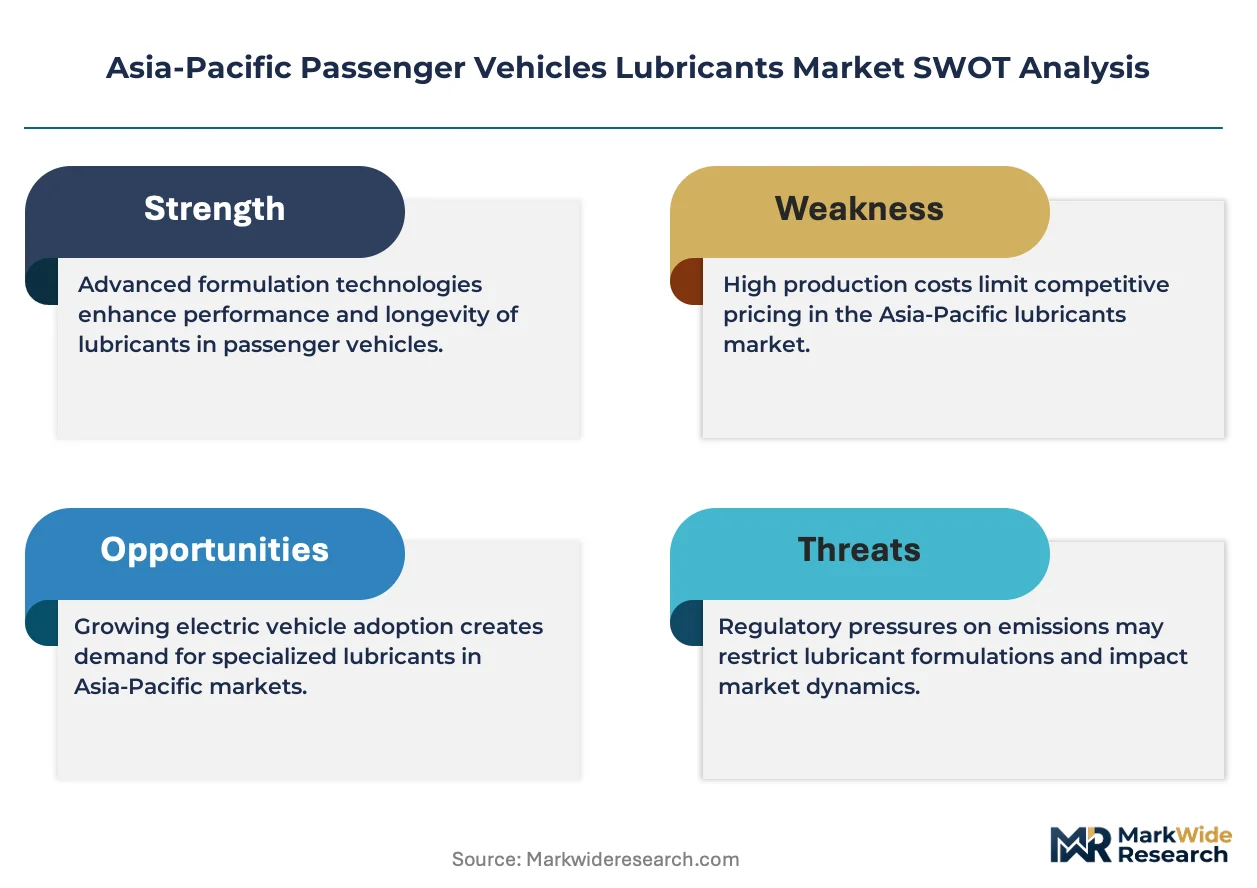
China's dual carbon goals and evolving GB standards for fuel economy are compressing lubricant viscosity grades across the Asia-Pacific passenger vehicle parc, forcing reformulation of legacy mineral portfolios and accelerating synthetic adoption timelines.
Growth Catalysts
- Urban fleet preventive maintenance expansion:Megacity fleet operators across Bangkok, Jakarta, and Ho Chi Minh City are institutionalizing scheduled oil change protocols to minimize downtime in high-utilization ride-hailing and delivery vehicle pools.
- India's BIS certification tightening:Forthcoming CAFE-equivalent regulations will mandate higher-performance lubricants across the mass-market segment, creating specification upgrades for vehicles manufactured in the Gurugram-to-Chennai corridor.
- Gasoline particulate filter compatibility requirements:China's SAMR mandates are cascading into additive chemistry restrictions that favor low-ash synthetic formulations, pulling demand away from conventional mineral bases.
Market Restraints
- Group II/III base oil supply concentration:Refinery capacity for high-quality base stocks concentrates in South Korea and Thailand, creating geographic vulnerability for blenders serving inland Chinese and Indian markets.
- Raw material volatility in additive packages:Molybdenum disulfide and zinc dialkyldithiophosphate prices fluctuate with mining output and sulfur processing economics, compressing blender margins unpredictably.
- Extended drain interval technology:Synthetic formulations enabling 15,000+ kilometer service intervals are structurally reducing per-vehicle lubricant consumption volumes in premium segments.
Strategic Opportunities
- Vietnam's underpenetrated synthetic segment:Motorcycle-dominated vehicle parc and nascent passenger car ownership create whitespace for first-mover synthetic education and OEM fill partnerships with emerging domestic assemblers.
- Online DIY platform expansion:Australia's established e-commerce infrastructure and South Korea's mobile-first retail culture enable direct-to-consumer synthetic lubricant sales, bypassing traditional service station intermediaries.
- Japan's METI fuel economy standards:Continuous tightening of viscosity grade requirements creates sustained demand for 0W-16 and 0W-8 ultra-low-viscosity formulations aligned with hybrid powertrains.
Industry Challenges
- OEM approval timeline compression:Korean and Taiwanese automakers are accelerating new specification certification cycles, straining lubricant laboratories' testing throughput and delaying product launches.
- Cross-jurisdictional formulation fragmentation:Divergent additive chemistry restrictions under China's GB standards, India's BIS, and Japan's JIS create SKU proliferation and inventory complexity for regional blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Grease Application: Light Duty Vehicles, Heavy Duty Vehicles, Commercial Vehicles, Fleet Use Formulation: Synthetic, Mineral, Semi-Synthetic, Biodegradable Distribution Channel: Retail, Online, Distributors, Service Stations |
| Companies Covered | ExxonMobil Corporation, ENEOS Corporation, BP PLC (Castrol), Idemitsu Kosan Co Ltd, GS Caltex, China National Petroleum Corporation, Royal Dutch Shell Plc, Indian Oil Corporation Limited, China Petroleum & Chemical Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Passenger Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and distribution architecture are converging to redefine competitive advantage, with regulatory stringency and consumption pattern shifts compressing traditional value chain positions.
Polyalkylene glycol-based lubricants are unifying thermal stability and electrical insulation properties for hybrid-electric powertrains. Japanese OEMs are specifying these chemistries for dual-clutch transmissions in next-generation hybrid platforms. This convergence is unifying previously separate engine and transmission fluid categories into single-fill solutions, reducing parts complexity but raising technical barriers for conventional mineral blenders.
China's SAMR and GB standards authorities are mandating compatibility with gasoline particulate filters through restricted sulfated ash, phosphorus, and sulfur content. This regulatory cascade is eliminating legacy high-ash additive packages from the domestic market. Domestic Chinese OEMs and joint ventures are responding by pre-certifying 0W-20 and 0W-16 low-SAPS formulations for 2027 model year releases.
Urban fleet operators are consolidating lubricant procurement through centralized maintenance contracts with specified viscosity grades and drain intervals. Immediate-consumption service stations in Southeast Asian megacities are losing share to direct supplier relationships with ride-hailing and logistics platforms. This concentration is most visible in Indonesia's Gojek and Grab fleet networks, where bulk synthetic supply agreements now bypass traditional retail channels entirely.
Asia-Pacific Passenger Vehicles Lubricants Market Segmentation
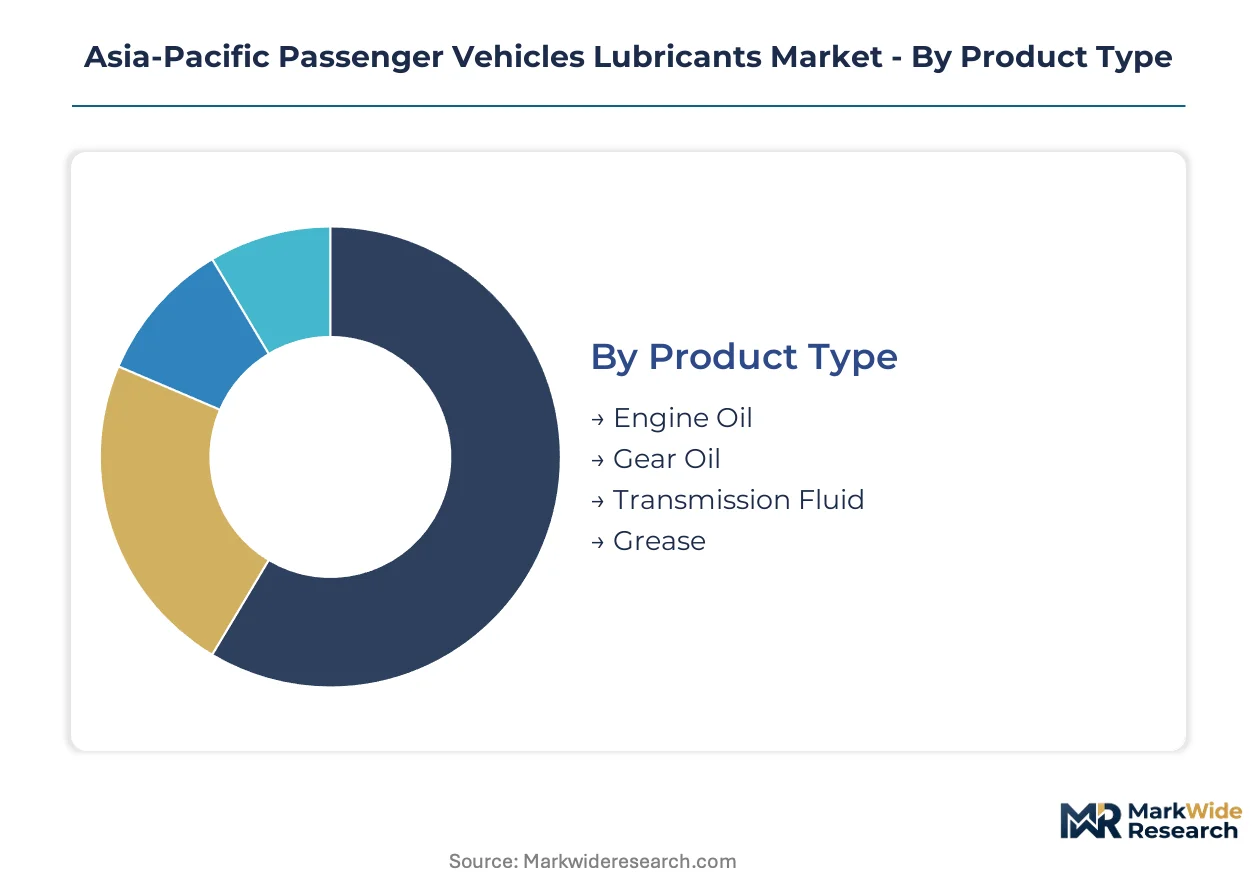
Lubricant segmentation in Asia-Pacific reflects divergent technical requirements across climates, OEM warranty regimes, and regulatory jurisdictions. Each category demands distinct formulation strategies, distribution architectures, and compliance protocols.
Product Type:
Standardization dominates high-volume categories while specialized formulations command premium positioning in performance segments.
- Engine Oil:Formulations span SAE viscosity grades from 0W-8 to 15W-40, with API SP and ILSAC GF-6 specifications governing additive chemistry. Demand concentrates in China's passenger vehicle parc where GB standards mandate low-SAPS compatibility with gasoline particulate filters. China's SAMR restrictions on sulfated ash content are forcing wholesale reformulation of legacy portfolios.
- Gear Oil:Hypoid gear lubricants for differentials and manual transmissions require extreme pressure additives with controlled thermal degradation profiles. India's northern manufacturing corridor from Gurugram to Chennai generates concentrated demand for OEM fill specifications serving domestic and export vehicle production.
- Transmission Fluid:Dual-clutch and continuously variable transmission formulations are gaining specification complexity as Japanese and Korean OEMs tighten shift quality requirements.
- Grease:Lithium complex and polyurea thickeners serve chassis and wheel bearing applications with extended service interval claims.
Most installed capacity flows through Engine Oil. Expansion is steepest in Transmission Fluid.
Application:
Volume concentration versus margin capture varies sharply across vehicle duty cycles and ownership structures.
- Light Duty Vehicles:Passenger cars and compact SUVs dominate lubricant consumption by unit volume, with synthetic penetration highest in premium segments. Australia's DIY maintenance culture and South Korea's mobile-first retail platforms are accelerating direct-to-consumer synthetic sales bypassing traditional service intermediaries.
- Heavy Duty Vehicles:SUVs and large displacement engines require higher viscosity grades and enhanced detergent packages for severe operating conditions. Southeast Asian megacity traffic patterns with extended idling cycles accelerate oil degradation and shorten effective drain intervals.
- Commercial Vehicles:Taxi and private hire fleets institutionalize preventive maintenance protocols with specified synthetic grades and centralized procurement.
- Fleet Use:Ride-hailing and logistics platforms in Indonesia's Gojek and Grab networks negotiate bulk supply agreements directly with lubricant blenders.
Light Duty Vehicles absorb the greatest volume. Fleet Use is climbing the fastest as urban mobility platforms consolidate procurement.
Formulation:
Base oil group selection determines performance ceiling, regulatory compliance, and manufacturing cost structure.
- Synthetic:Group III and Group IV base stocks enable extended drain intervals and ultra-low viscosity grades for fuel economy certification. Japan's METI standards cascade into 0W-16 and 0W-8 specifications for hybrid powertrains, with Japanese OEMs pre-certifying formulations for 2027 model year releases.
- Mineral:Group I and Group II base oils serve price-sensitive mass markets with shorter service intervals and higher consumption per vehicle. India's forthcoming CAFE-equivalent regulations under BIS certification will force specification upgrades across this segment.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-market vehicles with moderate drain interval requirements.
- Biodegradable:Ester-based and vegetable oil formulations address environmental compliance in sensitive watersheds and protected areas.
Mineral formulations retain the largest installed base. Synthetic grades are gaining share fastest as OEM drain intervals extend and China's dual carbon goals tighten.
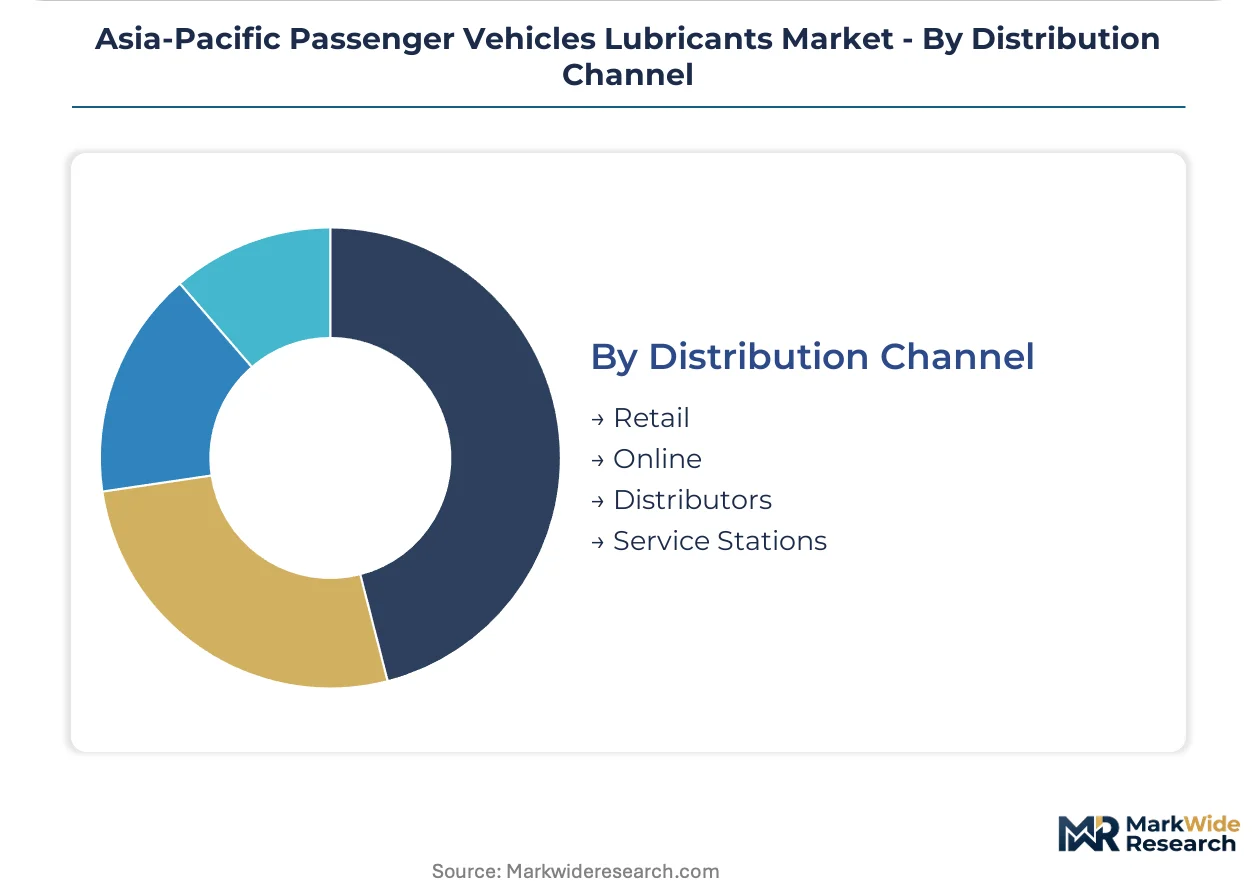
Distribution Channel:
Channel selection reflects purchase urgency, technical complexity, and customer segmentation.
- Retail:Automotive parts stores and hypermarkets serve emergency and planned maintenance needs with immediate product availability. Thailand and Indonesia maintain dense retail networks supporting both DIY consumers and independent workshops.
- Online:E-commerce platforms capture growing share in Australia and South Korea where consumers research specifications and price-compare across brands. Mobile-first purchasing behavior enables subscription models for scheduled oil change deliveries.
- Distributors:Regional warehousing networks supply independent workshops and smaller fleet operators with inventory financing and technical support.
- Service Stations:Immediate-consumption locations retain dominant share for unplanned maintenance and warranty-compliant servicing, though fleet bypass is eroding volume in Southeast Asian megacities.
Service Stations process the greatest throughput. Online channels are expanding most quickly as digital infrastructure matures and DIY segments grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lubricant formulation talent clusters in Japan's Kanto region, South Korea's Ulsan refining corridor, and India's Gurugram-Chennai manufacturing belt anchor technical development across the Asia-Pacific passenger vehicle lubricants market.
China
Domestic OEMs and joint ventures pre-certify 0W-20 and 0W-16 low-SAPS formulations for 2027 model year releases. SAMR mandates on sulfated ash, phosphorus, and sulfur content restrict additive chemistries compatible with gasoline particulate filters. Yangtze River Delta blenders reformulate legacy mineral portfolios to meet dual carbon goals and evolving GB standards for fuel economy.
Japan
Hybrid powertrain proliferation drives specification demand for 0W-16 and 0W-8 ultra-low-viscosity formulations. METI enforces fuel economy standards that cascade directly into lubricant viscosity grade requirements for domestic passenger vehicles. Kanto region OEMs specify polyalkylene glycol-based chemistries for dual-clutch transmissions in next-generation hybrid platforms.
India
Forthcoming CAFE-equivalent regulations under BIS certification will mandate higher-performance lubricants across the mass-market segment. The northern automotive manufacturing corridor stretching from Gurugram to Chennai generates concentrated demand for OEM fill specifications serving domestic and export vehicle production. Mineral-dominant portfolios serving price-sensitive segments face forced specification upgrades.
South Korea
Group II and Group III base oil refinery capacity concentrates in the Ulsan refining cluster, supplying high-quality base stocks to regional blenders. Korean automakers accelerate new specification certification cycles, straining lubricant laboratories' testing throughput. Domestic OEMs tighten shift quality requirements for dual-clutch and continuously variable transmission formulations.
Indonesia
Ride-hailing and logistics platforms in Gojek and Grab fleet networks negotiate bulk synthetic supply agreements directly with lubricant blenders, bypassing traditional service station intermediaries. Jakarta's megacity fleet operators institutionalize scheduled oil change protocols to minimize downtime in high-utilization vehicle pools. Immediate-consumption retail channels lose volume share to centralized procurement relationships.
Asia-Pacific Passenger Vehicles Lubricants Market Competitive Environment
Capital-heavy integrated refiners compete with asset-light blenders and additive specialists across the Asia-Pacific passenger vehicle lubricants market. The vendor base organizes around three strategic archetypes: integrated oil majors with captive base oil supply, regional refiners with dominant domestic distribution, and synthetic formulation specialists serving OEM certification channels. Consolidation pressure intensifies as specification complexity rises and approval timelines compress. Geographic expansion through local blending partnerships and backward integration into additive chemistry represent the dominant competitive vectors.
Within the integrated major tier, ExxonMobil Corporation and Royal Dutch Shell Plc exemplify capital-intensive players leveraging global supply chain scale. ENEOS Corporation occupies a position as a regional refiner with captive Japanese market access. Idemitsu Kosan Co Ltd represents the synthetic formulation specialist archetype aligned with Korean and Taiwanese OEM specification requirements. BP PLC through its Castrol division anchors a position balancing global reach with regional certification depth. These players collectively illustrate how technical approval velocity and base oil security determine competitive positioning across diverging national regulatory regimes.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| ENEOS Corporation |
| BP PLC (Castrol) |
| Idemitsu Kosan Co Ltd |
| GS Caltex |
| China National Petroleum Corporation |
| Royal Dutch Shell Plc |
| Indian Oil Corporation Limited |
| China Petroleum & Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialized lubricant formulation chemists concentrated in Japan's Kanto region and South Korea's Ulsan corridor command wage premiums that compress margins on economy-tier mineral blends while widening spreads to premium synthetic grades. Labor-cost differentials between these technical clusters and emerging blending operations in Vietnam and Indonesia directly shape three-tier pricing architecture across the Asia-Pacific passenger vehicle lubricants market.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the Asia-Pacific passenger vehicle lubricants market, with certification grade and volume scale serving as primary price differentiation drivers. Premium synthetic formulations bearing OEM-specific approvals from Japanese and Korean automakers capture substantial margin premiums over commodity mineral grades. Pricing pressure stems from raw material volatility in molybdenum disulfide and zinc dialkyldithiophosphate additive packages, compressing blender margins unpredictably. Fleet procurement managers demonstrate lowest price sensitivity due to total-cost-of-ownership calculations, while independent DIY consumers in price-sensitive mass markets exhibit highest elasticity.
Supply Chain Analysis
Workforce availability for specialized formulation chemistry concentrates in Japan's Kanto region, South Korea's Ulsan refining corridor, and Thailand's Eastern Economic Zone, creating geographic asymmetry in technical talent access. Base oil supply draws from Group II and Group III refinery capacity anchored in South Korea and Thailand, with additive packages resting on sulfur processing economics and mining output for key metallic components. Single-source vulnerability pervades the high-quality base stock segment, where inland Chinese and Indian blenders depend on coastal refinery output subject to logistics chokepoints. Distribution runs through service station networks for immediate consumption, though fleet bypass in Southeast Asian megacities is eroding traditional channel dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific passenger vehicle lubricants market offers margin expansion pathways through synthetic grade mix shift and operational leverage on extended drain interval technologies. Cost-down drivers in additive chemistry standardization and base oil supply security enable sustainable premium-tier positioning.
For Market Incumbents: Deploy backward integration into captive base oil supply to defend against Group II/III refinery concentration in South Korea and Thailand. Secure additive chemistry partnerships to buffer molybdenum disulfide price volatility, while accelerating OEM certification velocity to outpace Korean and Taiwanese automakers' compressed approval timelines. Channel control through fleet direct relationships in Indonesia's Gojek and Grab networks offers defensive moat against retail erosion. For New Entrants and Emerging Players: Vietnam's underpenetrated synthetic segment represents the most accessible white-space target, with motorcycle-dominated vehicle parc and nascent passenger car ownership creating education-first market development opportunity. Australia's established e-commerce infrastructure enables direct-to-consumer synthetic sales bypassing traditional service intermediaries, leveraging mobile-first purchasing behavior for subscription-based oil change delivery models. OEM fill partnerships with emerging domestic assemblers provide credible beachhead against incumbent technical approval advantages. For Investors and Strategic Acquirers: Integrated oil majors with captive refinery assets are the most active acquirer in this space, seeking additive technology capabilities to complete vertical coverage. Mid-term viability hinges on synthetic formulation expertise and OEM certification velocity rather than commodity mineral scale. Watch for divergence in China's GB standards, India's BIS certification, and Japan's JIS requirements as inflection indicator for portfolio fragmentation risk and compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group II/III refinery access insulates blenders from South Korean and Thai supply concentration risk. |
| OEM Certification Acceleration | Compressed approval timelines for Korean and Taiwanese automakers strain laboratory throughput and delay launches. |
| Fleet Direct Procurement Relationships | Bulk synthetic agreements with Indonesia's Gojek and Grab networks bypass eroding service station channels. |
| Polyalkylene Glycol Formulation Development | Japanese OEM specifications for hybrid powertrains unify engine and transmission fluid categories technically. |
| Online DIY Platform Expansion | Australia's e-commerce maturity and South Korea's mobile-first retail enable subscription-based synthetic sales. |
Study Parameters
Bottom-up vehicle parc modeling reconciled against top-down refinery output tracking forms the analytical core of this study. Primary interviews with lubricant blenders, OEM platform engineers, aftermarket distributors, and fleet procurement managers combined with secondary validation from customs trade data, vehicle production databases, and national standards authority filings establish demand-supply reconciliation. Cross-referencing of GB standards documentation, BIS certification records, and METI regulatory releases grounds regulatory scenario modeling.
Input-output matrices map base oil group supply through formulation chemistry to end-use consumption across passenger vehicle segments. Segmentation dimensions span product type, application duty cycle, formulation chemistry, and distribution channel, with propulsion architecture and regional regulatory cluster as industry-specific overlays. CAGRs derive from elasticity-adjusted volume projections against price-tier mix evolution, incorporating gasoline particulate filter penetration curves and hybrid powertrain adoption patterns as demand shapers.
Underlying measurement precision varies by segment; synthetic grade volumes and OEM-certified formulations carry tighter precision than commodity mineral estimates. Forecasts reflect assumptions on regulatory implementation timing, additive chemistry cost trajectories, and fleet procurement consolidation velocity. Material deviation in China's dual carbon policy enforcement, India's CAFE-equivalent regulation rollout, or base oil refinery capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Speed Bump Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Struts System Market
Automotive Parts
Automotive Forging Market