
 Global EV Speed Reducer Market | 2026-2036
Global EV Speed Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
Global EV Speed Reducer Market Analysis
Integrated motor-speed-reducer e-axle architectures is reconfiguring how drivetrain suppliers engineer power density into compact packages. Nidec Corporation leverages its motor-reducer integration expertise to anchor volume contracts with Asian EV platforms. BorgWarner sustains competitive positioning through R&D intensity in electromechanical reducer variants for premium passenger vehicles. ZF Friedrichshafen AG dominates European supply relationships with its scalable planetary gearbox platforms.
An EV speed reducer is a precision torque-modification device that steps down rotational speed from an electric motor to the drivetrain while multiplying torque output, typically achieving ratios between 8:1 and 12:1 through hardened alloy steel gearsets cut via hobbing or grinding processes. Its primary purpose is to match high-RPM electric motor characteristics to wheel-speed requirements while preserving efficiency across variable load conditions. Gear reducer configurations occupy the largest installed base due to proven durability under sustained torque loads, while electromechanical variants represent the fastest-expanding segment as OEMs pursue noise reduction and packaging efficiency. Planetary technology leads in passenger vehicle applications where coaxial motor alignment saves axial space, whereas helical designs compete in commercial vehicles demanding higher load capacity.
FDA guidelines on electromagnetic compatibility intersect with EPA tailpipe-equivalent emissions frameworks to shape reducer-integrated e-axle certification pathways in the US market. EMA's evolving automotive standards and REACH material restrictions influence European supplier decisions on lubricant chemistry and gearset alloy composition. China's MIIT new-energy vehicle catalog and GB standards dictate domestic reducer efficiency benchmarks that export-oriented manufacturers must satisfy. Stakeholders should monitor how divergent efficiency test cycles across these jurisdictions affect platform engineering costs and regional sourcing strategies.
Market Dynamics
Integrated e-axle architectures are compressing traditional tier boundaries as OEMs demand consolidated motor-reducer assemblies rather than discrete component sourcing. This structural shift rewards suppliers with electromechanical integration capabilities while marginalizing pure-play gear manufacturers.
Growth Catalysts
- Europe's CO2 fleet mandates:Tightened 2035 ICE phase-out targets force passenger vehicle electrification, expanding procurement volumes for planetary reducer platforms.
- China's Yangtze River Delta:Concentrated NEV manufacturing clusters generate localized demand for hardened alloy gearsets with 8:1 to 12:1 reduction ratios.
- Electromechanical reducer technology:Noise-sensitive premium passenger vehicle segments adopt non-gear torque multiplication for cabin comfort differentiation.
Market Restraints
- Alloy steel input volatility:Hardened gearset raw material costs fluctuate with nickel and molybdenum spot pricing, compressing foundry margins.
- German supplier concentration:Baden-Württemberg's planetary gearbox corridor creates single-region dependency risk for European OEM qualification programs.
- REACH lubricant restrictions:ECHA chemical limitations on extreme-pressure additives constrain high-load reducer fluid formulations.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for automotive component manufacturing attract reducer assembly localization for export platforms.
- Commercial vehicle electrification:Heavy-duty battery-electric trucks require helical load-capacity configurations absent from current passenger-centric portfolios.
- ISO 26262 functional safety:ASIL-D certification gaps among mid-tier suppliers create qualification arbitrage for integrated e-axle entrants.
Industry Challenges
- Hobbing/grinding specialist scarcity:Precision gear-cutting machine tool operators face generational retirement waves in Japan and Germany.
- E-axle thermal management integration:Reducer housing design must now accommodate motor coolant circuits, extending R&D validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EV Speed Reducer Market |
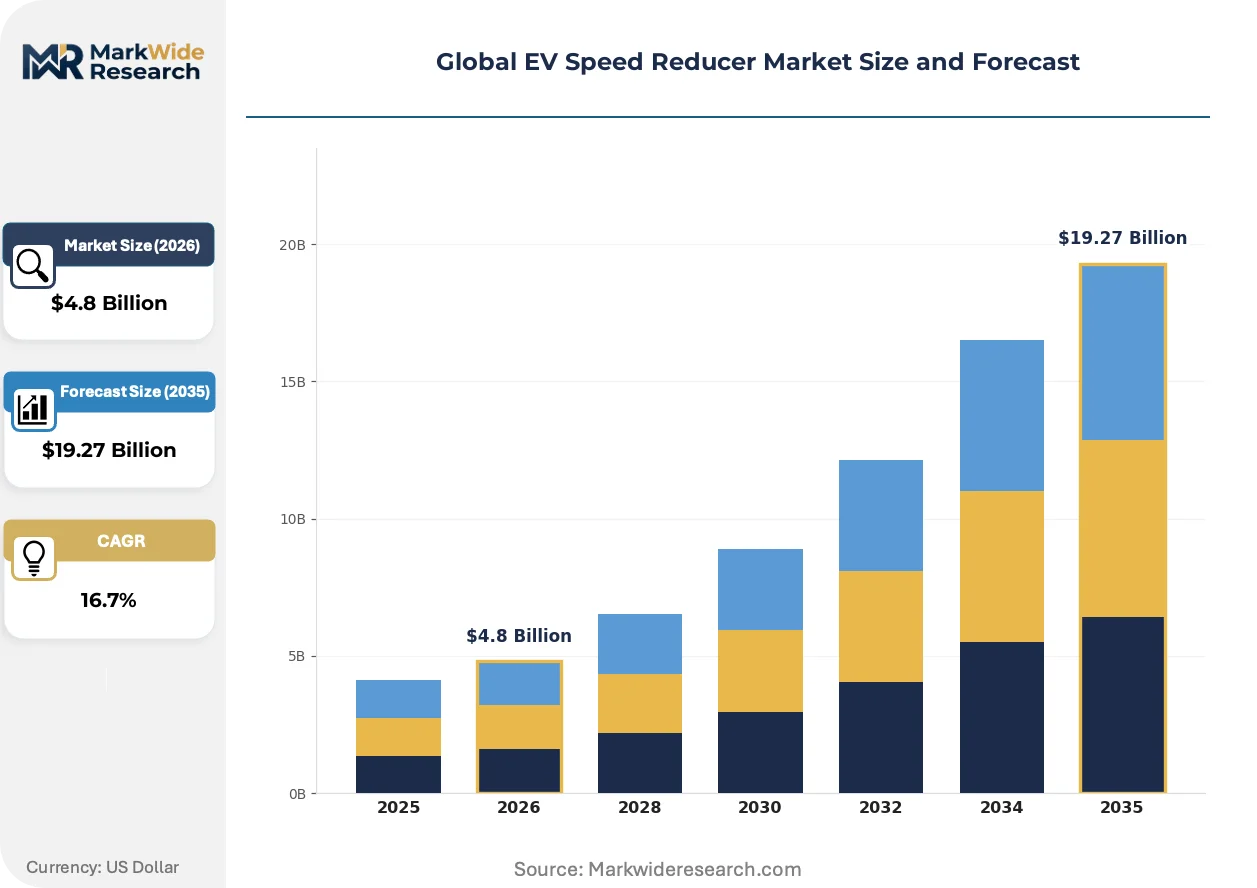
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Reducer, Belt Drive, Chain Drive, Electromechanical Technology: Planetary, Worm, Helical, Differential End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Application: Powertrain, Drivetrain, Regenerative Braking, Traction Control |
| Companies Covered | Nidec Corporation, BorgWarner, Bosch Mobility Solutions, Aisin Seiki, Magna International, ZF Friedrichshafen AG, GKN Automotive, Continental AG, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EV Speed Reducer Market Emerging Trajectories
Powertrain electrification is dissolving the historical separation between motor, inverter, and mechanical reduction systems. Suppliers now compete on thermal-mechanical integration density rather than standalone gear efficiency metrics.
Planetary gearsets with integrated hollow-shaft motor interfaces is hybridizing conventional drivetrain architectures. Asian EV platforms adopt these coaxial assemblies for packaging efficiency in compact passenger vehicles. The technology is compressing axial space requirements while forcing legacy parallel-axis suppliers toward electromechanical diversification.
EPA tailpipe-equivalent emissions frameworks now classify e-axle electromagnetic compatibility as certification-critical. NHTSA safety standards intersect with FCC radiated emission limits to create multi-agency validation pathways for integrated motor-reducer units. Premium passenger vehicle segments absorb these compliance costs through platform consolidation, while commercial vehicle suppliers delay electromechanical adoption pending regulatory harmonization.
Fleet operators now specify total-cost-of-ownership service contracts bundling reducer lubrication intervals with battery state-of-health monitoring. Traditional component distributors lose aftermarket revenue to OEM-captive service networks. China's MIIT catalog-compliant platforms exhibit this channel compression most acutely, where state-linked fleet procurement mandates integrated maintenance packages.
Global EV Speed Reducer Market Segmentation
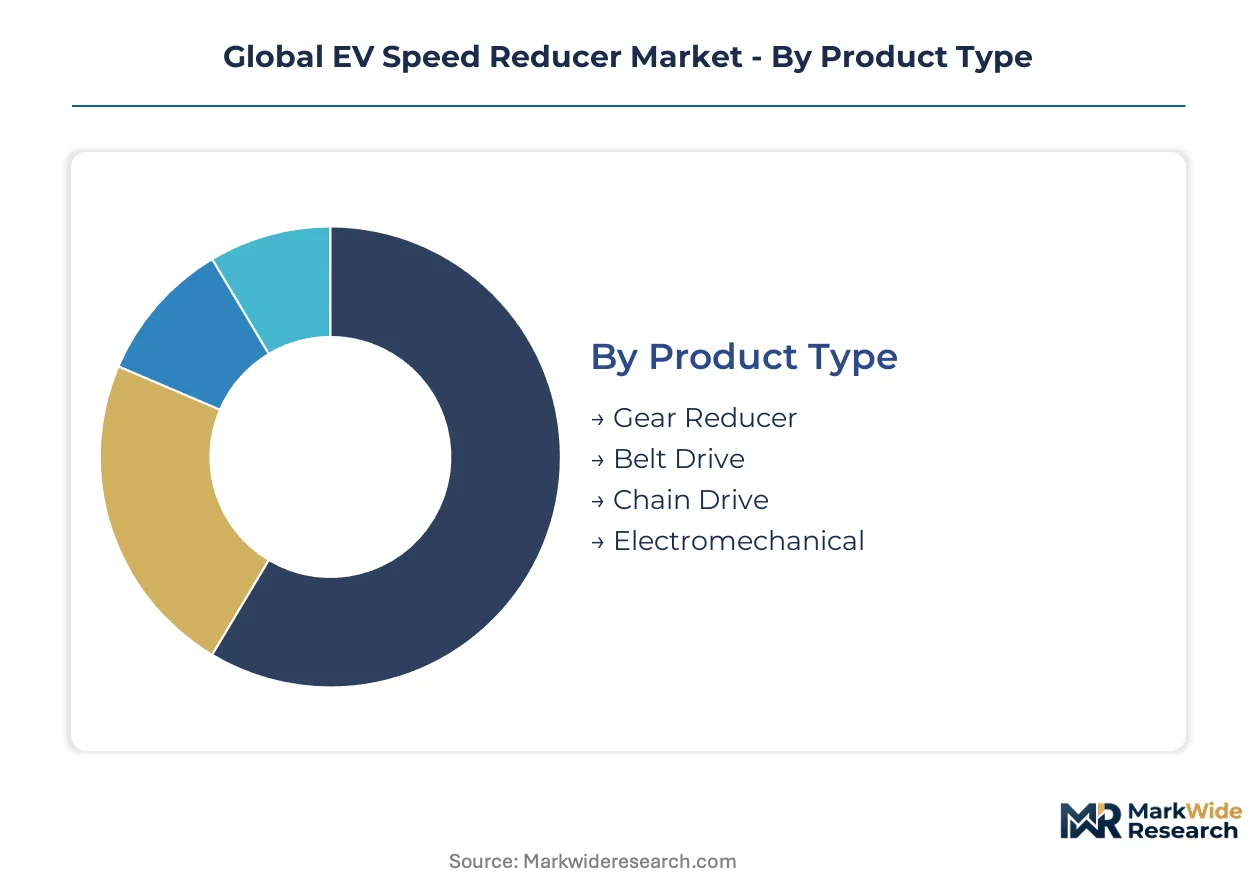
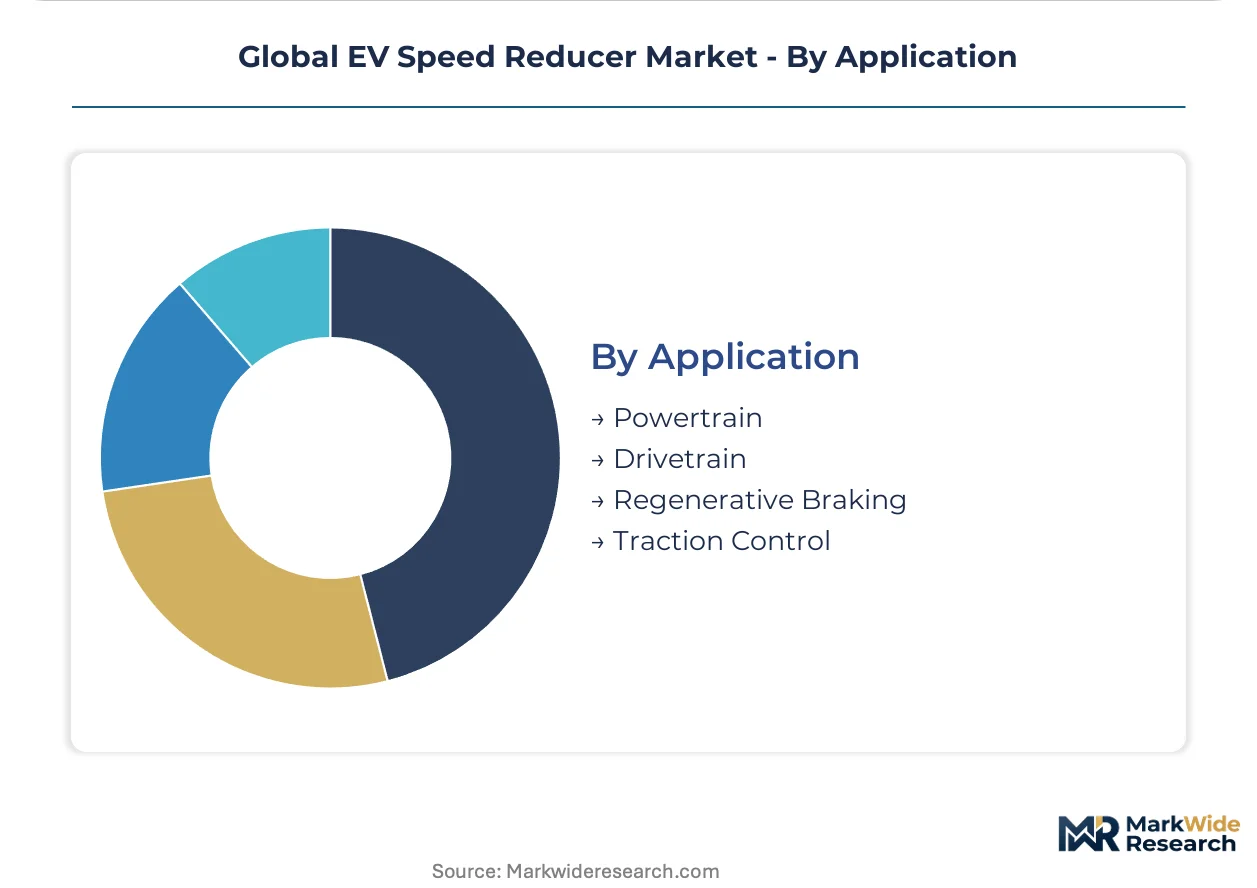
Speed reducer architectures fragment across torque multiplication mechanisms, gear geometries, vehicle duty cycles, and drivetrain integration points. Each segmentation axis reveals distinct supplier capability requirements and procurement criteria that reshape competitive positioning across passenger, commercial, and micromobility platforms.
Product Type:
Mature mechanical configurations dominate installed base volumes while emerging electromechanical variants capture premium positioning through noise reduction and packaging density.
- Gear Reducer:Hardened alloy steel gearsets achieve 8:1 to 12:1 reduction ratios through precision hobbing or grinding processes. China's Yangtze River Delta manufacturing cluster generates concentrated demand for these proven-duty configurations in mass-market passenger EV platforms.
- Electromechanical:Non-gear torque multiplication systems deploy magnetic or traction-drive principles to eliminate mesh contact noise. European premium passenger vehicle OEMs specify these for cabin comfort differentiation under tightened CO2 fleet mandates.
- Belt Drive:Synchronous belt systems offer intermediate cost positioning with reduced maintenance intervals compared to lubricated gearsets.
- Chain Drive:Roller chain configurations persist in two-wheeler and light commercial applications where shock load tolerance outweighs efficiency priorities.
Gear Reducer retains volume leadership; Electromechanical holds the steepest expansion curve.
Technology:
Cost tier stratification separates precision planetary platforms from commodity worm and helical alternatives, with differential architectures commanding premium positioning for all-wheel-drive integration.
- Planetary:Coaxial gear arrangements with sun, planet, and ring gear configurations enable compact axial packaging. Germany's Baden-Württemberg automotive corridor anchors European supply for these scalable platforms serving integrated e-axle architectures.
- Helical:Angled tooth engagement distributes load across multiple contact points for higher torque capacity. Heavy-duty battery-electric truck programs in North America specify these for drivetrain durability under sustained haulage loads.
- Worm:Single-thread worm and wheel sets provide high reduction ratios in limited space envelopes with inherent self-locking characteristics.
- Differential:Torque-vectoring capable reducers enable independent wheel speed management for traction optimization in all-wheel-drive EV platforms.
Planetary technology commands the broadest OEM qualification base; Differential configurations are expanding most quickly through electrified all-wheel-drive penetration.
End User:
Application scale divides the market between high-volume passenger platforms with standardized specifications and fragmented commercial segments demanding customized load-cycle engineering.
- Passenger Vehicles:Compact and mid-size EV platforms specify integrated motor-reducer assemblies with sub-100kg packaging targets. China's MIIT new-energy vehicle catalog dictates efficiency benchmarks that shape procurement criteria for export-oriented manufacturers.
- Commercial Vehicles:Heavy-duty battery-electric trucks require helical load-capacity configurations absent from current passenger-centric supplier portfolios. Fleet operators specify total-cost-of-ownership service contracts bundling reducer maintenance with battery state-of-health monitoring.
- Two-Wheelers:Low-torque, high-RPM reduction systems serve electric scooter and motorcycle platforms concentrated in Asian urban mobility markets.
- Buses:Transit electrification programs specify redundant-capacity reducers for stop-start duty cycles with extended warranty requirements.
Passenger Vehicles retain volume leadership; Commercial Vehicles hold the steepest expansion curve.
Application:
Integration depth varies from standalone powertrain torque modification to full drivetrain system architectures with regenerative and traction management functionality.
- Powertrain:Primary motor-to-wheel torque multiplication represents the foundational reducer application with established supply chains. Nidec Corporation anchors Asian volume contracts through motor-reducer integration expertise.
- Regenerative Braking:Bidirectional torque paths require reducer designs accommodating reverse energy flow with minimal efficiency loss. EPA tailpipe-equivalent emissions frameworks classify these integrated e-axle configurations as certification-critical in the US market.
- Drivetrain:Multi-speed reducer systems enable motor operating point optimization across extended vehicle speed ranges.
- Traction Control:Wheel-slip mitigation through torque modulation demands reducer architectures compatible with rapid response control systems.
Powertrain applications retain volume leadership; Regenerative Braking holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reducer exports flow primarily into European OEM assembly plants and North American EV platforms, establishing a transatlantic trade corridor that shapes procurement patterns across both markets.
China
MIIT catalog efficiency mandates and NEV subsidy tapering force domestic manufacturers toward higher-precision gearsets. Yangtze River Delta clusters around Shanghai and Suzhou concentrate planetary gearbox foundries serving BYD and NIO platforms. Local suppliers compete on 8:1 to 12:1 ratio standardization for mass-market passenger integration.
Germany
EMA automotive standards and REACH chemical restrictions govern lubricant formulations for integrated e-axle assemblies. Baden-Württemberg's Stuttgart-Karlsruhe corridor anchors ZF and Bosch production of scalable planetary platforms. The region's supplier density creates qualification bottlenecks for new electromechanical entrants seeking European OEM contracts.
United States
EPA tailpipe-equivalent emissions frameworks and NHTSA safety standards intersect to create multi-agency certification pathways for motor-reducer units. Michigan's Detroit-Ann Arbor automotive corridor hosts BorgWarner and Dana engineering centers focused on heavy-duty helical configurations. Fleet electrification programs in California drive demand for service-contract bundling.
Japan
METI industrial policy and JIS precision standards shape reducer quality benchmarks for export-oriented manufacturers. Nagoya's Chubu region concentrates Aisin Seiki and Nidec motor-reducer integration expertise. Aging hobbing specialist workforces in Toyota-supplier prefectures constrain capacity expansion timelines.
India
PLI scheme production-linked incentives attract reducer assembly localization for export platforms serving European and Middle Eastern markets. Tamil Nadu's Chennai-Sriperumbudur automotive belt hosts Magna and Continental supplier parks. Domestic two-wheeler electrification creates parallel demand for low-torque high-RPM reduction systems.
Global EV Speed Reducer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Integrated e-axle architectures reward suppliers with motor-reducer consolidation capabilities while marginalizing discrete component vendors. Three archetypes dominate: Japanese motor-integrators, German planetary specialists, and North American commercial-vehicle configurators. Competitive moves concentrate on backward integration into precision gear-cutting capacity and geographic co-location with Yangtze River Delta OEM final assembly.
Within the motor-integrator archetype, Nidec Corporation and Aisin Seiki occupy positions emphasizing electromechanical packaging density for Asian passenger platforms. German planetary specialists ZF Friedrichshafen AG and Bosch Mobility Solutions exemplify scalable gearbox platforms serving European CO2-mandated procurement. BorgWarner anchors North American competitive positioning through helical load-capacity engineering for commercial vehicle electrification programs.
| Leading Market Players |
|---|
| Nidec Corporation |
| BorgWarner |
| Bosch Mobility Solutions |
| Aisin Seiki |
| Magna International |
| ZF Friedrichshafen AG |
| GKN Automotive |
| Continental AG |
| Dana Incorporated |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta planetary gearbox foundries is compressing contract pricing for 8:1 to 12:1 ratio gearsets while simultaneously accelerating supplier consolidation. This utilization dynamic forces mid-tier manufacturers to absorb alloy steel input volatility or exit volume contracts, reshaping procurement leverage for OEM platform engineers.
Pricing Analysis
Current-generation planetary gearsets command premium positioning against prior-generation parallel-axis configurations and pre-commercial electromechanical prototypes. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified integrated e-axles from commodity gearboxes and unvalidated belt-drive alternatives. Pricing pressure stems from nickel and molybdenum spot volatility transmitting through hardened alloy foundry contracts. Fleet procurement managers exhibit highest price sensitivity in commercial vehicle segments, while premium passenger OEMs prioritize noise-reduction performance over unit cost.
Supply Chain Analysis
Export control regimes limiting precision hobbing machine tool flows from Germany and Japan constrain capacity expansion timelines for emerging Asian suppliers. Manufacturing gravity centers on China, Germany, and Japan, with China's Yangtze River Delta and Germany's Baden-Württemberg corridor anchoring planetary gearbox output. Supply chains draw from hardened alloy steel, extreme-pressure lubricant formulations, and rare-earth magnetic materials for electromechanical variants. Single-source vulnerability concentrates in German planetary gear-cutting equipment. Distribution runs through OEM-captive service networks displacing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as integrated e-axle architectures collapse tier boundaries, with OEM platform consolidation reducing qualified supplier lists from dozens to single-digit panels per vehicle program.
For Market Incumbents: Build captive precision gear-cutting capacity moats through backward integration into hobbing and grinding machine tool operations. Secure ASIL-D functional safety certification ahead of mid-tier competitors to defend European OEM qualification slots. Electromechanical entrants from adjacent motor markets threaten planetary gearbox incumbents through noise-reduction differentiation. Capacity addition in India's Tamil Nadu corridor offers geographic hedge against China concentration risk. For New Entrants and Emerging Players: Pursue commercial vehicle helical load-capacity configurations absent from passenger-centric incumbent portfolios. Target India's PLI scheme assembly localization for export platform access with lower qualification barriers than German OEM direct supply. Heavy-duty battery-electric truck programs represent the most penetrable white-space segment. Go-to-market through fleet operator total-cost-of-ownership service contracts bypasses entrenched OEM-captive distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical reducer sub-segments as magnetic material and thermal management R&D requirements escalate. Five-to-ten year viability favors suppliers with motor-reducer integration capabilities over discrete component manufacturers. Acquisition target archetype: mid-tier planetary specialists with hollow-shaft motor interface IP and underutilized Yangtze River Delta capacity. Watch for MIIT efficiency benchmark tightening as inflection signal requiring portfolio retooling.| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Reducer Integration Investment | Consolidates tier boundaries as OEMs demand single-source e-axle accountability from Nidec and ZF. |
| ASIL-D Functional Safety Certification | Creates qualification arbitrage for integrated e-axle entrants seeking European CO2-mandated procurement. |
| India PLI Scheme Localization | Attracts reducer assembly for export platforms serving Middle Eastern and European fleet operators. |
| Helical Configuration Expansion | Addresses heavy-duty battery-electric truck load cycles absent from current passenger-centric portfolios. |
| Hobbing Specialist Workforce Development | Counteracts generational retirement waves constraining capacity expansion in Japan and Germany. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, Tier 1 supplier procurement, and aftermarket service network management. Primary interviews with planetary gearbox foundry managers, electromechanical R&D directors, and fleet procurement officers combined with secondary validation against MIIT catalog filings, EMA automotive standard updates, and vehicle production databases. Bottom-up unit shipment modeling and top-down value chain triangulation anchored market size estimation.
Calibration against historical planetary gearbox adoption curves and electromechanical technology S-cycles informed trajectory projection across the analysis window. Segmentation dimensions modeled include reduction mechanism type, gear geometry configuration, vehicle duty cycle, and drivetrain integration depth. CAGRs derived from fitted growth curves applied to OEM platform rollout schedules and regional electrification policy intensity. Alloy steel price elasticity and REACH lubricant restriction compliance costs fed scenario-weighted forecast outputs.
Macroeconomic conditions sit as an overlay; deviation in battery-electric vehicle penetration rates or nickel spot pricing volatility would shift the trajectory. Forecasts reflect documented assumptions regarding OEM platform consolidation timing and electromechanical technology maturation curves. Material shifts in China's NEV subsidy structure or EPA tailpipe-equivalent emissions framework stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Tow Bar Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Timing Gear Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Air Springs Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Automotive Grease Market