
 Global Fiber Cement Board Market | 2026-2036
Global Fiber Cement Board Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Cement Board Market Analysis
High-density fiber cement formulations with enhanced impact resistance is reorganizing procurement priorities across major construction markets. James Hardie Industries plc leverages its captive supply of raw cellulose fiber to sustain margin stability in North American siding. Etex Group anchors its European position through specialized flat board production for rainscreen systems. SCG Building Materials dominates Southeast Asian distribution channels with localized manufacturing scale.
Global fiber cement board consists of a composite material formed from Portland cement, cellulose fibers, and silica fillers pressed into dense sheets under high pressure and heat, delivering Class A fire ratings and moisture resistance for exterior cladding and interior wet-area applications. Flat boards command the largest volume share due to standardized facade panel specifications across commercial and residential projects. Textured boards capture premium positioning as architects specify aesthetic surface finishes for visible elevations. Reinforced boards represent the fastest-growing product type as seismic and wind-load codes tighten in high-rise construction zones.
FDA guidelines on silica dust exposure during cutting and installation, EPA regulations on construction material emissions, and REACH chemical restrictions in Europe collectively elevate factory-controlled pre-finishing and wet-cutting protocols. OSHA enforcement on jobsite silica mitigation shifts demand toward prefabricated panel systems that reduce field cutting. Stakeholders must monitor how evolving carbon-border adjustments and embodied-carbon disclosure rules reshape sourcing decisions between regional plants and import-reliant distributors.
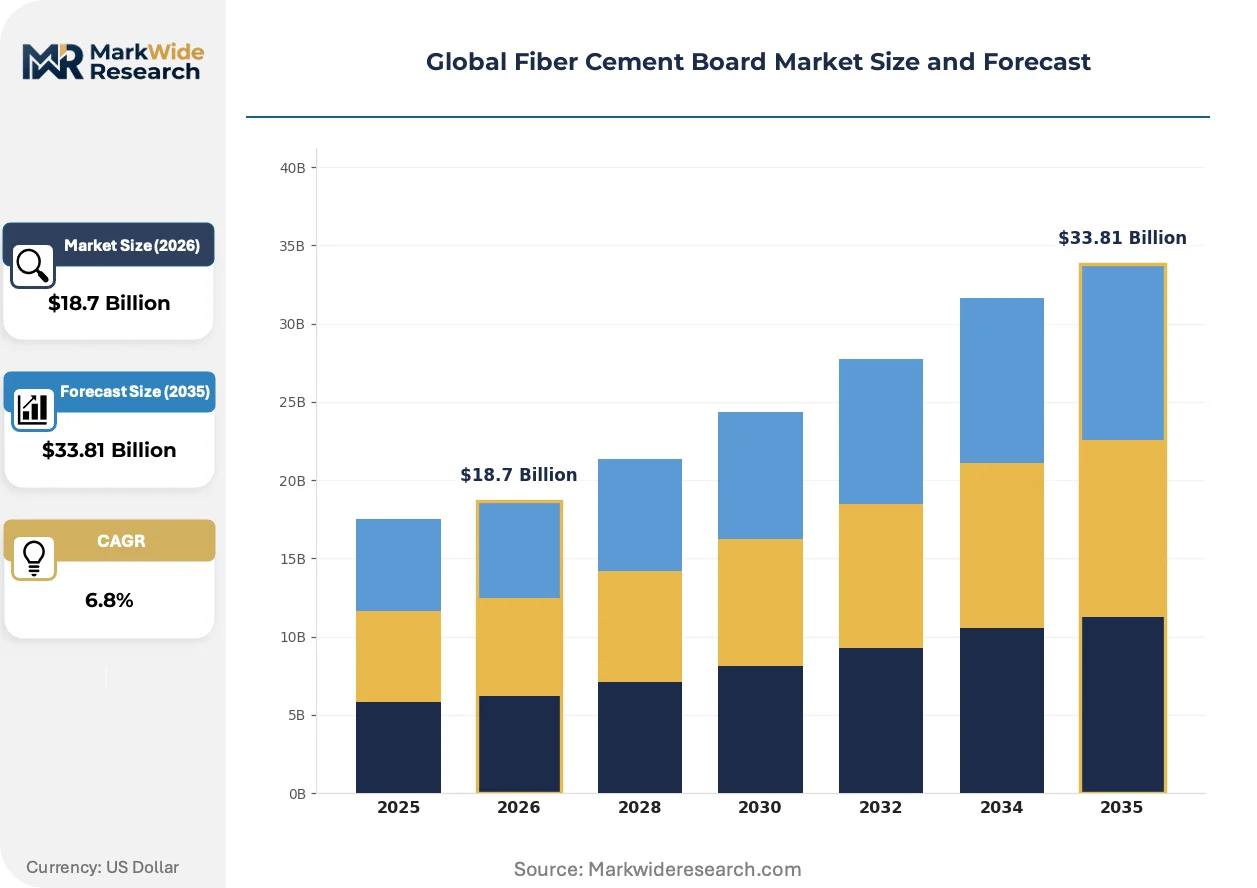
Market Dynamics
OSHA enforcement on crystalline silica exposure is compressing installation timelines and elevating factory-controlled pre-finishing adoption across North American construction sites. This regulatory pressure cascades through specification chains, rewarding suppliers with captive wet-cutting capabilities and penalizing field-dependent competitors.
Growth Catalysts
- Urban retrofit cycles:Aging commercial building stock in the United States and Germany requires fire-rated facade replacement, accelerating specification of Class A cladding systems.
- REACH chemical compliance:European manufacturers investing in low-emission formulations gain preferential access to public procurement frameworks mandating embodied-carbon disclosure.
- Cellulose fiber integration:Advanced pulp refining technologies enable higher fiber loading without strength degradation, reducing cement content and associated carbon intensity.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production concentrates in China, exposing global supply chains to fuel cost shocks and carbon-border adjustment risks.
- Silica sand sourcing concentration:High-purity silica deposits cluster in limited geographies, constraining regional manufacturing scale-up for specialized board grades.
- Substitute material advancement:Engineered wood products with improved fire ratings capture mid-rise residential segments previously dominated by fiber cement siding.
Strategic Opportunities
- Indian urban corridor expansion:Smart city infrastructure programs in Mumbai and Bangalore create demand for moisture-resistant exterior cladding in high-humidity coastal zones.
- Prefabricated panel systems:Offsite construction adoption in Japan and South Korea favors factory-finished boards delivered as complete rainscreen assemblies.
- EU Green Deal taxonomy alignment:Manufacturers certifying products under CSRD sustainability reporting standards unlock green bond financing and public project eligibility.
Industry Challenges
- Silica dust mitigation expertise:Field installation crews require specialized training on wet-cutting protocols to maintain OSHA compliance without productivity collapse.
- Embodied-carbon verification:Third-party environmental product declaration audits demand 12-18 month certification timelines that delay market entry for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Cement Board Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Boards, Textured Boards, Corrugated Sheets, Reinforced Boards Application: Residential Construction, Commercial Buildings, Industrial Facilities, Roofs Material: Cement, Cellulose Fiber, Silica, Additives Installation Method: Dry Construction, Wet Construction, Prefabricated, Direct Fixing |
| Companies Covered | Nichiha Corporation, Allura, James Hardie Industries plc, Cembrit Holding A/S, GAF Materials Corporation, Etex Group, SCG Building Materials, Shera Public Company Limited, CSR Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Cement Board Market Emerging Trajectories
Digital specification tools and automated facade engineering are compressing traditional procurement cycles while elevating performance data transparency. These forces reward manufacturers with verified technical documentation and integrated design support capabilities.
High-density fiber cement with nano-silica surface treatments is miniaturizing the performance gap between traditional thick boards and thin, lightweight alternatives. Commercial architects in Singapore and Sydney specify these reduced-thickness panels for high-rise curtain wall applications where dead load constraints previously excluded fiber cement. The technology is miniaturizing structural requirements while maintaining impact resistance, enabling penetration of steel-frame construction segments historically served by aluminum composite materials.
EPA construction material emissions guidelines and parallel EU F-Gas Regulation amendments are tightening volatile organic compound thresholds for factory-applied coatings. Manufacturers in Germany and the Netherlands invest in water-based acrylic curing systems and UV-cured surface finishes to maintain specification eligibility. Prefabricated panel producers with integrated finishing lines capture disproportionate share of public sector projects where environmental compliance documentation is mandatory.
Specification decisions increasingly consolidate around digital building information modeling libraries where architects filter products by fire rating, thermal performance, and carbon intensity before contacting suppliers. This behavior compresses the traditional sales cycle and elevates the importance of parametric product data hosted in platforms like Revit and Archicad. The shift is most visible in United Kingdom and Australian commercial markets where government mandates require embodied-carbon calculations at design stage.
Global Fiber Cement Board Market Segmentation
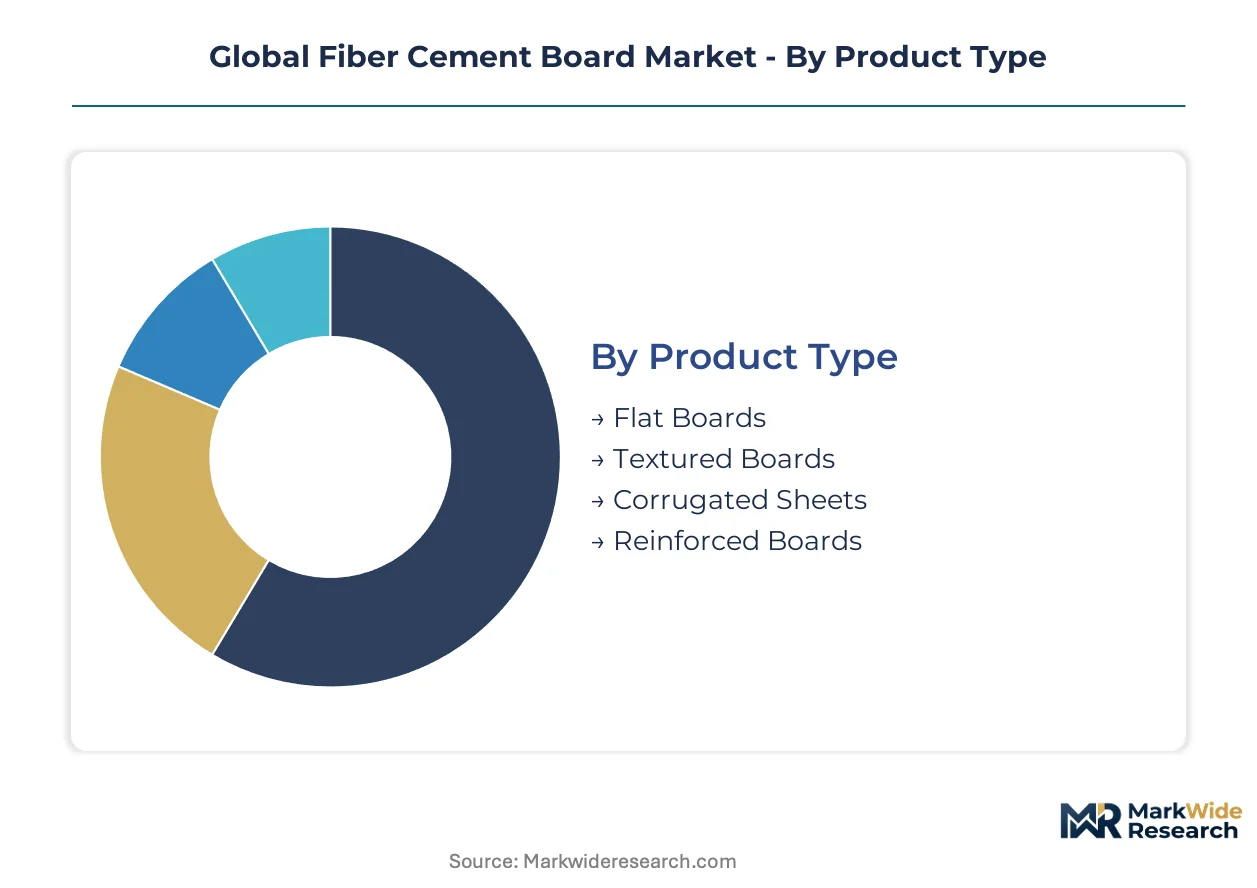
Segmentation in fiber cement board markets reveals how procurement decisions fragment across performance requirements, regulatory exposure, and installation economics. Manufacturers must align product portfolios with distinct margin architectures rather than pursuing volume across undifferentiated categories.
Product Type:
Margin pools concentrate in specialized formulations where technical differentiation commands specification premiums and limits price-based competition.
- Flat Boards:Standardized rectangular panels with uniform thickness dominate facade specifications for commercial rainscreen systems. Demand clusters in United States and German retrofit markets where Class A fire ratings are mandatory for high-rise recladding. Procurement contracts favor suppliers with wet-cutting factory capabilities that eliminate field silica exposure.
- Reinforced Boards:Glass fiber or synthetic mesh integration delivers enhanced flexural strength for seismic zones and wind-load corridors. Singapore and Sydney high-rise construction specify these for curtain wall applications where dead load constraints previously excluded fiber cement. The segment captures premium positioning as building codes tighten in Pacific Ring of Fire geographies.
- Textured Boards:Surface-patterned finishes replicate wood grain, stone, or stucco for visible residential elevations.
- Corrugated Sheets:Profiled cross-sections provide structural rigidity for roofing and agricultural building applications.
The dominant share belongs to Flat Boards, while Reinforced Boards are closing the gap fastest.
Application:
Volume flows follow construction cycle intensity, with commercial segments offering superior pricing power through specification stickiness and compliance documentation requirements.
- Commercial Buildings:Office towers, hospitals, and retail facades specify fiber cement for fire-rated cladding and moisture-resistant exterior envelopes. Mumbai and Bangalore smart city programs drive specification in high-humidity coastal zones where aluminum composite panels face corrosion limitations.
- Residential Construction:Single-family and multifamily siding applications concentrate in North American markets with established contractor installation networks. Engineered wood products with improved fire ratings are capturing mid-rise segments previously dominated by fiber cement, compressing growth in standard siding grades.
- Industrial Facilities:Manufacturing plants and warehouses deploy fiber cement for chemical resistance and low-maintenance exterior envelopes.
- Roofs:Agricultural buildings and industrial structures utilize corrugated profiles for weather protection.
Commercial Buildings command the largest revenue pool, though Residential Construction retains the highest shipment volumes.
Material:
Input cost structures determine regional manufacturing competitiveness, with cellulose fiber sourcing emerging as a critical control point for margin defense.
- Cellulose Fiber:Processed wood pulp provides flexural strength and workability while reducing cement content and associated carbon intensity. James Hardie Industries maintains captive pulp refining operations in North America to insulate margins from raw material volatility.
- Cement:Portland cement binders deliver compressive strength and fire resistance but concentrate carbon exposure in clinker production. Energy-intensive manufacturing in China exposes supply chains to fuel cost shocks and carbon-border adjustment risks under evolving EU trade rules.
- Silica:High-purity quartz fillers enhance density and weather resistance but deposit concentration constrains regional scale-up.
- Additives:Pigments, water repellents, and curing accelerators customize performance for specific climate exposures.
Cement constitutes the largest cost component by weight, while Cellulose Fiber sourcing is concentrating fastest as a competitive differentiator.
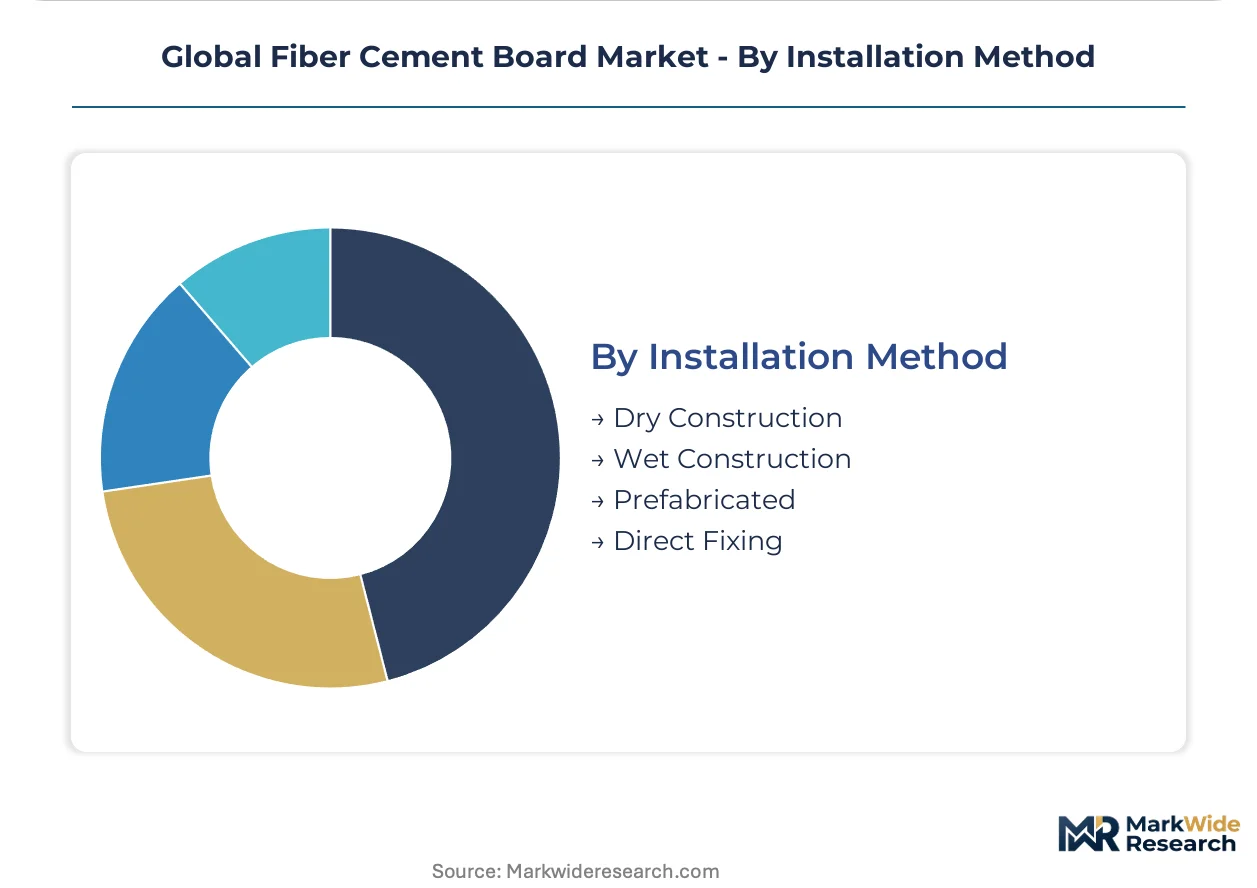
Installation Method:
Regulatory enforcement on silica exposure is restructuring demand toward factory-controlled processes that transfer compliance burden from contractors to manufacturers.
- Prefabricated:Complete rainscreen assemblies with factory-applied finishes and pre-cut dimensions eliminate field cutting and accelerate on-site installation. Japanese and South Korean offsite construction adoption favors this method, with public sector projects mandating environmental compliance documentation that prefabricated suppliers deliver.
- Dry Construction:Mechanical fastening systems allow rapid installation without wet trades, dominating North American residential siding where contractor productivity drives specification.
- Wet Construction:Adhesive bonding and mortar-based installation persists in European markets with traditional masonry contractor networks.
- Direct Fixing:Simplified attachment to structural substrates serves cost-sensitive renovation and agricultural applications.
Dry Construction retains the largest installed base, though Prefabricated methods are expanding most quickly as OSHA and REACH enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinker production clusters in China and India concentrate cement supply for fiber cement manufacturing, while finished board demand fragments across retrofit-heavy Western markets and high-rise construction corridors in Southeast Asia and the Middle East.
United States
Commercial facade replacement cycles in Chicago and New York drive specification of Class A fire-rated cladding systems. OSHA enforcement on crystalline silica exposure accelerates adoption of factory-pre-finished panels that eliminate field cutting. James Hardie Industries anchors North American supply through captive cellulose fiber operations concentrated in the Southeast.
China
Urban density in Shanghai and Shenzhen sustains volume demand for moisture-resistant exterior envelopes in high-humidity coastal construction. MEE enforcement on industrial emissions and the national dual carbon goals tighten clinker production standards, elevating input costs for domestic board manufacturers. GB standards on building fire safety mandate fiber cement in high-rise residential applications above 54 meters.
Germany
Rainscreen system specifications for commercial retrofits in Berlin and Munich concentrate demand for flat board products with REACH-compliant formulations. ECHA chemical restrictions and CSRD sustainability reporting requirements favor manufacturers with verified environmental product declarations. The country's national building energy efficiency regulations accelerate facade renovation timelines.
India
Smart city infrastructure programs in Mumbai and Bangalore create demand for moisture-resistant cladding in high-humidity coastal zones. BIS standards on construction material fire performance tighten specification requirements for high-rise commercial projects. Localized manufacturing scale in Gujarat and Maharashtra reduces import dependency for standard board grades.
Australia
Seismic and wind-load code tightening in Sydney and Melbourne high-rise construction specifies reinforced board variants for curtain wall applications. The country's national construction code mandates fire performance testing for external cladding following high-profile facade failures. Prefabricated panel adoption accelerates as skilled labor constraints compress on-site installation timelines.
Global Fiber Cement Board Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium positioning depends on captive raw material control and factory finishing capabilities. The vendor base concentrates around three strategic groupings: integrated pulp-to-board specialists, regional cement conglomerates with downstream diversification, and prefabricated system integrators. Dominant competitive moves include backward integration into cellulose fiber refining and capacity expansion in high-growth Asian corridors.
Within the integrated specialist tier, James Hardie Industries plc and Etex Group exemplify archetypes that combine captive fiber supply with specification-grade product portfolios. Among Asia-Pacific fabricators, SCG Building Materials and Nichiha Corporation occupy positions anchored in regional construction cycle intensity. Cembrit Holding A/S represents the European formulation-specialist archetype focused on rainscreen system compliance.
| Leading Market Players |
|---|
| Nichiha Corporation |
| Allura |
| James Hardie Industries plc |
| Cembrit Holding A/S |
| GAF Materials Corporation |
| Etex Group |
| SCG Building Materials |
| Shera Public Company Limited |
| CSR Limited |
| Others |
Supply Flow & Price Mechanics
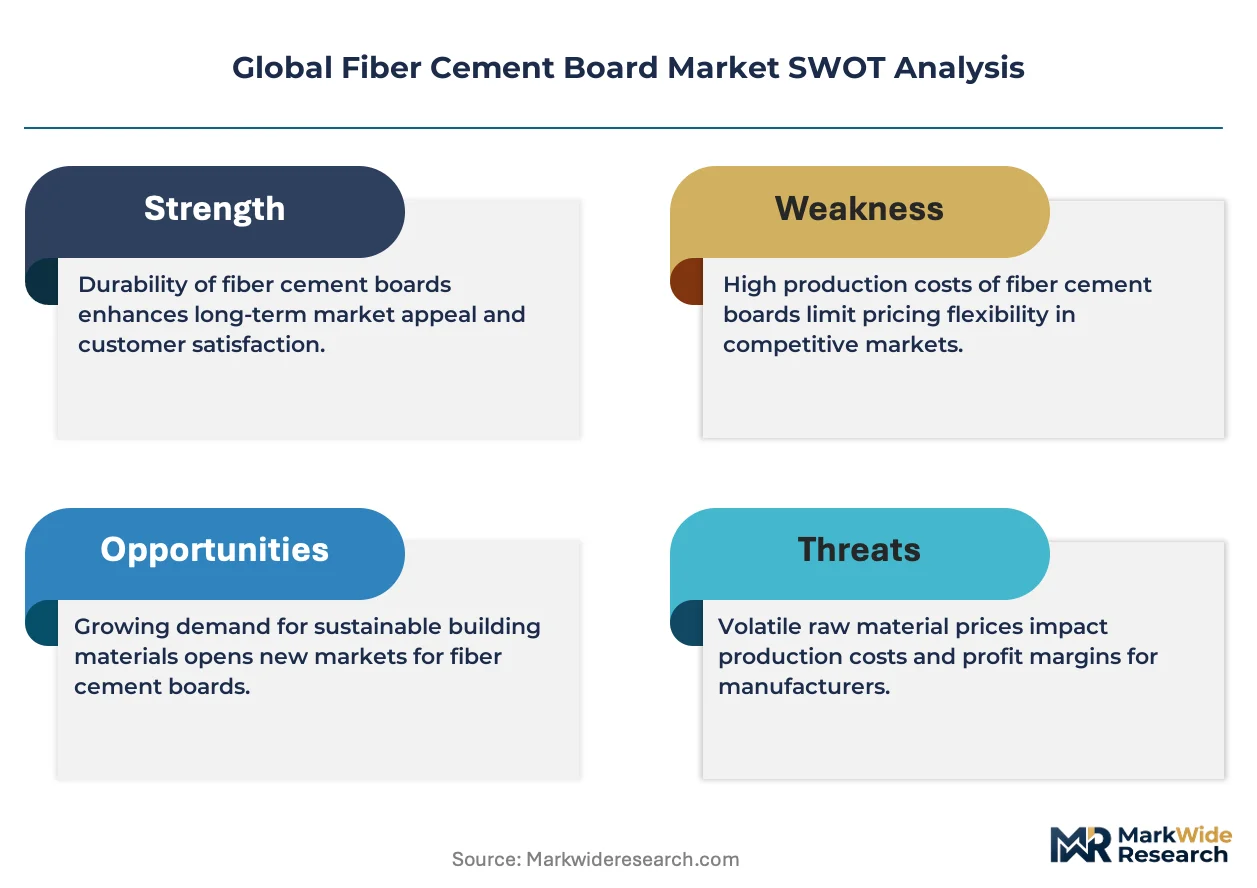
Sixty-to-ninety-day raw material inventory cycles in fiber cement board manufacturing tether pricing power directly to cellulose fiber sourcing control and Portland cement procurement timing. This lead-time band concentrates margin defense among suppliers with captive pulp operations while exposing import-dependent fabricators to energy cost pass-through volatility.
Pricing Analysis
REACH chemical compliance dictates the pricing tier structure across European fiber cement markets, separating EPD-certified premium formulations from standard-grade imports facing carbon-border adjustment exposure. Three-tier pricing structure across premium, standard, and economy levels aligns with fire-rating certification, wet-cutting factory capability, and embodied-carbon disclosure depth. Cost compression in economy-grade flat boards intensifies as Chinese clinker production faces MEE emissions enforcement and fuel price volatility. Residential siding contractors in North America exhibit highest price sensitivity, while commercial facade specifiers in Germany and Singapore prioritize compliance documentation over unit cost.
Supply Chain Analysis
China and India anchor Portland cement clinker production for fiber cement manufacturing, with Thailand and Vietnam hosting downstream board fabrication for Southeast Asian distribution. Raw material flows draw from Australian high-purity silica deposits, Brazilian pulp for cellulose fiber, and regional limestone for cement binders. Single-source vulnerability concentrates in cellulose fiber refining capacity controlled by integrated North American specialists. Distribution runs through construction merchant networks in developed markets and direct contractor relationships in high-growth Asian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital building information modeling platforms are reconfiguring fiber cement specification into an interoperability-driven ecosystem where parametric product data in Revit and Archicad libraries determines vendor inclusion before traditional sales engagement begins.
For Market Incumbents: Fortify captive cellulose fiber supply through backward integration into pulp refining or long-term offtake agreements with Australian and Brazilian suppliers. Expand wet-cutting factory capacity in Germany and the United States ahead of OSHA and REACH enforcement tightening. Certification investment in CSRD-aligned environmental product declarations secures public procurement eligibility as the EU Green Deal taxonomy hardens. For New Entrants and Emerging Players: Anchor in Indian smart city infrastructure programs where moisture-resistant cladding demand outpaces localized manufacturing capacity. Target prefabricated rainscreen assembly segments in Japan and South Korea where offsite construction adoption compresses traditional distribution channels. Go-to-market leverage rests on factory-finishing capabilities that eliminate field silica exposure for contractor compliance. For Investors and Strategic Acquirers: Carve-out targets emerge from regional cement conglomerates with underutilized downstream board fabrication assets in Southeast Asia and the Middle East. Five-to-ten-year viability hinges on carbon-intensity reduction trajectories and green bond financing access. The signal to watch is carbon-border adjustment implementation timing in European import frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Fiber | Captive pulp refining insulates James Hardie Industries from raw material volatility in North American siding markets. |
| Prefabricated Panel System Expansion | Factory-finished rainscreen assemblies capture Japanese public sector projects mandating OSHA-compliant installation protocols. |
| EPD Certification Investment | CSRD-aligned environmental product declarations unlock green bond financing for Etex Group's European retrofit positioning. |
| High-Density Nano-Silica R&D | Reduced-thickness panels penetrate Sydney curtain wall segments previously served by aluminum composite materials. |
| Smart City Distribution Partnerships | Localized Mumbai and Bangalore channel access secures SCG Building Materials' share in Indian urban corridor expansion. |
Methodological Framework
A standing panel of plant operations directors, commercial facade specifiers, construction procurement managers, and cellulose fiber supply specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade flow databases, SEC 10-K filings of listed building materials groups, OSHA enforcement action records, and ECHA REACH registration dossiers. Bottom-up volume modeling triangulated against top-down construction spend allocation across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including national construction material trade associations and regional cement consumption statistics. The analytical framework modeled product type, application segment, material composition, and installation method dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macro construction cycle intensity and regulatory compliance timeline assumptions.
Material uncertainties — Portland cement price volatility, carbon-border adjustment implementation sequencing, and engineered wood product fire-rating advancement — sit outside the modeled envelope. Forecasts reflect assumptions about OSHA enforcement trajectory and EU Green Deal taxonomy evolution. Recalibration cycles align with material shifts in clinker production energy costs and silica dust mitigation technology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Building Vibration Isolation Market