
 Africa Solar E-Bike Market | 2026-2036
Africa Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Solar E-Bike Market Analytics
Urban commercial fleet purchasing across Kampala, Dar es Salaam, and Kigali is consolidating around pay-as-you-go solar leasing models that lower capital barriers for motorcycle taxi operators. Spiro leverages West African assembly partnerships to control hardware costs and localize supply. Ampersand anchors East African operations with battery-swap infrastructure that reduces downtime for commercial riders. Roam competes through rugged frame designs engineered for unpaved road conditions prevalent across the continent.
Africa solar e-bikes integrate photovoltaic panels or dedicated solar charging stations with electric two-wheelers configured for 25-45 km/h assisted speeds and 50-150 km ranges per charge. These vehicles primarily serve commercial transport and urban mobility segments where liquid fuel price volatility and unreliable grid electricity create persistent operating cost pressure. City e-bikes dominate volume due to commuter density in Accra, Addis Ababa, and Dakar, while delivery services represent the fastest-expanding end user category as e-commerce logistics networks deepen penetration. Lithium-ion batteries command the technology segment through superior cycle life and declining cell prices, though lead acid retains residual share in price-sensitive rural microfinance schemes.
Kenya's Energy Regulatory Authority and Rwanda's Rwanda Utilities Regulatory Authority shape product standards through import duty exemptions for electric mobility and solar equipment. Nigeria's National Automotive Design and Development Council coordinates local content requirements that influence assembly location decisions. Stakeholders must monitor how carbon credit eligibility rules and green tariff structures across African electricity regulators affect total cost of ownership calculations for fleet operators evaluating solar e-bike deployment against conventional motorcycles.
Market Dynamics
Pay-as-you-go solar leasing models are compressing capital barriers for motorcycle taxi operators across East African urban corridors, fundamentally restructuring how commercial fleets acquire electric mobility assets.
Growth Catalysts
- Kenya's off-grid solar access programs:Government-backed rural electrification initiatives expand the addressable market for solar-charged two-wheelers beyond grid-connected urban centers.
- Falling lithium-ion battery costs:Cell price declines improve unit economics for fleet operators comparing total cost of ownership against petrol-powered motorcycles.
- Last-mile delivery expansion:E-commerce logistics networks in Lagos and Nairobi generate concentrated demand for solar e-bikes with 50-150 km daily range capabilities.
Market Restraints
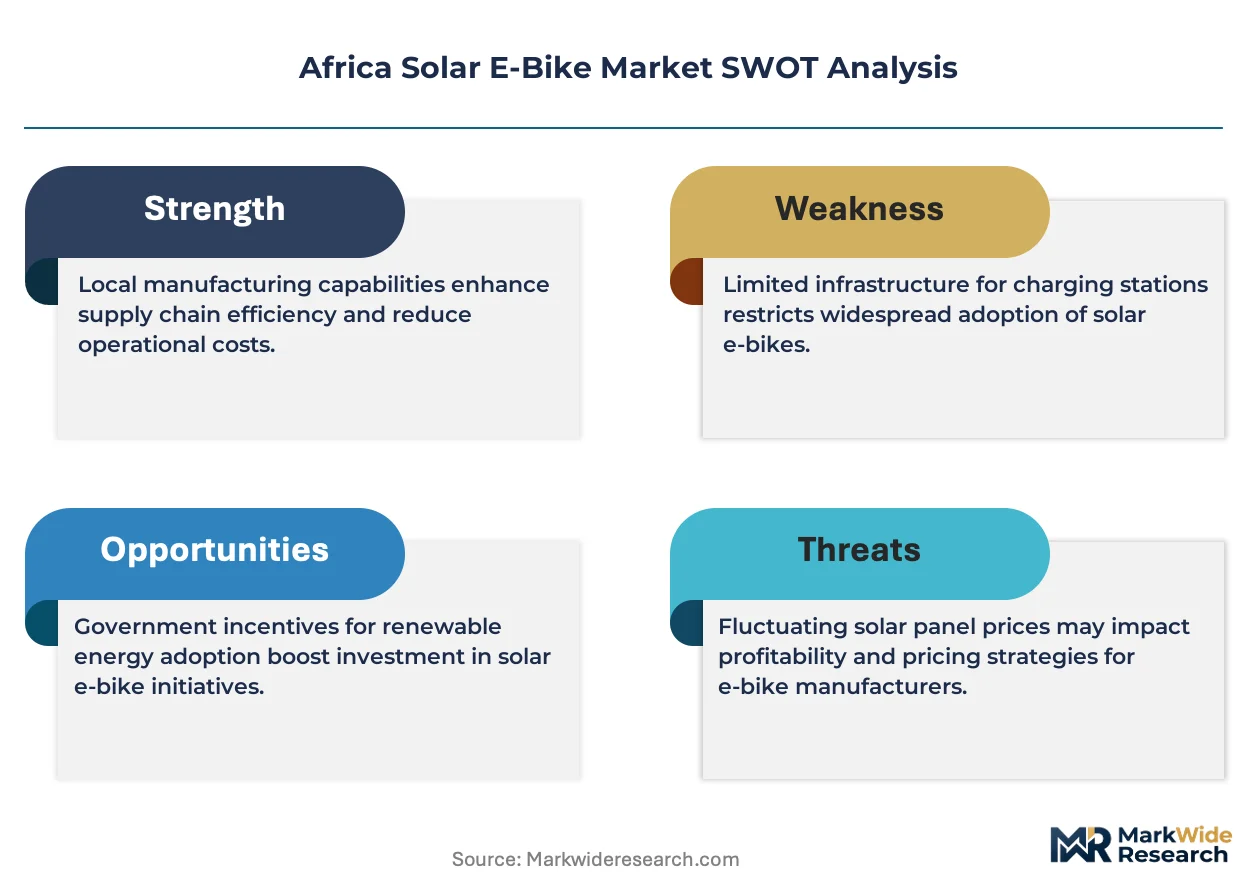
- Import duty complexity:Nigeria's National Automotive Design and Development Council local content requirements create assembly location friction and raise landed costs for fully-built units.
- Grid instability paradox:Unreliable electricity infrastructure that drives solar adoption simultaneously limits battery-swap station deployment density in secondary cities.
- Lead acid residual share:Price-sensitive rural microfinance schemes continue specifying heavier, shorter-cycle batteries that degrade vehicle performance and operator returns.
Strategic Opportunities
- Rwanda's regulatory tailwinds:Rwanda Utilities Regulatory Authority import duty exemptions for electric mobility and solar equipment create favorable total cost of ownership conditions for early fleet adopters.
- Battery-swap infrastructure convergence:Integration of photovoltaic charging stations with automated swap stations addresses downtime constraints for commercial riders in Kampala and Dar es Salaam.
- Unpaved road segment:Rugged frame engineering for rural transport applications opens penetration in agricultural logistics and remote healthcare delivery corridors.
Industry Challenges
- Technician training gaps:Shortage of certified lithium-ion battery diagnostics and solar panel maintenance skills limits after-sales service network expansion.
- Carbon credit verification timelines:Eligibility rules and green tariff structures across African electricity regulators remain unresolved, delaying fleet operator financing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Solar E-Bike Market |
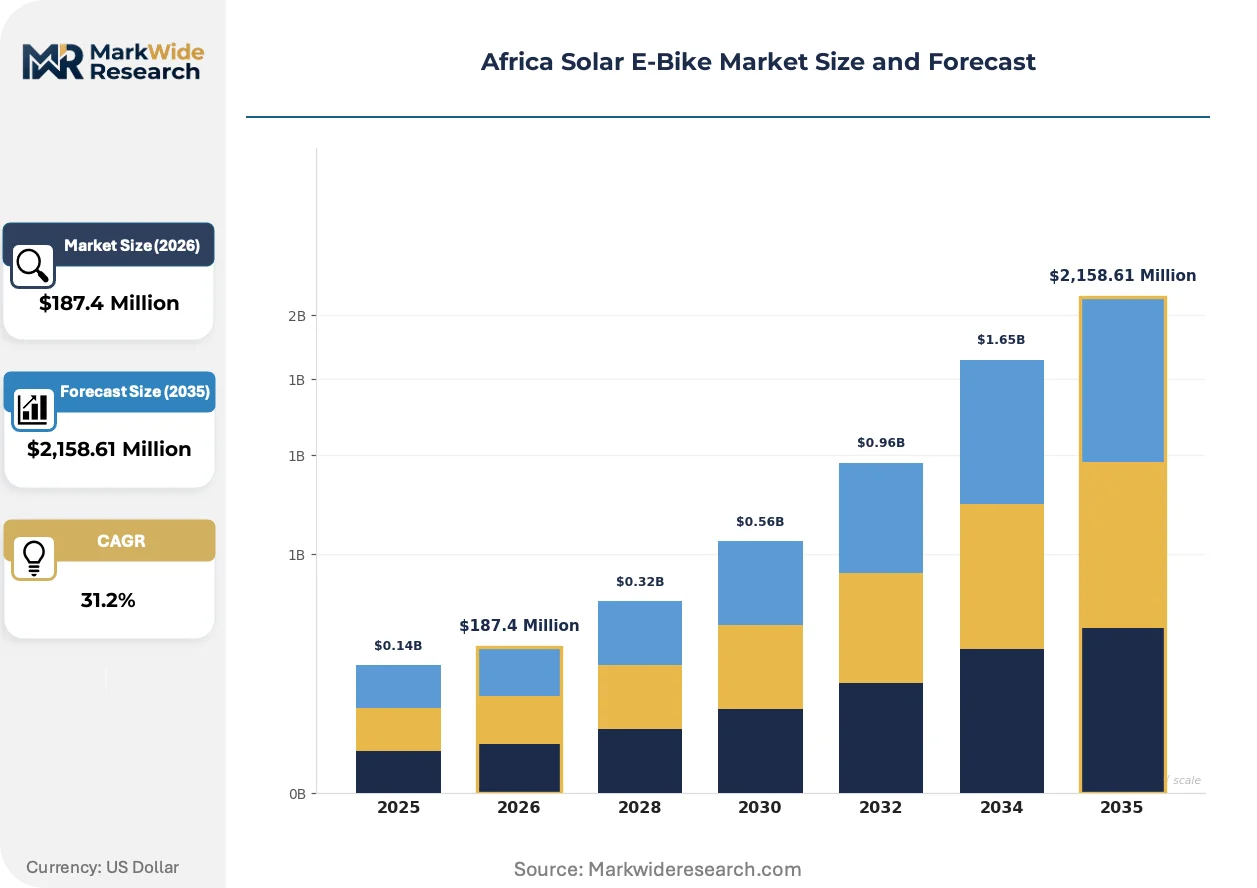
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,158.61 Million |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cruiser E-Bikes Battery Technology: Lithium-Ion, Lead Acid, Nickel-Cadmium, Solid State Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Commuters, Tourists, Delivery Services, Eco-Conscious Consumers |
| Companies Covered | Spiro, Roam, Ampersand, ARC Ride, Zembo, SolarTaxi, eBee, Kiri EV, Solar E-Cycles Kenya Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Solar E-Bike Market Evolving Landscape
Hardware localization and energy infrastructure unbundling are actively restructuring competitive positioning across the Africa solar e-bike value chain, with assembly partnerships and battery-swap networks emerging as distinct capability layers.
Solid-state battery prototyping is absorbing development resources from tier-one cell suppliers targeting tropical climate durability. Commercial fleet operators in Nairobi and Kampala are piloting these chemistries for improved thermal stability during rapid charging cycles. This technology trajectory is absorbing margin pressure from conventional lithium-ion commoditization while extending vehicle replacement cycles.
Kenya's Energy Regulatory Authority has finalized grid interconnection standards for solar charging stations that export surplus power, creating dual-revenue streams for fleet depot operators. This policy framework compresses payback periods for charging infrastructure investments. Motorcycle taxi cooperatives in Mombasa and Kisumu are restructuring capital deployment around these export-eligible station configurations.
Fleet procurement has consolidated around usage-based leasing contracts that unbundle vehicle ownership from battery responsibility. Commercial riders in Lagos and Accra are migrating from traditional hire-purchase arrangements toward per-kilometer battery subscriptions. This contract evolution is most visible among delivery services where downtime sensitivity exceeds capital ownership preferences.
Africa Solar E-Bike Market Segmentation
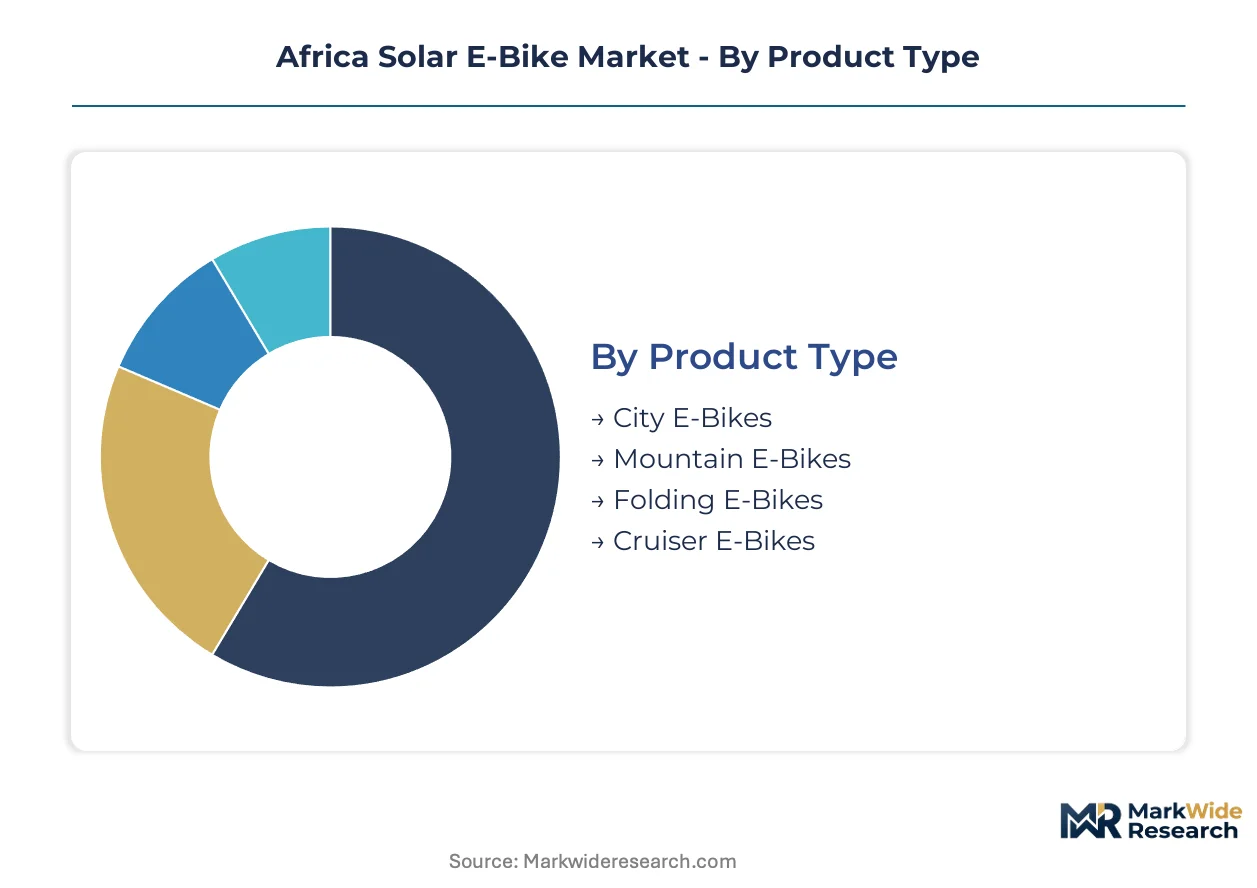
Product configuration and energy storage specifications determine how solar e-bike vendors address Africa's fragmented infrastructure conditions. Segmentation reveals where capital deployment concentrates across battery chemistries, distribution channels, and commercial use cases.
Product Type:
Frame geometry and wheelbase specifications map directly to road surface quality and rider payload requirements across African urban corridors.
- City E-Bikes:Step-through frames with 26-inch wheels and integrated rear racks dominate procurement from motorcycle taxi cooperatives in Nairobi and Lagos. These units prioritize low center of gravity for stop-start traffic and passenger carrying capacity.
- Mountain E-Bikes:Front suspension forks and reinforced chainstays absorb punishment on unpaved rural routes connecting agricultural collection points to paved highways. Demand clusters around cooperatives serving coffee and tea growing regions in Rwanda and Kenya's highlands.
- Folding E-Bikes:Hinge mechanisms and reduced wheel diameters suit intermodal commuters combining solar e-bike segments with informal minibus networks in Accra and Dakar.
- Cruiser E-Bikes:Upright seating positions and balloon tires target leisure rental fleets at coastal tourism destinations in Mombasa and Zanzibar.
Mature deployment sits with City E-Bikes. Newer deployment is concentrated in Mountain E-Bikes.
Battery Technology:
Cell chemistry selection governs total cost of ownership calculations where replacement cycles and thermal tolerance outweigh upfront capital outlays.
- Lithium-Ion:NMC and LFP cell formats deliver 800-1,500 cycle lifespans with superior energy density for 50-150 km daily ranges. Fleet operators in Kampala and Dar es Salaam specify these for commercial applications where downtime costs exceed battery replacement premiums.
- Lead Acid:Flooded and AGM variants persist in rural microfinance schemes across Nigeria's northern states due to lower entry prices and established recycling networks. Weight penalties and 300-500 cycle lifespans limit expansion beyond price-sensitive segments.
- Nickel-Cadmium:Military surplus and industrial backup cell repurposing supplies residual demand from institutional procurement in Ethiopia's Addis Ababa.
- Solid State:Prototyping programs with sulfide and oxide electrolyte formulations target tropical climate durability for rapid charging cycles in Nairobi pilot fleets.
Volume concentration rests with Lithium-Ion. Technology transition is accelerating fastest around Solid State.
Distribution Channel:
Customer acquisition economics and after-sales service reach determine channel selection across fragmented African retail infrastructure.
- Online Retail:Mobile money integration and WhatsApp-supported logistics enable direct-to-rider sales bypassing traditional dealer networks in Ghana and Senegal.
- Specialty Stores:Technical staff at dedicated electric mobility outlets in Kigali and Nairobi handle battery diagnostics and solar panel maintenance that generic retailers cannot support.
- Supermarkets:Mass retail penetration in South African urban centers exposes consumer-oriented models to grocery foot traffic.
- Direct Sales:Fleet procurement teams negotiate volume contracts with assembly partnerships for last-mile delivery operators in Lagos.
Established infrastructure sits with Specialty Stores. Channel expansion is broadening fastest through Online Retail.
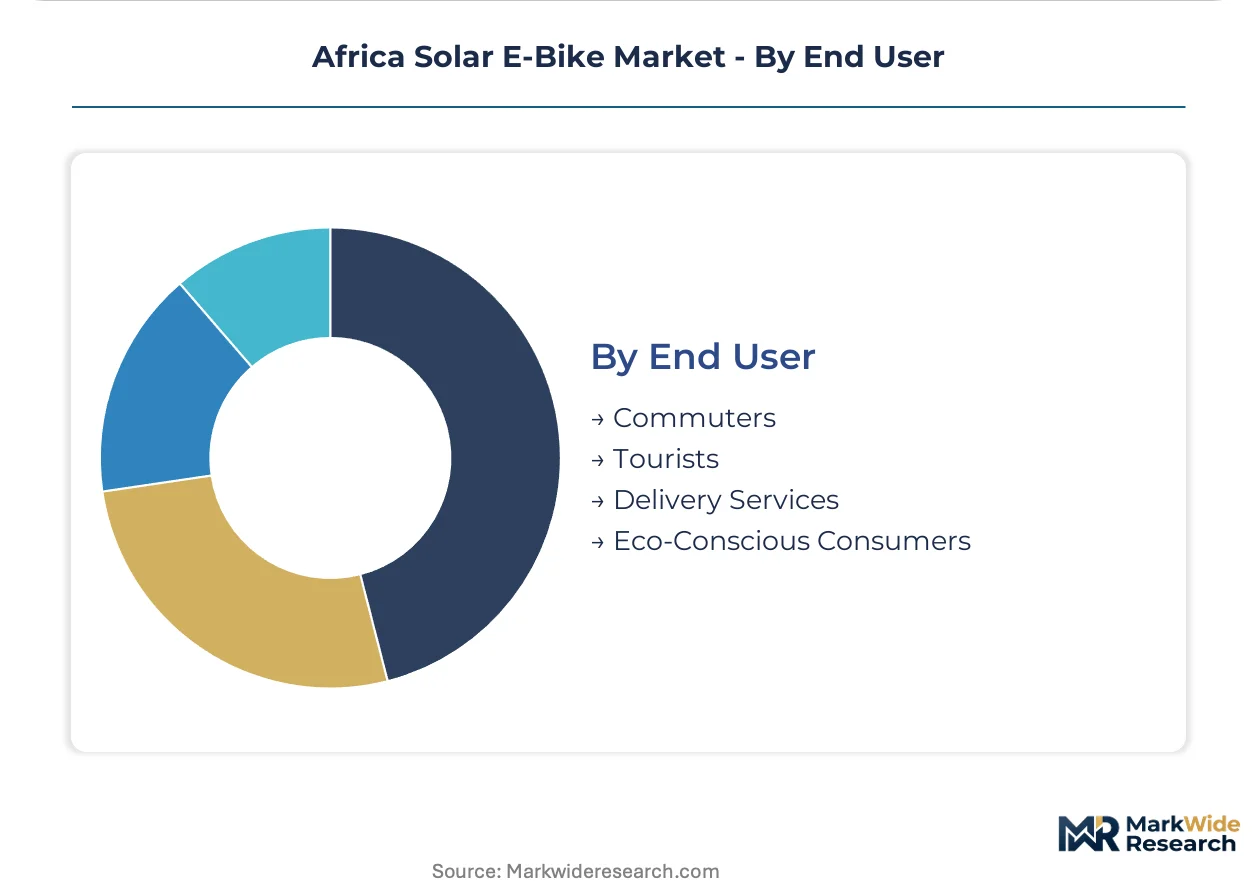
End User:
Rider economics and duty cycles segment demand across personal mobility, commercial transport, and institutional applications.
- Commuters:Daily 10-25 km trips on fixed routes in Addis Ababa and Dakar prioritize reliability and theft deterrence through integrated GPS tracking.
- Tourists:Short-term rental demand at Victoria Falls and Serengeti gateway towns emphasizes ease of operation and photographic appeal.
- Delivery Services:E-commerce logistics networks in Lagos and Nairobi generate concentrated procurement for 100+ km daily range configurations with swappable battery architectures.
- Eco-Conscious Consumers:Carbon offset eligibility and green tariff participation drive adoption among salaried professionals in Rwanda's Kigali.
Commercial maturity sits with Delivery Services. Volume expansion is climbing fastest among Commuters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Zimbabwe's Bikita and Arcadia mines anchor East African battery supply chains. Cobalt from the Democratic Republic of Congo feeds cathode production. These mineral localities shape where solar e-bike assembly and battery-pack manufacturing concentrate.
Kenya
Last-mile delivery cooperatives in Nairobi and Mombasa drive fleet procurement for solar-charged two-wheelers. Kenya's Energy Regulatory Authority finalized grid interconnection standards allowing charging stations to export surplus power. Motorcycle taxi operators in Kisumu are restructuring capital deployment around these dual-revenue station configurations.
Nigeria
Petrol price volatility and grid instability in Lagos generate concentrated demand from delivery services seeking operational cost predictability. The National Automotive Design and Development Council coordinates local content requirements that influence assembly location decisions. Commercial riders in Ibadan and Kano are migrating from hire-purchase arrangements toward per-kilometer battery subscriptions.
Rwanda
Motorcycle taxi cooperatives in Kigali consolidate procurement around pay-as-you-go solar leasing models. Rwanda Utilities Regulatory Authority maintains import duty exemptions for electric mobility and solar equipment. Battery-swap infrastructure deployment concentrates along the Northern Corridor connecting Kigali to Musanze.
Ghana
E-commerce logistics networks in Accra generate demand for city e-bikes with integrated rear racks and GPS tracking. The country's national energy regulator shapes product standards through grid interconnection rules for solar charging installations. Delivery fleet operators in Kumasi and Tamale pilot rugged frame configurations for intercity agricultural logistics.
Uganda
Commercial transport cooperatives in Kampala prioritize battery-swap architectures to minimize rider downtime. The country's utilities regulatory framework influences total cost of ownership calculations through electricity tariff structures. Solar charging station deployment clusters along the Kampala-Jinja corridor serving boda-boda operator networks.
Africa Solar E-Bike Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-swap infrastructure and pay-as-you-go financing innovations. The vendor base spans West African assembly partnerships, East African battery-swap operators, and rugged-frame specialists targeting unpaved road segments. Three archetypes dominate: hardware localizers controlling landed costs through regional assembly, energy infrastructure operators unbundling battery ownership from vehicle sales, and durability-focused engineers optimizing for rural terrain conditions. Geographic expansion and strategic partnerships constitute the dominant competitive moves as players seek regulatory alignment across national markets.
Within the hardware localization tier, Spiro and Roam exemplify divergent strategic positions. Spiro leverages West African assembly partnerships to control supply chain costs. Roam occupies a position anchored in rugged frame engineering for unpaved road conditions prevalent across East African agricultural corridors. Ampersand represents the energy infrastructure archetype, anchoring East African operations through battery-swap networks that reduce commercial rider downtime.
| Leading Market Players |
|---|
| Spiro |
| Roam |
| Ampersand |
| ARC Ride |
| Zembo |
| SolarTaxi |
| eBee |
| Kiri EV |
| Solar E-Cycles Kenya Ltd |
| Others |
Value Network & Pricing Analysis
Captive assembly partnerships in West Africa anchor supply positioning while compressing landed costs for fleet operators negotiating volume contracts. This integration choice concentrates pricing power with regional assemblers who control duty-exempt kit imports and local labor arbitrage, leaving pure traders exposed to Nigeria's National Automotive Design and Development Council content requirements.
Pricing Analysis
Warranty bundling separates premium fleet contracts from economy retail sales, with commercial operators securing 24-month battery replacement guarantees against individual buyers absorbing cell risk. Three-tier pricing structure across premium, standard, and economy levels reflects lithium-ion grade differentiation and swap-station access rights. Cost compression in the economy tier is intensifying because lead-acid residual demand from rural microfinance schemes forces price-matching. Delivery services exhibit lowest price sensitivity due to downtime cost calculus, while commuter segments prioritize capital outlay minimization.
Supply Chain Analysis
Freight cost differentials between containerized kit imports and fully-built unit shipping favor Nigerian and Ghanaian assembly hubs over direct China-to-end-user routes. Zimbabwe's Bikita lithium and DRC cobalt feed East African battery pack production, while frame components source from Chinese aluminum extruders. Single-source vulnerability concentrates in cathode precursor supply from Congolese mining cooperatives. Distribution runs through motorcycle taxi cooperative bulk procurement rather than individual retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cell manufacturing capacity constraints across African pack assembly facilities prop pricing premiums for fleet operators, creating a supply-constrained market structure favoring early offtake agreements.
For Market Incumbents: Deploy pay-as-you-go financing platform extensions to lock cooperative procurement relationships before emerging entrants replicate the model. Secure backward integration into lithium cell supply through offtake partnerships with Zimbabwean mining operators. Battery-swap infrastructure saturation in Kampala and Kigali represents the primary competitive threat requiring preemptive station density investment. For New Entrants and Emerging Players: Agricultural logistics cooperatives serving unpaved rural corridors remain underserved by current durability-optimized offerings. Rwanda's duty-exempt import regime offers the most penetrable regulatory entry point. Direct sales teams targeting regional e-commerce fulfillment centers bypass established dealer network dependencies. For Investors and Strategic Acquirers: Exit pathways concentrate in battery-swap infrastructure roll-ups and captive assembly facility acquisitions. Long-term viability hinges on 5-10 year lithium price trajectory stability and regulatory persistence of green tariff structures. Watch Kenya Energy Regulatory Authority grid interconnection standard expansion as inflection indicator for charging station revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Swap Station Network Expansion | Ampersand's East African density investments reduce commercial rider downtime below petrol refueling intervals. |
| West African Assembly Localization | Spiro's Nigerian partnerships circumvent National Automotive Design and Development Council content friction. |
| Rugged Frame Engineering | Roam's agricultural corridor positioning captures unpaved road segments ignored by urban-optimized competitors. |
| Solid-State Battery Piloting | Nairobi fleet trials validate tropical climate durability for next-generation thermal management. |
| Grid Interconnection Compliance | Kenya Energy Regulatory Authority export-eligible stations create dual-revenue streams compressing infrastructure payback. |
Research Methodology
Multi-period observation of fleet procurement volumes, battery-swap station deployment density, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with motorcycle taxi cooperative managers, last-mile delivery logistics directors, lithium mining procurement officers, and East African energy regulatory staff. Secondary validation drew from Kenya Energy Regulatory Authority interconnection standards, Rwanda Utilities Regulatory Authority duty exemption schedules, Nigeria National Automotive Design and Development Council local content guidelines, and customs import data. Bottom-up unit economics modeling triangulated against top-down addressable market sizing.
Input-output matrices mapped lithium cell cost trajectories, solar panel efficiency curves, and fleet operator total cost of ownership sensitivity across product type, battery chemistry, distribution channel, and end-user segmentation dimensions. CAGRs derived from regression analysis of historical procurement growth rates applied to projected infrastructure investment cycles. Modeled inputs incorporated Kenya's off-grid solar access program expansion schedules and Lagos e-commerce logistics network penetration curves.
Revisions become necessary when lithium supply disruptions from Zimbabwean mining operations, regulatory withdrawal of electric mobility duty exemptions, or solid-state battery commercialization timelines materially diverge from baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Ocean Power Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Europe Ocean Power Market