
 Renewable Energy Policy Fit Analysis Market | 2026-2036
Renewable Energy Policy Fit Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Policy Fit Analysis Market Analysis
Utility-scale solar development is repositioning policy fit analysis from a peripheral planning exercise to a core investment gate. McKinsey & Company leverages its energy practice network to anchor large-scale due diligence mandates across emerging markets. Deloitte competes through integrated tax and regulatory modules that sustain client retention in complex incentive environments. Wood Mackenzie differentiates via proprietary LCOE datasets that dominate upstream policy scenario modeling.
Renewable energy policy fit analysis evaluates the alignment between project-specific characteristics and applicable regulatory mechanisms to optimize financial returns and compliance outcomes. The discipline integrates technology performance parameters, incentive eligibility windows, and jurisdictional rule sets into unified decision frameworks for capital allocation. Feed-in tariff segments retain mature margin pools in European markets where contract-for-difference transitions demand continuous reassessment. Solar power and wind energy categories lead technology-based demand as interconnection standards tighten across major grids. Government agencies and utilities represent the fastest-growing stakeholder channels as public procurement incorporates climate conditionality into tender design.
The US Inflation Reduction Act, administered through Treasury and IRS guidance, shapes domestic content calculations that determine bonus credit eligibility for developers. EU Green Deal implementation through national recovery plans mandates regular policy fit reviews as member states adjust renewable support schemes. India's PLI scheme for solar manufacturing, overseen by MNRE and CEA, creates parallel analysis demand for domestic supply chain qualification. Stakeholders must monitor how carbon border adjustment mechanisms in Europe and prospective US analogues alter the effective value of clean energy certificates across trade-exposed industries.
Market Dynamics
Interconnection queue congestion is compressing project timelines and forcing developers to front-load policy fit assessments before land acquisition. Grid operators in high-growth markets now require policy compliance documentation at preliminary scoping stages, embedding regulatory analysis into earliest capital commitment decisions.
Growth Catalysts
- US IRA domestic content bonuses:Treasury guidance on qualifying domestic manufacturing is creating urgent recalculation demand across solar and storage project pipelines. Developers require continuous policy fit updates as safe harbor rules evolve.
- Feed-in tariff transitions:Germany's shift from EEG feed-in tariffs to market premium models forces existing asset owners into contract-for-difference reassessment. Continuous compliance monitoring sustains recurring advisory revenue.
- Offshore wind leasing:Bureau of Ocean Energy Management lease rounds in the US Atlantic incorporate increasingly complex community benefit and labor standard requirements. Policy fit tools parse layered eligibility conditions.
Market Restraints
- Specialized talent scarcity:Cross-functional expertise spanning tax equity, interconnection engineering, and jurisdictional regulatory history concentrates among senior practitioners at major consultancies. Mid-tier advisory firms face recruitment bottlenecks.
- Data licensing costs:Proprietary LCOE and interconnection queue datasets from established research providers command premium subscription fees. Independent developers cannot internalize equivalent analytical capabilities.
- Jurisdictional fragmentation:India's state-level electricity regulatory commissions maintain divergent open access and banking regulations. National policy frameworks require localized interpretation that resists standardization.
Strategic Opportunities
- Brazil distributed generation:Prosumag regulatory framework expansion into commercial and industrial segments creates policy fit demand among mid-scale installers previously served by simple net metering calculators.
- Green hydrogen offtake:EU Green Deal hydrogen bank auctions and US H2Hubs program introduce novel production tax credit stacking analysis. Electrolyzer developers need integrated policy fit across power, fuel, and carbon credit regimes.
- Carbon border adjustment alignment:Embedded emissions accounting for EU CBAM-covered imports is forcing trade-exposed manufacturers to verify renewable energy certificate provenance. Policy fit tools extend into supply chain Scope 2 verification.
Industry Challenges
- Model validation complexity:Policy scenario outputs require continuous backtesting against actual regulatory implementation, yet historical precedent for novel mechanisms like hydrogen production credits remains thin. Analytical credibility depends on proprietary judgment rather than empirical calibration.
- Client data integration:Developer ERP systems and interconnection application portals use non-standard data formats. Policy fit platforms face substantial implementation friction extracting project-specific parameters from fragmented source systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Policy Fit Analysis Market |
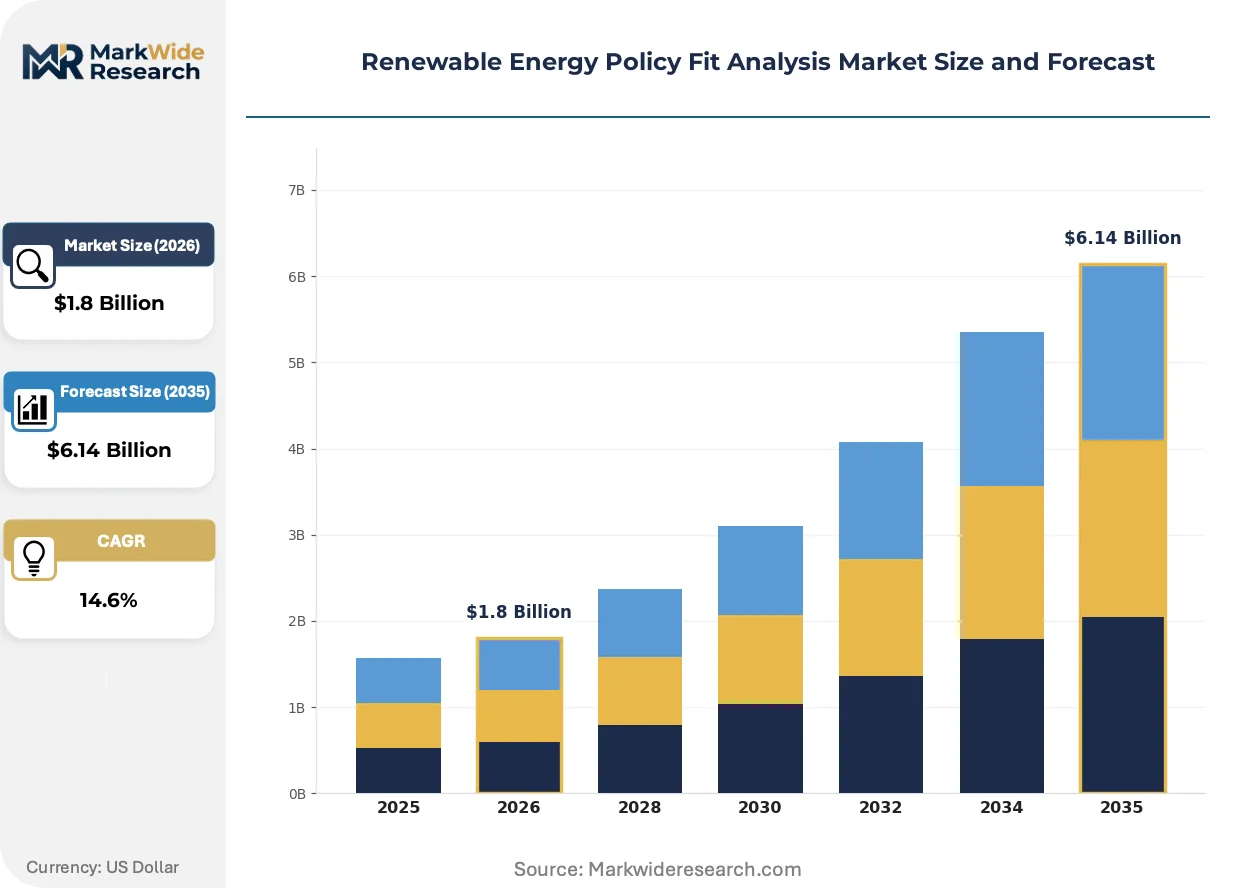
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Feed-in Tariffs, Tax Incentives, Renewable Portfolio Standards, Green Certificates Technology: Solar Power, Wind Energy, Biomass, Hydropower Stakeholder: Government Agencies, Private Investors, Non-Governmental Organizations, Utilities Implementation Stage: Proposal, Development, Active, Review |
| Companies Covered | McKinsey & Company, PwC, Deloitte, Accenture, Ernst & Young, Siemens AG, Schneider Electric, ABB Ltd., Wood Mackenzie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Policy Fit Analysis Market Emerging Trajectories
Artificial intelligence is compressing scenario generation timelines and enabling real-time policy monitoring across fragmented regulatory landscapes. Machine learning models trained on historical incentive modifications now flag proposed rule changes for client alert systems.
Cloud-native policy fit platforms are decentralizing analytical access from centralized consulting engagements to distributed developer teams. Mid-scale independent power producers in Texas and California now run self-service domestic content calculations through browser-based interfaces. Treasury's evolving safe harbor guidance propagates through automated update feeds rather than manual advisory memoranda.
The EU Green Deal's delegated acts on renewable fuels of non-biological origin are forcing cross-border project developers into multi-jurisdictional compliance mapping. Electrolyzer developers in Spain and Portugal must simultaneously satisfy national recovery plan conditions, hydrogen bank auction requirements, and prospective RED III implementation. Policy fit analysis is expanding from single-project optimization to portfolio-level regulatory arbitrage across member state schemes.
Corporate renewable energy buyers are consolidating procurement decisions under centralized sustainability functions with direct policy expertise. Large technology companies in Ireland and the Netherlands now embed regulatory analysts within power purchase agreement negotiation teams rather than outsourcing to external advisors. This capability internalization is compressing traditional advisory margins while elevating demand for specialized software licensing.
Renewable Energy Policy Fit Analysis Market Segmentation
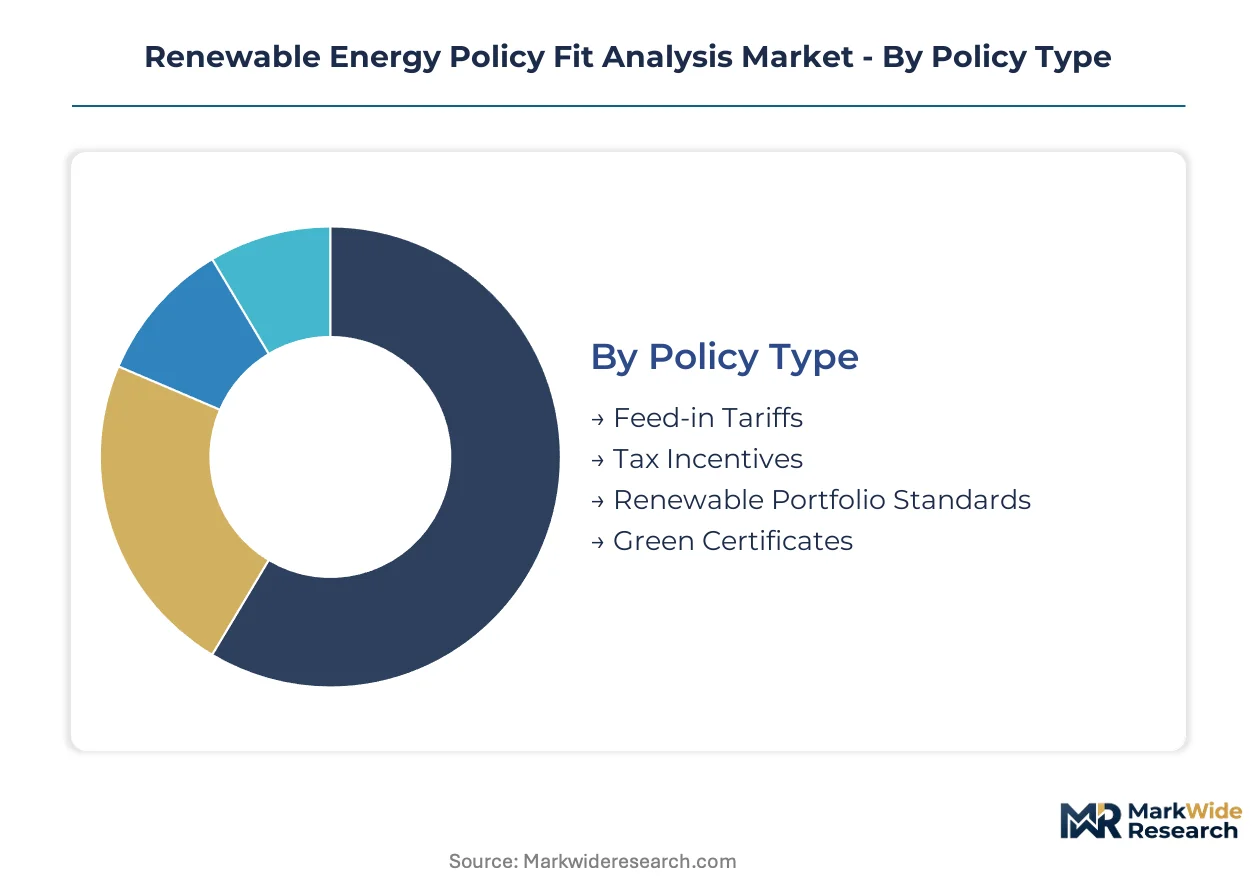
Policy fit analysis demand fragments across regulatory mechanism types, generation technologies, and implementation phases. Each segmentation axis reveals distinct capability requirements and margin structures for advisory providers.
Policy Type:
Supply concentration clusters around mechanisms with the most complex eligibility verification requirements.
- Feed-in Tariffs:Long-term purchase agreements at administratively set prices dominate European market analysis. Germany's EEG contract-for-difference transitions sustain continuous compliance monitoring mandates among existing asset owners.
- Tax Incentives:Investment and production credits require layered domestic content calculations. The US Treasury's evolving safe harbor guidance on IRA bonus eligibility forces iterative recalibration across solar and storage pipelines.
- Renewable Portfolio Standards:Compliance obligation markets in US states and Canadian provinces create recurring verification demand. Load-serving entities purchase bundled or unbundled renewable energy certificates to meet mandated percentages.
- Green Certificates:Voluntary and compliance-grade certificate systems require provenance tracking and retirement verification. EU Guarantees of Origin and North American REC markets operate under divergent issuance and tracking protocols.
Feed-in Tariffs absorb the bulk of installed capacity; Tax Incentives are expanding most quickly.
Technology:
Application complexity scales with interconnection standards and equipment qualification requirements.
- Solar Power:Photovoltaic and concentrating solar projects face bifacial module classification disputes and inverter efficiency tiering. India's PLI scheme for domestic cell and module manufacturing creates parallel supply chain qualification analysis.
- Wind Energy:Onshore and offshore turbine configurations trigger distinct grid code compliance pathways. Bureau of Ocean Energy Management lease rounds in the US Atlantic incorporate community benefit and labor standard conditions that layer onto base incentive eligibility.
- Biomass:Feedstock sustainability certification and emissions accounting requirements differentiate eligible installations. Combined heat and power configurations complicate renewable energy certificate allocation between thermal and electrical outputs.
- Hydropower:Run-of-river and pumped storage projects navigate divergent treatment under national renewable energy definitions. Small-scale exemptions from licensing requirements create threshold analysis demand.
Solar Power dominates current advisory volume; Wind Energy shows the steepest expansion trajectory as offshore leasing accelerates.
Stakeholder:
Customer type determines analytical depth and engagement duration.
- Government Agencies:Public procurement offices integrate climate conditionality into tender design. National recovery plan implementation across EU member states requires continuous scheme adjustment and impact assessment.
- Private Investors:Infrastructure funds and tax equity participants demand integrated regulatory and financial due diligence. Project finance lenders require policy risk documentation at term sheet stage.
- Non-Governmental Organizations:Advocacy groups and certification bodies monitor compliance integrity and environmental additionality. Corporate renewable energy buyers verify supply chain Scope 2 claims against evolving certificate standards.
- Utilities:Vertically integrated and unbundled utilities manage compliance portfolios across multiple jurisdictions. Grid operators in high-growth markets now require policy documentation at preliminary interconnection scoping.
Utilities anchor recurring revenue streams; Government Agencies are gaining share fastest as public procurement expands.
Implementation Stage:
Margin profiles shift from advisory intensity to platform licensing as projects mature.
- Proposal:Early-stage feasibility studies assess multiple policy scenarios against preliminary project parameters. Developers front-load analysis before land acquisition commitments.
- Development:Final investment decision support requires locked incentive applications and interconnection agreements. Data rooms incorporate regulatory risk matrices for lender review.
- Active:Operational assets require continuous compliance monitoring and periodic recertification. Feed-in tariff transitions and incentive reauthorization deadlines sustain recurring advisory relationships.
- Review:Asset repowering and ownership transfer trigger fresh policy fit assessments. M&A due diligence examines historical compliance and future eligibility windows.
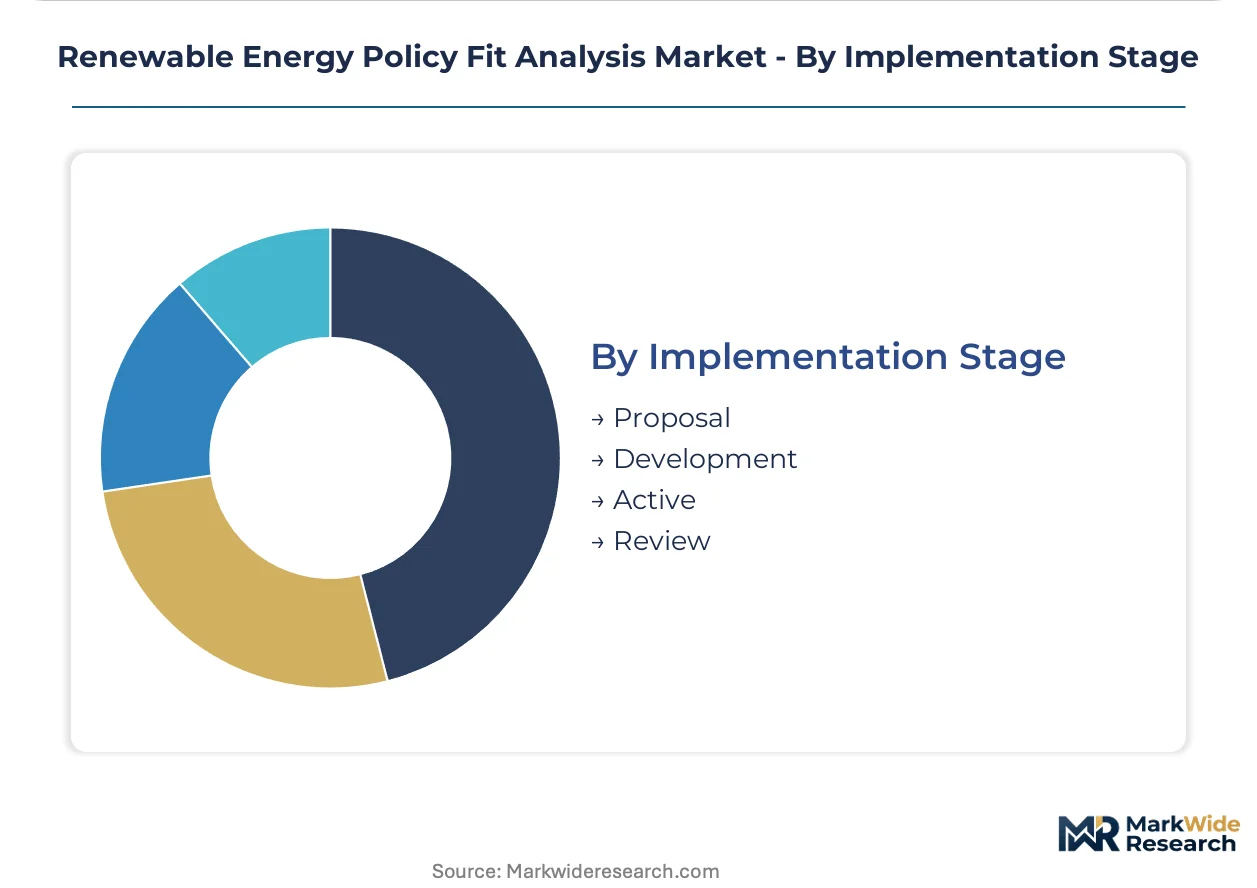
Active stage generates the largest installed base; Development stage is climbing the fastest as queue congestion compresses timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones and tax-incentive corridors are concentrating policy fit analysis demand in jurisdictions with layered regulatory frameworks. Treasury-administered zones in the United States, EU recovery plan implementation areas, and India's manufacturing clusters each generate distinct analytical requirements.
United States
Domestic content bonus calculations under Treasury and IRS guidance are reshaping solar and storage project economics. Developers in Texas and California front-load policy assessments before interconnection queue commitments. The Bureau of Ocean Energy Management's Atlantic lease rounds incorporate community benefit conditions that layer onto base incentive eligibility.
Germany
Feed-in tariff transitions under the EEG framework sustain continuous compliance monitoring among existing asset owners. The shift from administratively set prices to market premium models forces contract-for-difference reassessment. Industrial clusters in North Rhine-Westphalia and Bavaria anchor advisory demand as manufacturing facilities verify renewable energy certificate provenance.
India
The PLI scheme for solar manufacturing overseen by MNRE and CEA creates parallel supply chain qualification analysis. State-level electricity regulatory commissions maintain divergent open access regulations that resist standardization. Gujarat and Maharashtra host the densest concentrations of policy fit advisory as developers navigate banking and wheeling charges across jurisdictions.
Brazil
Prosumag regulatory framework expansion into commercial and industrial segments creates demand among mid-scale installers. Distributed generation growth in São Paulo and Minas Gerais outpaces simple net metering calculator capabilities. ANEEL's evolving grid code requirements embed regulatory analysis into preliminary project scoping.
United Kingdom
Contract-for-difference auction rounds under the Department for Business, Energy and Industrial Strategy require continuous eligibility verification. Offshore wind leasing in Scottish waters incorporates increasingly complex supply chain and labor conditions. London-based sustainability teams at technology companies are internalizing policy expertise previously outsourced to advisors.
Renewable Energy Policy Fit Analysis Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one consultancies anchoring complex due diligence while software platforms capture recurring licensing revenue. The vendor base concentrates among entities with proprietary datasets and jurisdictional regulatory history. Three archetypes dominate: integrated professional services networks, specialized energy research providers, and technology-enabled platform vendors. Competitive moves center on strategic partnerships with grid operators and vertical integration into data acquisition capabilities.
Within the integrated advisory tier, McKinsey & Company and Deloitte exemplify divergent positioning strategies. McKinsey leverages its energy practice network to anchor large-scale mandates, while Deloitte competes through integrated tax and regulatory modules. Wood Mackenzie occupies a distinct position as a research-native provider with proprietary LCOE datasets that dominate upstream policy scenario modeling. These three entities represent the spectrum from relationship-driven consulting to data-centric platform delivery.
| Leading Market Players |
|---|
| McKinsey & Company |
| PwC |
| Deloitte |
| Accenture |
| Ernst & Young |
| Siemens AG |
| Schneider Electric |
| ABB Ltd. |
| Wood Mackenzie |
| Others |
Supply Flow & Price Mechanics
Cross-functional regulatory talent concentration in London, Washington DC, and New Delhi creates labor-cost differentials that widen pricing-tier spreads between boutique specialists and platform-native vendors. Treasury guidance velocity on IRA domestic content bonuses forces continuous model recalibration, embedding labor intensity into premium-tier SaaS subscriptions.
Pricing Analysis
Short lead-time delivery commands premium positioning as developers facing interconnection queue compression require same-day policy scenario outputs. Three-tier pricing structure across premium, standard, and economy levels segments by analytical depth and update frequency. Price differentiation rests on proprietary LCOE dataset integration and jurisdictional regulatory history depth. Cost compression in the economy tier intensifies as cloud-native platforms automate baseline calculations. Mid-scale independent power producers exhibit highest price sensitivity; infrastructure funds and tax equity participants demonstrate lowest elasticity due to compliance failure costs.
Supply Chain Analysis
Freight cost pass-through from proprietary data licensing agreements concentrates analytical input costs among United States, United Kingdom, and Singapore headquarters of major research providers. Raw material dependencies span satellite-derived interconnection queue data, regulatory filing databases, and equipment qualification test results. Supply chain risk centers on single-source vulnerability for granular LCOE benchmarks tied to specific technology configurations. Distribution runs through direct enterprise sales for integrated advisory engagements and self-service browser interfaces for platform licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where proprietary data acquisition and in-house regulatory expertise determine margin sustainability. Players are pursuing backward integration into interconnection queue monitoring and equipment test result databases.
For Market Incumbents: Cement data exclusivity through captive agreements with grid operators and equipment certification bodies. Incumbents should lock long-term licensing arrangements with FERC and EIA data sources before emerging platforms achieve equivalent coverage. Threat substitution from AI-native scenario generation tools demands continuous model validation investment to preserve analytical credibility. For New Entrants and Emerging Players: Launch via white-label API distribution to ERP and interconnection application portal providers. Brazil's Prosumag framework expansion and India's state-level banking regulation divergence represent the most penetrable geographies for mid-tier SaaS positioning. Go-to-market angle should emphasize rapid deployment against fragmented jurisdictional interpretation requirements. For Investors and Strategic Acquirers: Re-rating potential sits with specialized energy research providers given recurring revenue conversion from advisory to platform licensing. Long-term viability favors entities with embedded regulatory history spanning multiple incentive regime transitions. Acquisition target archetype: mid-scale consultancies with dense MNRE, Treasury, or EU recovery plan practitioner networks. Signal to watch is corporate sustainability function internalization velocity compressing traditional advisory margins.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Data Acquisition | Captive LCOE datasets from Wood Mackenzie anchor upstream policy scenario modeling against generic benchmarks. |
| Platform Licensing Expansion | Cloud-native interfaces displace centralized consulting engagements among Texas and California developer teams. |
| Regulatory History Integration | Dense practitioner networks spanning Treasury, MNRE, and EU recovery plans sustain recurring compliance monitoring revenue. |
| AI-Native Scenario Generation | Machine learning models trained on historical incentive modifications enable real-time policy monitoring across fragmented landscapes. |
| Vertical Capability Buildout | Backward integration into interconnection queue databases reduces dependency on premium third-party data subscriptions. |
Methodological Framework
Independent corroboration across utility planning officers, IPP project developers, and grid operators underwrites the qualitative findings on interconnection queue compression impacts. Secondary validation draws from EIA project databases, FERC interconnection filings, IEA renewable policy tracking, and national regulatory commission dockets. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates policy mechanism transitions, technology cost trajectories, and stakeholder capability maturation across the modeling period. Segmentation dimensions span regulatory framework type, generation technology, project implementation stage, and regional grid interconnection standards. CAGRs derive from fitted trend extrapolation against historical incentive modification patterns and equipment deployment velocities. Forecast inputs incorporate Treasury safe harbor guidance evolution velocity and EU Green Deal delegated act implementation sequencing.
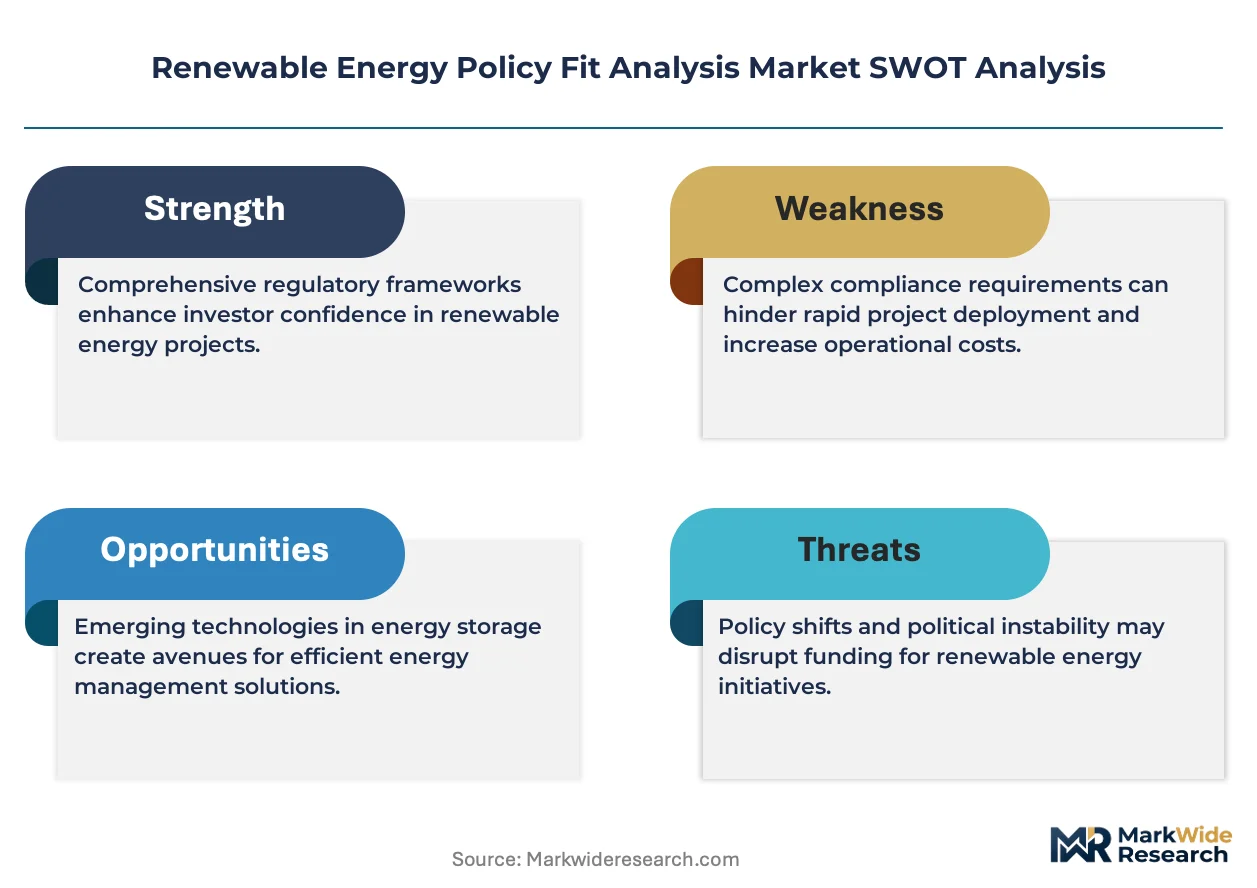
IRA guidance revision, EU recovery plan reallocation, and CBAM implementation delays are the dominant revision risks to installed base projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market