
 New Zealand Renewable Energy Market | 2026-2036
New Zealand Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Renewable Energy Market Foresight
Modular solar-plus-storage bundling is pivoting how commercial buyers evaluate project economics. Meridian Energy leverages its South Island hydro fleet to anchor bundled firm supply contracts. Contact Energy competes through geothermal baseload integration with intermittent renewables. Genesis Energy navigates the shift from thermal baseload to flexible peaking as its Huntly units transition.
New Zealand renewable energy encompasses electricity generated from solar photovoltaic, onshore wind, run-of-river and pumped hydro, and woody biomass combustion with typical utility-scale solar arrays ranging from 10 MW to 150 MW and wind turbines rated at 2-4 MW. Its primary commercial purpose is to displace fossil-fuel generation while maintaining grid stability across an isolated island system with limited interconnection. Hydro technology dominates installed capacity and revenue pools due to decades of capital deployment, yet solar deployment is expanding fastest among new build as falling module costs and distributed generation tariffs improve project returns. Application segmentation reveals power generation commanding the largest share of investment, while energy storage applications are attracting disproportionate capital as grid-scale batteries address the dry-year hydro risk that shapes New Zealand's security-of-supply framework.
The Electricity Authority governs wholesale market design and connection standards, while the Commerce Commission regulates Transpower New Zealand's transmission pricing methodology that shapes generator locational decisions. Resource Management Act reform and National Policy Statements for Renewable Electricity Generation streamline consent pathways for wind and solar projects. Stakeholders must monitor how the Resource Management Act replacement legislation alters consent timelines and whether the Climate Change Commission's carbon budgets tighten faster than grid infrastructure can accommodate new renewable capacity.
Market Dynamics
The Electricity Authority's market-making reforms are compressing wholesale price volatility while Transpower's grid investment incentives reroute generator locational decisions toward constrained nodes. This regulatory-technical interplay is restructuring how renewable developers sequence project commitments.
Growth Catalysts
- Transpower transmission pricing methodology:The Commerce Commission's regulated framework rewards generation investment in grid-constrained regions, redirecting capital toward the Auckland-Tauranga corridor where load growth outpaces infrastructure.
- Industrial power purchase agreements:Large commercial offtakers are contracting firm renewable supply directly, bypassing traditional retail channels and underwriting long-dated project finance.
- Distributed generation tariffs:Network-enabled pricing mechanisms improve solar-plus-storage project returns for commercial and industrial installations.
Market Restraints
- Grid connection queue congestion:Transpower's technical assessment timelines for new renewable connections extend developer cash lock-up periods and compress project IRRs.
- Domestic steel and concrete input costs:Wind turbine tower and foundation construction faces material cost volatility that erodes fixed-price EPC contract viability.
- Dry-year hydro dependency:The security-of-supply framework's reliance on South Island hydro reservoirs creates intertemporal price risk that distorts long-term contracting.
Strategic Opportunities
- Canterbury-Otago wind corridor:Underdeveloped high-capacity factor sites offer scale opportunities for developers with appetite for regional grid reinforcement co-investment.
- Green hydrogen offtake:Emerging industrial demand from ammonia and methanol producers creates anchor demand for dedicated renewable generation clusters.
- Resource Management Act replacement:Streamlined consent pathways for renewable electricity generation reduce project development timelines and uncertainty premiums.
Industry Challenges
- Grid-scale battery integration complexity:Developers face technical and commercial challenges in co-optimizing storage dispatch across energy, frequency, and reserve markets.
- Specialized electrical engineering talent:Scarce expertise in isolated grid stability and inverter-based resource modeling constrains project execution capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Renewable Energy Market |
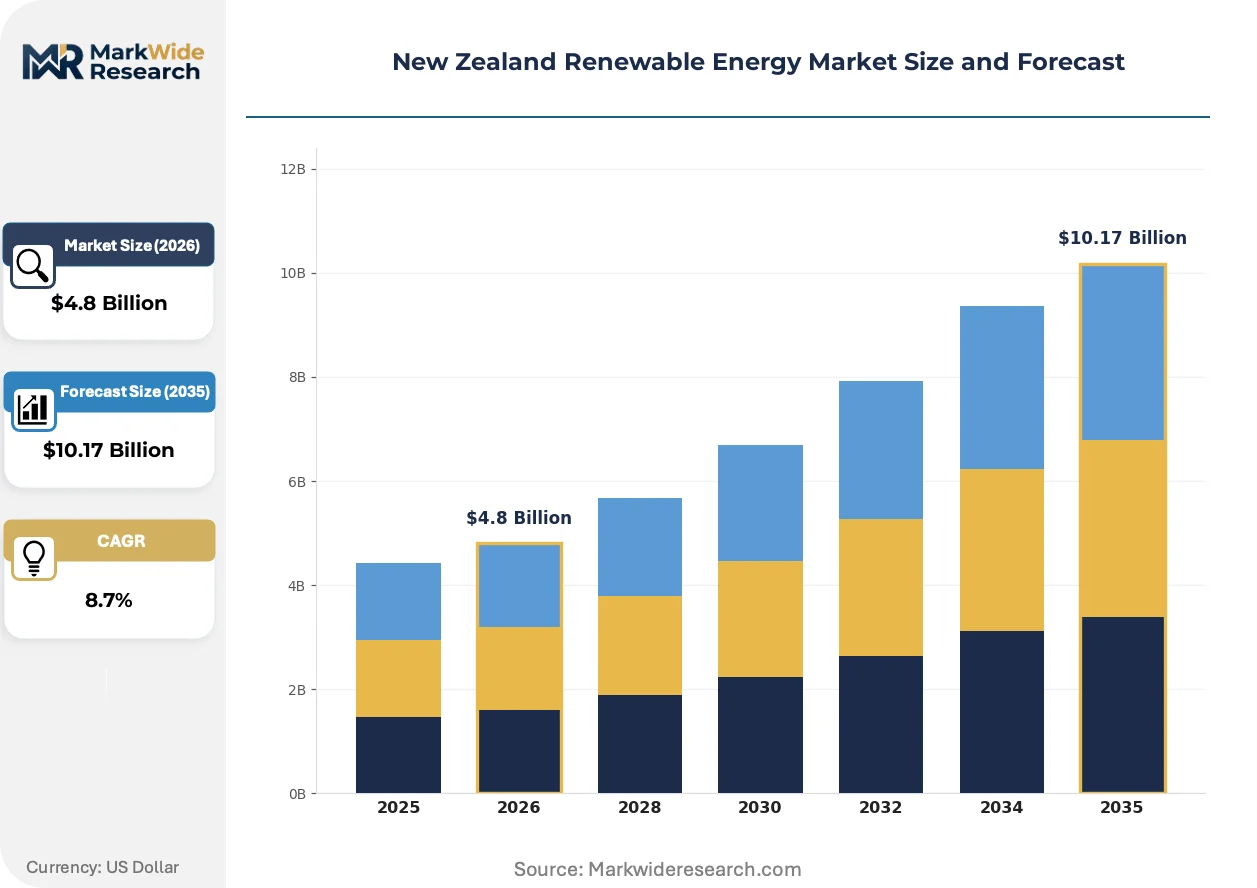
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Hydro, Biomass Application: Power Generation, Heating, Transportation, Energy Storage End User: Residential, Commercial, Industrial, Government Deployment: On-grid, Off-grid, Remote, Hybrid |
| Companies Covered | Genesis Energy, Manawa Energy, Meridian Energy, Lodestone Energy, Tilt Renewables, Contact Energy, Infratil, Transpower New Zealand, Mercury NZ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Renewable Energy Market Shifts & Advancements
Modular technology architectures are compressing project development cycles while policy frameworks accelerate capital rotation toward firm renewable supply. These forces are converging to reshape competitive positioning across generation, storage, and grid services.
Grid-scale battery energy storage systems are absorbing volatility from intermittent renewable output and providing synthetic inertia services that stabilize the island grid. Transpower and distribution network operators are procuring these assets aggressively to manage ramping constraints at solar and wind injection points. This technology is absorbing functions previously performed by thermal peaking plant, compressing the residual role of fossil-fuel generation.
The Resource Management Act replacement legislation streamlines consent pathways for renewable electricity generation, reducing regulatory friction for wind and solar development. The Climate Change Commission's carbon budgets tighten compliance obligations for industrial emitters, accelerating demand for firm renewable supply contracts. Heavy industry and data center operators are responding by contracting directly with generators for bundled hydro-wind-solar portfolios.
Corporate buyers are abandoning annual renewable energy certificate purchases in favor of 24/7 matching requirements that synchronize consumption with generation profiles. This behavioral shift disrupts traditional green tariff products and forces retailers to restructure supply offerings around time-coincident delivery guarantees. The Auckland-Tauranga corridor exhibits this pattern most acutely, where load growth and grid constraints coincide to premiumize firm supply.
New Zealand Renewable Energy Market Segmentation
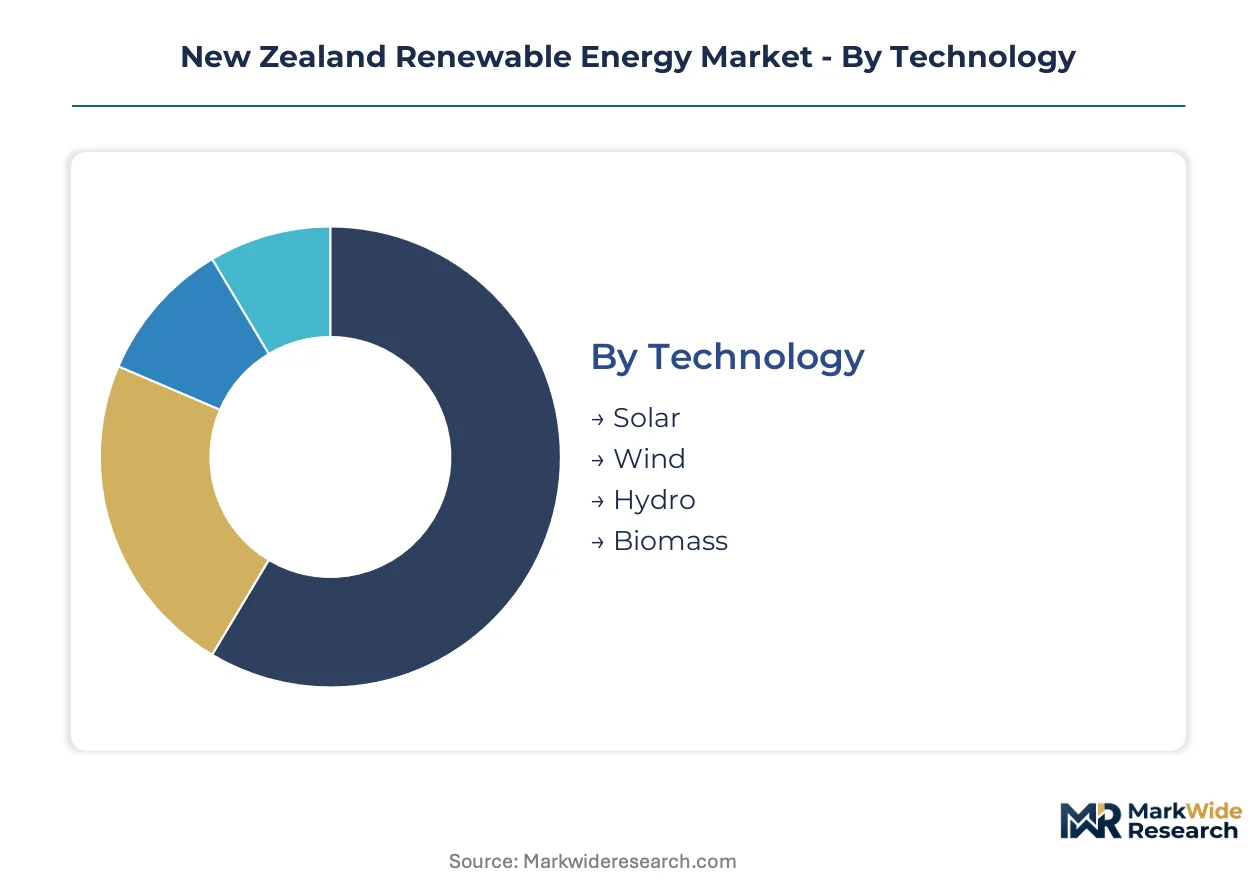
New Zealand's isolated grid architecture and hydro-dominated generation stack create distinct investment patterns across technology and deployment types. Segmentation reveals where capital concentrates and how regulatory incentives reroute project economics toward constrained nodes.
Technology:
Supply concentration in South Island hydro assets shapes competitive dynamics for newer entrants seeking grid access.
- Hydro:Run-of-river and pumped storage installations dominate installed capacity through decades of capital deployment. Demand concentrates among industrial offtakers in the Auckland-Tauranga corridor seeking firm supply contracts backed by South Island reservoir capacity, though dry-year intertemporal risk distorts long-term pricing.
- Solar:Utility-scale arrays from 10 MW to 150 MW and distributed commercial installations are expanding fastest among new build. Module cost declines and network-enabled tariffs improve project returns, with deployment clustering where Transpower's transmission pricing methodology rewards grid-constrained region investment.
- Wind:Onshore turbines rated at 2-4 MW exploit high-capacity factor sites in the Canterbury-Otago corridor. Grid reinforcement co-investment requirements filter developer participation.
- Biomass:Woody biomass combustion provides dispatchable renewable output for industrial process heat applications. Feedstock supply chain localization determines project viability.
Today's leader: Hydro. Tomorrow's challenger: Solar.
Application:
Cost tier differentiation separates capital-intensive infrastructure from distributed asset classes.
- Power Generation:Utility-scale renewable installations command the largest share of investment, displacing fossil-fuel baseload while maintaining grid stability across the isolated island system. The Electricity Authority's market-making reforms compress wholesale price volatility for generator returns.
- Energy Storage:Grid-scale batteries attract disproportionate capital as they address dry-year hydro risk within New Zealand's security-of-sufficiency framework. Transpower procures these assets aggressively to manage ramping constraints at renewable injection points.
- Heating:Industrial process heat electrification and biomass thermal systems reduce fossil dependency in manufacturing.
- Transportation:EV charging infrastructure and electrolyzer-fed hydrogen supply chains emerge as anchor demand for dedicated renewable clusters.
Power generation absorbs majority capital. Energy storage claims the steepest expansion trajectory.
End User:
Customer type determines contract structure, with direct generator agreements bypassing traditional retail channels.
- Industrial:Large commercial offtakers contract firm renewable supply directly through power purchase agreements, underwriting long-dated project finance. Data center and heavy industry operators drive 24/7 matching requirements that synchronize consumption with generation profiles.
- Commercial:Distributed solar-plus-storage bundling serves mid-scale electricity consumers through network-enabled tariffs. Auckland-Tauranga corridor load growth premiumizes firm supply offerings.
- Residential:Rooftop solar deployment responds to retail tariff structures and distribution network operator interconnection standards.
- Government:Public sector procurement anchors demonstration projects and grid-scale battery tenders.
Industrial buyers set contract terms today. Commercial segment adoption is climbing the fastest.
Deployment:
Maturity gradients separate established grid-connected assets from frontier applications requiring technical innovation.
- On-grid:Centralized renewable generation connects through Transpower's national transmission network and distribution operator systems. Grid connection queue congestion extends developer cash lock-up periods.
- Hybrid:Co-located solar-wind-storage configurations optimize capacity factor and firm output delivery for corporate offtakers. Resource Management Act replacement legislation streamlines consent pathways for these integrated projects.
- Off-grid:Industrial and remote community installations bypass transmission infrastructure constraints.
- Remote:Standalone systems serve geographic isolation where grid extension is uneconomic.
On-grid deployment dominates capacity. Hybrid configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's renewable energy infrastructure originated with South Island hydroelectric development in the early twentieth century, establishing generation patterns that persist today. The national grid now spans both islands with distinct regional characteristics shaping investment flows.
Auckland Region
Data center construction and heavy industry expansion drive electricity demand growth throughout the Auckland-Tauranga corridor. Transpower's transmission pricing methodology rewards generation investment in this grid-constrained node. The Auckland metropolitan area hosts the country's largest concentration of corporate renewable energy procurement activity.
Waikato Region
Geothermal resources anchor baseload renewable supply from the Taupo Volcanic Zone. The Electricity Authority's market-making reforms compress wholesale price volatility for generators operating here. Huntly's thermal units transition toward flexible peaking as renewable penetration increases.
Canterbury
High-capacity factor wind sites in the Canterbury-Otago corridor attract developers with appetite for grid reinforcement co-investment. Resource Management Act replacement legislation streamlines consent pathways for these projects. Christchurch anchors regional demand for industrial process heat electrification.
Otago
Run-of-river hydro installations dominate installed capacity through decades of capital deployment in the Clutha and Waitaki catchments. Dry-year intertemporal risk distorts long-term contracting for industrial offtakers seeking firm supply. Dunedin and surrounding industrial zones concentrate demand for stable renewable output.
Wellington Region
Government procurement anchors demonstration projects and grid-scale battery tenders concentrated in the capital. The Electricity Authority governs wholesale market design from its Wellington headquarters. Policy implementation for the Climate Change Commission's carbon budgets originates here, shaping national compliance obligations.
New Zealand Renewable Energy Market Competitive Landscape
The competitive structure tilts toward integrated generation-retail incumbents with established hydro fleets. Meridian Energy and Contact Energy command disproportionate market presence through legacy infrastructure positions. Three archetypes dominate: South Island hydro-centric integrated utilities, North Island geothermal-wind hybrids, and emerging solar-focused independents. Competitive moves center on power purchase agreement origination and grid-scale storage co-location.
Within the integrated utility tier, Meridian Energy exemplifies the South Island hydro-centric model, leveraging its Waitaki and Manapouri assets to anchor bundled firm supply contracts. Contact Energy occupies the North Island hybrid position, combining geothermal baseload with intermittent renewable portfolios. Among emerging independents, Lodestone Energy represents the solar-focused developer archetype targeting distributed generation opportunities. These three entities illustrate the strategic segmentation between legacy infrastructure incumbents and new-build specialists.
| Leading Market Players |
|---|
| Genesis Energy |
| Manawa Energy |
| Meridian Energy |
| Lodestone Energy |
| Tilt Renewables |
| Contact Energy |
| Infratil |
| Transpower New Zealand |
| Mercury NZ |
| Others |
Supply & Pricing Matrix
Industrial power purchase agreements for 24/7 firm renewable supply are forcing generators to restructure project finance around long-dated offtake certainty, which compresses developer margins while elevating the premium commanded by bundled hydro-wind-solar portfolios in the Auckland-Tauranga corridor.
Pricing Analysis
Contract-based long-term offtake dominates renewable pricing, with price differentiation resting on firmness guarantees and geographic delivery cost to constrained nodes. Certification under the Electricity Authority's market-making framework commands tier-one premiums, while spot-exposed merchant solar faces acute compression. Large industrial offtakers exhibit lowest price sensitivity due to carbon budget compliance obligations; distributed commercial buyers show highest sensitivity to network-enabled tariff fluctuations.
Supply Chain Analysis
Domestic-content considerations under Resource Management Act replacement legislation are reshaping sourcing toward localized EPC capacity and New Zealand-sourced electrical infrastructure. Module supply draws from China and Southeast Asian manufacturing hubs; turbine components rest on European and Chinese heavy engineering. Single-source vulnerability concentrates in grid-scale battery cell supply. Distribution runs through Transpower's national transmission network and regional distribution operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The New Zealand renewable energy market functions as a regulatory compounder where the Climate Change Commission's carbon budgets tighten compliance obligations faster than incumbent generation can restructure, accelerating demand for firm renewable supply contracts.
For Market Incumbents: Lock in long-dated power purchase agreements with data center and heavy industry operators before emerging solar-focused independents capture Auckland-Tauranga corridor load growth. Anchor bundled firm supply contracts with South Island hydro reservoir capacity to defend against geothermal-wind hybrid competitors. Prioritize grid-scale battery co-location at existing renewable injection points to capture synthetic inertia service revenues. For New Entrants and Emerging Players: Modular solar-plus-storage bundling offers the most penetrable wedge for commercial and industrial segments underserved by integrated utility green tariff products. Target distributed generation opportunities in grid-constrained regions where Transpower's transmission pricing methodology rewards local investment. Pursue network-enabled tariff structures that improve project returns without requiring wholesale market exposure. For Investors and Strategic Acquirers: Asymmetric upside sits with developers holding consented positions in the Canterbury-Otago wind corridor ahead of grid reinforcement co-investment requirements filtering participation. Acquisition target archetype: solar-focused independents with distributed generation pipelines and established distribution network operator relationships. Watch Resource Management Act replacement implementation timelines as inflection indicator for development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Long-dated offtake contracts from data center operators underwrite project finance for utility-scale solar and wind developments. |
| Grid-Scale Battery Deployment | Transpower procurement addresses ramping constraints at renewable injection points while capturing frequency and reserve market revenues. |
| Vertical Integration into Storage | Generators co-locate batteries with solar and wind assets to optimize dispatch across energy and ancillary service markets. |
| Technology Licensing | Modular solar-plus-storage system providers license architectures to EPC contractors accelerating commercial deployment timelines. |
| Green Certification Program | 24/7 matching requirements from corporate buyers drive restructuring of retail supply offerings around time-coincident delivery guarantees. |
Research Methodology
Multiple input streams — primary interviews with utility planning officers, IPP project developers, and EPC contractors; secondary validation against Electricity Authority market reports, Transpower grid investment disclosures, and Climate Change Commission carbon budget documentation; plus customs data on module and turbine imports — were reconciled through bottom-up project pipeline aggregation and top-down market sizing triangulation.
Data-stream reconciliation anchored the analytical framework across technology, application, end user, and deployment segmentation dimensions. CAGRs were derived from project-level capacity addition schedules and tariff evolution modeling. Forecast inputs incorporated dry-year hydro risk probability distributions and transmission pricing methodology incentive effects on locational investment decisions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Resource Management Act replacement legislative timing, grid connection queue processing velocity, and industrial green hydrogen offtake materialization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Republic of Congo Renewable Energy Market